
 Argan Oil Market | 2026-2036
Argan Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Argan Oil Market Intelligence
Asset-light contract manufacturing and cooperative-based sourcing is reshaping capital requirements for new entrants in argan oil. Moroccanoil leverages its vertical integration with Moroccan women's cooperatives to secure premium virgin grade supply. Olvea Group anchors its position through controlled origin traceability from the Souss-Massa region. Josie Maran Cosmetics differentiates via direct-to-consumer storytelling around ethical harvest practices.
Argan oil is a fixed oil expressed from the kernels of Argania spinosa, containing approximately 80% unsaturated fatty acids with oleic and linoleic acids dominant, and it serves primarily as a functional emollient and oxidative-stability ingredient across cosmetics and nutraceutical formulations. Virgin and cold-pressed grades command the deepest margin pools due to limited yield per tree and labor-intensive hand-extraction. Cosmetic applications lead volume absorption, while pharmaceutical-grade refining represents the fastest-growing demand corridor as clinical validation expands. Hair care formulations now rival skin care in procurement scale among beauty salons and cosmetic manufacturers.
The EU ECHA and FDA cosmetic safety frameworks enforce allergen disclosure and Good Manufacturing Practice compliance that filter out informal suppliers. Morocco's Department of Water and Forests regulates Argania spinosa harvest permits, constraining wild-collection expansion. Stakeholders must monitor cooperative certification density and climate stress on the Souss-Massa biosphere reserve as supply reliability variables.
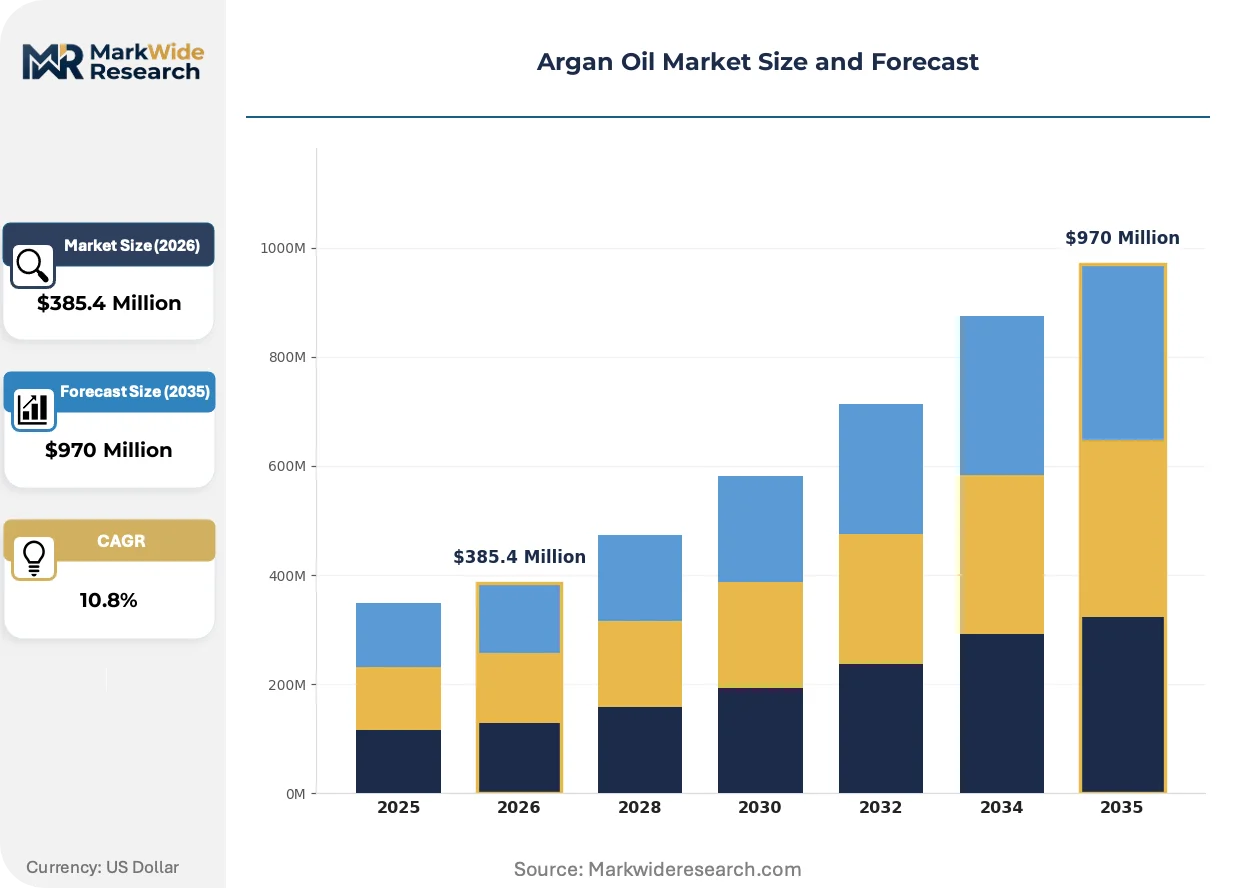
Market Dynamics
Clean-label cosmetic formulations are restructuring procurement hierarchies, forcing manufacturers to document cooperative provenance and cold-press extraction methods to satisfy EU Cosmetic Product Regulation safety dossiers.
Growth Catalysts
- EU Cosmetic Product Regulation compliance:Full traceability mandates favor suppliers with certified cooperative networks, accelerating formalization of Moroccan extraction operations.
- Hair care formulation expansion:Beauty salons and professional cosmetic manufacturers now procure argan oil at volumes rivaling traditional skin care applications.
- Pharmaceutical-grade clinical validation:Expanding oxidative-stability research in nutraceutical formulations opens new demand corridors beyond cosmetic emollients.
Market Restraints
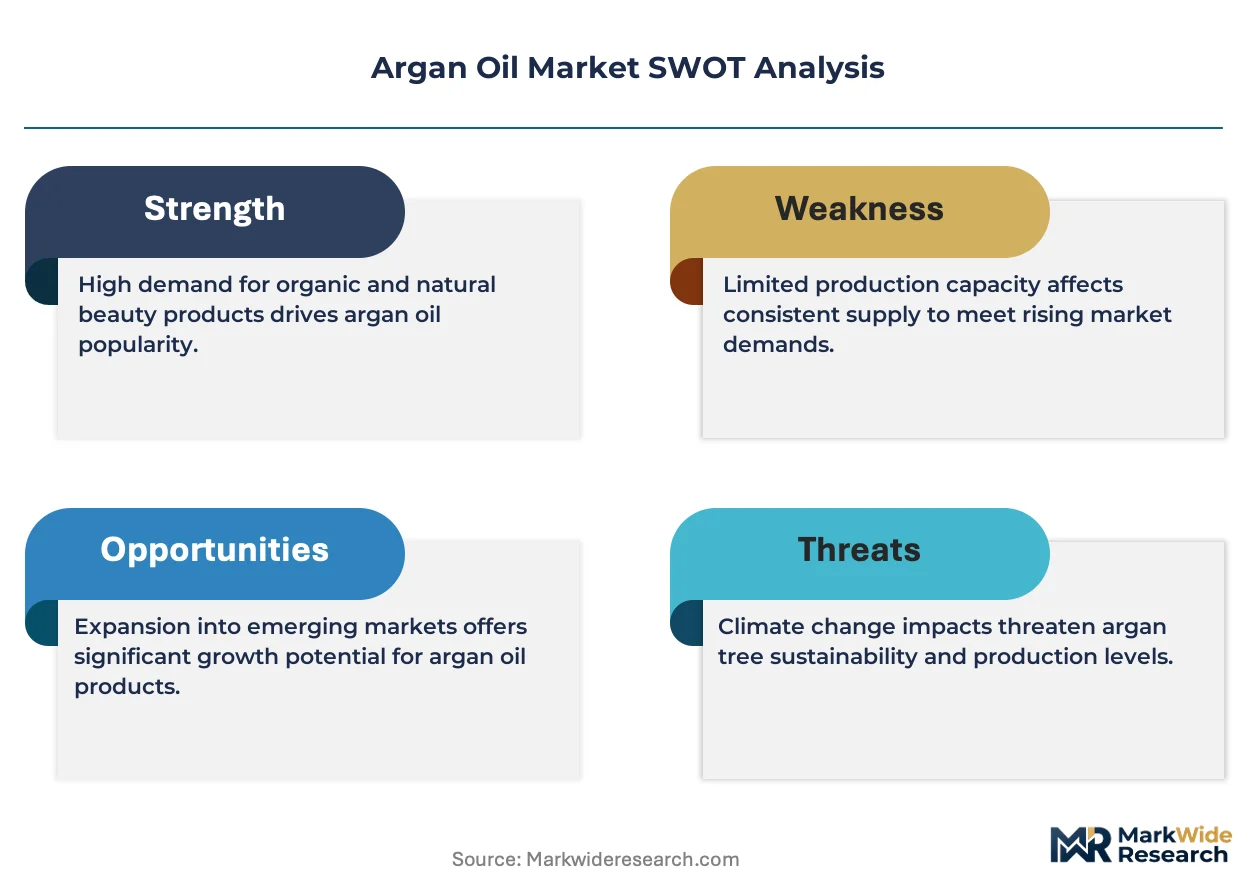
- Labor-intensive hand-extraction:Limited yield per Argania spinosa tree constrains virgin grade scalability regardless of price signals.
- Souss-Massa supply concentration:Morocco's Department of Water and Forests harvest permits restrict wild-collection expansion, concentrating supply risk in a single biosphere reserve.
- Shea butter substitution:Lower-cost emollients with comparable fatty acid profiles capture price-sensitive cosmetic formulations.
Strategic Opportunities
- Pharmaceutical-grade refining capacity:Clinical validation expansion creates whitespace for GMP-certified extraction facilities serving EU and US FDA frameworks.
- Direct-to-consumer ethical storytelling:Brands bypassing distributor markups by highlighting cooperative harvest practices capture margin expansion.
- Climate-adaptive cultivation:Argania spinosa nursery programs in Algeria and Tunisia diversify geographic supply beyond Moroccan concentration.
Industry Challenges
- Cooperative certification density gaps:Informal women's cooperatives lack ISO 22000 and organic certification infrastructure required by EU and US cosmetic safety frameworks.
- Climate stress monitoring:Stakeholders must track precipitation variability and heat stress indicators across the Souss-Massa biosphere reserve to forecast supply reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argan Oil Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $970 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin, Refined, Organic, Cold-Pressed Application: Cosmetics, Food Flavoring, Pharmaceuticals, Hair Care End User: Beauty Salons, Cosmetic Manufacturers, Food Producers, Pharmaceutical Companies Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Dropper Bottles, Tins |
| Companies Covered | Moroccanoil, John Masters Organics, Olvea Group, Honasa Consumer Limited, Dabur, L'ORÉAL, Josie Maran Cosmetics, ARGANisme Cosmetics, L'OCCITANE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argan Oil Market Strategic Shifts & Innovations
Digital traceability platforms and cold-chain logistics are compressing the distance between Moroccan cooperatives and European cosmetic laboratories, altering how origin verification creates competitive differentiation.
Blockchain-enabled provenance tracking is virtualizing cooperative certification documentation. Prestige beauty houses in France and Germany now require immutable harvest-to-bottle records. This technology is virtualizing the audit function that previously required on-site Moroccan inspections.
REACH registration requirements for cosmetic ingredients are tightening substance dossier standards across the European Economic Area. ECHA enforcement is filtering informal suppliers lacking full toxicological profiles. Hair care and skin care manufacturers are consolidating procurement around ECHA-registered Moroccan exporters with pre-submitted safety data.
Salon-direct bulk purchasing is fragmenting traditional distributor channels. Professional beauty supply houses in France, Germany, and the United Kingdom face disintermediation as cosmetic manufacturers sell liter-grade virgin oil directly to independent stylists. This channel compression is most visible in Paris and London metropolitan clusters where salon density supports minimum order thresholds.
Argan Oil Market Segmentation
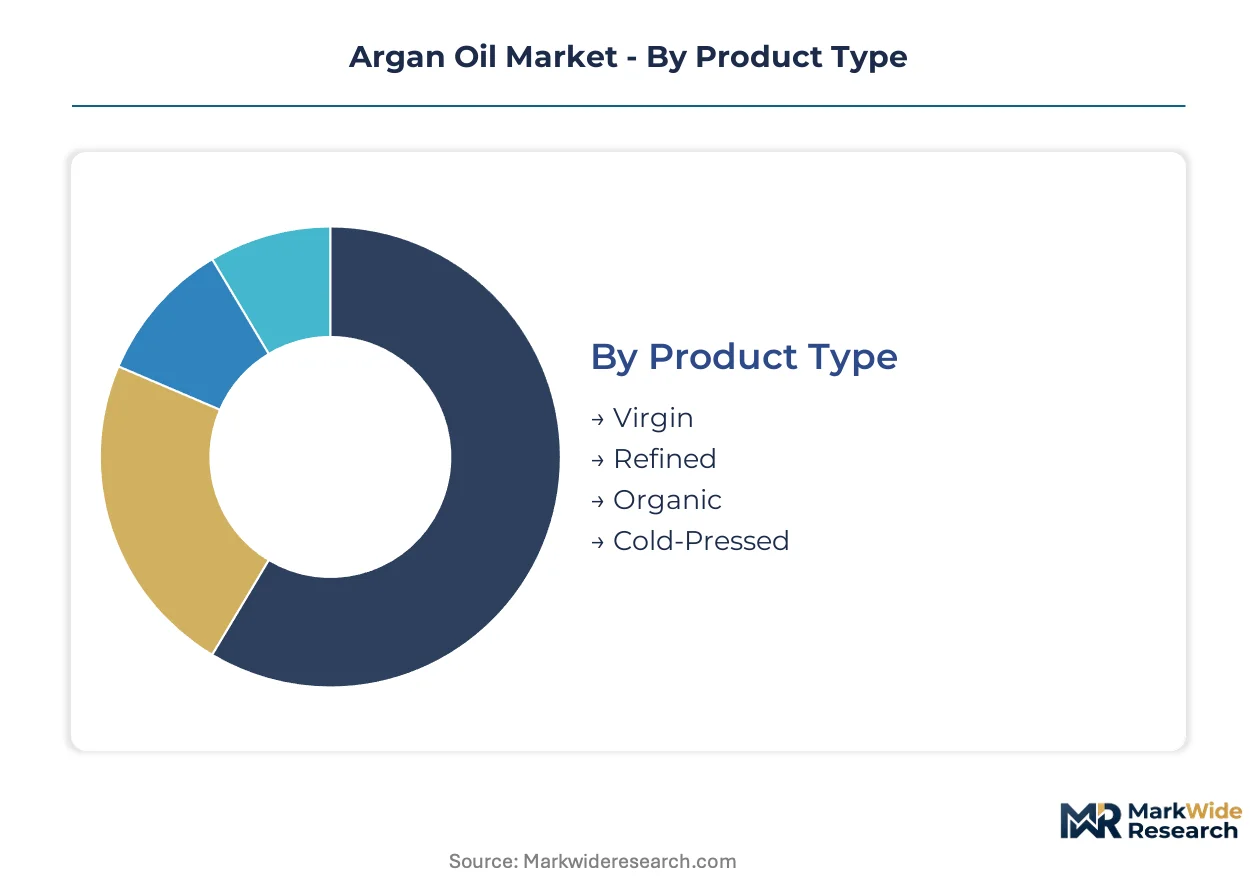
Argan oil procurement patterns diverge sharply across extraction grades and end-use specifications. Cosmetic manufacturers enforce the strictest purity thresholds, while food and pharmaceutical buyers prioritize oxidative stability metrics over sensory characteristics.
Product Type:
Cost tier determines margin capture and certification burden across extraction methods.
- Virgin:Unrefined oil retaining full tocopherol and polyphenol content through mechanical pressing without chemical treatment. French prestige beauty houses source virgin grade exclusively from Moroccan cooperatives with ECHA-registered safety dossiers.
- Cold-Pressed:Temperature-controlled extraction below 40°C preserves heat-sensitive fatty acid profiles for premium cosmetic formulations. German cosmetic laboratories specify cold-pressed origin documentation to satisfy REACH substance registration requirements.
- Refined:Deodorized and bleached oil meeting pharmaceutical-grade purity standards through activated carbon and clay filtration. GMP-certified facilities in Casablanca process refined volumes for nutraceutical encapsulation.
- Organic:ECOCERT and USDA-certified production with full traceability from Argania spinosa grove to bottling facility. Organic certification density remains concentrated among established women's cooperatives in the Souss-Massa region.
Virgin grade holds installed capacity. Cold-pressed is rotating up the share rankings.
Application:
Functional requirements across end-uses create divergent specification hierarchies.
- Cosmetics:Emollient and oxidative-stability properties drive formulation inclusion across skin creams, serums, and lip products. ECHA compliance mandates filter informal suppliers from EU cosmetic procurement channels.
- Hair Care:Cuticle-sealing fatty acid profiles support professional salon treatments and retail conditioning products. Paris and London metropolitan salon clusters now procure liter-grade volumes directly from Moroccan exporters.
- Food Flavoring:Roasted kernel oil with nutty sensory characteristics serves traditional Moroccan amlou and premium culinary applications. Food-grade extraction requires separate processing lines from cosmetic production.
- Pharmaceuticals:Clinical validation of anti-inflammatory and lipid-modulating properties expands nutraceutical formulation demand. FDA and EMA frameworks require full toxicological dossiers for pharmaceutical-grade registration.
Cosmetics maintains volume leadership. Hair care is climbing the fastest.
End User:
Customer type dictates order scale, certification requirements, and channel configuration.
- Cosmetic Manufacturers:Bulk procurement of certified grades for clean-label formulation integration. EU Cosmetic Product Regulation traceability mandates favor suppliers with ISO 22000 and cooperative certification infrastructure.
- Beauty Salons:Mid-volume purchasing of virgin and cold-pressed oils for professional treatment applications. Direct-to-salon distribution is fragmenting traditional wholesale channels in France and Germany.
- Pharmaceutical Companies:GMP-compliant refining specifications for clinical trial materials and commercial nutraceutical production. EMA quality documentation requirements exclude uncertified Moroccan suppliers.
- Food Producers:Roasted-grade procurement for specialty culinary product lines and ethnic food distribution. Food safety certification gaps limit cooperative penetration into formal food manufacturing channels.
Cosmetic manufacturers command procurement scale. Beauty salons are gaining share fastest.
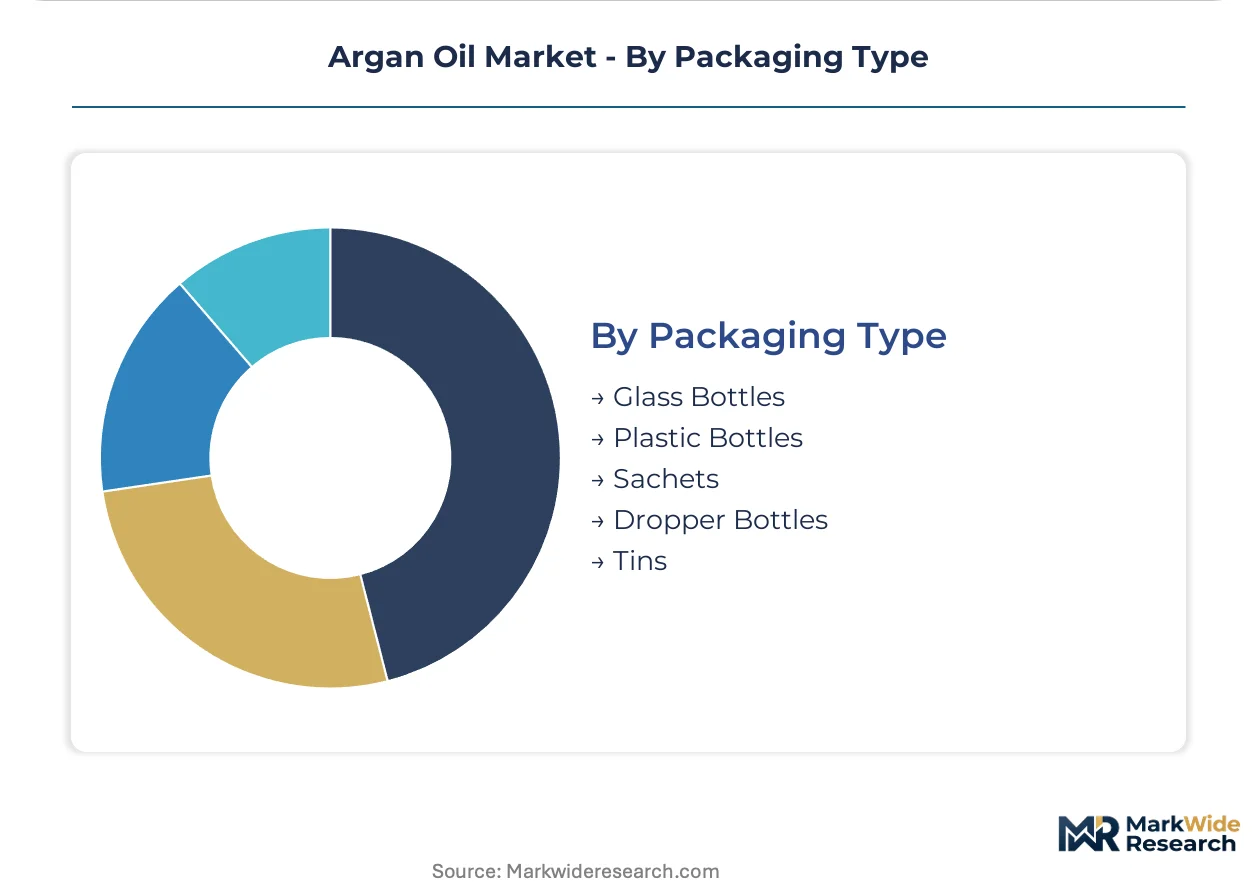
Packaging Type:
Packaging format aligns with end-use volume, oxidation sensitivity, and retail positioning.
- Glass Bottles:Premium retail presentation with UV protection for virgin and organic grades. French and German prestige beauty retail channels specify amber glass for tocopherol preservation.
- Dropper Bottles:Precision dispensing for facial serum and treatment oil applications. Direct-to-consumer brands in the United Kingdom favor dropper formats for e-commerce fulfillment efficiency.
- Plastic Bottles:Cost-optimized bulk packaging for professional salon and manufacturing procurement. HDPE and PET formats reduce freight weight for export logistics.
- Tins:Traditional Moroccan packaging for culinary-grade roasted oil and bulk cooperative distribution. Metal containers retain heat resistance for amlou preparation.
- Sachets:Single-use sampling and travel-size formats for brand trial and hotel amenity programs. Sachet production concentrates in Casablanca contract packaging facilities.
Glass bottles anchor premium positioning. Dropper formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Cosmetic Product Regulation traceability mandates and FDA cosmetic safety frameworks are redirecting procurement flows toward certified Moroccan exporters with full toxicological dossiers. France and Germany enforce the strictest cooperative certification requirements, while the United States and United Kingdom expand direct-to-salon distribution channels.
France
Prestige beauty houses in Paris source virgin grade exclusively from ECHA-registered Moroccan cooperatives with immutable harvest-to-bottle documentation. ANSM cosmetic safety inspections filter informal suppliers lacking ISO 22000 infrastructure. The Île-de-France metropolitan cluster hosts the densest concentration of salon-direct procurement, with independent stylists purchasing liter-grade volumes directly from Casablanca exporters.
Germany
German cosmetic laboratories specify cold-pressed origin documentation to satisfy REACH substance registration requirements for emollient formulations. BDIH and ECOCERT certification density exceeds other EU member states, compressing margins for uncertified competitors. The Frankfurt-Rhine-Main logistics corridor anchors bulk pharmaceutical-grade refining imports destined for nutraceutical encapsulation facilities.
United States
FDA cosmetic Good Manufacturing Practice compliance and MoCRA facility registration rules favor GMP-certified Moroccan exporters over informal cooperative networks. Direct-to-consumer brands in Los Angeles and New York leverage ethical harvest storytelling to bypass distributor markups. The Pacific Northwest hosts emerging clean-label formulation labs specifying full Souss-Massa provenance documentation.
United Kingdom
UK cosmetic manufacturers consolidate procurement around ECHA-registered suppliers despite post-Brexit regulatory divergence, maintaining alignment with EU safety dossier standards. London metropolitan salon clusters drive dropper-bottle format demand for professional treatment applications. The MHRA cosmetic ingredient notification system filters uncertified Moroccan supply from formal manufacturing channels.
Morocco
The Department of Water and Forests harvest permit system constrains wild-collection expansion across the Souss-Massa biosphere reserve, concentrating supply risk in a single geographic zone. Cooperative certification infrastructure remains uneven, with established women's cooperatives holding ECOCERT and USDA organic credentials while informal extractors lack EU market access. Casablanca hosts GMP-certified refining facilities processing pharmaceutical-grade volumes for EMA and FDA frameworks.
Argan Oil Market Key Industry Players
On the supply side, the industry is bifurcated between vertically integrated prestige brands and cooperative-dependent bulk suppliers. Moroccanoil anchors the premium tier through captive supply arrangements with women's cooperatives. The competitive arena separates into three strategic archetypes: cooperative-integrated prestige houses, GMP-certified pharmaceutical refiners, and direct-to-consumer storytelling specialists. Capacity expansion in Casablanca pharmaceutical facilities and blockchain-enabled provenance investments constitute the dominant competitive moves.
Among cooperative-integrated operators, Moroccanoil exemplifies backward integration into Moroccan women's cooperative networks. Olvea Group occupies a position within the GMP-certified refining tier, with Souss-Massa origin traceability anchoring its pharmaceutical-grade supply. Josie Maran Cosmetics represents the direct-to-consumer archetype, leveraging ethical harvest narratives to capture margin expansion beyond traditional distributor channels.
| Leading Market Players |
|---|
| Moroccanoil |
| John Masters Organics |
| Olvea Group |
| Honasa Consumer Limited |
| Dabur |
| L'ORÉAL |
| Josie Maran Cosmetics |
| ARGANisme Cosmetics |
| L'OCCITANE |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Moroccan cooperative networks determines both pricing tier spreads and supply chain shape, compressing margins for uncertified extractors while amplifying premium capture for ECHA-registered operators with full Souss-Massa traceability.
Pricing Analysis
Certification level creates the primary spread across argan oil procurement, with ECOCERT-organic and ECHA-registered grades commanding substantial premiums over informal cooperative output. Three-tier pricing structure across premium, standard, and economy levels reflects virgin, cold-pressed, and refined grade differentiation. Cost compression in the standard tier is intensifying because shea butter substitutes capture price-sensitive cosmetic formulations. Beauty salons and direct-to-consumer brands exhibit the highest price sensitivity, while prestige cosmetic manufacturers prioritize certification over unit cost.
Supply Chain Analysis
EU Cosmetic Product Regulation traceability requirements function as export controls limiting informal Moroccan suppliers from European market access. Geographic supply concentrates in Morocco, with nascent cultivation programs in Algeria and Tunisia attempting diversification. Raw material dependencies center on Argania spinosa kernel supply, hand-extraction labor pools, and GMP-certified refining capacity in Casablanca. Single-source vulnerability in the Souss-Massa biosphere reserve threatens supply continuity. Distribution runs through direct-to-salon channels fragmenting traditional wholesale networks in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance tracking and REACH registration tightening constitute a regulatory-technological inflection that will displace informal suppliers and consolidate procurement around certified cooperative networks.
For Market Incumbents: Pre-empt cooperative certification gaps by underwriting ISO 22000 infrastructure at informal women's collectives before ECHA enforcement hardens. Anchor backward integration into climate-adaptive Argania spinosa nursery programs in Algeria and Tunisia to diversify geographic risk beyond Moroccan concentration. Shea butter substitution in mid-market cosmetics represents the most pressing margin threat requiring grade-differentiation response.
For New Entrants and Emerging Players: Pharmaceutical-grade refining capacity in Casablanca represents the most penetrable entry point given clinical validation expansion and GMP-certified facility scarcity. Direct-to-salon distribution in Paris and London metropolitan clusters offers channel white-space with minimum viable scale thresholds. Launch with blockchain-verified ethical harvest storytelling to bypass distributor markups and capture margin expansion.
For Investors and Strategic Acquirers: The market sits at a formalization phase that favors cooperative-integrated operators with ECHA-registered dossiers over bulk commodity traders. Long-term viability hinges on climate resilience investments and certification infrastructure ownership rather than extraction volume alone. Watch cooperative certification density in the Souss-Massa region as the signal for supply reliability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | Immutable harvest-to-bottle records satisfy French ANSM inspection requirements and command premium positioning. |
| Pharmaceutical-Grade Refinery Expansion | GMP-certified Casablanca facilities capture nutraceutical demand growth under EMA and FDA frameworks. |
| Climate-Adaptive Cultivation Program | Argania spinosa nurseries in Algeria and Tunisia reduce single-source dependency on Moroccan biosphere reserves. |
| Direct-to-Salon Channel Development | Liter-grade virgin oil sales to Paris and London stylists disintermediate traditional wholesale markups. |
| Cooperative Certification Infrastructure | ISO 22000 and organic credential underwriting secures EU market access before regulatory enforcement tightens. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Moroccan cooperative managers, European cosmetic formulation chemists, French and German salon procurement heads, Casablanca refining facility operators, and ECHA regulatory affairs specialists. Secondary validation drew from EU Cosmetic Product Regulation safety dossier filings, ECOCERT and USDA organic certification databases, Moroccan Department of Water and Forests harvest permit records, and REACH substance registration disclosures. Bottom-up volume estimates from cooperative extraction capacity were triangulated against top-down cosmetic manufacturer procurement surveys.
Calibration against historical price differentials across virgin, cold-pressed, and refined grades anchored the analytical framework across the analysis window. Segmentation dimensions modeled include extraction grade tier, end-use application, customer type, and regional regulatory cluster. CAGRs were derived from supply-constrained growth assumptions reflecting Argania spinosa yield biology and cooperative certification expansion rates. Climate stress indicators and ECHA enforcement intensity served as industry-specific forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in euro-dirham exchange rates or EU cosmetic import tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding cooperative formalization pace and clinical validation timelines for pharmaceutical-grade applications. Material shifts in Souss-Massa precipitation patterns or Moroccan harvest permit policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Polypeptide Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Germany Collagen Market