
 Hair Styling Biopolymers Market | 2026-2036
Hair Styling Biopolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Styling Biopolymers Market Analytics
Professional salon distribution is narrowing as specialty chemical suppliers consolidate direct relationships with premium hair care brands. BASF SE leverages its integrated biopolymer fermentation capacity to supply film-forming agents for high-hold styling gels. Croda International Plc anchors its position through lipid-compatible cellulose derivatives tailored for alcohol-free mousses. Lubrizol Corporation differentiates via cationic biopolymer technology that enhances conditioning-styling hybrids for salon professionals.
Hair styling biopolymers comprise renewable polysaccharides and proteins engineered to deliver film-forming, viscosity-modifying, and hold-enhancing properties at concentrations typically ranging from 0.5% to 5% by formulation weight, replacing synthetic acrylates and silicones in styling products. Aqueous formulations lead volume demand due to compatibility with water-soluble hydroxypropyl starch and chitosan derivatives, while anhydrous creams capture expanding margin pools as consumers prioritize concentrated, waterless formats. Professional use segments sustain premium pricing through performance guarantees and technical service bundling that retail channels rarely replicate.
REACH registration requirements in Europe mandate full toxicological dossiers for novel biopolymer chemistries, elevating compliance costs for entrants while favoring established suppliers with dedicated regulatory affairs teams. FDA cosmetic ingredient oversight in the United States and ECHA polymer-of-low-concern classifications collectively shape permissible molecular weight thresholds and purity specifications across major markets. Stakeholders must monitor evolving microplastic-free labeling standards that threaten legacy synthetic alternatives and accelerate substitution timelines for certified biodegradable styling polymers.
Market Dynamics
REACH-compliant biopolymer formulations are displacing petrochemical-derived styling polymers across professional salon channels, with clean beauty mandates in Western Europe compressing substitution timelines and reshaping supplier qualification requirements.
Growth Catalysts
- REACH polymer registration:Full toxicological dossier requirements for novel biopolymer chemistries are accelerating R&D investment in cellulose and starch derivatives that satisfy ECHA purity specifications.
- Professional salon channel:Performance-grade hold requirements without synthetic residues are pulling corn starch and chitosan formulations into premium styling gel and mousse applications.
- Microplastic-free labeling:Certified biodegradable polymer demand from Germany, France, and Italy is displacing legacy acrylate alternatives in aqueous styling formulations.
Market Restraints
- Fermentation capacity concentration:Integrated biopolymer production clusters in Germany and the Netherlands create supply vulnerability for non-captive formulators seeking film-forming agents.
- Input cost volatility:Corn starch and agricultural cellulose feedstock prices fluctuate with commodity crop cycles, compressing margin stability for fermentation-based suppliers.
- Molecular weight thresholds:ECHA polymer-of-low-concern classifications impose strict purity specifications that disqualify mid-grade biopolymer batches from cosmetic-grade applications.
Strategic Opportunities
- Anhydrous cream formats:Waterless concentrated styling products are opening premium margin pools for lipid-compatible cellulose derivatives in alcohol-free mousses.
- Cationic biopolymer hybrids:Convergence of conditioning and styling functions is creating white space for chitosan-based film-formers in salon-exclusive treatment lines.
- Direct brand-supplier relationships:Specialty chemical suppliers are bypassing traditional distributors to capture technical service bundling value in Italy's professional channel.
Industry Challenges
- Regulatory affairs talent scarcity:REACH dossier compilation and ECHA negotiation expertise concentrates among established suppliers, delaying market entry for novel biopolymer developers.
- Formulation integration complexity:Water-soluble hydroxypropyl starch compatibility testing with existing preservative systems extends product development cycles for aqueous gel launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Styling Biopolymers Market |
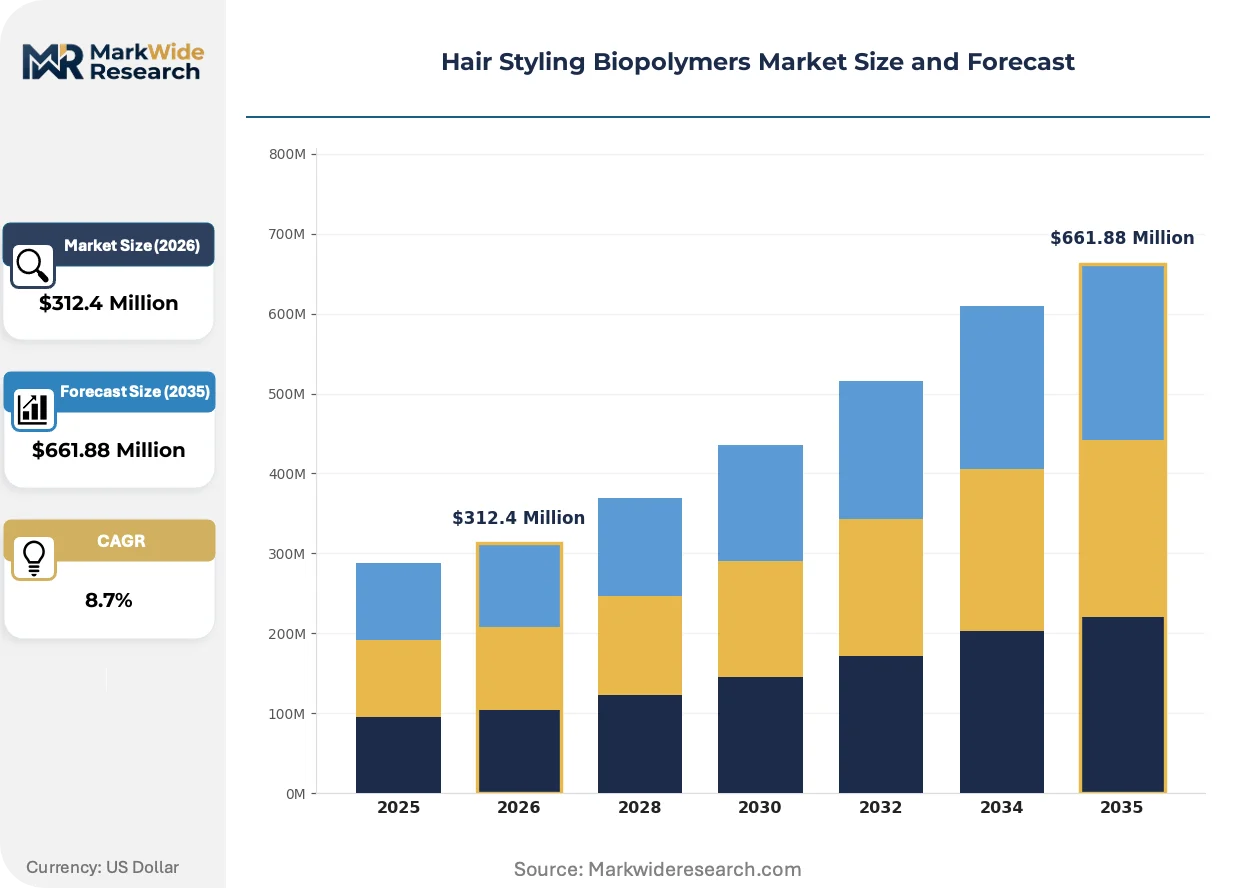
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Mousses, Creams, Sprays Application: Professional Use, Retail Use, Home Care, Salon Use Formulation Type: Aqueous, Anhydrous, Oil-based, Alcohol-free End User: Consumers, Salons, Hair Care Professionals, Distributors |
| Companies Covered | BASF SE, Lubrizol Corporation, Croda International Plc, Nouryon, Ashland, Evonik Industries, Clariant, Solvay, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Styling Biopolymers Market Evolving Landscape
Fermentation-derived film-forming technology is compressing cost curves for renewable styling polymers, while regulatory labeling mandates and professional channel restructuring simultaneously reshape competitive positioning.
Hydroxypropyl starch phosphate technology is collapsing the performance gap between biopolymer and synthetic acrylate hold agents. Professional stylists in Germany and France are adopting these film-formers at accelerating pace for high-hold gels. The technology is collapsing premium pricing tiers that previously separated petrochemical and renewable styling polymer categories.
ECHA microplastic-free labeling requirements are forcing reformulation roadmaps across the EU cosmetic sector. Manufacturers must now certify biodegradability for film-forming agents under tightened polymer classification protocols. Professional salon brands in Italy are responding fastest, prioritizing REACH-registered corn starch derivatives in new product pipelines.
Salon professionals are consolidating purchase decisions around performance guarantees bundled with technical formulation support. Traditional chemical distributors are losing share as specialty suppliers build direct relationships with premium hair care brands. This pattern concentrates most visibly in France, where technical service bundling now determines biopolymer supplier selection criteria.
Hair Styling Biopolymers Market Segmentation
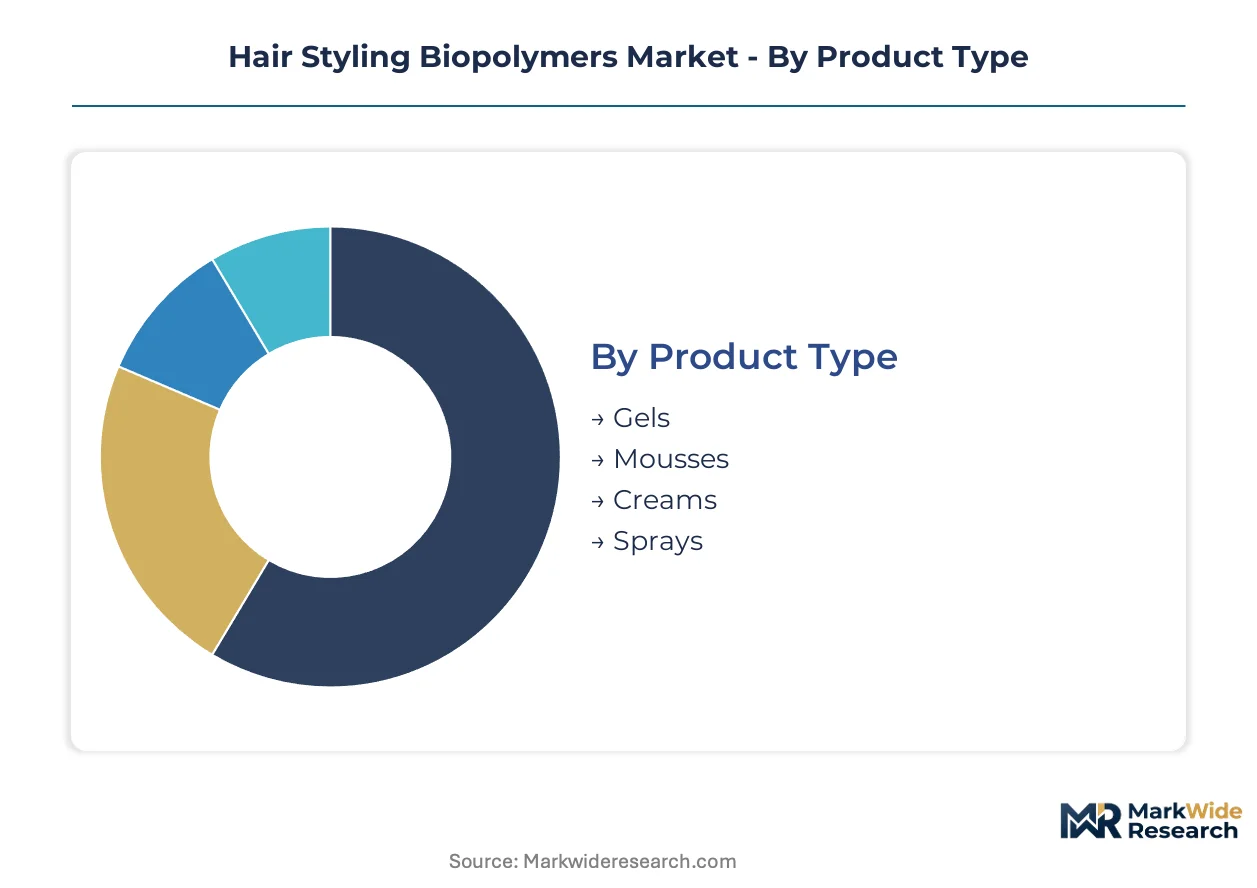
Hair styling biopolymer procurement patterns diverge sharply across formulation chemistry and channel economics. Understanding these divides clarifies where corn starch and cellulose derivatives command premium positioning versus commodity substitution.
Product Type:
Mature styling formats coexist with emerging concentrated formats as professional preferences fragment across hold intensity and finish aesthetics.
- Gels:Hydroxypropyl starch phosphate formulations deliver film-forming hold at 2-5% concentration, replacing synthetic acrylates in Germany's professional salon channel where REACH compliance is mandatory. Water-soluble polysaccharide compatibility with preservative systems determines supplier qualification.
- Mousses:Chitosan and cellulose derivatives create lightweight volumizing structures through aqueous foam stabilization. France's salon professionals prioritize alcohol-free variants that avoid drying effects on chemically treated hair.
- Creams:Lipid-compatible biopolymers enable anhydrous concentrated formats for Italy's premium treatment lines.
- Sprays:Fine-mist delivery demands low-viscosity hydrolyzed protein solutions compatible with pressurized packaging.
Gels retain volume leadership; creams hold the steepest expansion curve.
Application:
Channel economics separate performance-guaranteed professional supply from mass-market retail where price elasticity dominates.
- Professional Use:Technical service bundling and formulation support justify 40-60% price premiums over retail equivalents. BASF SE and Croda International Plc cultivate direct relationships with salon-exclusive brands in France and Germany, bypassing traditional chemical distributors.
- Salon Use:Performance guarantees for hold duration and humidity resistance drive specification of REACH-registered corn starch derivatives. Italian salon chains are consolidating procurement around single-source biopolymer suppliers offering batch-to-batch consistency certification.
- Retail Use:Mass-market styling products compete on ingredient storytelling rather than technical performance metrics.
- Home Care:Consumer-directed applications emphasize ease of application over professional-grade hold intensity.
Professional use commands margin leadership; salon use is gaining share fastest.
Formulation Type:
Water content determines biopolymer solubility requirements and regulatory classification pathways across the EU cosmetic sector.
- Aqueous:Water-soluble hydroxypropyl starch and chitosan derivatives dominate volume demand, compatible with standard preservative systems and ECHA polymer-of-low-concern classifications. Formulation integration complexity extends development cycles for new gel launches.
- Anhydrous:Concentrated waterless formats capture expanding margin pools through reduced packaging and shipping costs. Lipid-compatible cellulose derivatives from Croda International Plc enable alcohol-free mousses for Germany's clean beauty segment.
- Oil-based:Hydrophobic film-formers require modified starch esters with tailored HLB values for dispersion stability.
- Alcohol-free:Regulatory pressure on volatile organic compounds drives substitution in spray applications.
Aqueous retains volume leadership; anhydrous holds the steepest expansion curve.
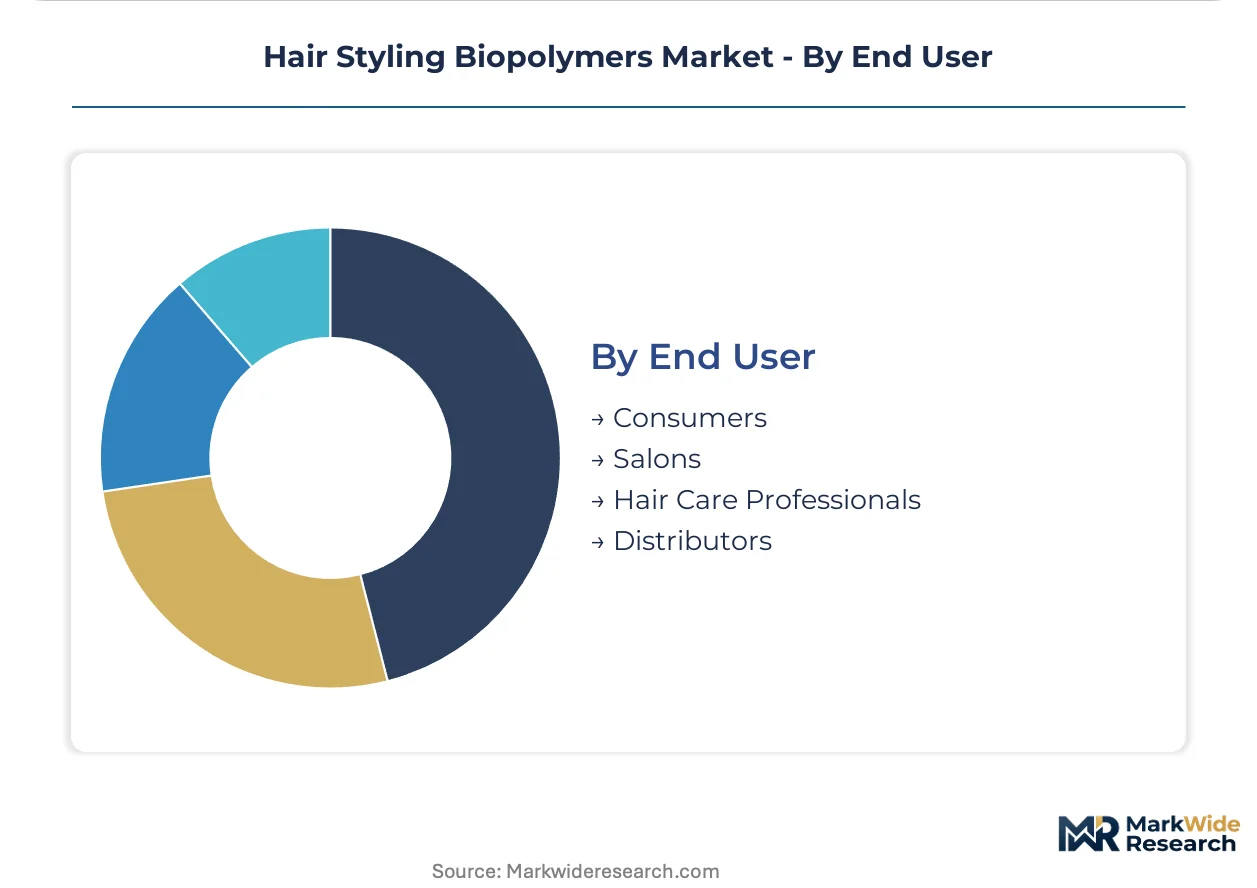
End User:
Purchase decision authority concentrates with technical buyers who evaluate film-forming performance against regulatory dossier completeness.
- Hair Care Professionals:Stylists in France and Germany specify biopolymer grades based on humidity resistance and reworkability. Direct supplier relationships are displacing distributor intermediaries as technical consultation becomes a selection criterion.
- Salons:Chain procurement offices negotiate volume contracts contingent on REACH registration verification and biodegradability certification.
- Consumers:End-user purchasing responds to clean beauty labeling and microplastic-free claims without technical specification input.
- Distributors:Traditional chemical distributors are losing share to specialty suppliers building direct brand relationships.
Hair care professionals retain specification authority; salons are consolidating procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western European professional channels where REACH compliance commands premium positioning, while cost-sensitive retail markets in Asia-Pacific compress margins for commodity-grade biopolymer grades.
Germany
Professional salon chains in Munich and Hamburg drive specification of corn starch-derived film-formers for high-hold styling gels. ECHA polymer-of-low-concern classifications mandate strict molecular weight thresholds that disqualify mid-grade batches. The Cologne-Düsseldorf chemical corridor hosts integrated fermentation capacity supplying REACH-registered biopolymers to premium hair care brands.
France
Paris-based luxury hair care houses prioritize alcohol-free mousse formulations using chitosan derivatives for chemically treated hair protection. ANSM cosmetic ingredient oversight aligns with EU microplastic-free labeling timelines accelerating synthetic substitution. The Lyon biotech cluster anchors cellulose derivative R&D for lipid-compatible anhydrous creams.
Italy
Milan salon professionals consolidate procurement around single-source suppliers offering batch-to-batch consistency certification for styling polymer performance guarantees. Clean beauty regulation tightens fastest here, pulling REACH-compliant corn starch formulations into new product pipelines. The Emilia-Romagna personal care manufacturing belt specializes in treatment-line biopolymer integration.
United States
Professional distributor networks in New York and Los Angeles are losing share to direct brand-supplier relationships as technical service bundling becomes a selection criterion. FDA cosmetic ingredient oversight maintains lower purity barriers than REACH, enabling faster formulation iteration for mid-tier styling brands. The New Jersey chemical corridor imports European fermentation-derived film-formers for premium salon channels.
Netherlands
Rotterdam-Amsterdam logistics hubs facilitate biopolymer feedstock distribution across northwestern European cosmetic manufacturers. Agricultural cellulose price volatility from commodity crop cycles concentrates margin pressure on fermentation-based suppliers operating near Antwerp. The Dutch specialty chemical sector specializes in hydroxypropyl starch phosphate technology bridging performance gaps with synthetic acrylates.
Hair Styling Biopolymers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry expertise. The vendor base organizes around three strategic archetypes: integrated fermentation operators with captive biopolymer supply, specialty chemical houses with direct brand relationships, and regional distributors losing share to technical service bundling. Capacity expansion and regulatory dossier compilation represent the dominant competitive moves as ECHA registration requirements elevate barriers for novel entrants.
Among integrated chemical conglomerates, BASF SE anchors the fermentation-derived film-former segment with upstream control over biopolymer production clusters. Specialty chemical positioning is occupied by Croda International Plc and Lubrizol Corporation, representing the direct brand-supplier relationship archetype that bypasses traditional distribution channels. These three exemplify how REACH compliance capabilities and technical consultation bundling now determine supplier selection criteria in professional salon channels.
| Leading Market Players |
|---|
| BASF SE |
| Lubrizol Corporation |
| Croda International Plc |
| Nouryon |
| Ashland |
| Evonik Industries |
| Clariant |
| Solvay |
| Dow |
| Others |
Value Network & Pricing Analysis
Undercapacity in Germany's integrated fermentation clusters is tightening supplier bargaining power and compressing margin buffers for non-captive formulators sourcing REACH-registered film-forming agents. This utilization squeeze simultaneously elevates pricing premiums for certified biopolymer grades and accelerates consolidation among buyers seeking volume guarantees.
Pricing Analysis
Configured-to-order pricing for REACH-registered corn starch derivatives commands 25-40% premiums over standard cellulose grades, with certification tier and batch-to-batch consistency driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by molecular weight purity and toxicological dossier completeness. Cost compression in mid-grade segments is intensifying because agricultural feedstock volatility feeds directly into fermentation economics. Retail channel buyers exhibit highest price sensitivity, while professional salon chains absorb premiums for technical service bundling.
Supply Chain Analysis
Extended payment terms from specialty chemical suppliers to premium hair care brands are displacing traditional distributor financing in France and Italy. Geographic supply concentration centers on Germany, the Netherlands, and Belgium, with the Cologne-Düsseldorf and Rotterdam-Antwerp corridors anchoring integrated fermentation capacity. Raw material dependencies rest on corn starch, agricultural cellulose, and chitosan feedstocks. Single-source vulnerability concentrates in Germany's captive biopolymer production clusters. Distribution runs through direct brand-supplier relationships that bypass traditional chemical distributors in professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized REACH dossier compilation expertise is scarce and concentrates among established European suppliers, creating durable competitive moats that entrants struggle to replicate without multi-year regulatory investment.
For Market Incumbents: Entrench regulatory affairs capabilities through dedicated ECHA negotiation teams and expand captive fermentation capacity in the Netherlands to secure feedstock access. Cellulose derivative substitution from Asian suppliers poses the primary volume threat. Backward integration into agricultural cellulose sourcing mitigates commodity price volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in Italy's anhydrous cream segment where lipid-compatible biopolymer demand outpaces established supply. Alcohol-free mousse formulations for chemically treated hair protection represent the most penetrable white space. Direct technical service partnerships with Milan salon chains offer a viable go-to-market angle that circumvents distributor gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fermentation operators with captive biopolymer supply and long-term offtake contracts with premium hair care brands. Long-term viability favors suppliers with proven ECHA registration track records and scalable production footprints. Watch for inflection signals in microplastic-free labeling adoption rates across German retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Expansion | ECHA registration depth determines supplier qualification in Western European professional channels. |
| Fermentation Capacity Addition | Integrated production clusters in Germany and the Netherlands secure feedstock cost advantages. |
| Direct Brand Relationship Building | Technical service bundling displaces traditional distributors in France and Italy salon networks. |
| Anhydrous Format Development | Waterless concentrated products capture premium margin pools for lipid-compatible cellulose derivatives. |
| Cationic Biopolymer Hybrid Launch | Conditioning-styling convergence creates white space in salon-exclusive treatment lines. |
Research Methodology
The analysis maps film-forming agent grades, formulation type compatibility, and channel procurement patterns, each validated through fermentation plant managers, procurement leads at premium hair care brands, technical R&D directors, and salon chain buyers. Primary stakeholder interviews combined with secondary validation from ECHA registration databases, customs trade data, Cefic sector reports, and SEC filings enabled bottom-up and top-down triangulation across market sizing.
Fixed assumptions across the analysis window held REACH compliance timelines and ECHA polymer classification protocols constant, while corn starch feedstock prices and professional channel restructuring were varied. Segmentation dimensions modeled include product type, application channel, formulation chemistry, and end-user purchase authority. CAGRs were derived through growth driver weighting and constraint factor discounting, with biopolymer substitution elasticity and salon professional adoption curves serving as industry-specific forecast inputs.
Stress conditions across agricultural commodity volatility, regulatory registration delays, and distributor relationship disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean beauty mandate acceleration and microplastic-free labeling adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycide Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market