
 Hybrid Construction Equipment Market | 2026-2036
Hybrid Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Construction Equipment Market Analytics
Skilled powertrain engineering talent is bifurcating competitive outcomes in the sector. Caterpillar Inc. leverages captive R&D centers in Illinois and Texas to sustain proprietary hybrid drive architectures. Komatsu Ltd. anchors its position through integrated motor-inverter manufacturing in Osaka. Volvo Construction Equipment differentiates via European channel control and rental fleet partnerships.
Hybrid construction equipment combines diesel or alternative-fuel engines with electric motors, energy storage systems, and regenerative braking to reduce fuel consumption and emissions during earthmoving, lifting, and material transport operations. Power output typically ranges from 50 kW to 400 kW depending on machine class, with battery packs sized for peak-load shaving rather than full electric range. Excavators capture the dominant share of current revenue as trenching and demolition cycles yield substantial regenerative energy recovery. Hydraulic hybrid technology leads installation volume in loaders and cranes where high-duty hydraulic circuits enable kinetic energy storage without full electrification cost. Plug-in hybrid configurations are gaining specification share among infrastructure developers with depot-based charging infrastructure.
EPA Tier 4 Final and EU Stage V emissions standards are compressing diesel-only equipment viability windows across North America and Europe. China's MIIT dual carbon goals and GB 36886 non-road mobile machinery standards are accelerating domestic OEM hybridization timelines. India's CEA efficiency mandates and BIS certification requirements for construction machinery are expanding addressable market scope for imported hybrid platforms. Stakeholders must monitor battery supply chain localization policies and their impact on total cost of ownership calculations across procurement cycles.
Market Dynamics
Stringent municipal emissions ordinances across Germany and Japan are compressing diesel-only equipment viability, redirecting procurement specifications toward OEMs with captive powertrain engineering capabilities and forcing contractors to absorb upfront hybrid premiums against lifecycle fuel savings.
Growth Catalysts
- EU Stage V Compliance Deadlines:Non-road mobile machinery operators in France and Italy face equipment replacement cycles that favor hybrid architectures over exhaust aftertreatment retrofits.
- China's Yangtze River Delta Cluster:State-backed contractors confront binding carbon-intensity targets on public works projects, mandating hybrid excavator deployment in Shanghai and Nanjing infrastructure tenders.
- Regenerative Hydraulic Circuits:Kinetic energy recovery in loader lift arms and crane hoists captures otherwise dissipated braking energy, reducing fuel burn without full battery electrification cost.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery pack cost volatility tracks Chinese cathode material processing and Indonesian nickel refining capacity, exposing European OEMs to input price spikes.
- Dual Powertrain Complexity:Parallel diesel-electric architectures require specialized technician training and diagnostic tooling that rural equipment dealers lack.
- Residual Value Uncertainty:Secondary market buyers discount hybrid machines due to battery degradation risk and proprietary inverter replacement costs.
Strategic Opportunities
- India's CEA Efficiency Mandates:Bureau of Indian Standards certification requirements for construction machinery create import pathways for certified hybrid platforms from established OEMs.
- Depot-Based Charging Infrastructure:Plug-in hybrid configurations gain specification share among German municipal fleets with overnight charging capability at centralized maintenance yards.
- Telematics-Enabled Performance Contracts:Equipment rental houses in Japan bundle hybrid machines with fuel-guarantee clauses, transferring operational risk from contractors to fleet owners.
Industry Challenges
- Powertrain Engineering Talent Scarcity:Motor-inverter integration expertise concentrates at Komatsu's Osaka facility and Caterpillar's Illinois R&D centers, limiting second-tier OEM access to skilled hybrid architects.
- Cross-Border Certification Timelines:GB 36886 non-road mobile machinery standards in China require separate homologation testing from EU Stage V protocols, delaying product launch synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Construction Equipment Market |
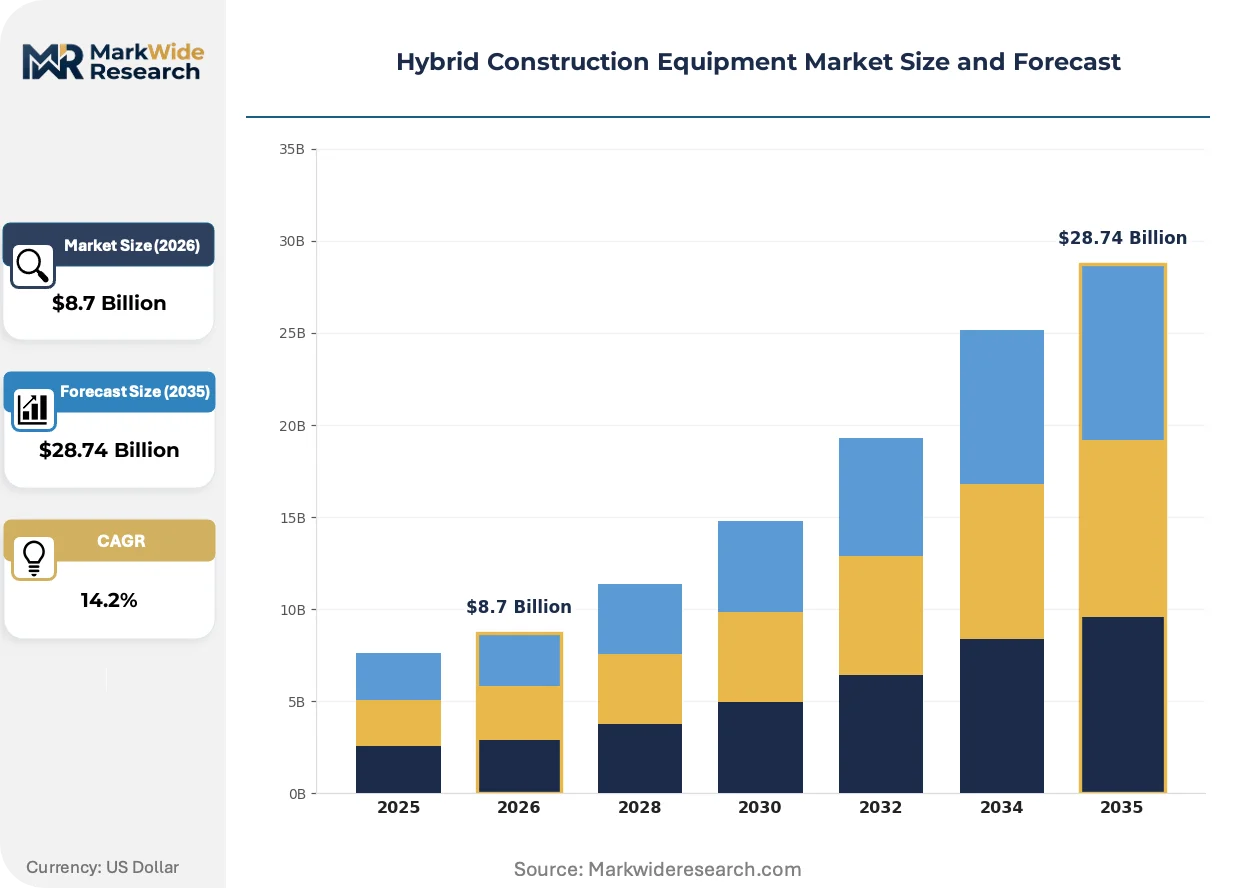
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Forklifts, Cranes, Loaders Technology: Hybrid Powertrains, Battery Electric, Hydraulic Hybrid, Plug-in Hybrid End User: Construction Companies, Demolition Services, Rental Services, Infrastructure Developers Application: Road Construction, Site Development, Material Handling, Landscaping |
| Companies Covered | John Deere, Liebherr Group, Caterpillar Inc., XCMG Group, SANY Group, Komatsu Ltd., Hitachi Construction Machinery, Doosan Infracore, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Construction Equipment Market Evolving Landscape
Active powertrain architecture decisions are bifurcating competitive outcomes, with integrated engineering capabilities separating viable hybrid platforms from compliance-focused retrofits. Three developments are redirecting specification patterns.
Modular battery-hydraulic integration is decomposing traditional equipment category boundaries. Standardized high-voltage bus architectures allow excavator, loader, and crane platforms to share common energy storage modules. Japanese infrastructure contractors now specify cross-platform battery packs that reduce fleet parts complexity. This convergence is compressing development timelines for mid-tier OEMs lacking captive cell sourcing.
EPA Tier 4 Final enforcement is narrowing diesel-only equipment viability windows across North American construction markets. Off-road engine certification costs have risen substantially for sub-75kW powertrains, pushing compact equipment manufacturers toward hybrid electric assist. Rental fleet operators in Texas and California now face customer sustainability scorecards that penalize pure diesel allocations.
Performance-based equipment procurement is displacing traditional capital purchase models among German municipal infrastructure developers. Contractors in Bavaria and North Rhine-Westphalia increasingly lease hybrid excavators with guaranteed fuel consumption ceilings, transferring technology risk to OEM captive finance arms. This shift concentrates demand among manufacturers with balance sheet capacity to underwrite operational guarantees.
Hybrid Construction Equipment Market Segmentation
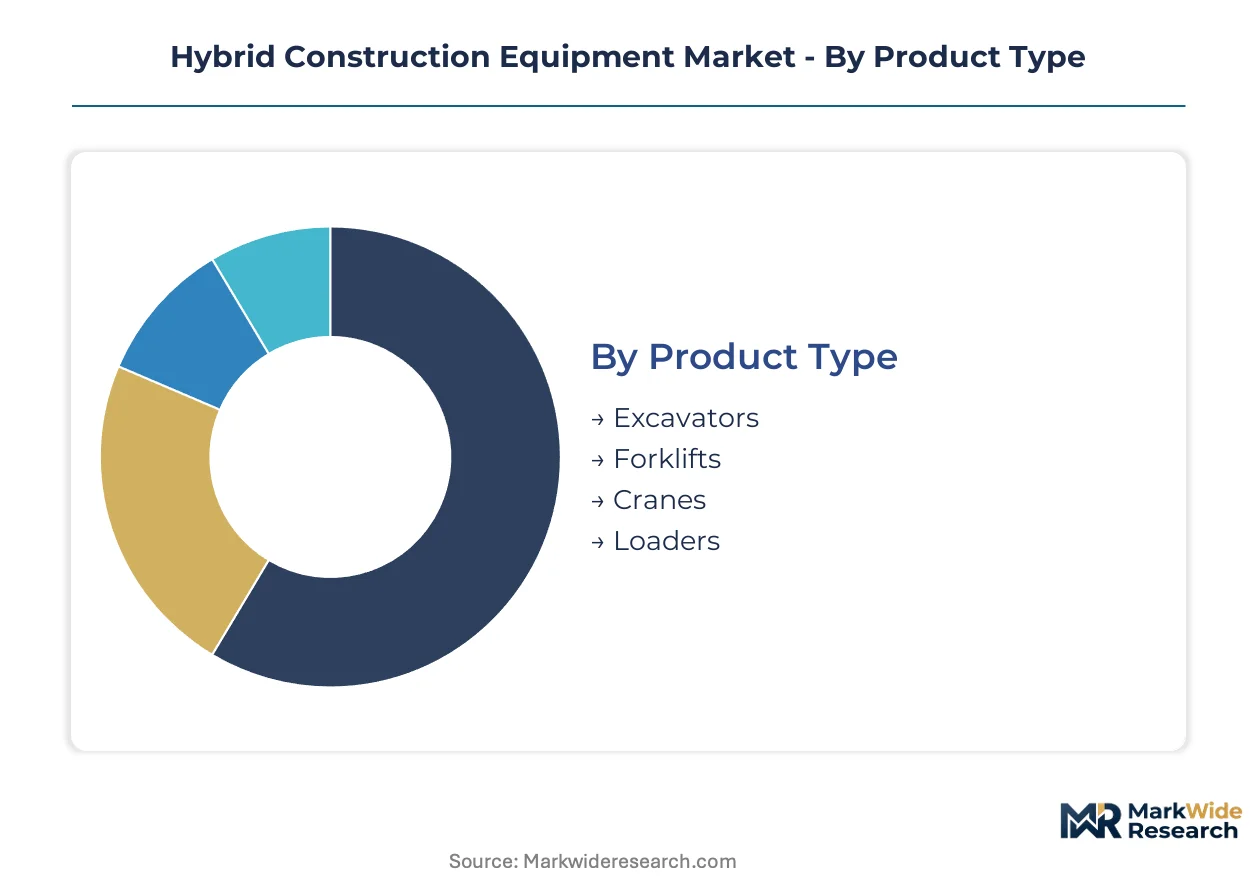
Equipment specification patterns diverge sharply across product classes and powertrain architectures. Procurement committees weight fuel-guarantee clauses, carbon-intensity targets, and depot charging availability differently depending on machine duty cycle and ownership model.
Product Type:
Margin pools concentrate in excavators and loaders where regenerative energy recovery justifies hybrid premiums through measurable fuel burn reduction.
- Excavators:Trenching and demolition cycles generate substantial regenerative braking energy through boom-down operations. Demand clusters in China's Yangtze River Delta where state-backed contractors face binding carbon-intensity targets on public works tenders.
- Loaders:High-duty hydraulic circuits enable kinetic energy storage in lift-arm accumulators without full electrification cost. German municipal fleets specify these for material handling at depot-based charging sites in Bavaria and North Rhine-Westphalia.
- Forklifts:Warehouse and logistics yards in Japan favor compact hybrid powertrains for indoor-outdoor duty cycling.
- Cranes:Hoist regenerative systems capture descending load energy; infrastructure developers specify these for bridge and high-rise construction.
Excavators hold installed capacity. Loaders are rotating up the share rankings.
Technology:
Cost tiers separate full electrification from hydraulic hybrid architectures that reduce fuel burn without battery pack scale.
- Hybrid Powertrains:Parallel diesel-electric systems combine internal combustion with electric motor assist for peak-load shaving. EPA Tier 4 Final enforcement pushes compact equipment manufacturers toward this architecture in Texas and California rental markets.
- Plug-in Hybrid:Overnight depot charging enables extended electric-only operation for municipal fleets with centralized maintenance yards. German infrastructure developers increasingly lease these with guaranteed fuel consumption ceilings.
- Hydraulic Hybrid:Kinetic energy storage in high-pressure accumulators avoids battery degradation risk and proprietary inverter replacement costs that depress secondary market values.
- Battery Electric:Full electrification demands charging infrastructure investment; specification concentrates among contractors with sustainability scorecard requirements.
Hybrid powertrains dominate current procurement volumes. Plug-in hybrid configurations are climbing the fastest as depot infrastructure spreads.
End User:
Customer type determines risk allocation between capital purchase and performance-based contracting models.
- Rental Services:Fleet operators in Japan bundle hybrid machines with fuel-guarantee clauses, transferring operational risk from contractors to balance-sheet-capable owners. Telematics-enabled performance contracts require OEM captive finance capacity.
- Infrastructure Developers:German municipal procurement specifies guaranteed fuel consumption ceilings through leasing structures that concentrate demand among manufacturers with underwriting capability.
- Construction Companies:Private contractors absorb upfront hybrid premiums against lifecycle fuel savings under tightening municipal emissions ordinances.
- Demolition Services:High-duty cycle operations favor excavators with regenerative boom-down energy capture.
Rental services hold contract innovation capacity. Infrastructure developers are gaining specification influence fastest.
Application:
Volume concentrates in earthmoving and material transport where duty cycles yield measurable regenerative energy recovery.
- Site Development:Grading and excavation operations in China's Yangtze River Delta cluster face binding carbon-intensity targets that mandate hybrid excavator deployment.
- Material Handling:Loader lift-arm cycles in German municipal yards capture kinetic energy through hydraulic hybrid systems without full battery electrification cost.
- Road Construction:Continuous duty cycles favor powertrain architectures with sustained power output and rapid refueling capability.
- Landscaping:Compact equipment sub-75kW faces rising off-road engine certification costs that push manufacturers toward hybrid electric assist.
Site development holds current project volume. Material handling is expanding most quickly as depot infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals and GB 36886 non-road mobile machinery standards anchor demand concentration in China's Yangtze River Delta cluster, while EPA Tier 4 Final and EU Stage V emissions standards compress diesel-only viability across North America and Europe.
China
State-backed contractors in Shanghai and Nanjing face binding carbon-intensity targets on public works tenders, mandating hybrid excavator deployment. MIIT dual carbon goals accelerate domestic OEM hybridization timelines beyond imported platform certification. The Yangtze River Delta cluster concentrates procurement volume where municipal infrastructure developers source equipment under state-mandated emissions budgets.
Germany
Municipal emissions ordinances in Bavaria and North Rhine-Westphalia redirect procurement specifications toward OEMs with captive powertrain engineering. EU Stage V compliance deadlines favor hybrid architectures over exhaust aftertreatment retrofits for non-road mobile machinery operators. Infrastructure developers in Frankfurt and Munich increasingly lease hybrid excavators with guaranteed fuel consumption ceilings.
United States
EPA Tier 4 Final enforcement narrows diesel-only equipment viability windows across Texas and California rental markets. Off-road engine certification costs for sub-75kW powertrains push compact equipment manufacturers toward hybrid electric assist. Fleet operators in Houston and Los Angeles face customer sustainability scorecards that penalize pure diesel allocations.
Japan
Urban infrastructure developers in Tokyo and Osaka expand procurement of hybrid excavators and loaders as municipal emissions ordinances tighten. METI efficiency mandates concentrate specification authority among contractors with depot-based charging infrastructure. Equipment rental houses in Nagoya bundle hybrid machines with fuel-guarantee clauses that transfer operational risk to fleet owners.
India
Bureau of Indian Standards certification requirements for construction machinery create import pathways for certified hybrid platforms. CEA efficiency mandates expand addressable market scope for established OEMs entering through joint venture structures. Contractors in Maharashtra and Gujarat absorb upfront hybrid premiums against projected lifecycle fuel savings under tightening state emissions protocols.
Hybrid Construction Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive powertrain engineering capabilities determining specification access in municipal procurement channels. The market structure concentrates around manufacturers with in-house motor-inverter integration and balance sheet capacity to underwrite performance guarantees. Three archetypes dominate: diversified industrial conglomerates with construction equipment divisions, dedicated earthmoving machinery specialists, and regional champions serving protected domestic markets. Competitive moves center on strategic partnerships for battery supply security and geographic expansion through certified distribution networks.
Among integrated industrial conglomerates, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by captive R&D infrastructure and captive finance arms capable of supporting outcome-based contracting models. Volvo Construction Equipment anchors the European channel control archetype through rental fleet partnerships and municipal leasing structures. XCMG Group represents the state-backed Chinese OEM vector, leveraging domestic procurement mandates to build scale before export certification.
| Leading Market Players |
|---|
| John Deere |
| Liebherr Group |
| Caterpillar Inc. |
| XCMG Group |
| SANY Group |
| Komatsu Ltd. |
| Hitachi Construction Machinery |
| Doosan Infracore |
| Volvo Construction Equipment |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for lithium-ion cell supply lock in both cathode material access and battery pack cost visibility for European OEMs facing MIIT dual carbon procurement mandates in China. German municipal fleets and Japanese rental houses absorb upfront hybrid premiums through guaranteed fuel consumption ceilings that transfer operational risk to manufacturers with captive finance capacity.
Pricing Analysis
Chinese cathode processing spreads diverge from European pack assembly costs by margins that reflect Indonesian nickel refining volatility and domestic GB 36886 certification overhead. Three-tier pricing structure across premium, standard, and economy levels tracks powertrain integration depth, with fully integrated motor-inverter architectures commanding standard tier placement against hydraulic hybrid economy offerings. Cost compression in compact equipment sub-75kW intensifies because EPA Tier 4 Final certification burdens push manufacturers toward electric assist. Municipal infrastructure developers in Germany exhibit lowest price sensitivity due to performance-guarantee leasing structures, while private construction contractors in India face highest capital constraint pressure.
Supply Chain Analysis
Strait of Malacca transit underwrites cathode precursor delivery schedules from Chinese processing hubs to South Korean cell assembly plants serving Japanese OEM motor-inverter integration. Battery supply draws from China, South Korea, and Japan for cell manufacturing, with Germany and the United States anchoring powertrain final assembly. Lithium carbonate, nickel sulfate, and rare-earth permanent magnets constitute critical input dependencies. Single-source vulnerability concentrates in Chinese cathode active material processing. Distribution runs through OEM captive finance arms and certified dealer networks with specialized diagnostic tooling for parallel diesel-electric architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as binding carbon-intensity targets on public works tenders in China's Yangtze River Delta cluster accelerate specification shifts before full electrification infrastructure matures.
For Market Incumbents: Secure motor-inverter integration expertise through targeted hiring from Komatsu's Osaka engineering cluster and Caterpillar's Illinois R&D centers before talent scarcity hardens. Deepen backward integration into battery cell supply through joint venture structures with South Korean cathode processors to deflect input price volatility. Channel control investments in German municipal leasing partnerships protect specification access against emerging Chinese OEM export certification campaigns. For New Entrants and Emerging Players: Lead with hydraulic hybrid architectures for Indian CEA efficiency mandate compliance, where Bureau of Indian Standards certification creates import pathways without full powertrain engineering depth. Depot-based charging infrastructure gaps in Maharashtra and Gujarat municipal fleets represent the most penetrable white space. Target equipment rental houses with telematics-enabled fuel-guarantee contracts that transfer technology risk to balance-sheet-capable fleet owners. For Investors and Strategic Acquirers: Powertrain engineering boutiques with motor-inverter integration capabilities and existing OEM supplier relationships represent the highest-conviction acquisition archetype for this 5-10 year electrification transition window. Balance sheet capacity to underwrite performance-based equipment procurement contracts serves as the critical viability filter. Watch for inflection when Chinese domestic OEMs achieve synchronized EU Stage V and GB 36886 homologation timelines that unlock export volume scale.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Joint Venture | Locks cathode precursor access for European OEMs facing MIIT procurement mandates. |
| Depot Charging Infrastructure Partnership | Enables plug-in hybrid specification share gains among German municipal fleet operators. |
| Motor-Inverter Integration Acquisition | Captures scarce powertrain engineering talent concentrated at Japanese and US R&D centers. |
| Telematics-Enabled Performance Contract | Transfers fuel consumption risk from contractors to rental fleet balance sheets in Japan. |
| Dual Certification Acceleration Program | Synchronizes EU Stage V and GB 36886 homologation timelines for Chinese OEM export expansion. |
Research Methodology
A standing panel of equipment procurement directors at German municipal infrastructure agencies, Japanese rental fleet operators, and Chinese state-backed contractor engineering departments provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with maintenance directors, plant engineers, and OEM procurement teams with secondary validation against customs trade records, MIIT equipment certification filings, and EPA Tier 4 Final enforcement disclosures. Bottom-up equipment shipment data triangulated against top-down carbon-intensity target modeling.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across equipment class, powertrain architecture, end-user contracting model, and regional regulatory cluster. CAGRs derived from equipment replacement cycle timing, emissions ordinance enforcement calendars, and battery cost trajectory assumptions. Forecast inputs included municipal procurement mandate expansion schedules and depot charging infrastructure deployment curves.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EU Stage V and China's dual carbon protocols would require recalibration. Forecasts reflect documented assumptions regarding battery cell supply localization policies and their impact on total cost of ownership calculations. Practitioners should keep alternative scenarios live as cross-border certification timeline convergence and residual value uncertainty for hybrid platforms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Tower Crane Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Press Brakes Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Wood Chipping Machinery Market