
 Electric Shovel Market | 2026-2036
Electric Shovel Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Shovel Market Analytics
The electric shovel supply base is consolidating around a sharp split between premium electrified models and conventional diesel-hydraulic commodity units. Komatsu Mining Corp. leverages its AC-drive technology leadership to dominate high-tonnage mine deployments. Caterpillar Inc. anchors the North American aftermarket through its captive parts and service network. SANY competes aggressively on delivered cost for emerging market customers seeking medium-duty wheel shovel configurations.
An electric shovel is a track-mounted or wheeled excavating machine powered by electric motors or diesel-electric hybrid systems, typically rated above 15 cubic meters bucket capacity, designed for continuous loading of haul trucks in open-pit mining and heavy civil earthmoving. Its primary purpose centers on high-volume, low-cost-per-ton material extraction where uptime reliability directly determines mine economics. Crawler shovels command the largest installed base due to superior stability on unimproved benches, while wheel shovels represent the fastest-growing configuration for quarry and construction crossover applications where mobility between faces matters. The heavy-duty size class captures disproportionate margin pools because OEMs bundle long-term maintenance contracts with initial equipment sales.
MSHA mandates in the United States, REACH substance restrictions in Europe, and China's GB standards for non-road mobile machinery electrification collectively tighten compliance thresholds for engine emissions and operator safety systems. These frameworks push end users toward retrofit-ready platforms and OEMs toward modular powertrain architectures that can accommodate future battery or tethered electric upgrades. Stakeholders must weigh capital commitment timing against the accelerating regulatory timeline for zero-emission surface equipment.
Market Dynamics
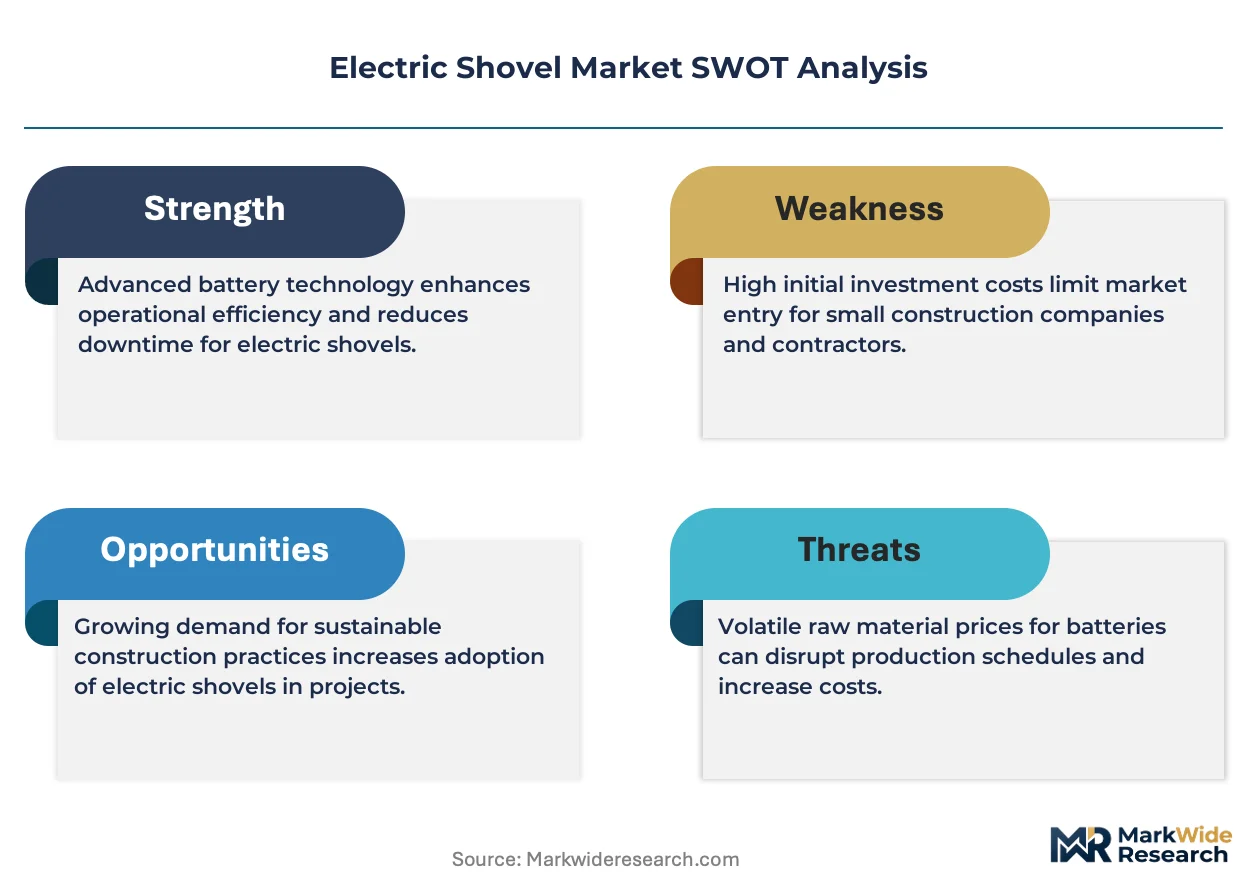
Electrification mandates are compressing the design window for new shovel platforms, forcing OEMs to architect modular powertrains that accommodate battery, tethered, and fuel-cell variants within a single chassis family. This structural pressure is reshaping R&D allocation and supplier qualification timelines across the value chain.
Growth Catalysts
- EPA Tier 4 Final emissions standards:US surface mining operators face compliance deadlines that accelerate fleet turnover toward electric-drive configurations, particularly in Appalachian coal and Arizona copper operations.
- Autonomous haulage integration:Shovels equipped with machine-to-machine communication protocols enable direct coordination with driverless truck fleets, cutting load cycle variability by enabling real-time payload optimization.
- Inner Mongolia autonomous region:State-owned mining conglomerates in this coal-rich territory are executing multi-year capital programs that specify electric shovels above 20 cubic meters for new super-pit developments.
Market Restraints
- High-voltage grid infrastructure:Tethered electric shovels require substation upgrades and trailing cable management systems that add capital intensity beyond the machine itself, particularly at remote greenfield sites lacking utility access.
- Copper and rare earth magnet supply:AC-drive motors depend on concentrated upstream supply from Chilean copper mines and Chinese rare earth processing, creating input cost volatility and geopolitical exposure.
- MSHA electrical safety certification:The approval timeline for new high-voltage platforms extends 18-24 months, compressing the effective sales window before the next regulatory cycle.
Strategic Opportunities
- Brazilian iron ore expansion:Vale's Serra Sul and Carajás complexes represent underpenetrated demand for 400-ton-class electric shovels as the company executes its decarbonization roadmap.
- Retrofit-ready platform architecture:OEMs can capture aftermarket value by designing diesel-hydraulic frames with pre-engineered electric conversion kits, extending asset life for cost-constrained operators.
- EU Green Deal carbon border adjustments:European mining equipment procurement is tilting toward verified low-carbon supply chains, creating preference premiums for OEMs with transparent Scope 3 emissions accounting.
Industry Challenges
- High-voltage technician scarcity:Mines struggle to recruit electricians qualified for 6,600V maintenance, forcing OEMs to bundle multi-year service contracts that compress margin realization.
- Legacy fleet interoperability:New electric shovels must integrate with existing dispatch systems, haul truck fleets, and maintenance management software without triggering downtime cascades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Shovel Market |
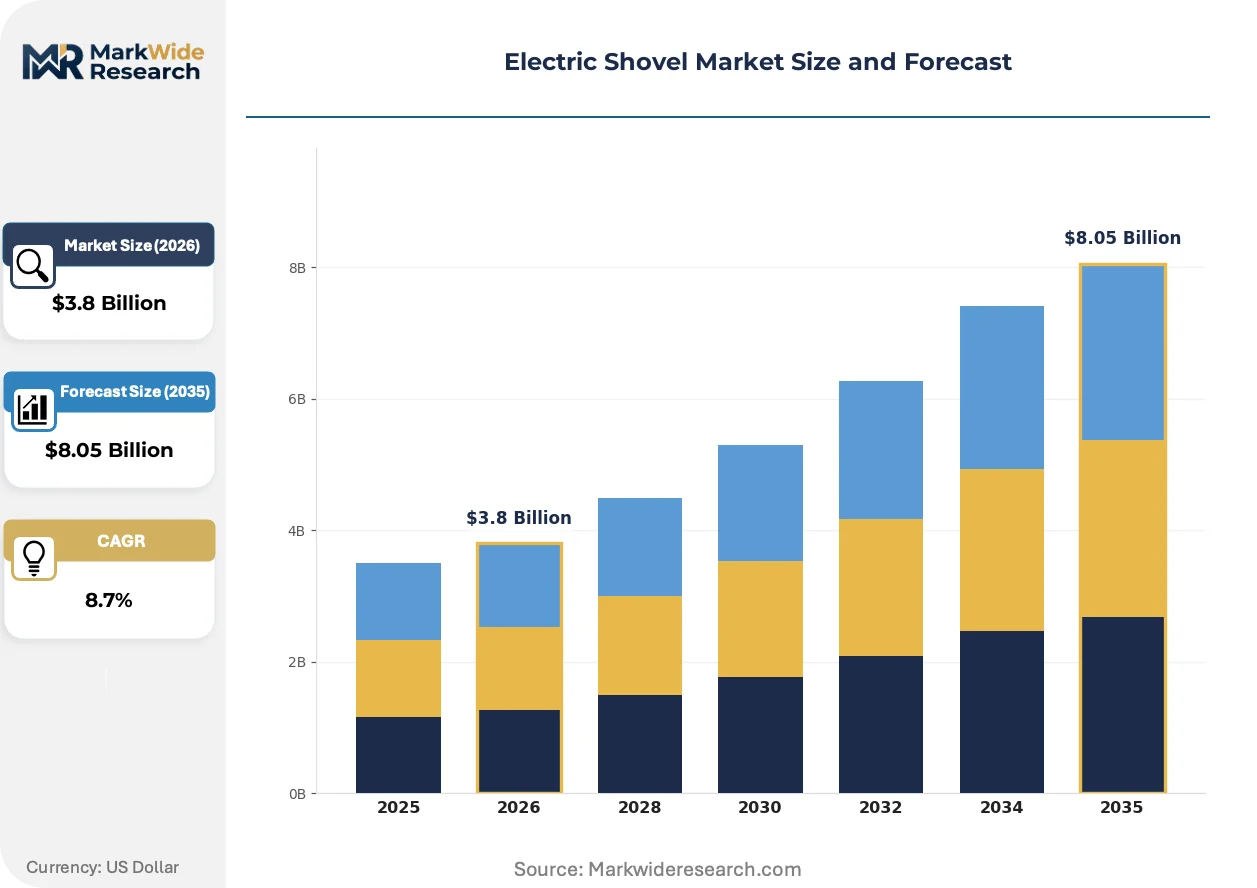
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Shovels, Wheel Shovels, Mini Shovels, Full-Size Shovels End User: Construction, Mining, Agriculture, Demolition Application: Excavation, Material Handling, Earthmoving, Landscaping Size: Compact, Medium, Large, Heavy Duty |
| Companies Covered | Caterpillar Inc., Komatsu Mining Corp., Hitachi Construction Machinery, Liebherr Group, SANY, P&H Mining, IZ-KARTEX, Taiyuan Heavy Industry Co., Ltd., L&H Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Shovel Market Evolving Landscape
Digitalization is penetrating the shovel cabin and powertrain simultaneously, creating convergence between automation layers and electrification hardware. Equipment buyers now evaluate platforms on software extensibility and energy management granularity rather than mechanical reliability alone.
Integrated energy storage modules are unifying peak-shaving and regenerative braking functions into a single battery subsystem. Tier-one copper producers in Chile are piloting these configurations to reduce grid demand charges and capture kinetic energy from boom deceleration. This unification is compressing the total cost of ownership gap between tethered and diesel-electric variants, accelerating adoption in jurisdictions with volatile electricity pricing.
REACH substance restrictions on hydraulic fluids and lubricants are forcing formulation changes that degrade performance in extreme temperatures. European OEMs are responding with synthetic ester alternatives and sealed-for-life bearing designs that eliminate contamination pathways. The heavy-duty size class faces the steepest compliance burden due to higher fluid volumes and longer service intervals.
Buyer evaluation criteria are migrating from upfront capital cost to total cost per ton moved, with energy consumption and maintenance predictability weighted more heavily. Australian iron ore operators now require ISO 50001-certified energy management systems as a procurement gate, displacing traditional specification checklists. This behavioral shift is most pronounced in Western Australia, where mine automation maturity enables precise measurement of shovel contribution to fleet efficiency.
Electric Shovel Market Segmentation
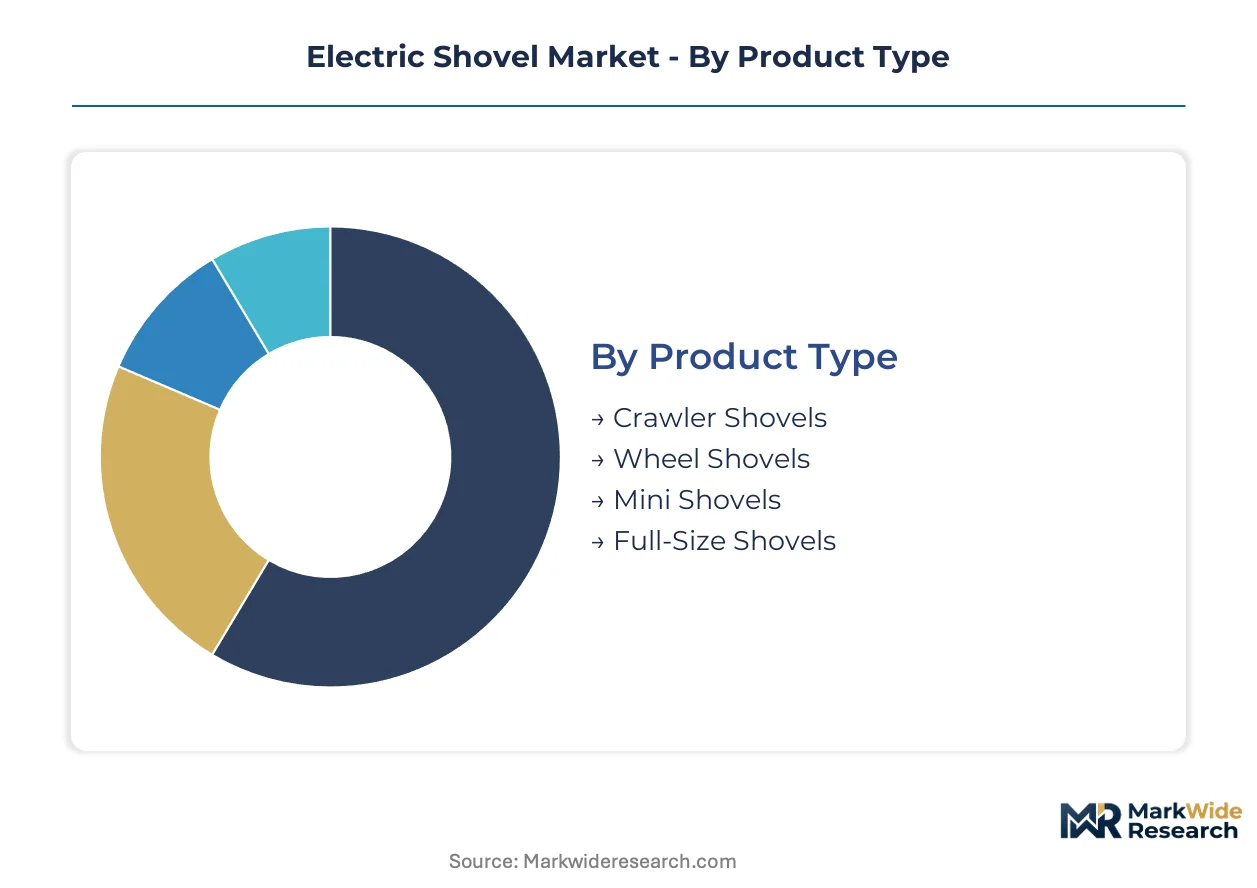
Electric shovel procurement splits sharply across capital intensity thresholds, with mining-grade configurations demanding substation infrastructure and construction crossover units prioritizing mobility. Segment boundaries increasingly blur as OEMs architect modular platforms spanning multiple size classes and powertrain variants.
Product Type:
Capital intensity escalates dramatically from wheeled quarry units to tethered crawler systems requiring dedicated electrical infrastructure.
- Crawler Shovels:Track-mounted platforms rated above 15 cubic meters dominate open-pit copper and iron ore extraction. Australian iron ore operators in the Pilbara region specify these for 24-hour continuous loading cycles where stability on unimproved benches determines productivity.
- Wheel Shovels:Rubber-tired configurations sacrifice some stability for rapid face-to-face mobility in multi-bench quarries. Brazilian limestone and aggregate producers favor these for contract mining operations requiring frequent site relocation.
- Mini Shovels:Compact diesel-electric units below 5 cubic meters serve urban demolition and confined civil works.
- Full-Size Shovels:Mid-range crawler and wheeled platforms between 10-20 cubic meters bridge construction and light mining applications.
Mature deployment sits with crawler shovels. Newer deployment is concentrated in wheel shovels.
End User:
Customer archetypes diverge on uptime requirements, with mining operators accepting 18-month delivery cycles for custom configurations while construction buyers prioritize parts availability.
- Mining:Surface coal, copper, and iron ore extraction commands the premium tier, with operators specifying AC-drive systems and autonomous haulage integration. Vale's Carajás complex in Brazil and state-owned conglomerates in China's Shanxi province anchor demand for 400-ton-class machines.
- Construction:Heavy civil earthmoving and quarry operations drive medium-duty procurement, with buyers evaluating total cost per cubic meter moved rather than upfront capital.
- Agriculture:Drainage excavation and land leveling represent sporadic demand for compact and mini configurations.
- Demolition:Building deconstruction and site clearance generate intermittent requirements for specialized boom geometries and hydraulic attachments.
Volume concentration remains with mining. Margin expansion is steepest in construction crossover segments.
Application:
Functional specialization determines attachment specification and boom kinematics, with excavation duty cycles imposing the severest mechanical stress.
- Excavation:Continuous loading of haul trucks in bench mining requires reinforced undercarriages and high-torque swing drives. Chilean copper producers specify these configurations for altitude-compensated powertrain performance.
- Material Handling:Stockpile management and port operations favor extended reach booms with grapple attachments for bulk commodity transfer.
- Earthmoving:Mass grading and cut-fill operations utilize standard bucket configurations with priority on cycle speed over breakout force.
- Landscaping:Precision contouring and environmental restoration demand mini shovels with fine-control hydraulics.
Equipment utilization peaks in excavation. Application diversity broadens fastest in material handling.
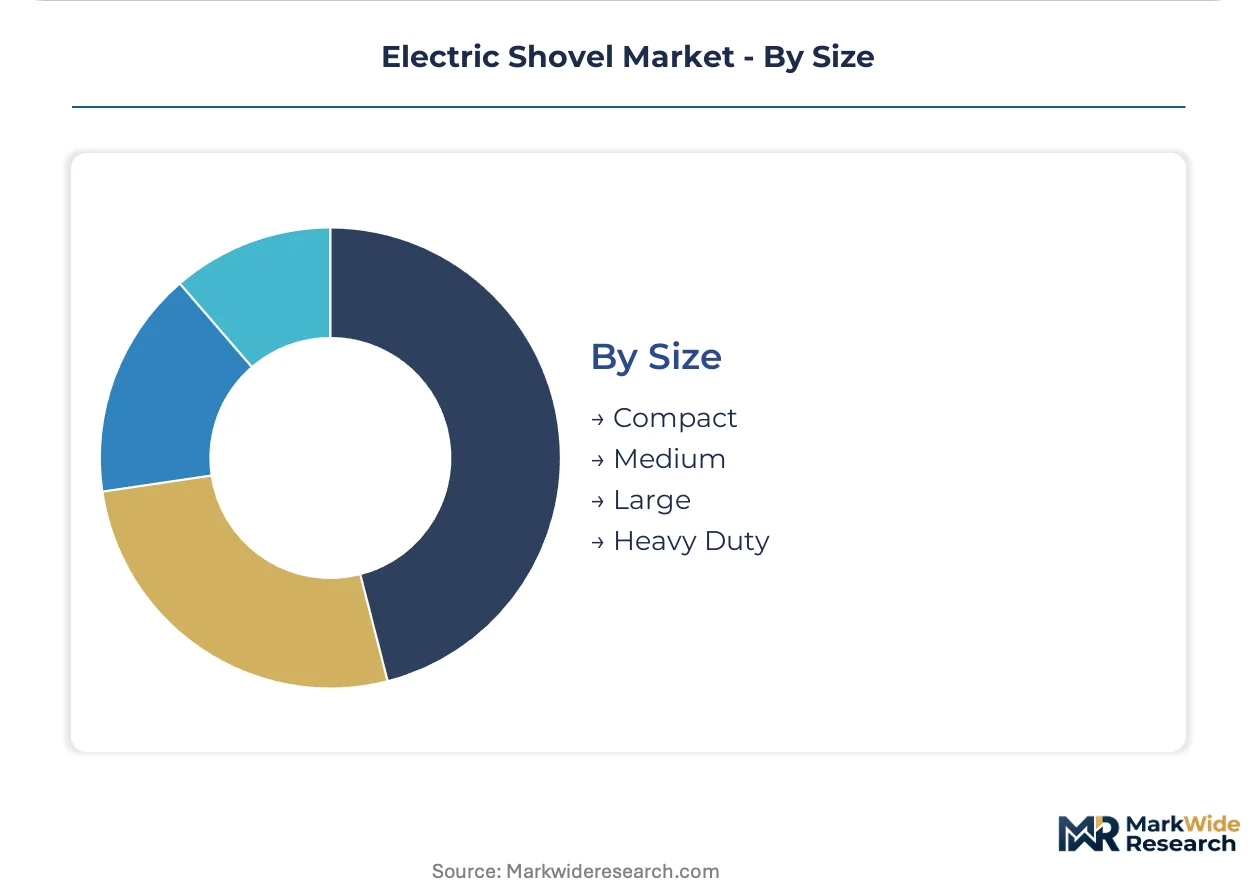
Size:
Size-class boundaries align with haul truck matching economics, with 200-ton and 400-ton truck fleets dictating shovel specification.
- Heavy Duty:Machines above 30 cubic meters bucket capacity integrate directly with autonomous haulage systems and command bundled long-term service contracts. Australian and Brazilian super-pit developments specify these for single-pass loading efficiency.
- Large:20-30 cubic meter platforms serve mid-tier mining operations and large-scale quarry production with balanced capital and operating cost profiles.
- Medium:10-20 cubic meter units dominate construction and aggregate applications where truck fleet heterogeneity requires loading flexibility.
- Compact:Sub-10 cubic meter configurations address urban infrastructure and specialized civil works with restricted access.
Technology migration originates in heavy duty. Volume scaling is most pronounced in medium size classes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara region in Western Australia anchors electric shovel procurement for iron ore super-pits, with BHP and Rio Tinto specifying 400-ton-class machines for autonomous haulage integration. Surface mining corridors in Brazil, China, and the United States concentrate demand for high-voltage tethered systems.
Australia
Iron ore extraction in the Pilbara and Hunter Valley drives demand for heavy-duty crawler shovels above 30 cubic meters. The Australian government's Safeguard Mechanism reforms tighten emissions baselines for large mining facilities. Perth-based equipment distributors coordinate fleet standardization across BHP's South Flank and Rio Tinto's Gudai-Darri operations.
China
Coal mining in Shanxi province and Inner Mongolia autonomous region consumes the largest volume of electric shovels above 20 cubic meters. GB standards for non-road mobile machinery electrification mandate progressive emission reductions through 2030. Taiyuan Heavy Industry maintains manufacturing presence in Shanxi's capital to serve state-owned mining conglomerates.
Brazil
Vale's Carajás and Serra Sul iron ore complexes represent underpenetrated demand for 400-ton-class electric shovels as decarbonization roadmaps accelerate. ANVISA and environmental licensing frameworks impose stricter tailings and emissions protocols on new mine developments. Equipment procurement concentrates in Pará state's northern mining corridor.
United States
Copper operations in Arizona and coal extraction in Appalachia face EPA Tier 4 Final compliance deadlines that accelerate fleet turnover. MSHA electrical safety certification extends approval timelines for new high-voltage platforms. Phoenix-area mining equipment dealers coordinate specification alignment between shovel OEMs and Freeport-McMoRan's Morenci complex.
Chile
Altitude-compensated powertrains dominate copper extraction in the Atacama Desert and central mining districts. The Ministry of Mining's National Mining Policy 2050 outlines electrification targets for surface operations. Antofagasta Minerals and Codelco specify AC-drive systems for high-elevation pits above 3,000 meters.
Electric Shovel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrification capability and aftermarket service bundling. The supply base consolidates around three tiers: integrated mining equipment conglomerates with captive financing arms, specialized shovel OEMs with regional fabrication footprints, and component suppliers seeking forward integration into final assembly. Strategic moves center on modular powertrain architecture licensing and multi-year maintenance contract anchoring.
Among integrated mining equipment conglomerates, Caterpillar Inc. and Komatsu Mining Corp. exemplify the premium-tier archetype through AC-drive technology leadership and captive parts networks. SANY occupies a position within the delivered-cost-focused tier serving emerging market procurement. These three anchors span the strategic spectrum from aftermarket-anchored North American dominance to aggressive emerging market penetration.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Mining Corp. |
| Hitachi Construction Machinery |
| Liebherr Group |
| SANY |
| P&H Mining |
| IZ-KARTEX |
| Taiyuan Heavy Industry Co., Ltd. |
| L&H Industrial |
| Others |
Value Network & Pricing Analysis
LME copper futures and Chinese rare earth oxide indices cascade through electric shovel manufacturing tiers, compressing margins on AC-drive motors while amplifying pricing power for OEMs with captive magnet processing. Tier-one mining operators absorb cost pass-throughs through bundled service contracts, whereas quarry contractors face spot-market volatility in hydraulic component sourcing.
Pricing Analysis
Cost-per-ton-moved contracts anchor electric shovel procurement, with Australian iron ore operators negotiating throughput-linked payments that shift uptime risk to OEM service arms. Price differentiation rests on AC-drive certification tier and autonomous haulage integration depth, with MSHA-compliant platforms commanding premiums over baseline configurations. Cost compression in mid-size wheel shovels intensifies as SANY and Chinese competitors expand export capacity. Emerging market contractors exhibit highest price sensitivity, while Pilbara super-pit operators prioritize energy efficiency guarantees over upfront capital.
Supply Chain Analysis
Regional distribution centers in Perth, Phoenix, and Santiago coordinate hub-and-spoke patterns for high-voltage drivetrain components, with emergency spools concentrated near Chilean copper belts and Australian iron ore corridors. Manufacturing draws from Japan for precision gearing, Germany for hydraulic systems, and China for structural fabrications. Single-source vulnerability concentrates in rare earth magnet supply from Chinese processing facilities. Distribution runs through OEM-captive service depots rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric shovel procurement sits in a technology-transition phase, with tethered and battery-electric platforms displacing diesel-hydraulic legacy fleets under tightening emissions mandates.
For Market Incumbents: Anchor aftermarket revenue through multi-year maintenance contracts that lock in high-voltage technician deployment, countering margin erosion from Chinese delivered-cost competition. Prioritize modular powertrain architecture R&D to accommodate fuel-cell retrofits, defending position against emerging battery-OEM entrants.
For New Entrants and Emerging Players: Launch via retrofit-ready conversion kits targeting cost-constrained mid-tier mining operators in Brazil and Indonesia, bypassing greenfield capital intensity. Brazilian iron ore expansion represents the most penetrable white-space, with Vale's decarbonization roadmap creating demand for 400-ton-class electric platforms without incumbent lock-in.
For Investors and Strategic Acquirers: Distressed-cycle entries favor shovel OEMs with proven AC-drive integration and ANVISA or MSHA certification pipelines in Chile and the United States. Long-term viability hinges on electrification IP depth rather than hydraulic legacy. Watch Chilean Ministry of Mining electrification targets as the inflection signal for South American fleet turnover velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Powertrain Architecture | Enables battery, tethered, and fuel-cell variants within single chassis families for mining OEMs. |
| Multi-Year Service Contract Bundling | Captures aftermarket value and locks in high-voltage technician deployment for Australian operators. |
| Retrofit-Ready Platform Design | Extends asset life for Brazilian and Indonesian cost-constrained mining contractors. |
| Autonomous Haulage Integration | Reduces load cycle variability for Pilbara iron ore operators coordinating with driverless truck fleets. |
| GB Standard Compliance Investment | Secures procurement access for Shanxi province and Inner Mongolia state-owned conglomerates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving maintenance directors at Chilean copper operations, procurement leads at Australian iron ore super-pits, aftermarket service heads at North American mining equipment distributors, and plant engineers at Chinese state-owned mining conglomerates. SEC 10-K disclosures, MSHA certification databases, ANVISA environmental licensing records, and Australian Bureau of Statistics mining capital expenditure reports supplied quantitative validation. Bottom-up unit economics and top-down sectoral demand models underwent iterative reconciliation.
Data-stream reconciliation across equipment shipment records, mine development pipeline tracking, and energy price scenario modeling informed the analytical framework. Segmentation dimensions spanned powertrain configuration, size class, end-use mining versus construction, and regional regulatory cluster. CAGRs derived from slope-log regression across the projection horizon, with electric grid infrastructure buildout schedules and copper price trajectory assumptions as primary forecast inputs.
Regulatory timeline acceleration, rare earth supply disruption, and mining capital commitment delays are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crawler Dozers Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
United States Crane Market
Construction Equipment
Rotomolding Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Separation Machinery Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Fixed Crane Market