
 Italy Metal Fabrication Equipment Market | 2026-2036
Italy Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Metal Fabrication Equipment Market Foresight
CE marking and the EU Machinery Directive is repositioning the compliance burden for entry into the Italian metal fabrication equipment sector. Salvagnini leverages its integrated automation systems to dominate high-end sheet metal processing lines serving automotive Tier 1 suppliers. Prima Industrie anchors its position through concentrated R&D in fiber laser sources for thick-plate cutting. Amada competes aggressively on service network density across the Po Valley manufacturing belt.
Italy metal fabrication equipment encompasses CNC machines, press brakes, laser cutters, and welding systems engineered to cut, form, join, and finish metallic workpieces with tolerances typically ranging from ±0.1 mm to ±0.01 mm depending on process control. This equipment serves as the production backbone for industries requiring precise metal components, from aircraft fuselage stringers to reinforced steel frameworks. CNC machines and laser cutters command the largest installed base, reflecting sustained replacement demand from job shops and OEM captive facilities. Electric technology variants within press brakes and bending systems represent the fastest-expanding configuration as energy efficiency mandates tighten operating cost structures for Milanese and Turinese fabricators.
Italy's Ministry of Economic Development, INAIL workplace safety standards, and EU F-Gas Regulation collectively shape equipment specifications, refrigerant choices in cooling systems, and operator certification requirements for metalworking machinery deployment. BIS certification alignment for exported Indian components and REACH material compliance for coated tooling add layered conformity obligations for equipment vendors serving cross-border supply chains. Stakeholders must monitor how the EU AI Act's risk classification framework will apply to autonomous quality inspection modules increasingly embedded in Italian-built fabrication lines.
Market Dynamics
Electric press brake technology is compressing energy consumption benchmarks across Lombardy and Emilia-Romagna fabrication clusters, forcing incumbent hydraulic equipment into accelerated replacement cycles.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Binding emission reduction targets for manufacturing facilities are compelling Milanese and Turinese job shops to retire hydraulic systems in favor of servo-electric bending equipment.
- Aerospace precision fabrication demand:Defense and commercial aircraft programs are expanding capacity for titanium and aluminum structural components with sub-0.05 mm tolerance requirements.
- Fiber laser thick-plate cutting:12 kW and 20 kW source platforms are displacing plasma and oxyfuel methods in steel service centers throughout the Po Valley manufacturing belt.
Market Restraints
- Specialized steel alloy input volatility:Tool steel and high-strength plate pricing fluctuations compress margin predictability for capital equipment producers dependent on German and Swedish mill supply.
- CE marking compliance timeline extension:EU Machinery Directive conformity assessment procedures for autonomous quality inspection modules are extending time-to-market for integrated system vendors.
- Used equipment channel competition:Refurbished German and Swiss CNC press brakes flood secondary markets at 40-60 percent of new-equipment cost, constraining greenfield sales.
Strategic Opportunities
- Southern Italy fabrication infrastructure gap:Campania and Sicily industrial zones remain underpenetrated by automated sheet metal processing relative to northern density.
- EU AI Act risk classification framework:Autonomous defect detection and predictive maintenance modules embedded in Italian-built lines will require certification, creating first-mover advantage for compliant system architects.
- Hybrid electric-hydraulic press brake architecture:Convergence of servo motor precision with hydraulic force capacity addresses transitional buyer segments unwilling to abandon proven forming mechanics.
Industry Challenges
- CNC programming and Industry 4.0 integration expertise scarcity:Northern Italian fabricators report acute shortage of technicians capable of deploying IoT-enabled production monitoring across heterogeneous machine vintages.
- REACH material compliance documentation burden:Coated tooling and cooling system refrigerant suppliers face extended verification timelines for cross-border component shipments into Italian assembly plants.
- Legacy hydraulic system interoperability friction:Retrofitting 1990s-era press brakes with modern control architectures requires custom mechanical adaptation, complicating upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Metal Fabrication Equipment Market |
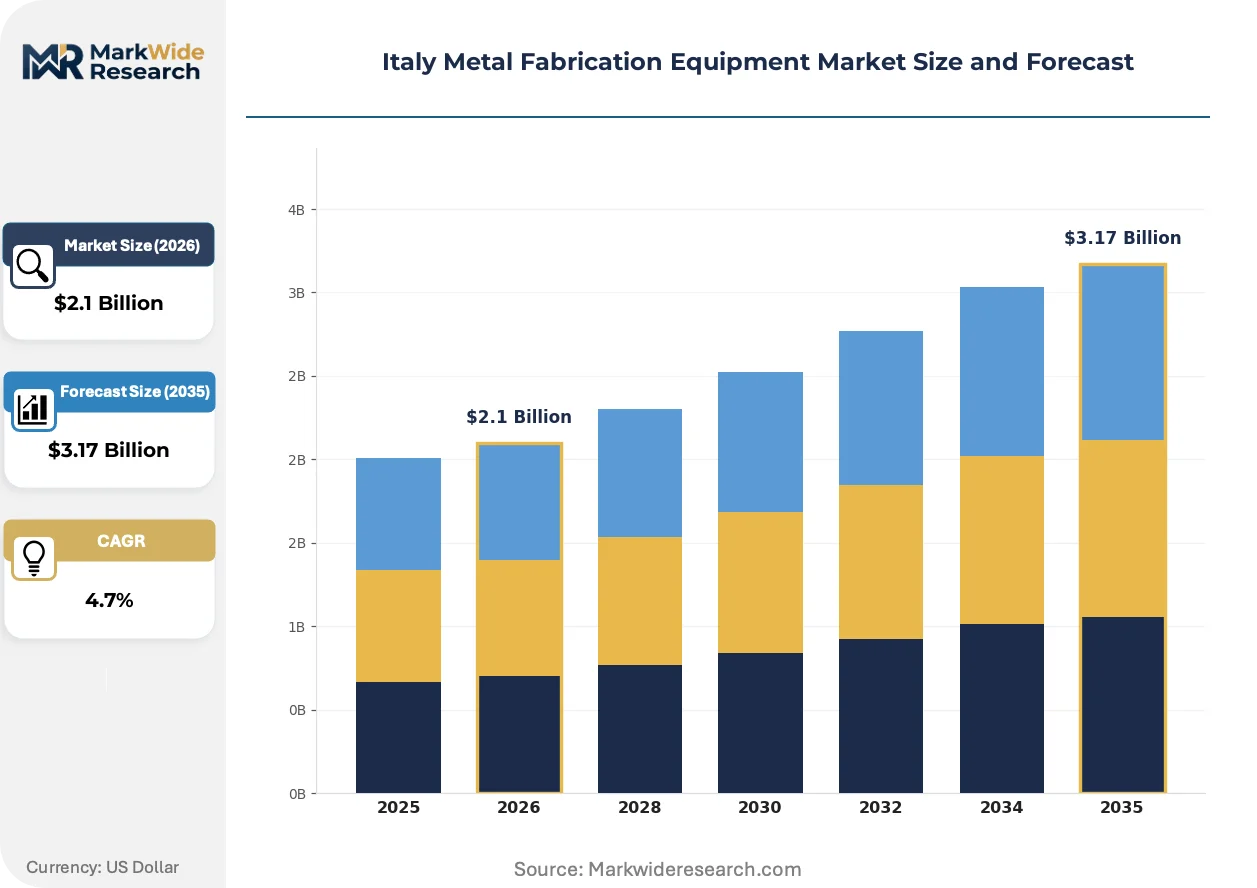
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Machines, Press Brakes, Laser Cutters, Welders End User: Aerospace, Construction, Automotive, Electronics Technology: Mechanical, Hydraulic, Pneumatic, Electric Application: Sheet Metal, Structural Steel, Tank Fabrication, Pipe Bending |
| Companies Covered | Fagor Arrasate, Salvagnini, TRUMPF, LVD Group, Fives Group, DMG Mori, Prima Industrie, Amada, Bystronic Laser AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Metal Fabrication Equipment Market Shifts & Advancements
Automation architecture and regulatory compliance frameworks are compressing equipment replacement cycles while redefining supplier-customer relationships across Italian metalworking clusters.
Collaborative robotic bending cells are automating small-batch production runs previously handled by manual press brake operators. Tier 2 automotive suppliers in Modena and Reggio Emilia are deploying these systems at 18-24 month payback thresholds. The technology is automating fixture changeover and part handling, collapsing setup times from 45 minutes to under 8 minutes for mixed-model fabrication.
F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon refrigerants from laser cooling systems by 2030. Equipment vendors must redesign thermal management architectures using CO2 or water-glycol alternatives. Thick-plate fiber laser installations above 6 kW in Bologna and Milan industrial parks face accelerated obsolescence risk without cooling system retrofit compatibility.
After-sales service unbundling is fragmenting traditional maintenance contract structures. Large Po Valley automotive Tier 1 suppliers now demand à-la-carte spare parts procurement and remote diagnostics subscriptions rather than comprehensive service agreements. This behavioral shift concentrates in Emilia-Romagna, where Ferrari and Lamborghini supply chain auditors enforce total cost of ownership transparency across 10-year equipment lifecycles.
Italy Metal Fabrication Equipment Market Segmentation
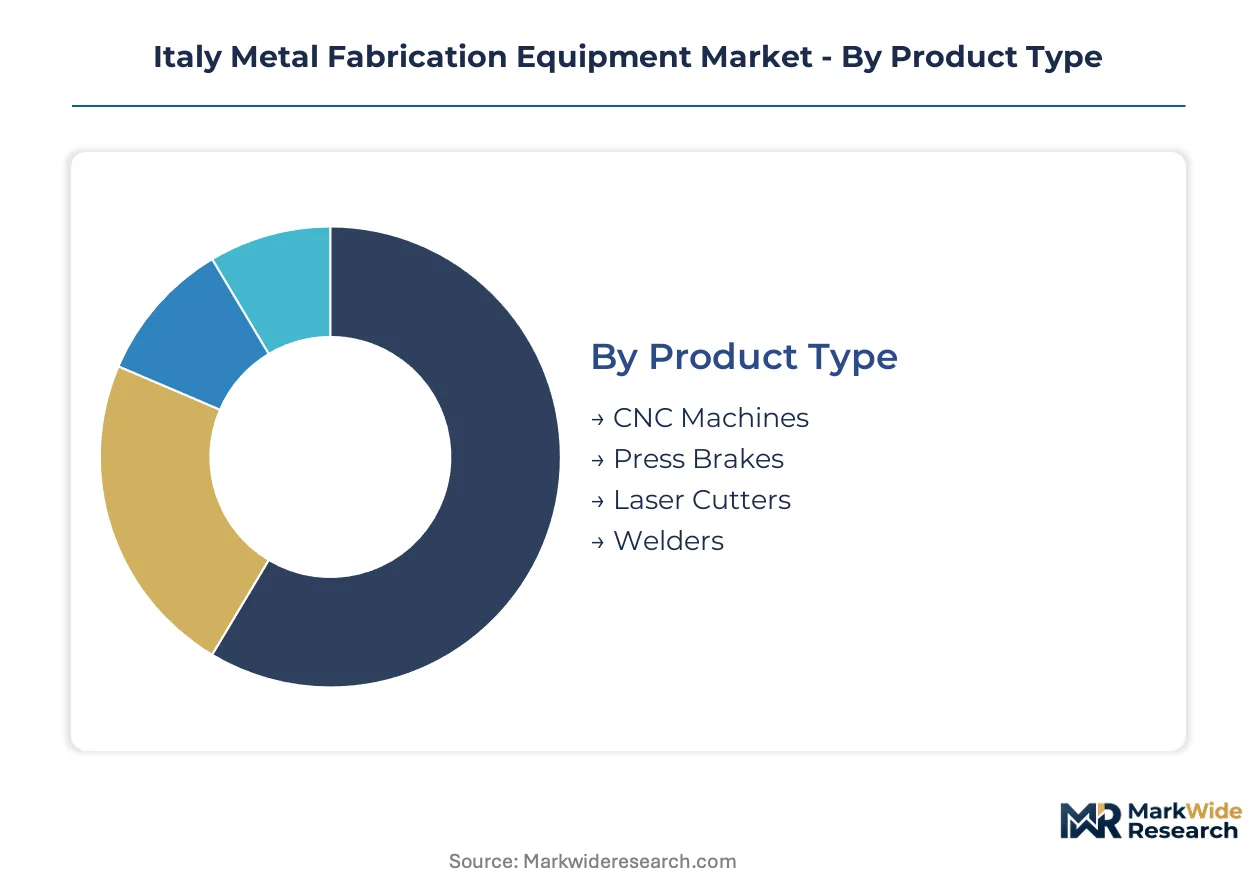
Equipment segmentation in Italy metal fabrication reveals distinct capital deployment patterns across northern industrial clusters. Procurement decisions in Milanese and Bolognese job shops align equipment type with tolerance requirements and batch economics.
Product Type:
Capital intensity varies sharply across equipment categories, with fiber laser platforms demanding the highest upfront investment followed by multi-axis CNC machining centers.
- CNC Machines:Multi-axis milling and turning centers dominate high-mix, low-volume production across Turinese automotive supplier parks. Demand concentrates in 5-axis configurations for titanium aerospace structural components where Salvagnini and DMG Mori maintain established service networks.
- Press Brakes:Servo-electric and hybrid hydraulic-electric bending systems form the replacement core in Lombardy sheet metal job shops. Milanese fabricators prioritize 200-400 ton electric models to satisfy EU Green Deal energy efficiency benchmarks while maintaining forming precision.
- Laser Cutters:Fiber source platforms from 6 kW to 20 kW displace CO2 systems in Emilia-Romagna steel service centers.
- Welders:Robotic MIG and TIG cells automate repetitive joining operations for Modena-area automotive exhaust fabricators.
Most installed capacity flows through CNC Machines. Expansion is steepest in Laser Cutters.
End User:
Application complexity and certification requirements drive divergent equipment specifications across buyer verticals.
- Aerospace:Tier 1 suppliers in Turin and Varese deploy 5-axis machining centers and fiber laser cutting systems for aluminum and titanium airframe components. AS9100 quality mandates enforce sub-0.05 mm tolerance verification protocols.
- Automotive:Ferrari and Lamborghini supply chain auditors in Modena and Sant'Agata Bolognese mandate traceable fabrication equipment with predictive maintenance capability.
- Construction:Steel framework fabricators across Veneto and Friuli-Venezia Giulia prioritize cost-efficient plasma cutting and semi-automatic welding systems.
- Electronics:Precision sheet metal enclosures for telecommunications hardware concentrate in Brianza manufacturing districts.
Aerospace commands the highest equipment specification tier. Construction absorbs the greatest unit volume.
Technology:
Energy transition timelines and force-precision tradeoffs segment adoption patterns across northern Italian clusters.
- Electric:Servo motor-driven press brakes and bending systems deliver 60-70 percent energy reduction versus hydraulic equivalents. Milanese job shops facing INAIL workplace safety audits prefer electric architectures for reduced noise and eliminated hydraulic oil contamination risk.
- Hydraulic:Legacy 1990s-era systems persist in Campania and Sicily where replacement capital remains constrained.
- Mechanical:Flywheel-driven stamping presses serve high-volume automotive component production in Piedmont.
- Pneumatic:Light-duty forming and clamping applications utilize compressed air systems in small-batch Emilian job shops.
Hydraulic technology retains the largest installed base. Electric configurations are gaining share fastest.
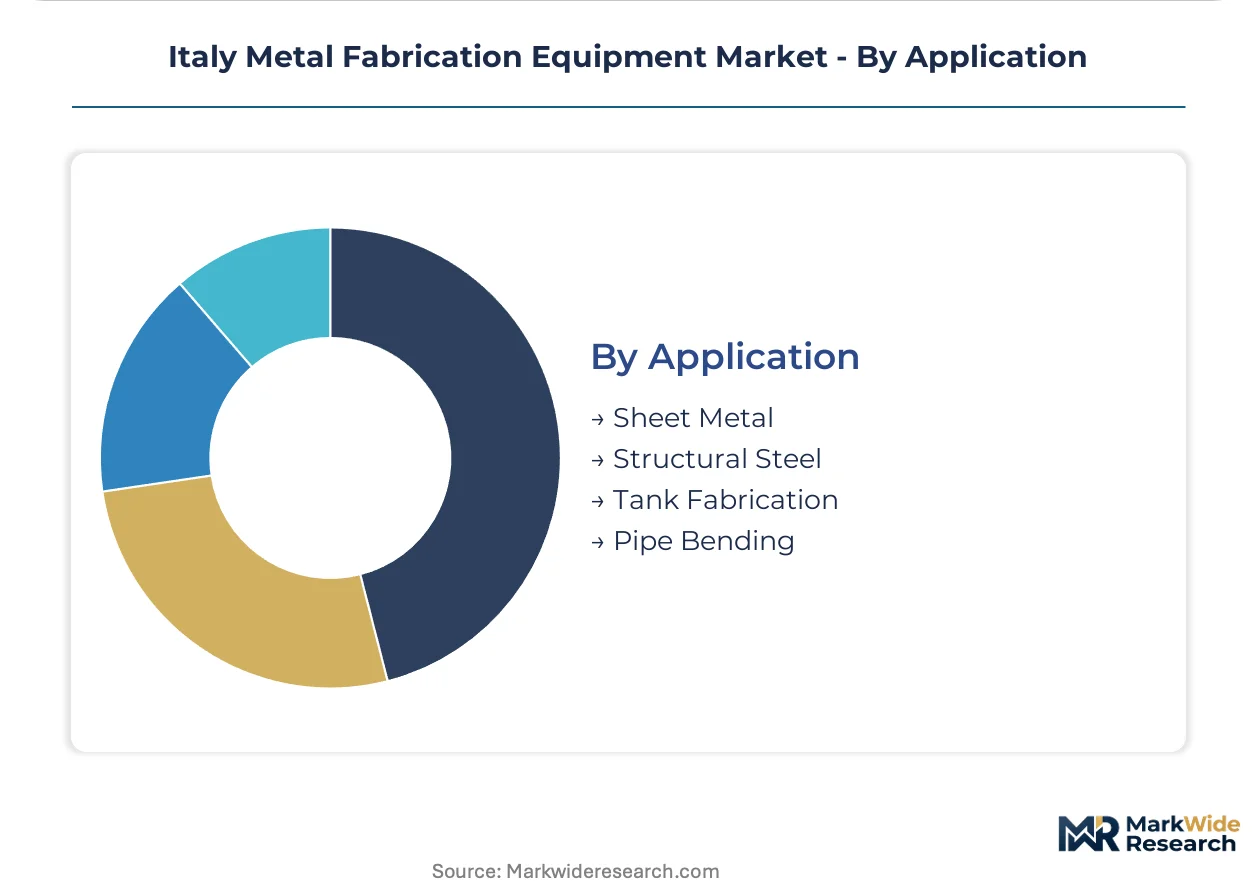
Application:
Workpiece geometry and material thickness dictate equipment selection across Po Valley fabrication corridors.
- Sheet Metal:Thin-gauge aluminum and steel processing dominates Lombardy appliance and electronics enclosure manufacturing. Automated panel bending cells from Salvagnini serve white goods producers in Milan and Monza.
- Structural Steel:Heavy beam and column fabrication for commercial construction concentrates in Veneto and Friuli-Venezia Giulia steel service centers.
- Tank Fabrication:Pressure vessel and storage tank welding applications utilize submerged arc and robotic MIG systems in Emilian industrial zones.
- Pipe Bending:CNC mandrel and roll benders serve plumbing and HVAC contractors across northern Italy.
Sheet Metal applications deploy the most sophisticated automation. Pipe Bending shows the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled CNC programmers and Industry 4.0 integration specialists concentrate heavily in northern Italy's machine tool corridor, anchoring regional equipment demand patterns.
Lombardy
Milanese appliance manufacturers and electronics enclosure fabricators drive demand for automated panel bending cells. EU Green Deal energy efficiency mandates accelerate servo-electric press brake replacement of legacy hydraulic systems. The Monza-Brianza industrial zone hosts dense clusters of precision sheet metal job shops serving white goods producers.
Emilia-Romagna
Automotive Tier 1 suppliers to Ferrari and Lamborghini mandate predictive maintenance capability and total cost of ownership transparency. F-Gas Regulation phase-down schedules force cooling system redesigns in Bologna and Modena laser cutting installations. Sant'Agata Bolognese supply chain auditors enforce traceable fabrication equipment specifications across 10-year lifecycles.
Piedmont
Turin-based aerospace Tier 1 suppliers expand 5-axis machining capacity for titanium and aluminum airframe components. AS9100 quality mandates enforce sub-0.05 mm tolerance verification protocols. The Varese industrial corridor anchors precision fabrication demand for defense and commercial aircraft programs.
Veneto
Steel framework fabricators prioritize cost-efficient plasma cutting systems for commercial construction applications. INAIL workplace safety standards shape equipment specifications and operator certification requirements. Friuli-Venezia Giulia steel service centers concentrate heavy beam and column fabrication capacity.
Campania
Underpenetrated automated sheet metal processing relative to northern density creates infrastructure investment opportunities. Legacy hydraulic systems persist where replacement capital remains constrained. Naples-area industrial zones show rising interest in hybrid electric-hydraulic press brake architectures.
Italy Metal Fabrication Equipment Market Competitive Landscape
The competitive structure tilts toward integrated automation specialists serving high-volume automotive and aerospace verticals. Salvagnini anchors the premium tier through bundled hardware-software-service offerings, while mid-market vendors compete on service network density and retrofit compatibility. Strategic archetypes include full-line automation integrators, component-specialist technology licensors, and regional service-intensive distributors. Capacity expansion in fiber laser source platforms and M&A targeting predictive maintenance software capabilities dominate competitive moves.
Among Italian-headquartered fabricators, Salvagnini S.p.A. and Prima Industrie S.p.A. occupy positions as integrated automation specialists. Salvagnini exemplifies the full-line systems architect archetype through its dominance of high-end sheet metal processing lines. Prima Industrie anchors the fiber laser technology tier with concentrated R&D positioning. TRUMPF GmbH + Co. KG, a German-based Co., Ltd. structure, represents the multinational scale-driven competitor archetype competing aggressively on service network density across the Po Valley manufacturing belt.
| Leading Market Players |
|---|
| Fagor Arrasate |
| Salvagnini |
| TRUMPF |
| LVD Group |
| Fives Group |
| DMG Mori |
| Prima Industrie |
| Amada |
| Bystronic Laser AG |
| Others |
Supply & Pricing Matrix
EU Green Deal industrial decarbonization mandates gate qualified supply and premium-tier pricing access for Italian metal fabrication equipment vendors, as CE marking and F-Gas Regulation compliance costs stratify market participation between certified system integrators and component assemblers. Milanese automotive Tier 1 suppliers now demand unbundled service contracts and predictive maintenance subscriptions, compressing traditional bundled-equipment margins while elevating transparent total cost of ownership documentation as a pricing differentiator.
Pricing Analysis
The bundled-versus-unbundled service split now defines pricing architecture across northern Italian fabrication clusters. Three-tier pricing structure across premium, standard, and economy levels separates Salvagnini-integrated automation lines from mid-market electric press brakes and refurbished German CNC equipment flooding secondary channels. Price differentiation hinges on CE marking certification tier and predictive maintenance software integration. Cost compression in the standard tier intensifies because Campania-based fabricators prioritize hybrid electric-hydraulic architectures over full electric conversion. Used equipment channels exhibit highest price sensitivity; aerospace Tier 1 suppliers in Turin show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Ferrari and Lamborghini supply chain auditors, while regional distributors serve fragmented job shops across the Po Valley manufacturing belt. Component sourcing draws from Germany, Switzerland, and Sweden for precision ball screws, servo motors, and specialized tool steel alloys. Raw material dependencies center on high-strength steel plate, fiber laser source platforms, and refrigerant alternatives for thermal management systems. Single-source vulnerability concentrates in German mill supply for aerospace-grade titanium processing equipment. Distribution runs through authorized service networks anchored in Milan, Bologna, and Turin industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU AI Act risk classification frameworks and F-Gas Regulation phase-down schedules continuously reset equipment qualification barriers and replacement demand cycles.
For Market Incumbents: Hedge against margin erosion from unbundled service demands by anchoring proprietary predictive maintenance software to hardware sales, while accelerating CE marking pre-certification for autonomous quality inspection modules before EU AI Act enforcement tightens. Vertical integration into fiber laser source manufacturing reduces exposure to German component pricing volatility. For New Entrants and Emerging Players: Regional distributors in Campania and Sicily offer lowest competitive density for automated sheet metal processing lines, where legacy hydraulic system replacement cycles lag northern Italy by 5-7 years. Target hybrid electric-hydraulic press brake architectures as the transitional technology of choice for capital-constrained southern fabricators seeking EU Green Deal compliance without full electric conversion costs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service-intensive distributors with dense Po Valley technician networks but limited software capabilities. Long-term viability across the analysis window favors targets with installed base access for retrofit predictive maintenance deployment. Watch EU AI Act certification timelines as the inflection signal for autonomous module market access.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Integration | Captures recurring revenue streams from Ferrari and Lamborghini supply chain auditors demanding 10-year lifecycle transparency. |
| CE Marking Pre-Certification Investment | Accelerates time-to-market for autonomous quality inspection modules under EU AI Act risk classification frameworks. |
| Hybrid Electric-Hydraulic Architecture Development | Addresses transitional buyer segments in Campania unwilling to abandon proven forming mechanics. |
| Southern Italy Distribution Network Expansion | Penetrates underautomated Campania and Sicily industrial zones with localized service capabilities. |
| F-Gas Compliant Cooling System Redesign | Eliminates obsolescence risk for 6 kW and above fiber laser installations in Bologna and Milan industrial parks. |
Research Methodology
Direct dialogue with plant engineers at Turinese aerospace Tier 1 suppliers, procurement leads at Modena automotive exhaust fabricators, aftermarket service heads at Lombardy job shops, and INAIL workplace safety auditors grounded qualitative findings. Secondary validation incorporated EU Machinery Directive implementation guidance, F-Gas Regulation phase-down schedules, REACH material compliance databases, and customs records for German and Swiss equipment imports. Bottom-up equipment shipment tallies and top-down manufacturing value-added estimates were triangulated across the analysis window.
Bottom-up modeling segmented volume and value projections by product type, technology configuration, end-use vertical, and regional industrial cluster density. The analytical framework weighted electric press brake replacement cycles against fiber laser thick-plate cutting adoption curves throughout the forecast period. CAGRs derived from historical equipment retirement patterns, EU Green Deal mandate implementation timelines, and aerospace program capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement timing and German tool steel alloy pricing volatility. Forecasts reflect documented assumptions regarding INAIL workplace safety standard revision schedules and southern Italy infrastructure investment flows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Scaffolding Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Garage Equipment Market