
 Disposable Ph Sensors Market | 2026-2036
Disposable Ph Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Ph Sensors Market Insights
Direct-to-laboratory distribution is reconfiguring as sensor vendors bypass traditional distribution layers to serve contract research organizations and biopharma quality-control labs directly. Thermo Fisher Scientific leverages its analytical instrumentation footprint to bundle disposable pH sensors with chromatography and mass spectrometry workflows. Sartorius AG anchors its position through deep integration with single-use bioreactor platforms, where pH monitoring is mandatory. PreSens Precision Sensing GmbH specializes in optical dissolved-oxygen and pH sensor spots for microfluidic and small-volume applications.
Disposable pH sensors are single-use electrochemical or optical devices that measure hydrogen-ion activity in aqueous solutions through ion-selective membranes or fluorescent indicator chemistry, typically operating across a 0–14 pH range with ±0.01 resolution for bioprocess monitoring. Their primary commercial purpose is eliminating cross-contamination risk and reducing cleaning validation burden in pharmaceutical manufacturing, food safety testing, and environmental water analysis. Electrochemical sensors dominate unit volume due to lower per-test cost and established calibration protocols, while optical sensors capture premium positioning in bioreactor applications where steam sterilization is impossible. Probe sensors lead the product-type hierarchy in biopharma end-use, whereas electrode strips expand fastest in point-of-care environmental field testing.
FDA process analytical technology guidance and EMA good manufacturing practice Annex 1 revisions on contamination control compel biopharma manufacturers to validate disposable sensor accuracy within active production lines. ISO 10993 biocompatibility testing and USP Class VI plastic certification further constrain material selection for sensors contacting cell culture media. Stakeholders must monitor how evolving pharmacopeial standards for single-use systems reshape supplier qualification timelines and sensor replacement economics.
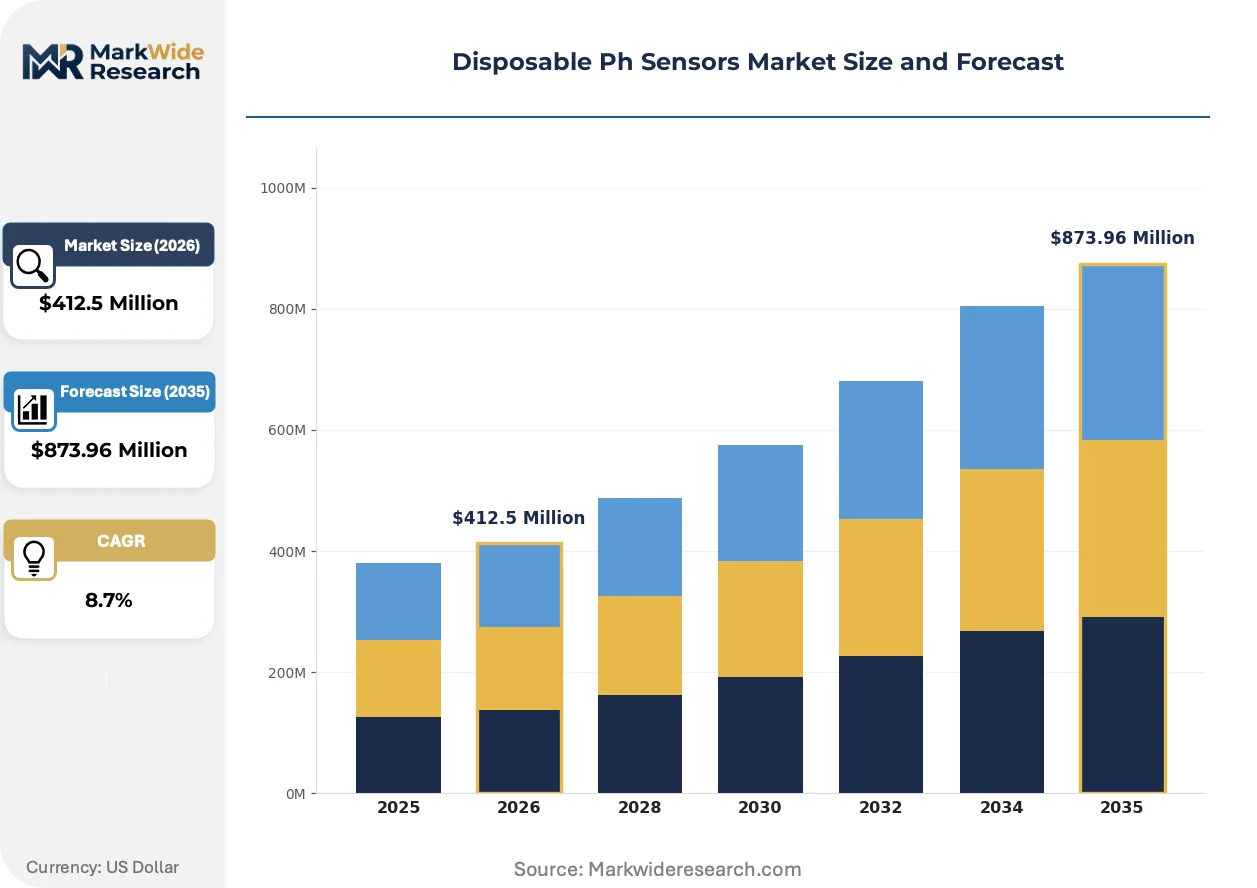
Market Dynamics
Single-use bioprocessing infrastructure is displacing stainless-steel equipment across pharmaceutical manufacturing, creating embedded demand for disposable sensors that eliminate cleaning validation cycles and cross-contamination protocols.
Growth Catalysts
- FDA process analytical technology guidance:Mandates real-time monitoring in active production lines, compelling biopharma manufacturers to validate disposable sensor accuracy within GMP workflows.
- Optical sensor chemistry:Fluorescent indicator technologies enable steam-sterilization-free bioreactor monitoring, capturing premium positioning where thermal methods fail.
- Contract manufacturing concentration in Germany, the United States, and China:CMO procurement scale drives volume commitments for electrochemical probe sensors in multi-thousand-liter single-use bioreactor installations.
Market Restraints
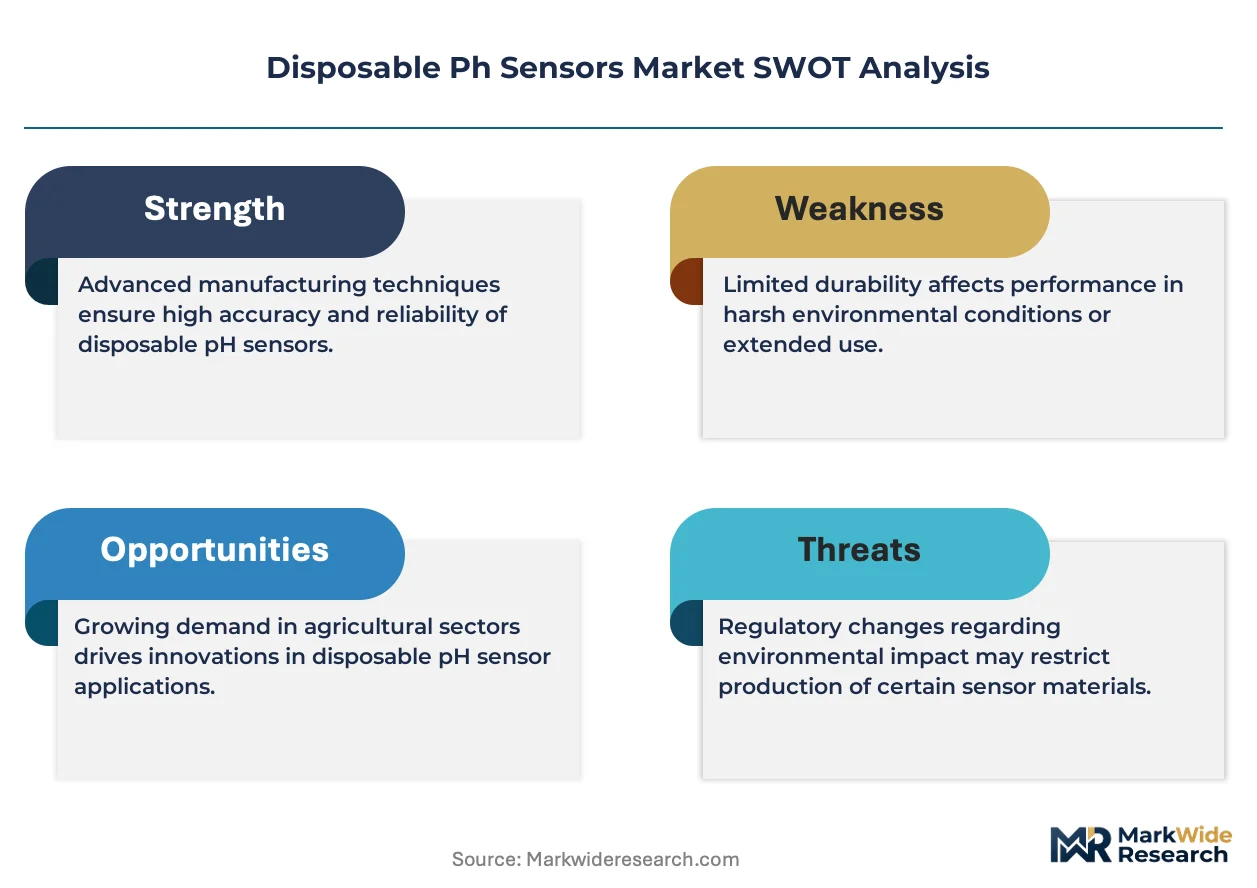
- Platinum electrode cost volatility:Electrochemical sensor manufacturing depends on precious metal inputs subject to commodity price swings that compress per-unit margins.
- Optical sensor supply concentration:Specialized fluorescent dye synthesis concentrates among German and Swiss specialty chemical suppliers, creating single-source vulnerability.
- ISO 10993 biocompatibility testing timelines:Extended validation cycles for sensors contacting cell culture media delay product launches by 12-18 months.
Strategic Opportunities
- Point-of-care environmental field testing:Electrode strip formats for water quality monitoring remain underpenetrated in Southeast Asian municipal utilities.
- EMA Annex 1 contamination control revisions:Stricter GMP requirements create regulatory tailwind for single-use sensor adoption in European fill-finish operations.
- Microfluidic convergence with optical sensing:Integration of PreSens-style sensor spots with lab-on-chip platforms opens sub-milliliter volume applications.
Industry Challenges
- Electrochemical-optical calibration protocol divergence:Biopharma quality-control labs must maintain dual competency streams, stretching technical training resources.
- Legacy SCADA integration complexity:Disposable sensor data streams require middleware development to interface with established process control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Ph Sensors Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sensors, Probe Sensors, Electrode Strips, Membrane Sensors End User: Laboratories, Agriculture, Food Industry, Environmental Monitoring Technology: Optical Sensors, Electrochemical Sensors, Solid-State Sensors, Polymer-Based Sensors Application: Soil Testing, Water Quality Monitoring, Food Testing, Industrial Processes |
| Companies Covered | Sartorius AG, Hamilton Company, Thermo Fisher Scientific Inc., Mettler-Toledo International Inc., Endress+Hauser AG, Broadley-James Corporation, PendoTECH LLC, PreSens Precision Sensing GmbH, Polestar Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Ph Sensors Market Trends and Innovations
Sensor vendors are compressing calibration and data transmission into single-use formats, eliminating the infrastructure overhead that previously anchored electrochemical probe dominance.
Optical pH sensing is virtualizing the measurement workflow by embedding fluorescent indicator chemistry directly into bioreactor film surfaces. Biopharma manufacturers running perfusion cell culture are adopting these sensor-integrated bags at accelerating rates. This technology is virtualizing the need for separate probe insertion ports and sterilization validation protocols.
EMA Annex 1 revisions on contamination control are tightening GMP requirements for sterile manufacturing environments. The guidance compels fill-finish operators to demonstrate closed-system processing with validated monitoring. Bioreactor sensor suppliers are responding with enhanced documentation packages for single-use optical systems.
Direct-to-laboratory distribution is bypassing traditional distribution layers that previously served contract research organizations. Sensor vendors now maintain dedicated sales engineering teams for biopharma quality-control labs, displacing the distributor markup structure. This channel compression is most visible in the United States where CRO consolidation has concentrated purchasing power.
Disposable Ph Sensors Market Segmentation
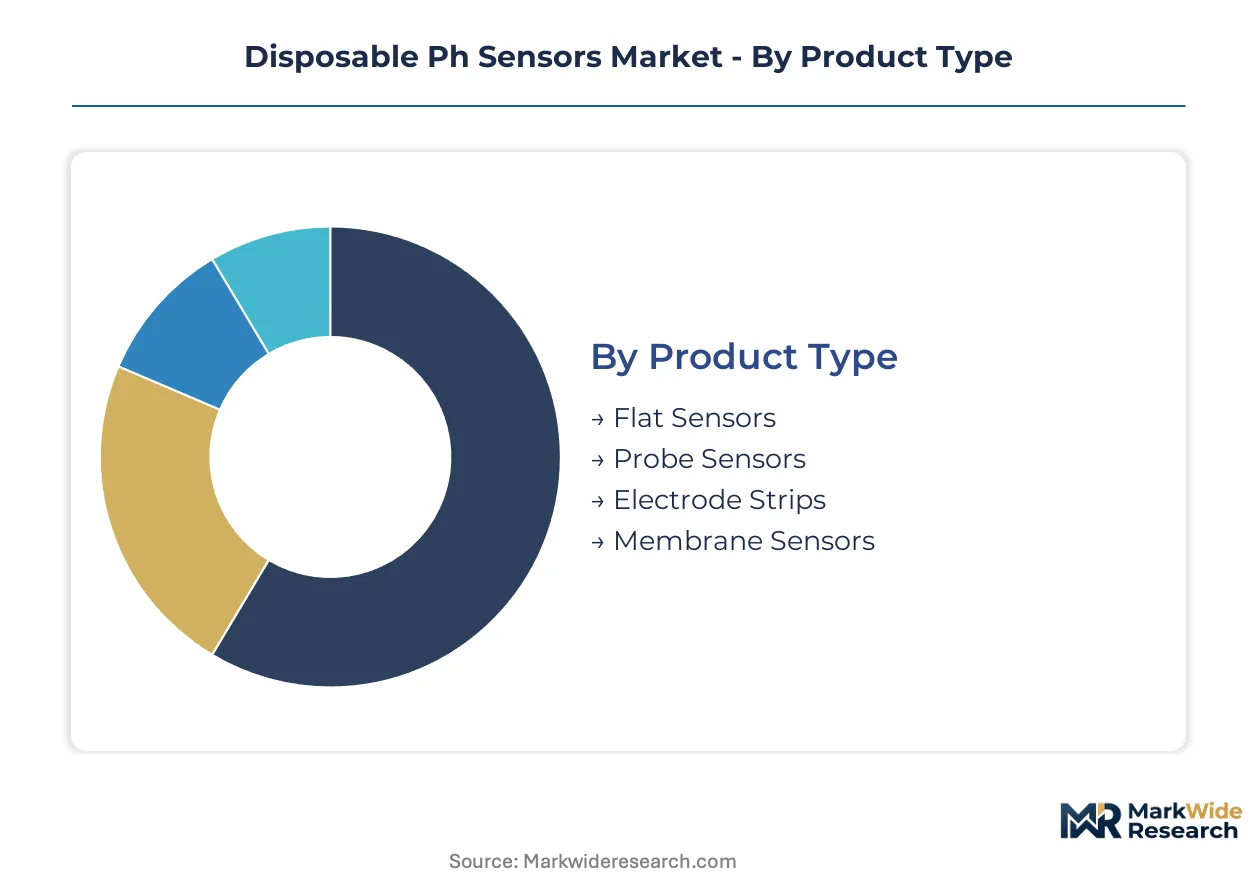
Disposable pH sensor segmentation reveals how technology choices, end-use requirements, and regulatory environments fragment procurement patterns across biopharma, environmental, and food safety verticals. Each dimension carries distinct margin profiles and qualification timelines that reshape vendor go-to-market strategies.
Product Type:
Probe sensors anchor mature biopharma installations while flat and membrane formats emerge in miniaturized applications.
- Probe Sensors:Cylindrical electrochemical assemblies with integrated reference electrodes dominate single-use bioreactor deployments. Thermo Fisher and Sartorius bundle these with chromatography workflows in German and US contract manufacturing facilities where GMP validation is mandatory.
- Flat Sensors:Thin-film electrochemical or optical configurations integrate directly into bioreactor bag surfaces, eliminating probe ports. PreSens-style sensor spots for microfluidic platforms concentrate demand in Swiss and German precision instrument clusters.
- Electrode Strips:Single-use test strips with printed conductive traces serve point-of-care environmental field testing.
- Membrane Sensors:Ion-selective membrane assemblies target specialized industrial process monitoring.
Probe sensors retain volume leadership; electrode strips hold the steepest expansion curve.
End User:
Laboratory procurement concentrates purchasing power while environmental and agricultural segments expand through distributed field deployment.
- Laboratories:Biopharma quality-control labs and CROs drive premium optical sensor adoption. Direct-to-laboratory distribution bypasses traditional channels as vendors maintain dedicated sales engineering teams for US and German contract research organizations.
- Environmental Monitoring:Municipal utilities and field testing operations favor low-cost electrode strip formats. Southeast Asian water quality programs represent underpenetrated demand for portable pH monitoring.
- Food Industry:HACCP-compliant disposable sensors support safety testing in production line environments.
- Agriculture:Soil and irrigation water testing drives seasonal procurement of robust field-deployable units.
Laboratories command premium pricing; environmental monitoring scales fastest through volume procurement.
Technology:
Electrochemical platforms dominate unit economics while optical chemistry captures sterilization-critical applications.
- Electrochemical Sensors:Glass or polymer-body probes with Ag/AgCl reference systems deliver ±0.01 pH resolution at lowest per-test cost. Established calibration protocols and ISO 10993 biocompatibility certification sustain dominance in high-volume biopharma manufacturing.
- Optical Sensors:Fluorescent indicator chemistry embedded in polymer matrices enables steam-sterilization-free monitoring. German and Swiss specialty dye suppliers concentrate upstream supply for bioreactor applications where thermal methods fail.
- Solid-State Sensors:Ion-sensitive field-effect transistor architectures target miniaturized integration.
- Polymer-Based Sensors:Flexible substrate configurations enable conformal mounting on single-use bioreactor films.
Electrochemical sensors maintain installed base dominance; optical platforms gain share fastest in sterile processing.
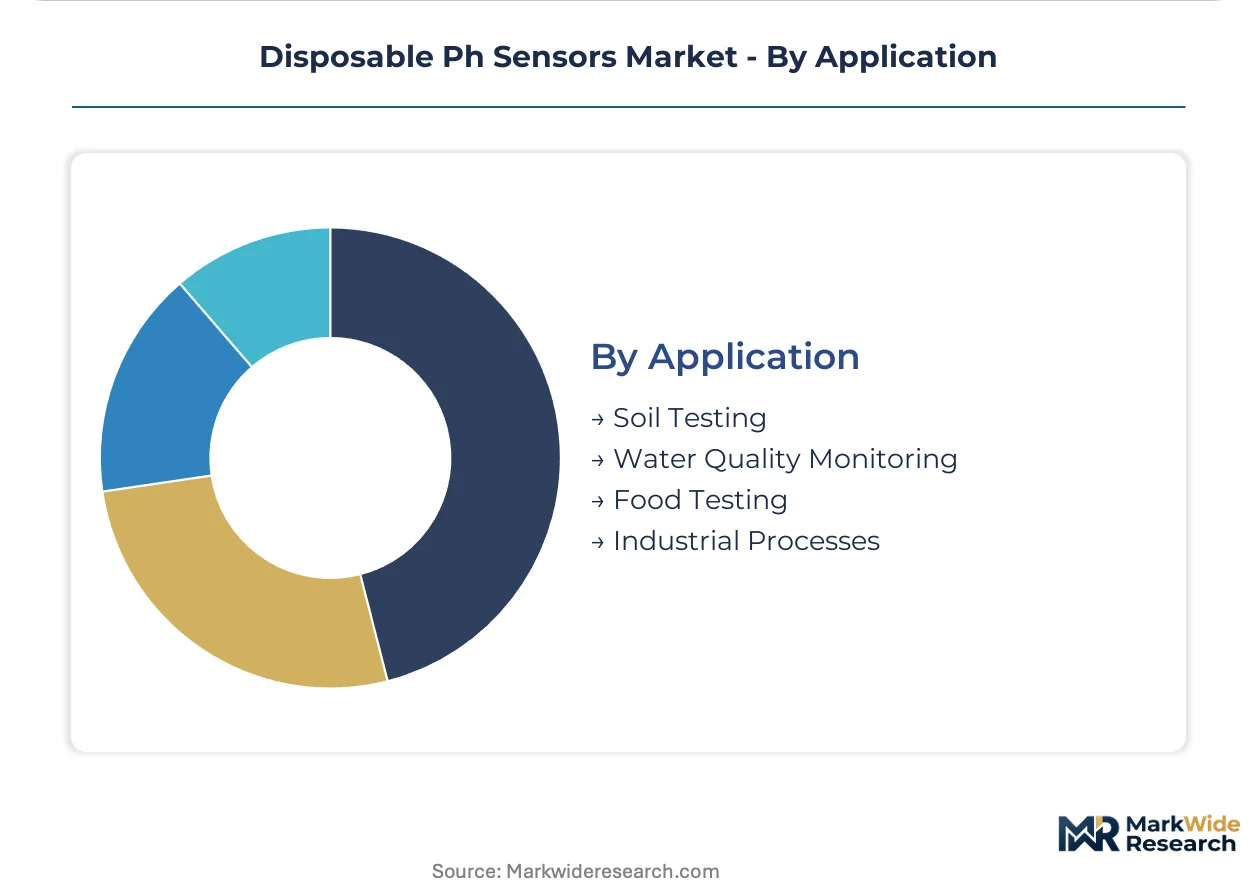
Application:
Water quality and industrial process monitoring concentrate recurring demand while food testing segments by regulatory jurisdiction.
- Water Quality Monitoring:Municipal utilities, environmental agencies, and industrial discharge compliance drive electrode strip and probe sensor procurement. US EPA and EU Water Framework Directive monitoring requirements sustain replacement cycles across German, US, and Chinese installations.
- Industrial Processes:Pharmaceutical manufacturing and chemical production embed pH sensors in continuous process control. FDA process analytical technology guidance mandates real-time monitoring in active GMP production lines.
- Soil Testing:Agricultural extension services and precision farming operations deploy portable electrochemical units.
- Food Testing:Safety validation in dairy, beverage, and packaged goods production requires rapid-turnaround disposable testing.
Industrial processes capture value concentration; water quality monitoring scales through regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites Europe's bioprocessing supply chain density, while China's Yangtze River Delta manufacturing corridor anchors Asia-Pacific sensor production scale.
United States
FDA process analytical technology guidance mandates real-time pH monitoring in active GMP production lines, compelling biopharma manufacturers to validate disposable sensor accuracy. The EPA's Clean Water Act compliance programs sustain municipal utility procurement of electrode strip formats. Greater Boston's contract manufacturing cluster concentrates optical sensor adoption for perfusion cell culture applications.
Germany
EMA Annex 1 revisions on contamination control tighten GMP requirements for sterile manufacturing environments, driving single-use sensor qualification. The country's national pharmaceutical regulator enforces extended biocompatibility testing timelines for sensors contacting cell culture media. Bavaria's precision instrument corridor hosts specialized fluorescent dye synthesis suppliers serving bioreactor applications.
China
NMPA good manufacturing practice standards for single-use bioprocessing systems reshape supplier qualification timelines for domestic contract manufacturers. The Ministry of Ecology and Environment's water quality monitoring mandates expand electrode strip deployment in municipal utilities. Shanghai's biopharma manufacturing base scales disposable sensor procurement for multi-thousand-liter single-use bioreactor installations.
Switzerland
Swissmedic guidance on process analytical technology shapes product standards for sterile processing applications. The country's national pharmaceutical regulator emphasizes closed-system processing documentation for fill-finish operations. Basel's life sciences cluster concentrates demand for PreSens-style optical sensor spots in microfluidic and small-volume applications.
India
CDSCO manufacturing practice requirements for biologics production drive validation protocols for disposable monitoring systems. The Central Pollution Control Board's industrial discharge monitoring sustains field-deployable pH sensor demand. Maharashtra's contract research organization corridor concentrates direct-to-laboratory distribution channels bypassing traditional markup structures.
Disposable Ph Sensors Market Competitive Landscape
On the supply side, the industry is consolidating around instrumentation conglomerates with chromatography and mass spectrometry footprints, while specialized optical sensing firms occupy defensible niches in microfluidic applications. Strategic archetypes include analytical instrumentation bundlers, single-use bioreactor integrators, and precision optical specialists. Dominant competitive moves encompass direct-to-laboratory distribution channel compression and bioreactor film surface integration partnerships.
Among German-based precision sensing specialists, PreSens Precision Sensing GmbH exemplifies the optical sensor spot archetype for microfluidic platforms. Thermo Fisher Scientific Inc. represents the analytical instrumentation bundler model, leveraging chromatography workflow integration. Sartorius AG anchors the single-use bioreactor integration tier, where pH monitoring functions as mandatory embedded capability.
| Leading Market Players |
|---|
| Sartorius AG |
| Hamilton Company |
| Thermo Fisher Scientific Inc. |
| Mettler-Toledo International Inc. |
| Endress+Hauser AG |
| Broadley-James Corporation |
| PendoTECH LLC |
| PreSens Precision Sensing GmbH |
| Polestar Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's chemical logistics corridor shapes cost dynamics for fluorescent dye inputs and electrochemical components, concentrating pricing power among German and Swiss specialty suppliers while downstream buyers in Bavaria and Greater Boston face tiered procurement economics based on GMP certification requirements and volume scale.
Pricing Analysis
Volume-discount tiering separates ISO 10993-certified optical sensors for bioreactor applications from standard electrochemical probes for environmental field testing. Price differentiation rests on biocompatibility certification grade and single-source dye chemistry availability. Cost compression in electrode strip formats is intensifying because municipal utilities in Southeast Asia consolidate procurement through competitive tendering. Environmental monitoring agencies exhibit highest price sensitivity; biopharma quality-control labs demonstrate lowest sensitivity due to GMP validation lock-in.
Supply Chain Analysis
Contract manufacturing concentration among German precision instrument clusters and Swiss specialty chemical suppliers anchors capacity for optical sensor spot production. Upstream synthesis of fluorescent indicator dyes draws from Bavarian and Basel-based chemical operations, while electrochemical probe assembly sources Ag/AgCl reference systems and platinum electrodes from German metallurgical suppliers. Single-source vulnerability in specialized dye synthesis creates structural risk. Distribution runs through direct-to-laboratory channels that bypass traditional distributor markups for CRO and biopharma quality-control procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable sensor refurbishment services pose a substitution threat that single-use incumbents must neutralize through embedded integration and validation documentation depth.
For Market Incumbents: Insulate installed base position by deepening bioreactor film surface integration partnerships and accelerating ISO 10993 documentation packages ahead of EMA Annex 1 enforcement. Prioritize captive supply of fluorescent indicator chemistry through backward integration into German specialty dye synthesis or exclusive offtake agreements with Bavarian chemical suppliers.
For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian municipal water quality monitoring through electrode strip formats optimized for tropical field conditions and competitive tender pricing. Target India's Maharashtra CRO corridor with direct sales engineering teams that bypass established distribution layers. Lead with portable electrochemical units for agricultural irrigation testing where GMP validation requirements are absent.
For Investors and Strategic Acquirers: Carve-out targets emerge from analytical instrumentation conglomerates seeking to divest non-core sensor divisions amid chromatography workflow consolidation. Long-term viability hinges on optical chemistry IP depth and bioreactor platform integration density. Monitor NMPA qualification timeline acceleration for domestic Chinese contract manufacturers as inflection signal for regional procurement scale shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Film Integration Partnership | Embedding pH sensor chemistry directly into single-use bag surfaces eliminates probe port validation for Sartorius and Thermo Fisher workflows. |
| Fluorescent Dye Synthesis Backward Integration | Captive supply of indicator chemistry from Bavarian or Basel operations reduces single-source vulnerability for PreSens-style optical platforms. |
| Direct-to-Laboratory Channel Buildout | Dedicated sales engineering teams for US and German CROs displace distributor markups and capture quality-control lab procurement. |
| ISO 10993 Documentation Acceleration | Pre-validated biocompatibility packages compress 12-18 month qualification timelines ahead of EMA Annex 1 enforcement. |
| Microfluidic Sensor Spot Miniaturization | Sub-milliliter volume optical sensing opens lab-on-chip applications in Swiss precision instrument clusters. |
Research Methodology
Desk research of FDA 483 inspection observations, EMA guidance documents, and ISO 10993 biocompatibility testing protocols preceded structured interviews with biopharma process development directors, single-use bioreactor procurement managers, and regulatory affairs specialists. Secondary validation drew from US EPA Clean Water Act compliance filings, NMPA good manufacturing practice standards, and customs trade data for electrochemical component imports. Bottom-up sensor unit demand modeling triangulated against top-down bioprocessing capacity expansion announcements across the analysis window.
Assumption sets held FDA process analytical technology guidance and EMA Annex 1 contamination control revisions as fixed regulatory drivers while varying CMO concentration rates across German, US, and Chinese manufacturing corridors. Segmentation dimensions spanned product type, technology platform, end-user vertical, and application area with regional regulatory cluster overlays. CAGRs were derived from installed base replacement cycles and new bioreactor deployment pipelines. Forecast inputs incorporated platinum electrode commodity price trajectories and fluorescent dye synthesis capacity utilization rates.
Stress conditions across precious metal cost volatility, biocompatibility testing timeline extensions, and single-source dye supplier disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that pharmacopeial standard revisions or NMPA qualification acceleration could materially revise trajectory. Quarterly review of CMO procurement contract announcements and specialty chemical supplier capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market