
 Asia Pacific Lidar Market | 2026-2036
Asia Pacific Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Lidar Market Analysis
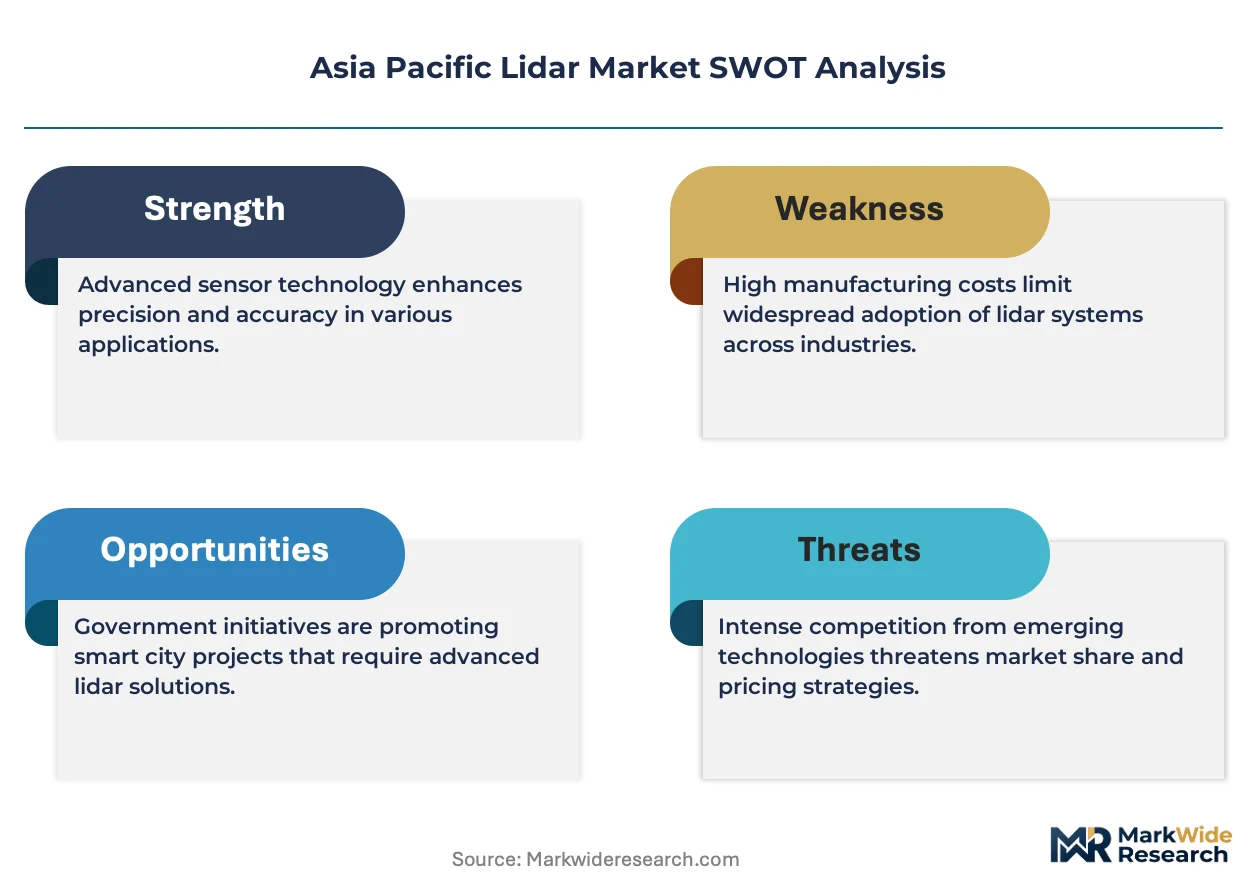
The capability gap between capital-heavy solid-state developers and mechanical legacy suppliers is redrawing competitive boundaries across the Asia Pacific Lidar Market. Hesai Group leverages integrated chip-scale manufacturing to dominate high-volume automotive contracts. RoboSense Technology Co., Ltd. anchors its position through dense OEM partnerships with domestic Chinese EV brands. Luminar Technologies Inc. sustains premium positioning via long-range detection architectures for highway autonomy.
Lidar systems emit pulsed or continuous-wave laser light to generate dense three-dimensional point clouds, with solid-state variants eliminating mechanical rotation through optical phased arrays or MEMS mirrors for improved shock resistance and cycle life. The technology serves autonomous navigation, precision agriculture, and geological survey applications by measuring time-of-flight or frequency shifts in returned photons. Solid-state lidar captures the fastest expansion trajectory as automakers demand automotive-grade reliability at sub-thousand-dollar unit economics. Frequency Modulated Continuous Wave lidar concentrates margin pools in mining and aerospace end users requiring velocity measurement alongside spatial mapping. Mechanical lidar retains installed-base dominance in infrastructure development where retrofit cycles extend across decades.
MIIT mandates on intelligent connected vehicles and China's GB standards for automotive sensor performance are accelerating homologation timelines for domestic suppliers. Japan's METI roadmap for autonomous mobility and South Korea's MFDS certification requirements for aerial survey equipment are fragmenting compliance architectures across the region. Stakeholders must monitor divergence between Chinese national standards and Japanese JIS frameworks when designing pan-Asian product platforms.
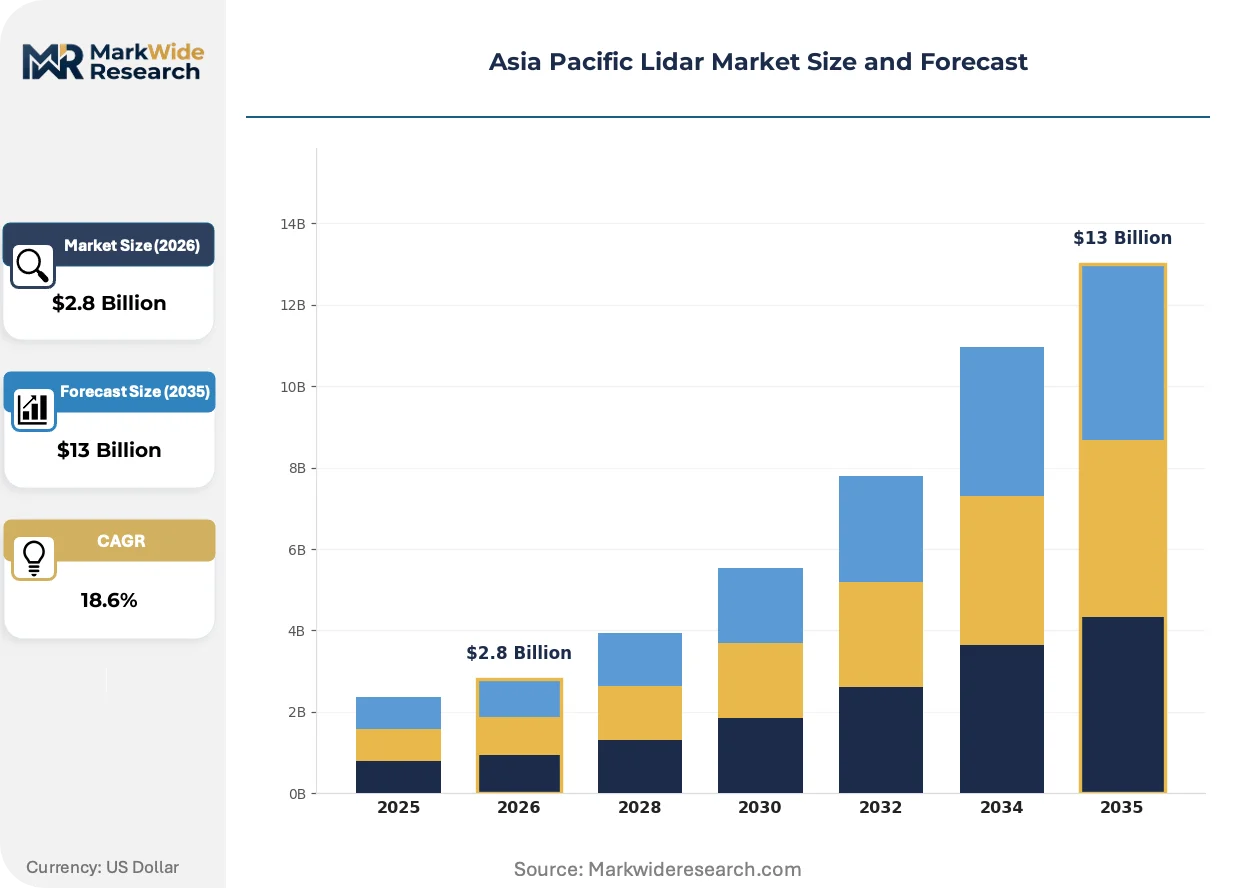
Market Dynamics
China's MIIT mandates on intelligent connected vehicles are compressing homologation timelines for lidar suppliers, forcing simultaneous investment in solid-state manufacturing scale and GB standards compliance across the Yangtze River Delta corridor.
Growth Catalysts
- Dual Carbon Goals:China's emission reduction frameworks mandate precision mapping for renewable infrastructure siting, pulling frequency-modulated continuous wave lidar into utility-scale solar and wind development.
- Vehicle Intelligence Mandates:MIIT regulations require Level 2+ autonomous systems on new passenger vehicles, creating installed-base demand for automotive-grade solid-state sensors.
- Precision Agriculture:Japan's METI agricultural modernization incentives fund laser-based crop monitoring across Hokkaido and Tohoku farming cooperatives.
Market Restraints
- InGaS Wafer Supply Concentration:Epitaxial wafer fabrication for 1550nm lasers concentrates in Taiwanese and Japanese foundries, exposing automotive lidar makers to input bottlenecks.
- JIS-GB Standards Divergence:Japan's industrial standards frameworks for optical safety testing create parallel certification costs for suppliers serving both markets.
- Camera-Radar Fusion:Tesla-style vision-only autonomy architectures in budget EV segments threaten to compress lidar attach rates in entry-level vehicle classes.
Strategic Opportunities
- Indonesia Infrastructure:Nusantara capital relocation and trans-Java toll road expansion create greenfield demand for geological survey and construction monitoring lidar.
- Drone Integration:South Korea's MFDS aerial certification pathway enables packaged sensor-payload sales to agricultural UAV operators.
- Chip-Scale Manufacturing:Optical phased array integration with silicon photonics foundries promises order-of-magnitude cost reduction for MEMS mirror production.
Industry Challenges
- Optomechanical Engineering Talent:Cross-disciplinary expertise combining laser physics with automotive reliability engineering remains scarce across Shenzhen and Shanghai hiring pools.
- Homologation Timeline Compression:MIIT's accelerated approval cycles for intelligent vehicle components strain supplier validation capacity without corresponding test infrastructure expansion.
- Patent Thicket Navigation:Dense intellectual property holdings by US and Israeli pioneers complicate freedom-to-operate analysis for Chinese solid-state developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Lidar Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Lidar, Phase Lidar, Frequency Modulated Continuous Wave Lidar, Others Application: Mapping, Environmental Monitoring, Autonomous Vehicles, Infrastructure Development End User: Aerospace, Automotive, Mining, Agriculture Technology: Solid-State Lidar, Mechanical Lidar, Hybrid Lidar, Others |
| Companies Covered | RoboSense Technology Co., Ltd., Hesai Group, Velodyne Lidar Inc., Quanergy Systems Inc., Ouster Inc., Innoviz Technologies Ltd., Luminar Technologies Inc., Trimble Inc., SICK AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Lidar Market Emerging Trajectories
Solid-state architectures are actively compressing the cost-performance frontier across automotive and industrial lidar deployments, while regulatory fragmentation between Chinese and Japanese frameworks forces parallel product development tracks.
Optical phased array technology steers laser emission through silicon waveguide interference patterns rather than mechanical rotation. Tier 1 automotive suppliers are adopting these architectures for 2027 model year highway autonomy programs. This transition is supplanting MEMS mirror designs in long-range detection applications above 200 meters.
China's GB/T standards for automotive lidar performance and safety testing entered force under MIIT supervision in 2023, establishing domestic certification requirements distinct from ISO 26262 functional safety frameworks. Suppliers must maintain parallel test protocols for vehicles exported to European versus Chinese assembly plants. Solid-state units with integrated ASIL-D rated processors capture preferential listing on MIIT-approved component registries.
Fleet operators in autonomous taxi and logistics segments are consolidating sensor procurement under multi-year supply agreements with direct manufacturer relationships, bypassing traditional tiered automotive distribution. Chinese robotaxi deployers in Beijing and Shanghai negotiate volume commitments spanning 50,000-unit annual offtake. This concentration shifts pricing power toward buyers with certified in-house integration capabilities.
Asia Pacific Lidar Market Segmentation
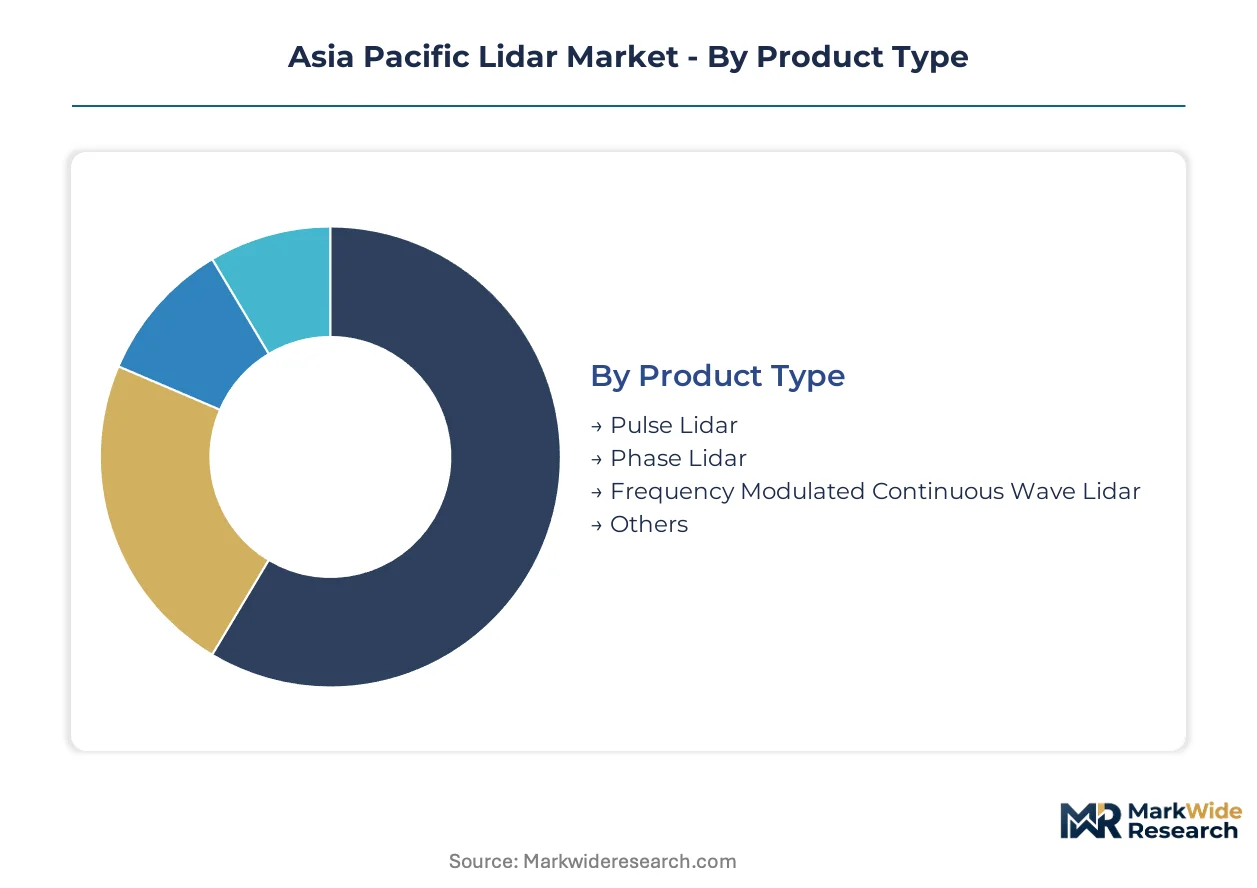
Lidar segmentation across Asia Pacific reflects divergent regulatory frameworks and application maturity. MIIT vehicle mandates, METI agricultural incentives, and MFDS aerial certifications each pull distinct technology configurations into commercial deployment.
Product Type:
MIIT's GB standards for automotive sensor performance create divergent certification pathways across laser modulation architectures, with 1550nm wavelength requirements favoring specific product categories in Chinese passenger vehicle programs.
- Pulse Lidar:Emits discrete laser pulses measuring time-of-flight to target surfaces. Automotive OEMs in China's Yangtze River Delta specify pulse architectures for Level 2+ highway autonomy due to proven ASIL-D functional safety integration. MIIT homologation timelines compress validation cycles for established pulse suppliers.
- Frequency Modulated Continuous Wave Lidar:Continuous wave emission with frequency modulation enables simultaneous distance and velocity measurement through Doppler shift detection. Mining operators in Australia's Pilbara region and renewable infrastructure developers across China's western provinces specify FMCW for precision terrain mapping under dual carbon siting mandates.
- Phase Lidar:Interferometric phase comparison delivers sub-millimeter precision for industrial metrology applications. Japanese precision manufacturing clusters in Aichi Prefecture deploy phase systems for quality control.
- Others:Doppler and polarimetric variants serve specialized atmospheric research and defense applications across South Korean and Australian government laboratories.
Established volume favors pulse architectures; emerging adoption favors frequency modulated continuous wave systems.
Application:
Application demand concentrates where government procurement and private fleet investment intersect, with autonomous vehicle deployment creating the steepest volume ramp.
- Autonomous Vehicles:Robotaxi fleets in Beijing and Shanghai negotiate 50,000-unit annual sensor commitments directly with lidar manufacturers. MIIT mandates on intelligent connected vehicles mandate Level 2+ systems on new passenger vehicles, pulling solid-state units through certified component registries.
- Mapping:Geological survey applications across Indonesia's Nusantara capital relocation and trans-Java toll expansion specify long-range mechanical units. Survey contractors face compressed project timelines from infrastructure stimulus programs.
- Environmental Monitoring:Precision agriculture deployment across Japan's Hokkaido farming cooperatives leverages METI modernization incentives for crop health monitoring.
- Infrastructure Development:Construction monitoring and tunnel surveying across India's Delhi-Mumbai Industrial Corridor utilize terrestrial laser scanning for progress verification.
Fleet procurement concentrates in autonomous vehicles; public infrastructure sustains mapping demand.
End User:
End user margins vary sharply with integration complexity, with automotive commanding volume but aerospace retaining premium pricing.
- Automotive:Domestic Chinese EV brands anchor sensor procurement through dense OEM partnerships. Solid-state unit economics target sub-thousand-dollar price points for mass vehicle deployment.
- Mining:Australian and Indonesian open-pit operators specify ruggedized mechanical units with 300-meter range for haul truck automation. Dust penetration and vibration tolerance drive specification.
- Aerospace:South Korean UAV manufacturers pursue MFDS aerial certification for packaged sensor-payload integration. Agricultural drone operators represent the fastest-climbing demand segment within aerospace.
- Agriculture:Japanese farming cooperatives fund laser-based crop monitoring through METI subsidy programs, with variable-rate application driving return on investment.
Automotive commands unit volume; aerospace retains margin premium.
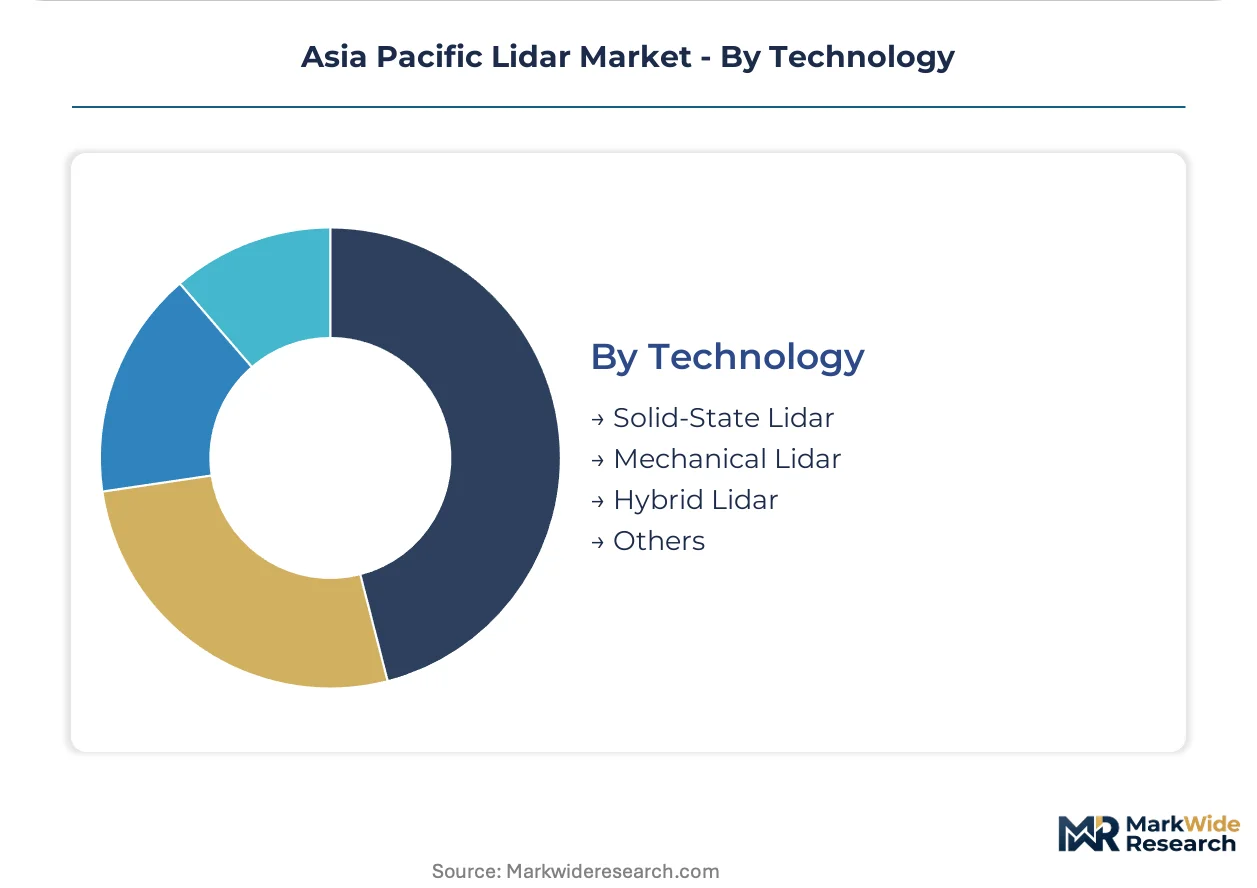
Technology:
Technology selection tracks reliability requirements and cost compression trajectories, with solid-state architectures displacing mechanical rotation in shock-sensitive applications.
- Solid-State Lidar:Optical phased arrays and MEMS mirrors eliminate mechanical rotation for improved shock resistance. Tier 1 automotive suppliers adopt these architectures for highway autonomy programs above 200-meter detection range.
- Mechanical Lidar:Rotating sensor heads retain installed-base dominance in infrastructure development where retrofit cycles extend across decades. Survey and construction applications tolerate maintenance intervals.
- Hybrid Lidar:Combines solid-state emitters with limited mechanical scanning for mid-range automotive applications. Chinese suppliers optimize hybrid configurations for cost-performance balance in domestic EV platforms.
- Others:Flash lidar and emerging optical coherence tomography variants serve niche medical and industrial inspection markets.
Mechanical systems defend installed base; solid-state architectures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Japan demonstrate the lowest price elasticity as MIIT mandates and METI subsidies absorb premium sensor costs, while Indonesian and Indian infrastructure contractors exhibit acute cost sensitivity that favors mechanical legacy systems.
China
Robotaxi fleets in Beijing and Shanghai negotiate 50,000-unit annual sensor commitments directly with lidar manufacturers. MIIT regulations on intelligent connected vehicles mandate Level 2+ autonomous systems on new passenger vehicles. The Yangtze River Delta manufacturing corridor concentrates solid-state production capacity as Hesai Group and RoboSense anchor chip-scale fabrication facilities.
Japan
Precision agriculture deployment across Hokkaido farming cooperatives leverages METI modernization incentives for laser-based crop monitoring. METI's roadmap for autonomous mobility establishes JIS certification pathways distinct from Chinese GB standards. Aichi Prefecture's precision manufacturing clusters deploy phase lidar systems for sub-millimeter industrial metrology applications.
South Korea
Agricultural UAV operators represent the fastest-climbing demand segment within aerospace end uses. MFDS certification requirements for aerial survey equipment establish compliance frameworks for packaged sensor-payload integration. Seoul Capital Area manufacturers pursue silicon photonics foundry partnerships for optical phased array production.
Australia
Mining operators in the Pilbara region specify ruggedized mechanical units with 300-meter range for haul truck automation. Dust penetration and vibration tolerance drive specification requirements in open-pit extraction environments. Western Australian logistics corridors test autonomous haulage systems with frequency modulated continuous wave lidar for precision terrain mapping.
Indonesia
Nusantara capital relocation and trans-Java toll road expansion create greenfield demand for geological survey and construction monitoring lidar. Infrastructure stimulus programs compress project timelines for survey contractors. Jakarta-based engineering firms source long-range mechanical units for tunnel surveying and progress verification applications.
Asia Pacific Lidar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific Lidar Market. The vendor base structures around three tiers: capital-intensive solid-state developers with integrated chip-scale manufacturing, mechanical legacy suppliers defending installed-base positions in infrastructure applications, and hybrid specialists optimizing cost-performance balance for domestic EV platforms. Dominant competitive moves include capacity expansion in Yangtze River Delta fabrication corridors and strategic partnerships bypassing traditional tiered automotive distribution.
Among China-based developers, Hesai Group and RoboSense Technology Co., Ltd. exemplify the integrated manufacturing archetype, while Luminar Technologies Inc. occupies a position representing premium long-range detection specialization for highway autonomy programs.
| Leading Market Players |
|---|
| RoboSense Technology Co., Ltd. |
| Hesai Group |
| Velodyne Lidar Inc. |
| Quanergy Systems Inc. |
| Ouster Inc. |
| Innoviz Technologies Ltd. |
| Luminar Technologies Inc. |
| Trimble Inc. |
| SICK AG |
| Others |
Supply Flow & Price Mechanics
Multi-year direct procurement contracts between Chinese robotaxi operators and lidar manufacturers lock in both InGaS wafer supply access and unit price visibility across volatile input markets. These arrangements concentrate pricing power with fleet buyers possessing certified in-house integration capabilities while compressing margins for component suppliers locked into volume commitments.
Pricing Analysis
After-sales calibration and field service contracts now drive lifetime value beyond initial hardware sales, with automotive OEMs bundling multi-year maintenance into per-vehicle sensor packages. Pricing stratifies across ASIL-D certified premium tiers, standard automotive-grade configurations, and economy hybrid units for domestic EV platforms. Cost compression in solid-state MEMS production is intensifying because silicon photonics foundries are achieving scale economies in Yangtze River Delta corridors. Mining operators in Australia exhibit the lowest price sensitivity due to operational downtime costs, while Indonesian infrastructure contractors demand mechanical legacy systems at aggressive unit economics.
Supply Chain Analysis
Taiwan and Japan anchor epitaxial wafer fabrication for 1550nm lasers, while China concentrates optical phased array assembly and MEMS mirror production. Automotive lidar production draws from InGaS substrates, silicon photonics wafers, and precision optomechanical housings. Single-source vulnerability concentrates in Taiwanese foundries supplying high-purity epitaxial material. Distribution runs through direct manufacturer relationships with fleet operators, bypassing traditional tiered automotive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined lidar calibration and over-the-air performance optimization represent a service-attach layer expanding faster than hardware shipments as fleets demand predictive maintenance and dynamic range adjustment.
For Market Incumbents: Shield core automotive contracts through captive control over silicon photonics foundry capacity in the Yangtze River Delta corridor. Camera-radar fusion architectures in budget EV segments threaten to erode attach rates; counter by accelerating ASIL-D certification investment to maintain preferential MIIT registry listing. For New Entrants and Emerging Players: Aftermarket retrofit services for existing mechanical lidar installations present a service-layer gap where incumbents under-serve infrastructure contractors with decade-old sensor fleets. Indonesia's Nusantara capital relocation and trans-Java toll expansion offer the most penetrable geography for geological survey equipment. Pursue packaged sensor-payload integration partnerships with South Korean UAV manufacturers seeking MFDS aerial certification. For Investors and Strategic Acquirers: Solid-state developers with integrated chip-scale manufacturing capabilities but incomplete automotive certification represent the named acquisition target archetype directly. Long-term viability hinges on navigating patent thickets held by US and Israeli pioneers while securing freedom-to-operate for optical phased array architectures. Monitor divergence between Chinese GB standards and Japanese JIS frameworks as the inflection indicator for pan-Asian platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Enables order-of-magnitude cost reduction for MEMS mirror production in Yangtze River Delta corridors. |
| ASIL-D Functional Safety Certification | Secures preferential listing on MIIT-approved component registries for Level 2+ vehicle mandates. |
| Direct Fleet Procurement Agreement | Bypasses tiered automotive distribution to capture 50,000-unit annual commitments from Beijing robotaxi deployers. |
| Dual Standards Compliance Investment | Addresses JIS-GB divergence to serve both Japanese METI and Chinese MIIT regulatory pathways. |
| Agricultural UAV Payload Integration | Leverages South Korea MFDS certification for packaged sensor sales to Hokkaido farming cooperatives. |
Methodological Framework
A spread of perspectives from lidar platform engineers, Tier 1 automotive procurement directors, MIIT certification specialists, and mining fleet maintenance managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from sensor manufacturers, MIIT GB standards documentation, and vehicle production databases tracking Level 2+ system penetration. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segmentation dimensions modeled include laser modulation architecture, application vertical, end-user industry, and technology type across the analysis window. CAGRs derived from fitted growth curves applied to validated baseline volumes, with trajectory adjustments for MIIT mandate implementation timing and solid-state manufacturing scale milestones. Industry-specific forecast inputs incorporated InGaS wafer supply constraints and optical phased array yield improvement curves.
Underlying assumptions cover sustained MIIT enforcement of Level 2+ mandates, continued InGaS wafer supply from Taiwanese foundries, and stable dual carbon policy commitment in China, with deviation risk concentrated in JIS-GB standards divergence and camera-radar fusion adoption in budget EV segments. Recalibration cycles align with material shifts in MIIT homologation timelines and silicon photonics foundry capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Barometer Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Air Flow Monitoring System Market