
 Motion Sensor Market | 2026-2036
Motion Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Sensor Market Intelligence
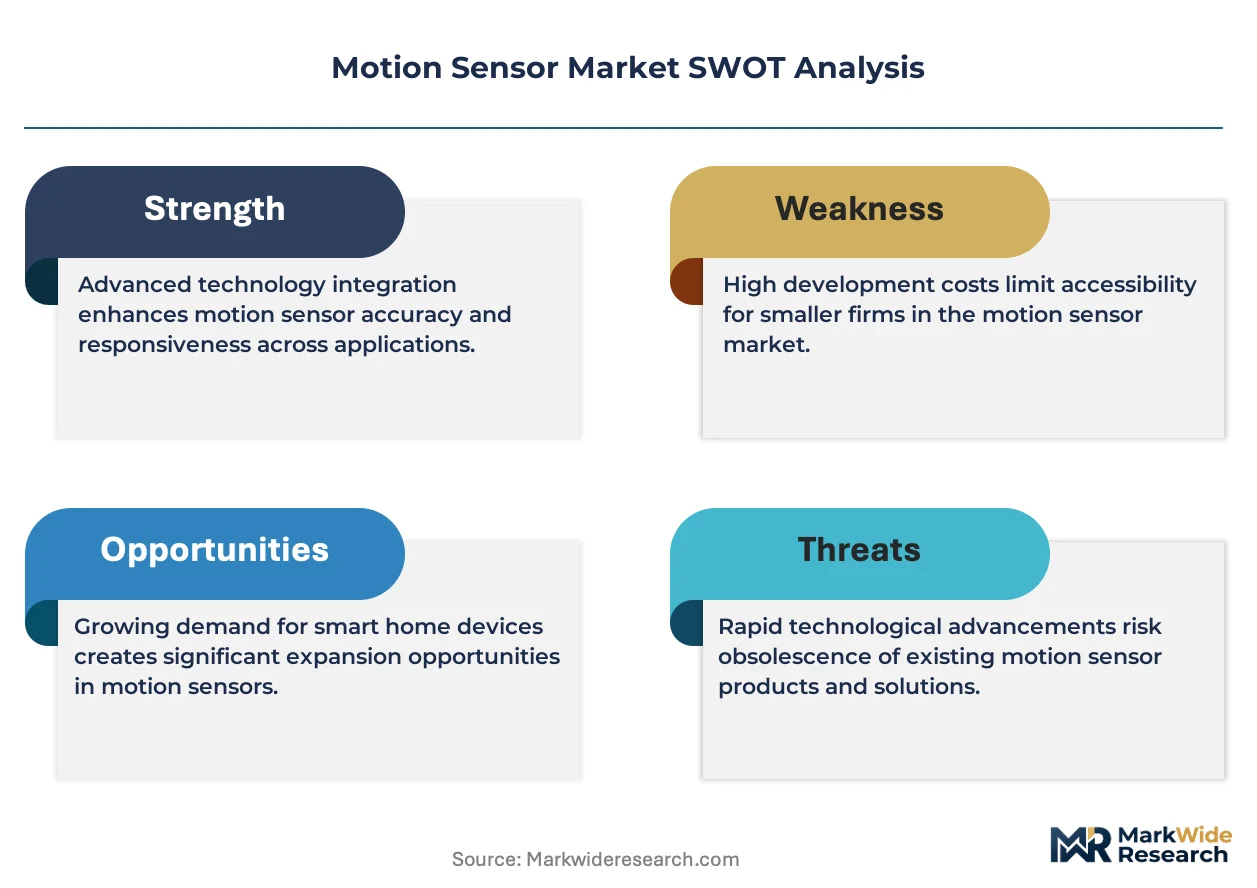
Software-defined sensitivity and feature-set subscriptions are expanding the value proposition beyond hardware sales. This shift allows customers to upgrade sensor performance through firmware updates rather than physical replacement. STMicroelectronics leverages its broad semiconductor portfolio to integrate advanced sensor fusion capabilities. Robert Bosch GmbH differentiates through its deep expertise in automotive and industrial applications, anchoring its position in high-reliability segments.
A motion sensor is an electronic device utilizing technologies like passive infrared (PIR) or micro-electro-mechanical systems (MEMS) to detect physical movement in a defined area. Its primary function is to trigger an automated response, such as activating an alarm, controlling lighting, or providing input for an automated system. While passive infrared sensors command the largest volume in security systems, ultrasonic sensors are gaining share in complex industrial automation tasks. The automotive and smart home applications represent the fastest-growing end-use categories, driven by convenience and safety features.
Product compliance is governed by a patchwork of regional electronics standards, including the FCC Part 15 rules in the United States and CE marking requirements in Europe. In China, adherence to GB standards for electronic interference and safety is mandatory for market access, influencing component design choices. Suppliers must navigate these divergent regulatory landscapes while deciding where to invest in next-generation sensor fusion and low-power wireless technologies.
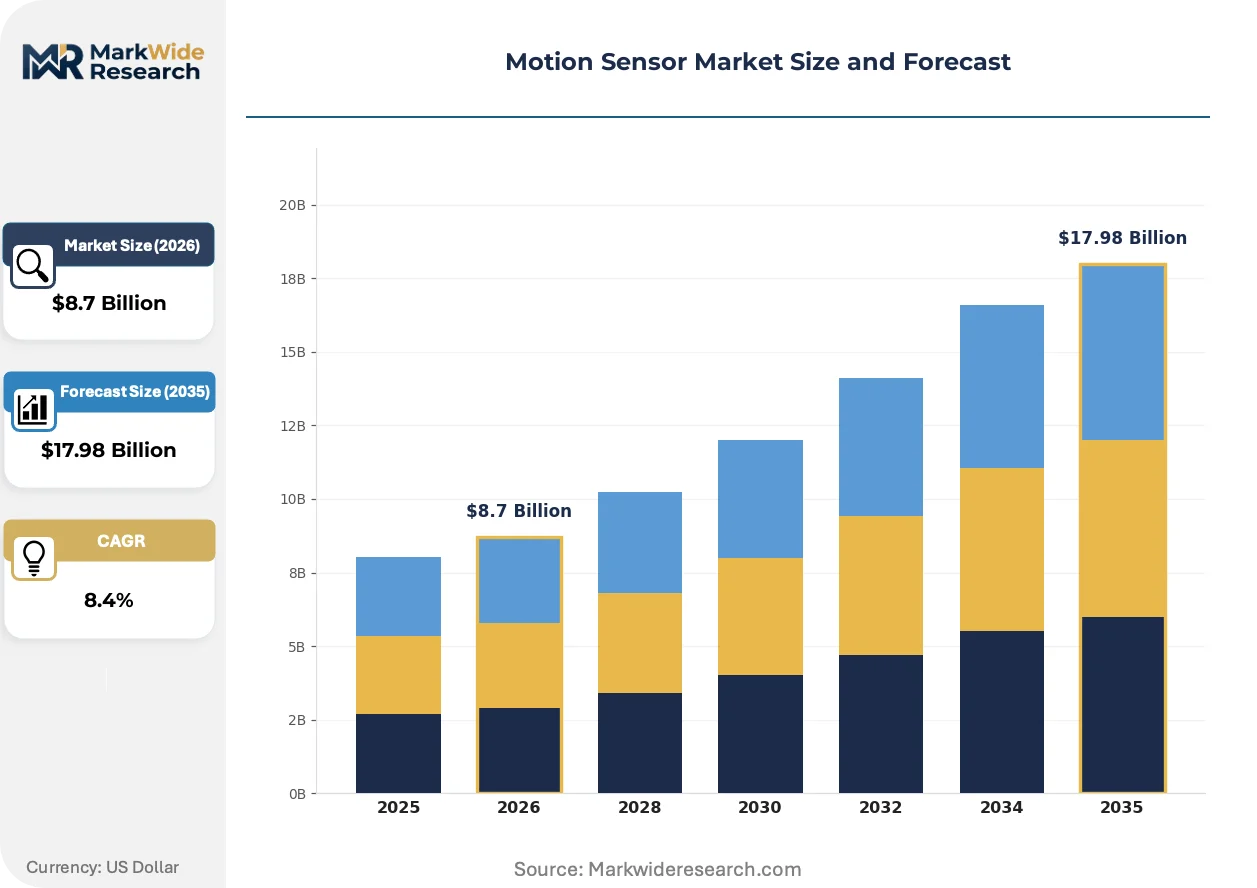
Market Dynamics
The convergence of low-power wireless communication and on-device sensor fusion algorithms is the central force shaping the market. This combination enables more sophisticated, context-aware applications beyond simple presence detection, driving value in industrial predictive maintenance and smart building automation.
Growth Catalysts
- Industrial Automation Demand:China's advanced manufacturing clusters require high-precision MEMS sensors for machinery monitoring and robotic guidance systems, pulling significant volume into the industrial segment.
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) necessitates energy efficiency tracking, creating a compliance-driven demand for occupancy sensors in commercial buildings to manage lighting and HVAC usage.
- Technology Miniaturization:Continuous advances in MEMS fabrication allow for smaller, more power-efficient sensors, enabling their integration into a wider range of consumer electronics and smart home devices.
Market Restraints
- Technical Limitations:Passive infrared (PIR) sensors, while cost-effective, remain susceptible to false alarms from ambient temperature changes, limiting their reliability in high-security or mission-critical applications without complementary technologies.
- Supply Chain Concentration:The fabrication of high-performance MEMS gyroscopes and accelerometers depends on a concentrated number of specialized foundries, exposing the supply chain to potential disruptions and price volatility.
- Regulatory Fragmentation:Navigating divergent requirements, such as FCC Part 15 rules in the United States and China's mandatory GB standards for interference, adds significant cost and complexity to global product development.
Strategic Opportunities
- Emerging Applications:Sensor fusion combining motion, vibration, and acoustic data creates opportunities in predictive maintenance for industrial machinery, identifying potential failures before they occur.
- Technology Convergence:Integrating motion sensors with low-power wide-area networks (LPWAN) enables large-scale deployments for smart agriculture, such as livestock tracking and monitoring irrigation equipment.
- Service Model Innovation:The shift towards software-defined sensors allows for recurring revenue through firmware updates and feature-set subscriptions, moving beyond a purely hardware-based sales model.
Industry Challenges
- Legacy System Integration:Connecting modern, IP-based motion sensors with older, analog-based building automation and security systems often requires costly custom gateways and significant integration effort.
- Algorithm Development Talent:A scarcity of engineers with dual expertise in both MEMS sensor physics and the machine learning algorithms required for advanced sensor fusion inhibits rapid innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Sensor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PIR Sensors, Ultrasonic Sensors, Microwave Sensors, Tomographic Sensors Technology: Analog, Digital, Hybrid, Wireless Application: Security Systems, Automotive, Smart Homes, Industrial Automation End User: Residential, Commercial, Healthcare, Retail |
| Companies Covered | STMicroelectronics, Murata Manufacturing Co., Ltd., Robert Bosch GmbH, Analog Devices, Inc., NXP Semiconductors, Honeywell International Inc., TE Connectivity, TDK Corporation, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental pivot from selling discrete hardware components to providing adaptable, software-defined sensing platforms. This transition expands the total addressable value by enabling post-deployment upgrades and creating recurring revenue streams for manufacturers.
Sensor fusion algorithms, often running on edge microcontrollers, combine inputs from multiple sensing technologies like PIR and ultrasonic. This approach is adopted by industrial IoT and smart home system developers seeking higher accuracy and context awareness. This software-centric methodology is overtaking the traditional reliance on single-technology, fixed-function hardware components for complex detection tasks.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy driver. This regulation compels large organizations to disclose detailed energy consumption metrics, which in turn creates a strong incentive for deploying networked occupancy sensors. The commercial real estate and facilities management sectors are most affected, accelerating retrofits of lighting and HVAC controls to meet these new reporting obligations.
A clear behavioral shift from one-time hardware procurement to subscription-based access for sensor features is underway. This model disrupts traditional component distribution by creating a direct, continuous relationship between the sensor manufacturer and the system integrator. This trend is most prominent within Germany's industrial automation sector and the high-end smart home security market in the United States.
Motion Sensor Market Segmentation
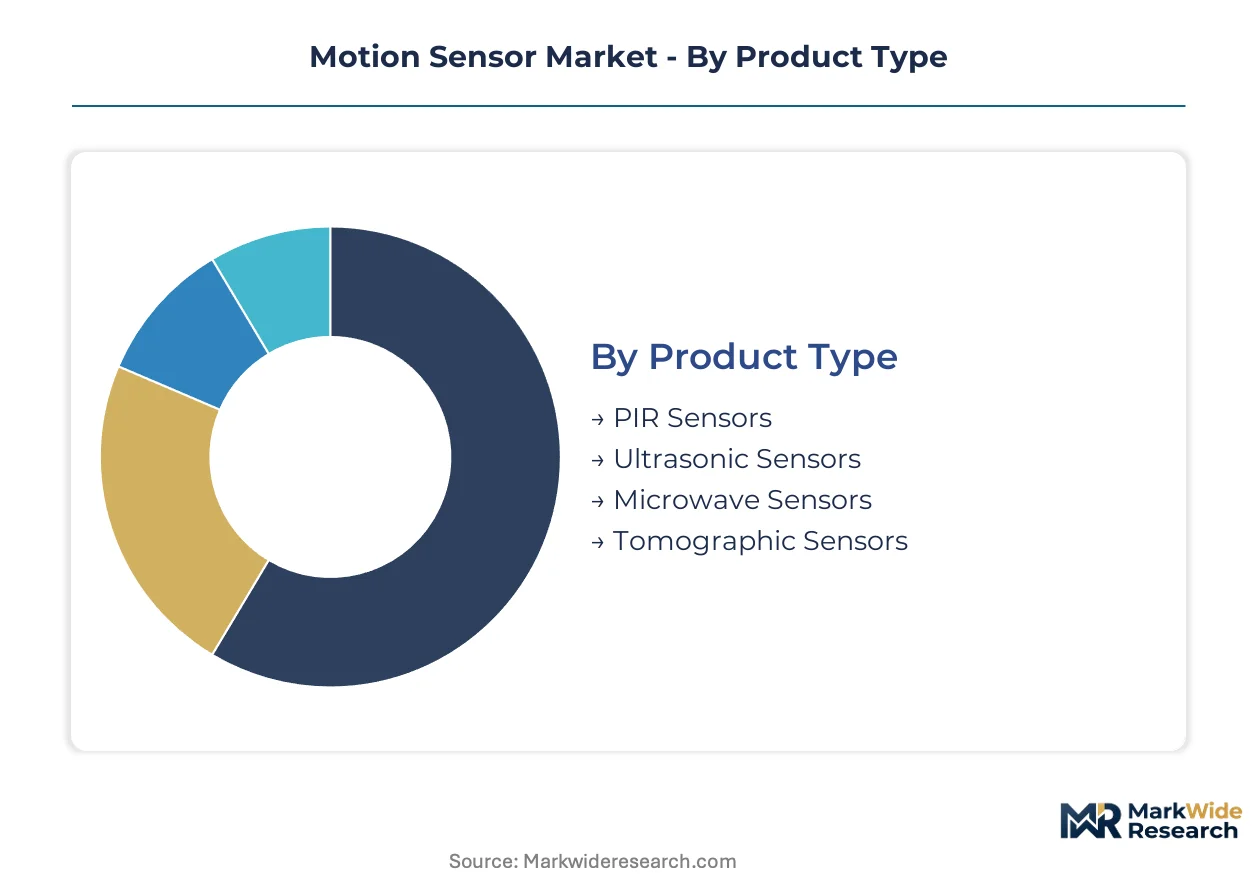
The motion sensor market segments across various dimensions, reflecting distinct technological approaches, application requirements, and end-user needs. Understanding these divisions is crucial for manufacturers to target product development and for integrators to select appropriate solutions for specific deployment scenarios.
Product Type:
Segmentation by product type reveals a spectrum of sensor technologies, from standalone discrete units to those integrated deeply into larger systems.
- PIR Sensors:Passive Infrared (PIR) Sensors detect motion by sensing changes in infrared radiation emitted by objects. Their low cost and reliability make them fundamental to security systems in the United States and Europe for basic presence detection.
- Ultrasonic Sensors:Ultrasonic Sensors emit high-frequency sound waves and measure the reflection time to detect objects and their movement. Industrial automation in Germany increasingly utilizes these for precise object positioning and collision avoidance.
- Microwave Sensors:These sensors emit microwave radiation and detect changes in the reflected signal caused by moving objects. They offer broader coverage and can penetrate non-metallic materials.
- Tomographic Sensors:Tomographic sensors create a mesh network of radio waves, detecting disturbances in the field caused by movement. They provide wide-area coverage and are less susceptible to line-of-sight obstructions.
PIR Sensors leads volumes today; Ultrasonic Sensors is gaining share fastest.
Technology:
Technology segmentation highlights the varying cost structures and processing capabilities embedded within motion sensor devices.
- Digital:Digital sensors convert analog signals into digital data directly within the sensor, enabling on-device processing and reduced noise. Smart home systems in China leverage digital technology for enhanced security and automation features.
- Wireless:Wireless sensors integrate communication modules like Bluetooth or Zigbee, removing the need for physical cabling. Industrial predictive maintenance in Canada increasingly adopts wireless sensors for remote monitoring of machinery.
- Analog:Analog sensors produce a continuous electrical signal proportional to the detected motion. These are typically simpler and less expensive, often requiring external processing.
- Hybrid:Hybrid sensors combine multiple sensing principles or integrate both analog and digital components. They offer enhanced accuracy or specialized functionality for complex detection tasks.
Digital technologies currently dominate new deployments; wireless connectivity is expanding most quickly across diverse applications.
Application:
Application segmentation illustrates the varied volume demands and performance requirements across different end-use environments.
- Security Systems:Security Systems utilize motion sensors for intrusion detection, triggering alarms or surveillance recordings. Residential and commercial buildings worldwide rely on these for perimeter and interior protection.
- Automotive:Automotive applications use motion sensors for airbag deployment, anti-theft systems, and advanced driver-assistance systems (ADAS) like blind-spot detection. German automotive manufacturers integrate high-precision MEMS sensors for occupant sensing.
- Smart Homes:Smart Homes integrate motion sensors for automated lighting, climate control, and personalized user experiences. Consumer adoption in the US and UK drives demand for seamless integration with other smart devices.
- Industrial Automation:Industrial Automation employs motion sensors for robotic guidance, machinery monitoring, and safety interlocks on factory floors. China's advanced manufacturing clusters demand high-precision sensors for quality control.
Security Systems command the largest installed base; Smart Homes exhibit the steepest expansion trajectory.
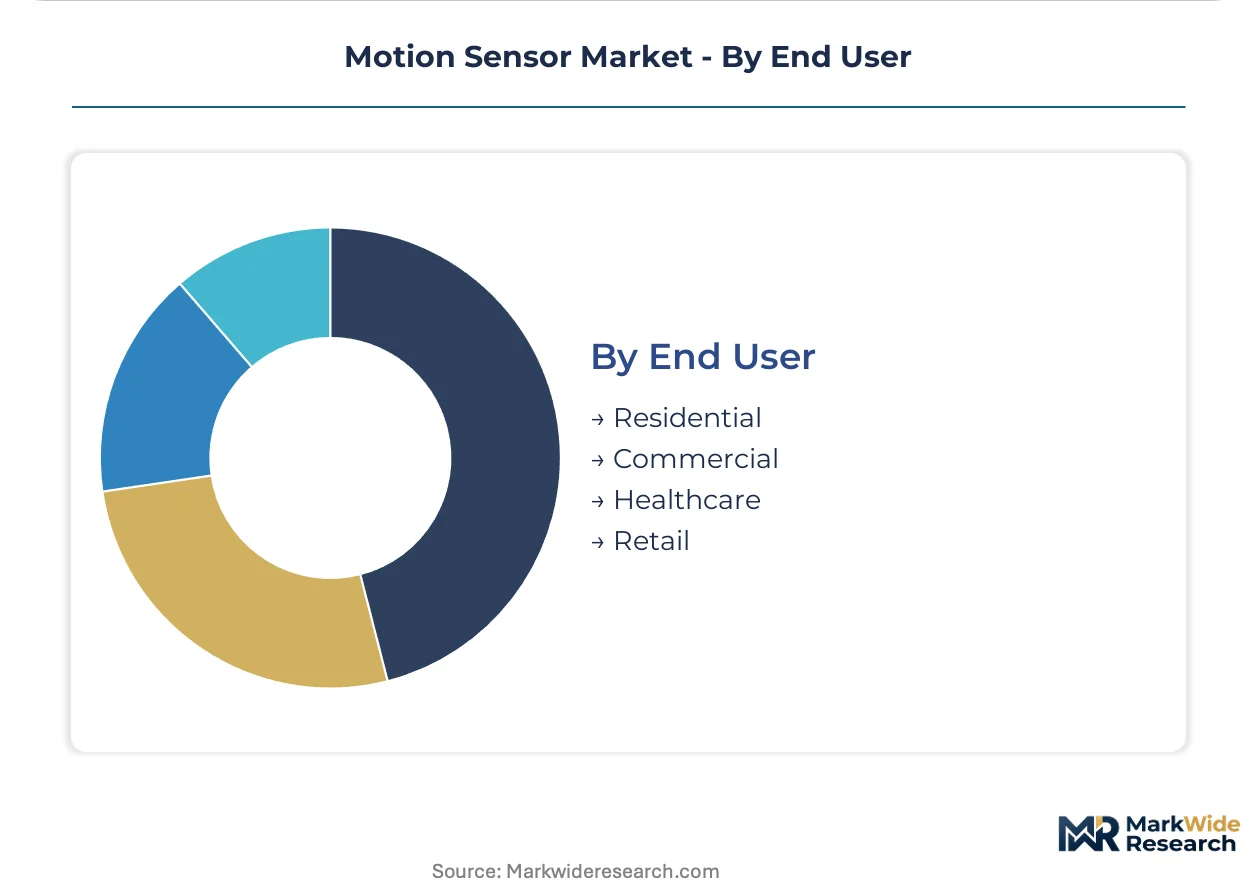
End User:
End-user segmentation differentiates motion sensor deployments based on the specific customer type and their operational needs.
- Residential:Residential users deploy motion sensors primarily for home security, energy management, and convenience features like automated lighting. The market in Japan shows strong demand for unobtrusive, aesthetically pleasing designs.
- Commercial:Commercial entities employ motion sensors for facility management, energy efficiency, and security in office buildings and retail spaces. The EU's CSRD mandates create significant demand for commercial occupancy sensors.
- Healthcare:Healthcare applications include patient monitoring, fall detection in assisted living facilities, and access control in sensitive areas. Hospitals in Australia use these for discreet patient safety.
- Retail:Retail environments use motion sensors for customer traffic counting, heat mapping, and automated lighting in store aisles. Businesses in France implement these for operational efficiency and security.
Residential deployments represent the largest segment; Healthcare applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence creates an environment where production and R&D investments shift to optimize compliance costs and market access. Motion sensor manufacturers strategically navigate varied regional standards to gain competitive advantage. This dynamic influences component design choices and market entry strategies across key geographies.
China
China's advanced manufacturing clusters drive substantial demand for high-precision MEMS sensors in robotics and quality control. Adherence to GB standards for electronic interference and safety is mandatory for market entry. Cities like Shenzhen and Shanghai anchor innovation, fostering a robust ecosystem for digital sensor development and deployment.
Germany
Germany's automotive sector and industrial automation leverage high-reliability motion sensors for advanced driver-assistance systems and machinery monitoring. The KBA oversees automotive component approvals, ensuring stringent safety and performance requirements. Bavaria and Baden-Württemberg host major automotive OEMs and industrial giants, leading sensor integration into complex systems.
United States
The United States market exhibits strong demand for motion sensors in smart home security and consumer electronics applications. FCC Part 15 rules govern radio frequency emissions, influencing wireless sensor design and certification. Silicon Valley and Texas's tech hubs concentrate R&D efforts, pushing innovation in low-power wireless and sensor fusion algorithms.
Japan
Japan's residential sector shows robust demand for unobtrusive motion sensors in home security and energy management systems. JIS standards provide a framework for product quality and interoperability, impacting local component sourcing. The Tokyo metropolitan area and Kansai region lead in smart home device integration, emphasizing aesthetic design and seamless user experience.
India
India's expanding industrial base and smart city initiatives are creating new opportunities for motion sensor adoption in automation and public safety. BIS certification ensures product quality and safety for electronic components sold domestically. Bengaluru and Pune emerge as technology centers, spearheading localized development for industrial IoT applications.
Motion Sensor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the motion sensor market structure. The ecosystem features a tiered competitive landscape, from large integrated semiconductor firms to niche component suppliers. Strategic archetypes include diversified electronics conglomerates, specialized MEMS foundries, and application-specific module providers. Dominant competitive moves involve portfolio diversification into adjacent sensing technologies and strategic partnerships for advanced sensor fusion development.
Diversified electronics conglomerates like Robert Bosch GmbH anchor the high-reliability segments, leveraging deep expertise in automotive and industrial applications. STMicroelectronics exemplifies a broad semiconductor portfolio, integrating advanced sensor fusion capabilities into its offerings for smart home and industrial IoT. Murata Manufacturing Co., Ltd. occupies a position as a specialized component supplier, focusing on high-volume, performance-critical applications within consumer electronics and industrial IoT. These firms collectively represent the strategic depth and breadth of the motion sensor market, influencing innovation cycles and market standards across various end-use sectors.
| Leading Market Players |
|---|
| STMicroelectronics |
| Murata Manufacturing Co., Ltd. |
| Robert Bosch GmbH |
| Analog Devices, Inc. |
| NXP Semiconductors |
| Honeywell International Inc. |
| TE Connectivity |
| TDK Corporation |
| Texas Instruments |
| Others |
Cost & Logistics Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates for energy efficiency tracking compel motion sensor manufacturers to provide compliant solutions, enabling value-added pricing for advanced features. This regulatory push shifts procurement preferences towards integrated, software-defined sensing platforms.
Pricing Analysis
Direct-to-OEM discounts influence pricing structures for high-volume motion sensor procurements. The market operates on a hybrid model, combining per-unit transactional costs for hardware with recurring feature-set subscriptions for software-defined functionality. Price differentiation stems from certification levels, such as CE marking compliance, and the integration of advanced sensor fusion capabilities. Pricing softness affects basic PIR sensors due to market commoditization, making the residential segment highly price-sensitive compared to industrial automation buyers.
Supply Chain Analysis
Direct-to-OEM channels handle large-volume motion sensor procurements, complemented by specialized electronics distributors for smaller system integrators. Geographic supply concentrates in China for digital sensor manufacturing and Germany for high-precision MEMS components. The supply chain depends on specialized MEMS foundries and semiconductor wafer suppliers for critical inputs. Concentration of high-performance MEMS foundries presents a single-source vulnerability, exposing the market to potential disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motion sensor market functions as a regulatory compounder, with the EU's Corporate Sustainability Reporting Directive (CSRD) notably driving demand. This directive compels organizations to adopt advanced occupancy sensors for energy efficiency tracking, creating sustained market growth.
For Market Incumbents:Deploy advanced sensor fusion R&D to differentiate offerings beyond basic hardware. Incumbents must integrate software-defined feature subscriptions, moving towards recurring revenue models. This strategy counters the commoditization threat from basic PIR sensors and secures market share against emerging software-centric competitors. Investing in direct-to-OEM channel control ensures stable volume procurement.
For New Entrants and Emerging Players:The price-point gap between high-precision industrial sensors and basic security sensors offers entry opportunities. Target smart agriculture applications by integrating motion sensors with low-power wide-area networks for livestock tracking. Focus on localized industrial IoT solutions in emerging markets like India, where demand for automation is rising. An outcome-based service model can provide a compelling go-to-market angle.
For Investors and Strategic Acquirers:Asymmetric upside sits with vertically integrated mid-cap specialists possessing strong intellectual property in sensor fusion algorithms. The market exhibits long-term viability driven by sustained demand from regulatory mandates and technology convergence. Target acquisition profiles should emphasize companies with specialized MEMS fabrication capabilities or expertise in low-power wireless integration. Monitor the increasing adoption of subscription-based sensor features as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Software-Defined Sensing Platform | This initiative enables recurring revenue streams and post-deployment feature upgrades for commercial clients. |
| Partner with AI/ML Algorithm Developers | Collaboration accelerates the integration of advanced sensor fusion capabilities for predictive maintenance applications. |
| Acquire Specialized MEMS Foundry | This move secures critical component supply and enhances control over high-precision sensor manufacturing processes. |
| Expand into China's Manufacturing Clusters | Targeting this region addresses the high demand for precision sensors in industrial automation and robotics. |
| Invest in Low-Power Wireless Module Production | This investment supports the growing market for large-scale, battery-operated sensor deployments in smart agriculture. |
Research Approach
Bottom-up end-use modeling for smart home, industrial automation, and automotive applications, reconciled against top-down semiconductor supply-side tracking, forms the analytical core. This approach combined primary interviews with R&D directors, procurement managers, and system integrators. Secondary validation drew from industry association reports, patent databases, and national electronics standards. Qualitative insights and quantitative data underwent rigorous triangulation.
An input-output matrix underpins volume and value projections across the modeling period. The framework modeled segmentation by product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected technology adoption rates. Key forecast inputs included MEMS miniaturization rates and smart building retrofit cycles.
The model assumes a particular technology adoption path; alternative pathways for sensor fusion algorithms would alter the outlook. Forecasts reflect assumptions regarding supply chain stability and regulatory consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Embedded Biometric Sensor Market