
 Smart Glove Market | 2026-2036
Smart Glove Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Glove Market Analysis
Software-defined gesture calibration and remote therapy monitoring is rebalancing how smart glove vendors monetize hardware deployments. Bioservo Technologies leverages its industrial exoskeleton heritage to anchor premium pricing in occupational settings. Neofect competes through specialized rehabilitation software that extends patient engagement beyond the clinic. Flint Rehabilitation Devices differentiates by focusing on home-based neurorehabilitation protocols that reduce provider overhead.
Smart gloves integrate flexible sensor arrays, haptic actuators, and wireless connectivity modules to capture hand kinematics and deliver tactile feedback for human-machine interaction. Fabrication employs stretchable printed electronics and silicone molding to achieve sub-millimeter bend sensing accuracy across 15-20 degrees of freedom. Rehabilitation gloves lead the product type landscape due to established clinical workflows and payer familiarity with assistive devices. Haptic gloves represent the fastest-expanding application segment as virtual reality training modules gain traction in industrial safety programs. Gesture control gloves occupy a narrower margin pool concentrated in gaming peripherals where price sensitivity limits premium positioning.
FDA 510(k) pathways govern therapeutic smart gloves marketed for neuromotor recovery in the United States, while EU MDR and CE marking impose biocompatibility and electrical safety standards for European market access. Japan's PMDA maintains distinct clinical evidence requirements that delay entry but reward validated outcomes with favorable reimbursement. Stakeholders must monitor evolving digital health taxonomy decisions by national regulators that will determine whether smart gloves classify as medical devices, wellness products, or software-as-a-service platforms.
Market Dynamics
Reimbursement pathway fragmentation is forcing smart glove vendors to architect dual-track regulatory strategies, with FDA 510(k) clearance and EU MDR certification now operating as parallel rather than sequential gates to commercialization.
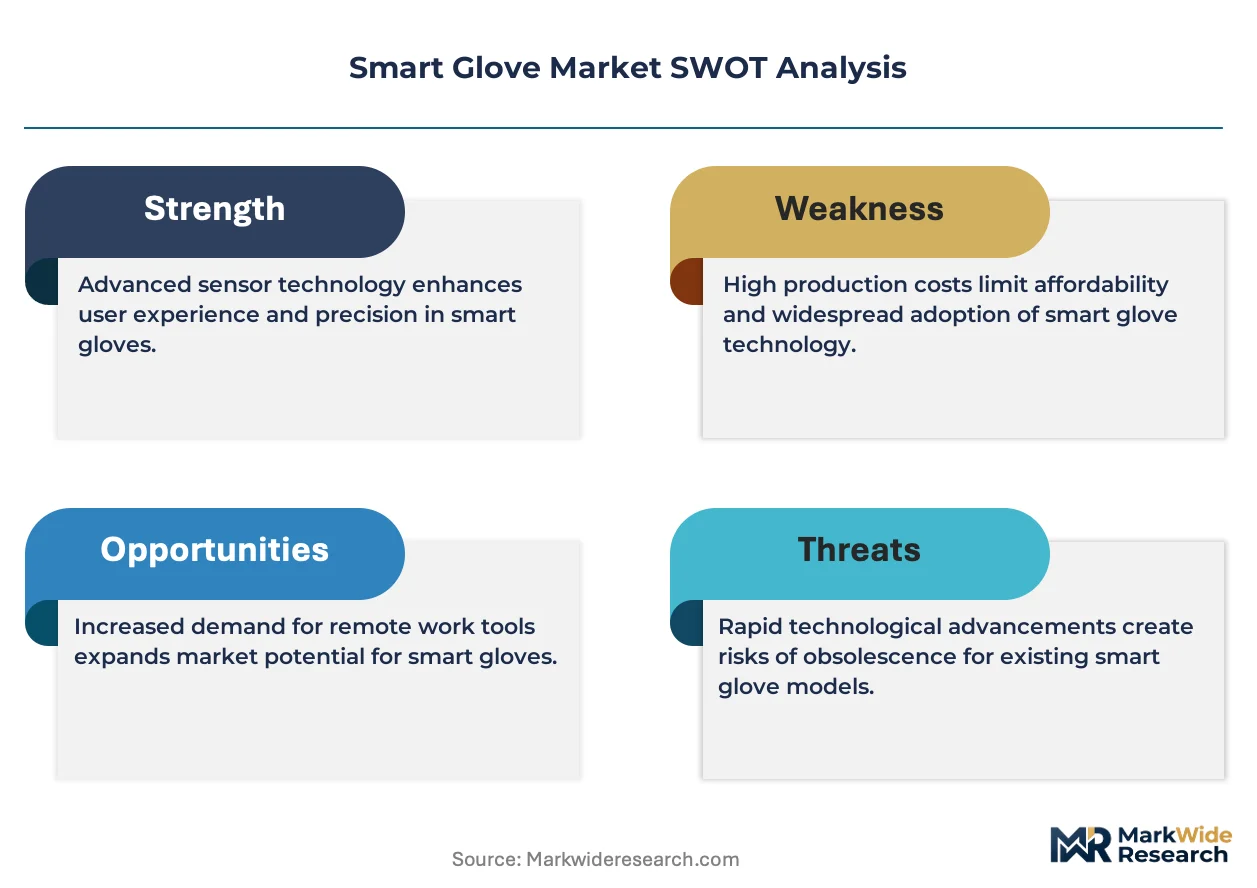
Growth Catalysts
- Digital Therapeutics Reimbursement:Germany's DiGA framework and Japan's PMDA digital health taxonomy are creating sustainable payment rails for haptic rehabilitation gloves prescribed outside hospital settings.
- Flexible Printed Electronics:Stretchable sensor arrays fabricated via roll-to-roll processing are collapsing per-unit sensor costs while maintaining sub-millimeter kinematic accuracy across 15-20 degrees of freedom.
- Occupational Safety Mandates:OSHA recordkeeping requirements for repetitive strain injuries are accelerating industrial procurement of gesture-tracking gloves for ergonomic intervention programs.
Market Restraints
- Silicone Supply Concentration:Haptic actuator membranes depend on medical-grade silicone feedstocks concentrated among three German and Japanese chemical suppliers, exposing manufacturers to input volatility.
- Battery Energy Density Limits:Lithium-polymer cell volumetric constraints restrict continuous haptic feedback duration to 4-6 hours, constraining all-day industrial deployments without tethered power.
- EU MDR Clinical Evidence Burden:Expanded biocompatibility and electrical safety documentation requirements under 2017/745 are extending CE marking timelines by 12-18 months for therapeutic claims.
Strategic Opportunities
- Home-Based Neurorehabilitation:Unmet demand for stroke recovery outside clinic walls creates white space for gloves paired with remote therapist monitoring platforms in the United States and Germany.
- VR Industrial Training Convergence:Integration with immersive safety simulation modules opens enterprise budgets previously reserved for dedicated haptic suits and motion capture systems.
- India PLI Scheme for Wearables:Production-linked incentives for electronics manufacturing are attracting component suppliers to Tamil Nadu and Karnataka, enabling cost-competitive export platforms.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time sensor fusion algorithms require specialized expertise in edge computing and signal processing that outpaces available engineering pipelines in most markets.
- Legacy EMR Integration Friction:Rehabilitation software platforms face protracted API negotiation cycles with Epic and Cerner systems, delaying clinical workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Glove Market |
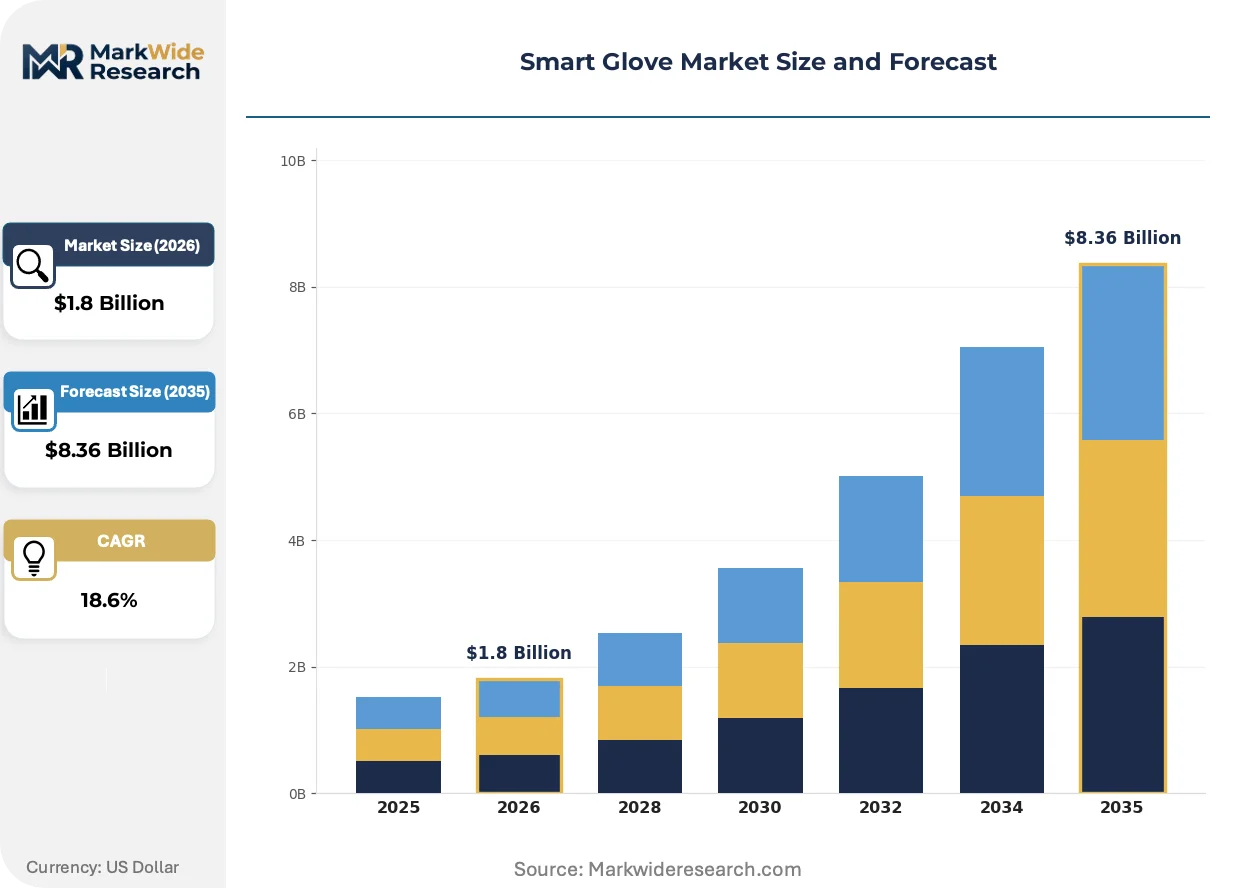
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Gloves, Haptic Gloves, Gesture Control Gloves, Rehabilitation Gloves Technology: Sensors, Connectivity, Actuation, Software Integration Application: Gaming, Healthcare, Industrial Training, Virtual Reality End User: Consumers, Healthcare Professionals, Industrial Workers, Researchers |
| Companies Covered | Bioservo Technologies, Flint Rehabilitation Devices, Syrebo, Myomo, Tyromotion, Neofect, BTL Industries, Ekso Bionics, Saebo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Glove Market Emerging Trajectories
Haptic feedback architectures are fragmenting into application-specific configurations, with industrial safety, clinical rehabilitation, and consumer gaming each demanding incompatible force-profile specifications. This divergence is compressing vendor R&D efficiency and fragmenting component supply bases.
Stretchable printed circuit fabrication is modularizing smart glove production, separating sensor array design from final garment integration. Rehabilitation centers in Germany and Japan are adopting platform-agnostic sensor modules that pair with third-party therapy software. This decomposition is compressing hardware margins while expanding addressable software attach rates.
FDA's evolving digital health software precertification pilot is reshaping therapeutic smart glove pathways, with algorithm-driven exercise adaptation now triggering SaMD classification discussions. The agency's 2023 guidance on machine learning-enabled devices is forcing vendors to document locked versus adaptive algorithm behaviors. Stroke recovery applications face the steepest compliance burden as adaptive difficulty protocols attract enhanced scrutiny.
Hospital procurement committees are unbundling hardware from software licensing, with bundled per-patient reimbursement models displacing capital equipment purchases. This shift is most visible in United States health systems participating in Medicare Advantage value-based care contracts, where remote monitoring outcomes directly impact risk-adjusted payments. Vendors without flexible SaaS pricing are losing access to integrated delivery networks.
Smart Glove Market Segmentation
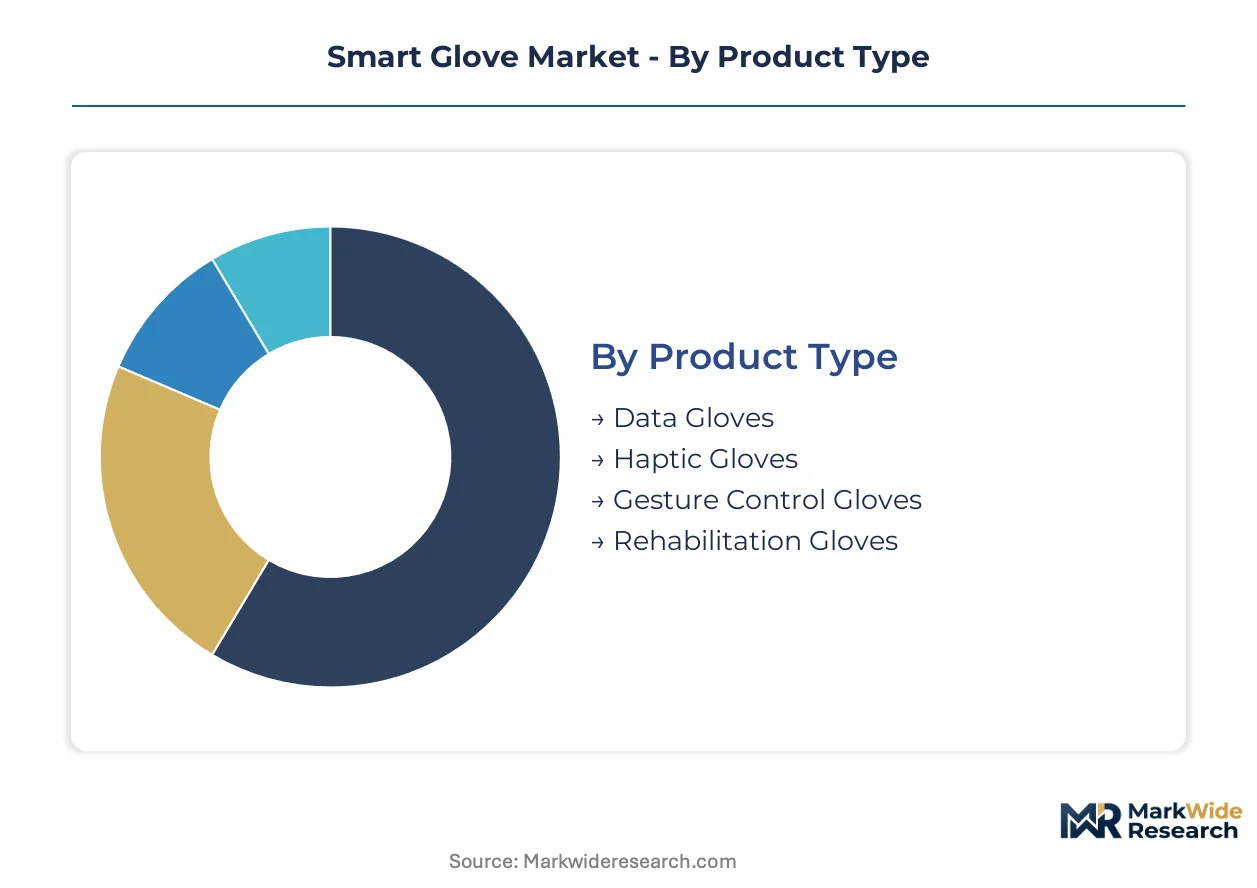
Smart glove architectures fragment across four distinct product categories, each demanding incompatible component specifications and regulatory pathways. Technology choices determine whether a glove functions as a passive data collector or an active therapeutic intervention. Application and end-user dimensions further stratify pricing power and margin structures.
Product Type:
Standardized rehabilitation platforms anchor volume procurement, while specialized haptic configurations command customization premiums in industrial and research settings.
- Rehabilitation Gloves:These integrate flexible sensor arrays with clinician-facing software dashboards for stroke and neuromotor recovery protocols. Demand concentrates in Germany and Japan where DiGA and PMDA reimbursement frameworks validate therapeutic claims outside hospital walls. FDA 510(k) clearance requirements tighten performance documentation for adaptive difficulty algorithms.
- Haptic Gloves:Force-feedback actuators deliver tactile resistance for virtual object manipulation in safety training simulations. Industrial procurement in the United States accelerates under OSHA ergonomic intervention mandates, though lithium-polymer battery constraints limit continuous deployment to 4-6 hour cycles.
- Gesture Control Gloves:Kinematic tracking enables touchless interface navigation for gaming peripherals and presentation tools. Price sensitivity in consumer channels compresses margins despite volume scale.
- Data Gloves:Pure capture devices without feedback mechanisms serve motion research and animation workflows. Academic and studio budgets favor modular sensor configurations over integrated garment designs.
Leading the category by volume: Rehabilitation Gloves. Growing fastest: Haptic Gloves.
Technology:
Component cost tiers separate high-precision clinical deployments from consumer-grade implementations, with sensor accuracy and wireless reliability as the primary differentiation axes.
- Sensors:Stretchable printed electronics fabricated via roll-to-roll processing achieve sub-millimeter bend sensing across 15-20 degrees of freedom. German and Japanese chemical suppliers concentrate medical-grade silicone feedstocks for haptic actuator membranes.
- Actuation:Electromechanical and pneumatic force generators create tactile feedback profiles. Industrial safety applications demand higher force ranges than rehabilitation protocols, fragmenting component supply bases.
- Connectivity:Low-latency wireless modules transmit kinematic data to edge processors or cloud platforms. Bluetooth and proprietary protocols compete on power consumption versus bandwidth tradeoffs.
- Software Integration:Real-time sensor fusion algorithms require specialized firmware expertise in edge computing. Rehabilitation platforms face protracted API negotiations with Epic and Cerner EMR systems.
Sensor arrays dominate component spend. Software integration delivers the steepest margin expansion trajectory.
Application:
Regulatory intensity varies dramatically, with healthcare-facing deployments navigating FDA and EU MDR pathways while gaming and VR segments operate under lighter compliance burdens.
- Healthcare:Therapeutic claims trigger FDA 510(k) and EU MDR biocompatibility requirements. Medicare Advantage value-based contracts in the United States favor remote monitoring outcomes that directly impact risk-adjusted payments.
- Virtual Reality:Immersive training modules for industrial safety programs open enterprise budgets previously reserved for dedicated haptic suits. Integration complexity with existing simulation platforms varies by vendor.
- Industrial Training:Ergonomic intervention programs accelerate procurement under OSHA recordkeeping requirements for repetitive strain injuries. Gesture-tracking data feeds into predictive injury models.
- Gaming:Peripheral price sensitivity limits premium positioning despite volume potential. Consumer channels favor standardized SKUs over specialized configurations.
Healthcare commands the highest average selling prices. VR industrial training exhibits the fastest adoption velocity among non-medical segments.
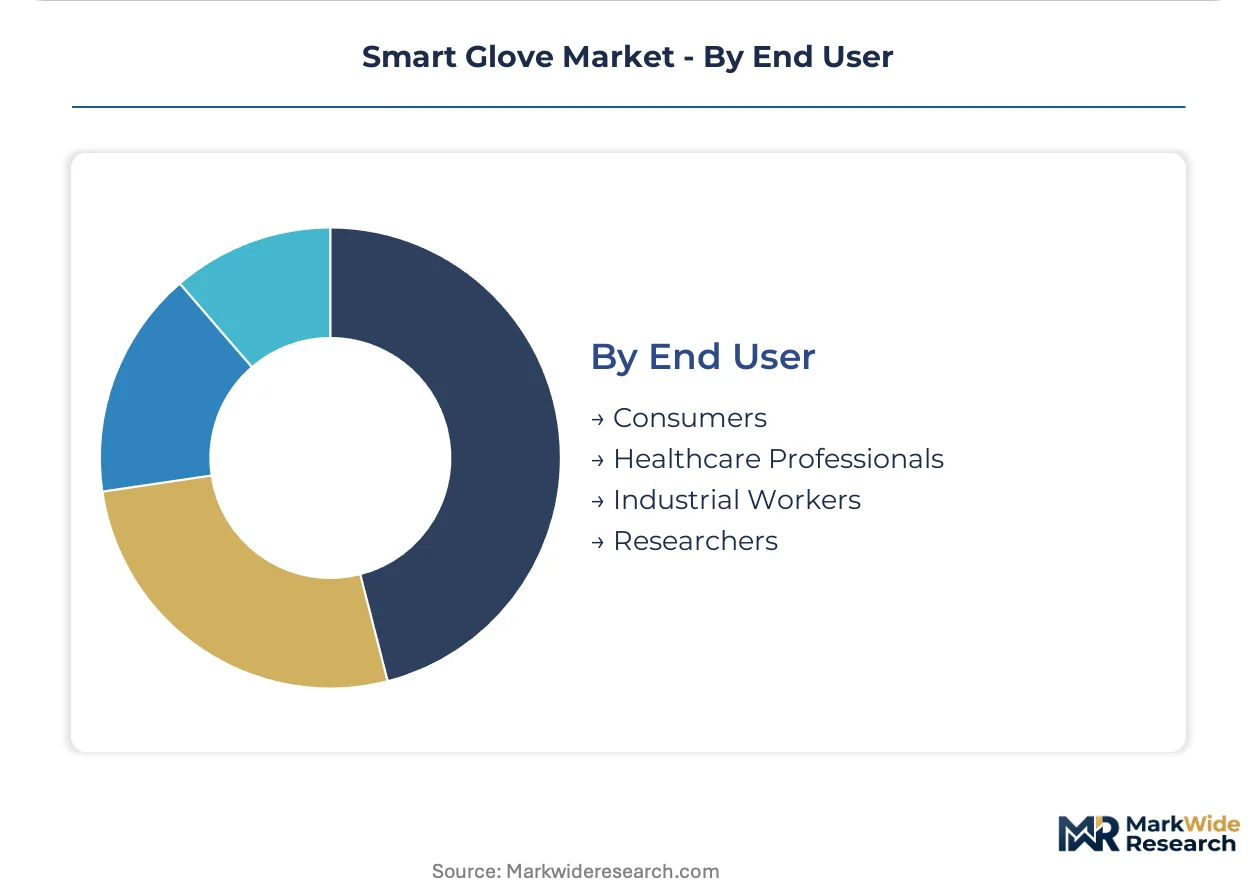
End User:
Procurement authority and reimbursement access create distinct commercial motions, from direct consumer sales to hospital committee approvals and enterprise safety budgets.
- Healthcare Professionals:Rehabilitation centers and hospital systems negotiate bundled per-patient reimbursement models. Germany's DiGA framework enables prescription outside traditional clinic walls.
- Industrial Workers:Safety departments procure gesture-tracking gloves for ergonomic monitoring. OSHA compliance documentation requirements shape feature prioritization.
- Researchers:Academic and corporate R&D labs demand open kinematic data formats and modular sensor configurations. Budget cycles favor capital equipment purchases over recurring subscriptions.
- Consumers:Gaming and fitness applications drive direct-to-channel volume. Price elasticity constrains feature inclusion compared to professional segments.
Healthcare Professionals generate the highest revenue per unit. Industrial Workers represent the fastest-expanding procurement category outside medical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santa Clara County anchors North American smart glove development, with San Jose-based sensor startups supplying stretchable electronics to rehabilitation hardware manufacturers across the United States.
United States
Medicare Advantage value-based contracts accelerate hospital procurement of remote monitoring gloves for stroke recovery. FDA 510(k) clearance requirements tighten documentation for adaptive difficulty algorithms. Pittsburgh's robotics corridor hosts rehabilitation technology clusters where clinician-software partnerships drive protocol validation.
Germany
DiGA framework reimbursement enables prescription of haptic rehabilitation gloves outside traditional clinic walls. EU MDR biocompatibility standards under 2017/745 extend CE marking timelines for therapeutic claims. Munich's medical device cluster concentrates industrial exoskeleton heritage firms pivoting toward occupational safety applications.
Japan
PMDA digital health taxonomy rewards validated clinical outcomes with favorable reimbursement for home-based neurorehabilitation. METI production incentives support domestic manufacturing of flexible sensor arrays. Osaka-Kobe industrial corridor hosts precision actuator suppliers serving both medical and VR training markets.
India
PLI scheme incentives for electronics manufacturing attract component suppliers to Tamil Nadu and Karnataka export platforms. Central Drugs Standard Control Organization regulates therapeutic device imports while domestic production scales. Bangalore's hardware startup ecosystem prototypes low-cost gesture control modules for industrial safety pilots.
South Korea
MFDS digital health pathways classify algorithm-driven rehabilitation gloves as software-as-medical-device when adaptive protocols trigger enhanced scrutiny. Ministry of Trade, Industry and Energy funds stretchable printed electronics research. Seoul Capital Area concentrates VR content studios integrating haptic feedback for industrial training simulations.
Smart Glove Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the smart glove landscape, with integrated garment manufacturers maintaining captive sensor fabrication while modular platform vendors outsource stretchable electronics to specialty foundries. The vendor base separates into three strategic archetypes: industrial exoskeleton heritage firms anchoring premium occupational pricing, rehabilitation software specialists monetizing through per-patient SaaS models, and component module suppliers enabling third-party therapy platform integration. Dominant competitive moves include backward integration into medical-grade silicone membrane production and strategic partnerships with Epic and Cerner for EMR API access.
Within the rehabilitation-focused tier, Neofect and Flint Rehabilitation Devices exemplify software-centric positioning, while Bioservo Technologies anchors the industrial heritage archetype with Swedish engineering credibility.
| Leading Market Players |
|---|
| Bioservo Technologies |
| Flint Rehabilitation Devices |
| Syrebo |
| Myomo |
| Tyromotion |
| Neofect |
| BTL Industries |
| Ekso Bionics |
| Saebo |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees and Medicare Advantage risk-bearing entities concentrate purchasing authority for therapeutic smart gloves, anchoring pricing power in outcome-contingent reimbursement models rather than capital equipment markups. This buyer concentration forces vendors toward per-patient SaaS structures that compress hardware margins while expanding software attach rates.
Pricing Analysis
Value-based pricing tied to stroke recovery outcomes anchors therapeutic smart glove commercialization in the United States and Germany. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared rehabilitation platforms from wellness-grade gesture controllers and industrial haptic modules. Cost compression in consumer gaming peripherals intensifies because price elasticity constrains feature inclusion. Healthcare professionals exhibit the least price sensitivity due to reimbursement insulation, while direct-to-consumer channels face the steepest resistance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from industrial safety programs, while specialized distributors serve rehabilitation centers with bundled software licensing. Component fabrication concentrates in Germany, Japan, and South Korea, where medical-grade silicone feedstocks and stretchable printed electronics anchor sensor array production. Battery cell supply draws from South Korean and Chinese manufacturers, exposing vendors to lithium-polymer sourcing volatility. Single-source vulnerability in haptic actuator membranes creates procurement risk. Distribution runs through hospital GPOs and enterprise safety procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone membrane capacity and specialized firmware engineering pipelines constrain supply expansion, propping pricing power for vendors with captive component access or exclusive therapist software partnerships.
For Market Incumbents: Hedge against modular platform disruption by securing backward integration into stretchable sensor fabrication or exclusive EMR API partnerships with Epic and Cerner. FDA software precertification pilot participation defends against SaMD reclassification threats. Capacity expansion in Tamil Nadu leverages India's PLI scheme to offset German and Japanese chemical supplier concentration. For New Entrants and Emerging Players: Capture white space in home-based neurorehabilitation by pairing low-cost gesture modules with remote therapist monitoring platforms. India's domestic production scaling offers the most penetrable geography for cost-competitive export platforms. Go-to-market through DiGA framework qualification in Germany bypasses hospital procurement committee friction. For Investors and Strategic Acquirers: The window for entry favors rehabilitation software specialists with validated clinical outcomes and flexible SaaS pricing architectures. Long-term viability hinges on reimbursement pathway diversification across FDA, EU MDR, and PMDA jurisdictions. Watch FDA algorithm classification guidance as the inflection signal for adaptive protocol compliance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| EMR API Partnership | Epic and Cerner integration unlocks hospital procurement committee access for rehabilitation platforms. |
| Backward Integration | In-house production of stretchable sensor arrays defends margin position against modular platform commoditization. |
| DiGA Framework Qualification | Germany's digital therapeutics reimbursement enables prescription outside traditional clinic walls. |
| FDA Software Precertification | Early pilot participation reduces adaptive algorithm compliance burden for stroke recovery applications. |
| PLI Scheme Manufacturing | India's production-linked incentives attract component suppliers to Tamil Nadu export platforms. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, DiGA reimbursement approvals, and PMDA digital health taxonomy decisions anchored the trend analysis, supplemented by interviews with rehabilitation technology executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA device filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare Advantage risk-adjustment data. Bottom-up sensor array cost modeling and top-down reimbursement pathway sizing were triangulated against vendor pricing disclosures.
Segment-weighting across product type, technology tier, application intensity, and end-user procurement authority shaped volume and value outputs. Modeled dimensions included rehabilitation versus haptic versus gesture control architectures, stretchable printed electronics versus conventional sensor configurations, healthcare versus industrial versus gaming end-markets, and direct-to-provider versus GPO-channeled distribution. CAGRs were derived from unit shipment trajectories and average selling price evolution across the projection horizon. Forecast inputs incorporated lithium-polymer energy density constraints and EU MDR clinical evidence burden timelines.
The model holds under stable reimbursement taxonomy classifications; deviation in FDA SaMD reclassification or EU MDR biocompatibility enforcement would shift commercialization timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
United States Sensor Market