
 UAE Greenhouse Horticulture Market | 2026-2036
UAE Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Greenhouse Horticulture Market Insights
The UAE's National Food Security Strategy 2051 is shifting procurement patterns across the horticulture value chain, compelling buyers to prioritize domestic greenhouse output over imports. Pure Harvest Smart Farms leverages advanced controlled-environment systems to supply premium tomatoes and berries to UAE retailers year-round. Emirates Hydroponics Farms anchors production capacity in Al Ain, sustaining consistent output for hotel and catering contracts. Al Dahra Agriculture competes through its integrated feed-to-food model, extending operational scale across multiple emirates.
Greenhouse horticulture denotes the cultivation of crops within enclosed structures where temperature, humidity, light, and CO2 levels are actively managed, typically employing hydroponic or soil-less substrates to optimize water use in arid climates. Its primary commercial purpose is to deliver fresh produce with predictable quality regardless of external weather conditions. Vegetables dominate volume throughput, while hydroponic technology captures the fastest expansion as growers prioritize water efficiency in a region with negligible rainfall. Commercial growers represent the deepest margin pool, locking in long-term supply agreements with supermarket chains and hospitality groups.
MOHAP and the Emirates Authority for Standardization and Metrology enforce food safety and quality benchmarks that determine market access for domestic greenhouse operators. The UAE's federal agricultural subsidies and emirate-level sustainability mandates shape capital allocation toward energy-efficient cooling and LED lighting systems. Stakeholders must monitor evolving import tariff policies and local content requirements that could either protect domestic growers or expose them to price competition from subsidized overseas suppliers.
Market Dynamics
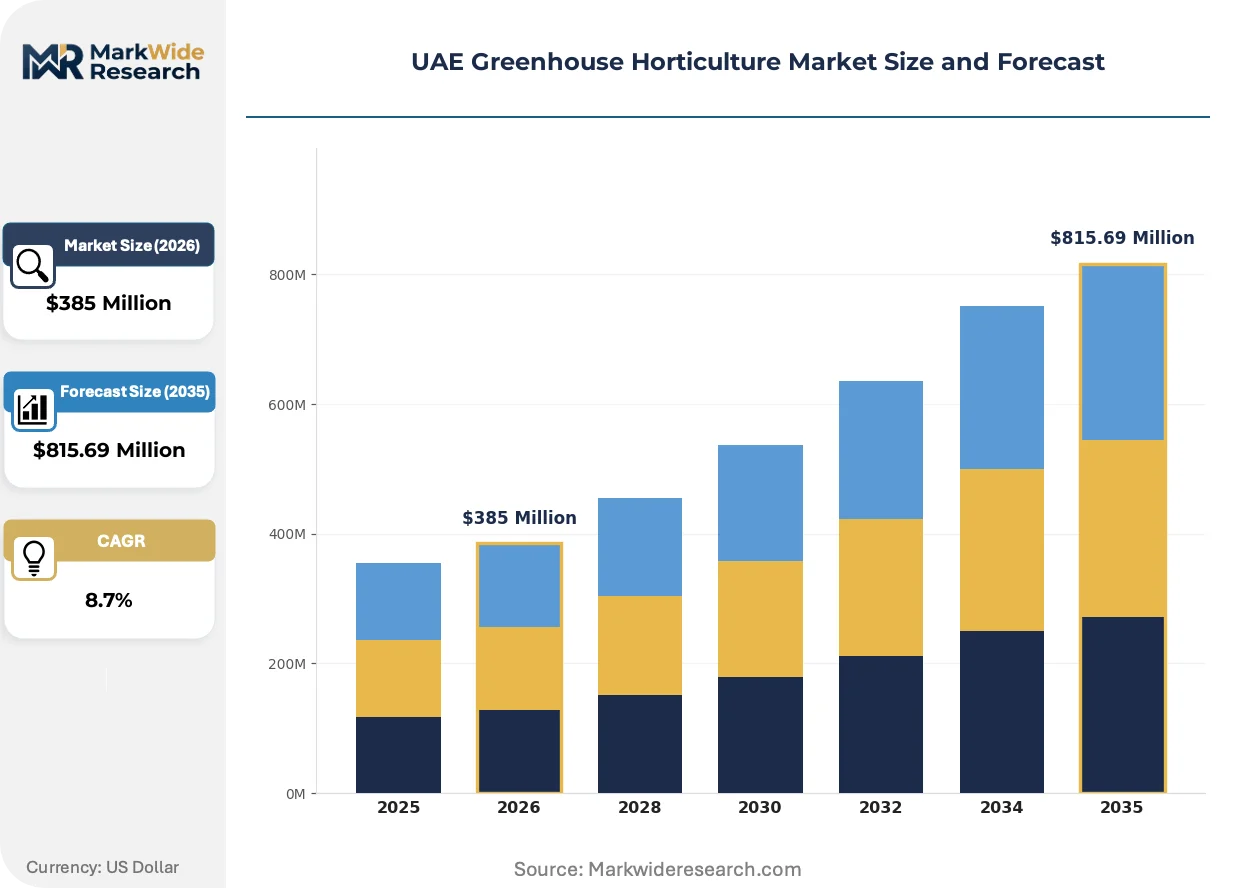
Federal agricultural subsidies under the National Food Security Strategy 2051 are redirecting capital flows toward controlled-environment agriculture, compressing payback periods for cooling and LED infrastructure while locking in long-term offtake agreements with hospitality and retail buyers.
Growth Catalysts
- National Food Security Strategy 2051:Federal subsidy frameworks reduce capital expenditure barriers for greenhouse developers, accelerating deployment of climate-controlled growing systems across Abu Dhabi and Dubai agri-tech zones.
- Hospitality procurement mandates:Hotel chains and catering groups are embedding local sourcing clauses into supplier contracts, creating guaranteed demand pools for domestic tomato and berry output.
- LED spectral tuning:Advanced lighting systems optimize photosynthetic photon flux density for specific cultivars, reducing energy intensity per kilogram of produce harvested.
Market Restraints
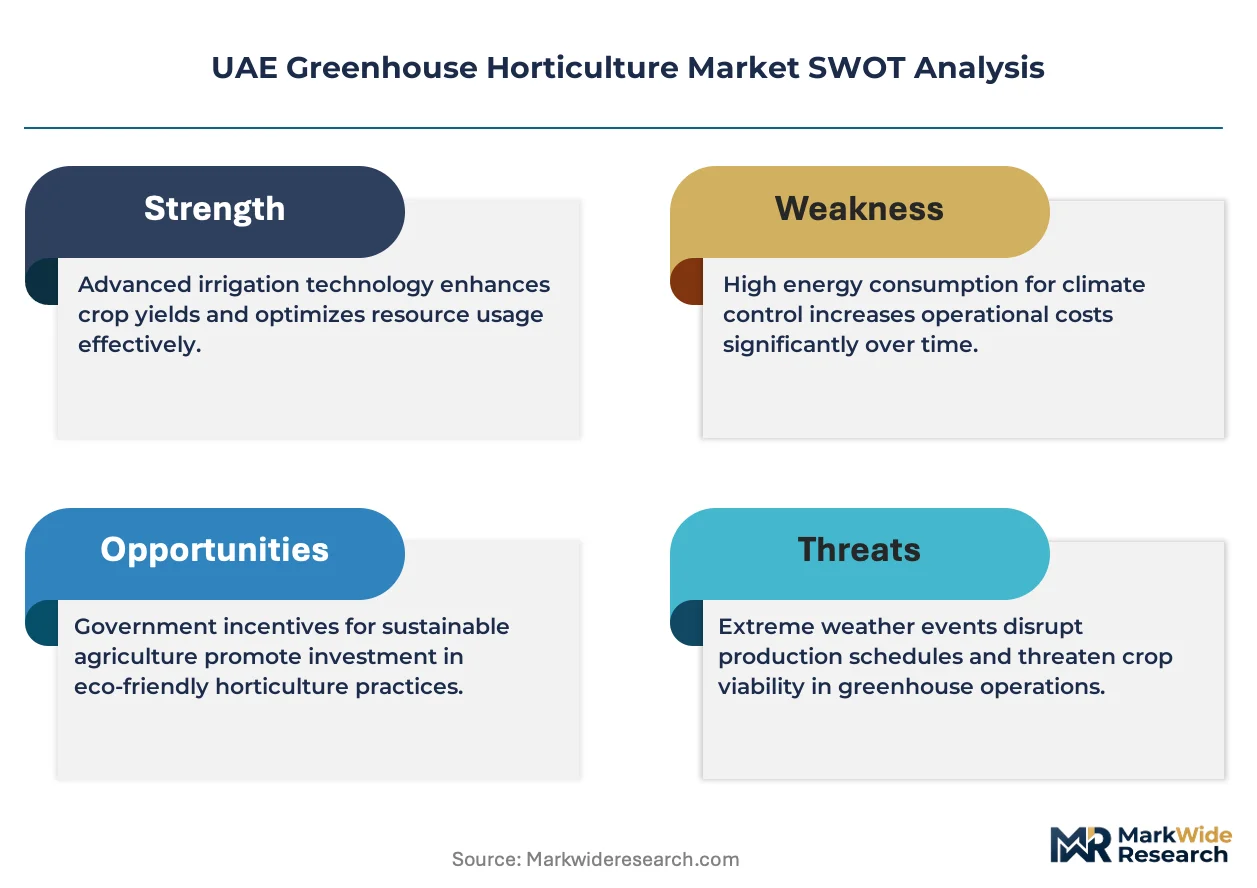
- Desalinated water dependency:Greenhouse operators remain tethered to municipal desalination capacity, exposing margins to tariff adjustments and supply rationing during peak summer demand.
- Cooling energy intensity:Evaporative and mechanical cooling systems consume 35-45% of operational expenditure, with grid tariffs set by federal electricity authorities.
- Import competition from subsidized producers:Dutch and Spanish greenhouse exporters benefit from EU Common Agricultural Policy support, pricing premium tomatoes below domestic production cost structures.
Strategic Opportunities
- Al Ain expansion corridor:Lower land costs and proximity to groundwater reserves position the eastern emirate for large-scale hydroponic leafy green production serving Abu Dhabi retail networks.
- Pharmaceutical-grade botanical extraction:Controlled-environment systems can pivot toward high-value medicinal plant cultivation, leveraging MOHAP GMP certification pathways for export markets.
- Direct-to-hotel distribution platforms:Digital procurement interfaces are bypassing wholesale intermediaries, enabling greenhouse operators to capture margin previously allocated to trading houses.
Industry Challenges
- Agronomic technician scarcity:Controlled-environment agriculture demands specialized expertise in nutrient solution management and integrated pest management, with training pipelines lagging facility commissioning schedules.
- MOHAP food safety certification timelines:Pre-market approval processes for novel growing substrates and biological inputs extend commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Greenhouse Horticulture Market |
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $815.69 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Herbs, Flowers Technology: Hydroponics, Aquaponics, Aeroponics, Soil-based End User: Commercial Growers, Research Institutions, Home Gardeners, Retailers Distribution Channel: Direct Sales, E-commerce, Wholesale, Retail Outlets |
| Companies Covered | Pure Harvest Smart Farms, Emirates Hydroponics Farms, Al Ain Farms, Al Dahra Agriculture, Elite Agro LLC, Madar Farms, Al-Futtaim Group, Al Jazeera Agricultural Company, Al Khorayef Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Greenhouse Horticulture Market Trends and Innovations
Technology convergence between automation hardware and crop science is compressing the gap between research-stage cultivation protocols and commercial-scale deployment, with regulatory frameworks racing to keep pace with operational innovation.
Closed-loop hydroponic systems with integrated nutrient film technique and dissolved oxygen monitoring are overtaking substrate-based cultivation in new facility designs. Commercial growers in Dubai's agri-tech zones are specifying these configurations for leafy green production lines. The shift is overtaking traditional perlite and rockwool setups by eliminating substrate replacement costs and reducing water consumption metrics that determine subsidy eligibility.
MOHAP's updated food safety regulations for controlled-environment agriculture now mandate full traceability from seed source to retail shelf, with digital logging requirements effective for all facilities exceeding two hectares of covered production area. Large-scale operators are retrofitting sensor networks to comply, while smaller growers face consolidation pressure from compliance cost burdens. The hospitality supply segment is responding fastest, with hotel procurement teams prioritizing certified suppliers in vendor scorecards.
Hypermarket buyers are consolidating supplier panels and demanding year-round volume guarantees that only multi-crop greenhouse operators can fulfill. This concentration is displacing spot-market purchasing and seasonal contracting models that dominated fresh produce procurement through 2020. Dubai-based retail chains are leading the transition, with Abu Dhabi cooperatives following as local production volumes stabilize.
UAE Greenhouse Horticulture Market Segmentation
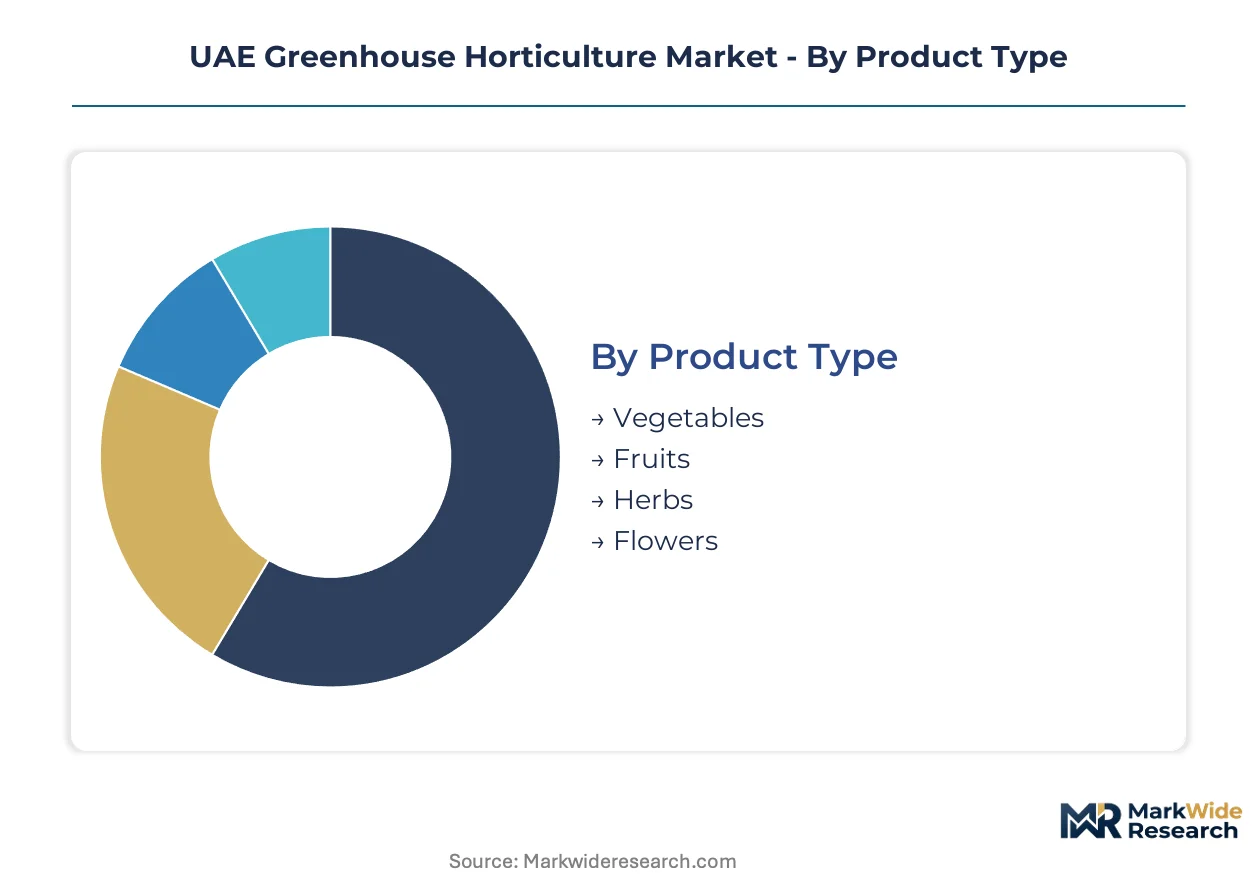
Segmentation in UAE greenhouse horticulture reveals how capital allocation and subsidy eligibility diverge across cultivation methods and buyer categories. Federal incentives under the National Food Security Strategy 2051 favor specific technology-product combinations, creating distinct margin pools that reshape competitive positioning.
Product Type:
Standalone vegetable production dominates facility design, while fruit and herb segments increasingly embed within multi-crop operations to optimize fixed-cost absorption.
- Vegetables:Tomatoes, cucumbers, and leafy greens constitute the primary throughput in controlled-environment facilities, with year-round output securing long-term supply contracts from Dubai-based retail chains. Abu Dhabi hospitality procurement teams prioritize certified vegetable suppliers for hotel and catering operations, embedding local sourcing mandates into vendor scorecards.
- Fruits:Strawberries and blueberries command premium positioning through advanced hydroponic substrates and spectral-tuned LED systems, though production volume remains constrained by pollination complexity and extended cultivation cycles. Demand concentrates in high-end retail segments where price tolerance absorbs elevated unit costs.
- Herbs:Basil, mint, and coriander serve restaurant and hotel kitchens requiring fresh-cut consistency, with shorter growth cycles enabling rapid inventory turnover for commercial growers.
- Flowers:Ornamental cultivation occupies limited greenhouse acreage, primarily serving event hospitality and landscaping contracts rather than mass retail channels.
Volume placements concentrate in Vegetables; the faster expansion belongs to Fruits.
Technology:
Cost tier differentiation separates capital-intensive hydroponic installations from lower-entry soil-based alternatives, with subsidy frameworks tilting investment toward water-efficient systems.
- Hydroponics:Nutrient film technique and deep water culture configurations eliminate substrate replacement costs while reducing water consumption metrics that determine federal subsidy eligibility. Dubai agri-tech zones specify these systems for new facility approvals.
- Aquaponics:Integrated fish-horticulture loops remain experimental at commercial scale, with MOHAP certification pathways for dual-output facilities still under development.
- Aeroponics:Mist-based root delivery minimizes water use below hydroponic benchmarks, though technical complexity and maintenance requirements limit deployment to research institutions and premium commercial operations.
- Soil-based:Traditional substrate cultivation persists in legacy Al Ain facilities where groundwater access reduces desalination dependency, though expansion is capped by emirate-level sustainability mandates.
Revenue concentration sits with Hydroponics; Aeroponics is climbing the fastest despite its narrower installed base.
End User:
Customer type determines contract structure, with commercial growers locking multi-year offtake agreements while research institutions and home gardeners operate on spot purchasing or grant funding.
- Commercial Growers:Large-scale operators capture the deepest margin pools through supermarket chain partnerships and hospitality supply contracts, with MOHAP traceability certification becoming a competitive threshold for panel inclusion.
- Research Institutions:Khalifa University and UAE University agricultural departments pilot novel cultivars and automation protocols, transferring proven techniques to commercial adopters.
- Home Gardeners:Residential hydroponic kits represent a niche segment, primarily distributed through e-commerce platforms targeting expatriate communities.
- Retailers:Hypermarket buyers consolidate supplier panels and demand year-round volume guarantees that displace seasonal contracting models.
Contract value aggregates with Commercial Growers; Research Institutions are gaining share fastest through technology transfer partnerships.
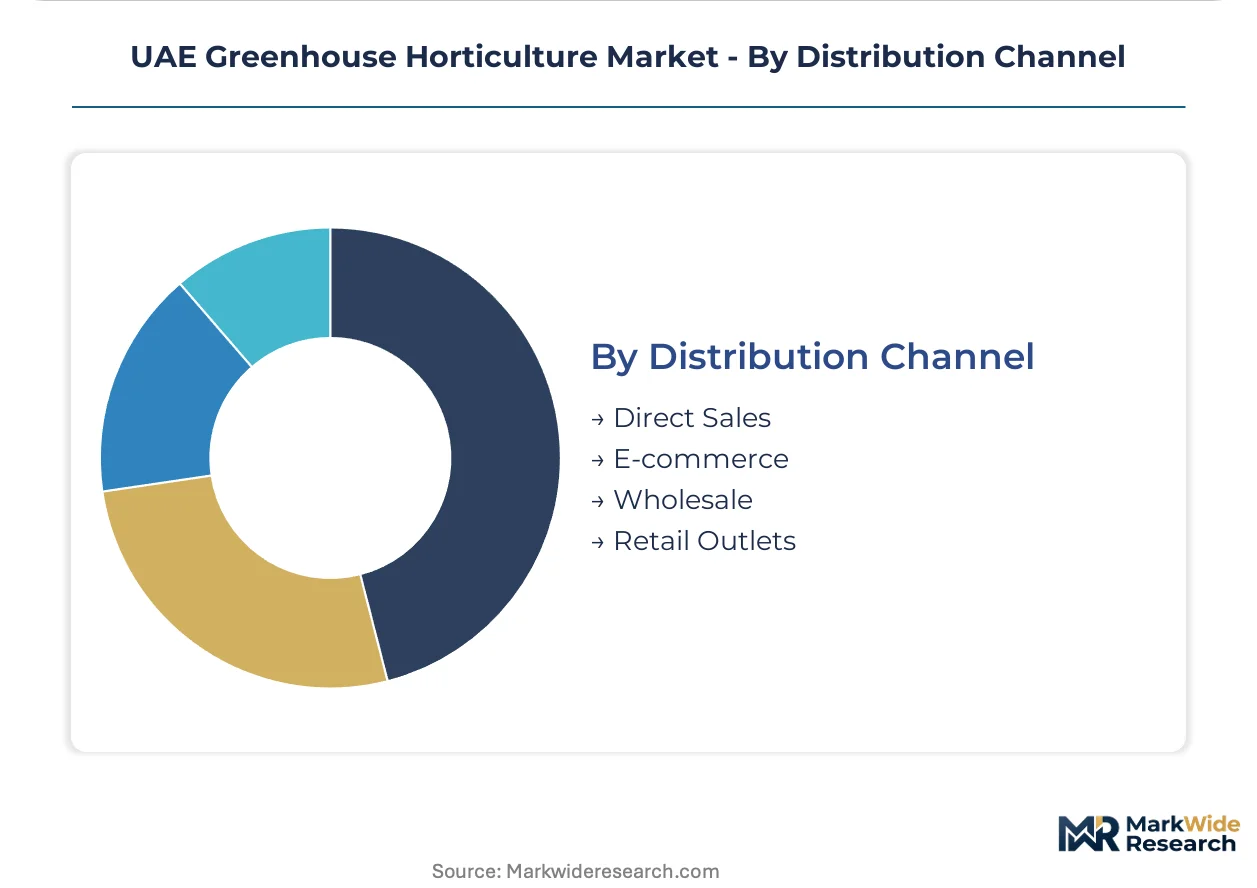
Distribution Channel:
Geography shapes channel effectiveness, with direct sales penetrating Abu Dhabi and Dubai hospitality clusters while wholesale intermediaries retain relevance in northern emirates.
- Direct Sales:Greenhouse operators bypass trading houses through digital procurement interfaces, capturing margin previously allocated to intermediaries while meeting hotel chain traceability requirements.
- E-commerce:Platform-based ordering expands reach to home gardeners and small restaurants, though cold-chain logistics constraints limit perishable throughput.
- Wholesale:Traditional trading houses retain volume in spot-market vegetable transactions, particularly for operators lacking MOHAP certification for retail direct supply.
- Retail Outlets:Hypermarket shelf space allocation favors certified domestic producers, with local sourcing clauses in federal procurement guidelines reinforcing placement priority.
Transaction volume flows through Direct Sales; E-commerce is expanding most quickly from its smaller base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's agri-tech zones and vertical farming clusters concentrate the bulk of UAE greenhouse investment, with government-backed infrastructure redirecting capital toward domestic production capacity.
Abu Dhabi
Hotel procurement teams and retail cooperatives drive vegetable offtake demand across the emirate. MOHAP traceability mandates shape supplier certification requirements for hospitality contracts. Al Ain anchors large-scale hydroponic production, leveraging groundwater access to reduce desalination dependency for leafy green supply chains.
Dubai
Hypermarket buyers consolidate supplier panels around year-round volume guarantees for tomatoes and berries. Federal subsidies under the National Food Security Strategy 2051 compress payback periods for LED and cooling infrastructure. Emirates Hydroponics Farms and Pure Harvest Smart Farms anchor production capacity within designated agri-tech corridors.
Sharjah
Research partnerships between UAE University agricultural departments and commercial growers transfer novel cultivar protocols to operational scale. Emirate-level sustainability mandates cap traditional soil-based expansion. Sharjah's industrial zones host pilot facilities testing integrated pest management automation.
Northern Emirates
Lower land costs attract greenhouse developers serving spot-market vegetable transactions outside certified retail channels. Wholesale intermediaries retain volume relevance where MOHAP certification barriers limit direct-to-hotel distribution. Ras Al Khaimah and Fujairah position for expansion as Dubai and Abu Dhabi land scarcity intensifies.
UAE Greenhouse Horticulture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability tiers, with MOHAP food safety approval separating panel-eligible suppliers from spot-market operators. The vendor base clusters around three archetypes: technology-integrated vertical farms, legacy hydroponic scale operators, and diversified agribusiness conglomerates with feed-to-food integration. M&A activity concentrates among mid-scale facilities seeking certification compliance through acquisition, while strategic partnerships between growers and hospitality procurement teams lock in multi-year offtake volumes.
Within the technology-integrated tier, Pure Harvest Smart Farms and Emirates Hydroponics Farms exemplify capital-intensive controlled-environment models. Al Dahra Agriculture occupies a diversified agribusiness position spanning multiple emirates. These three anchors represent divergent strategic bets on subsidy capture, hospitality contract density, and operational scale.
| Leading Market Players |
|---|
| Pure Harvest Smart Farms |
| Emirates Hydroponics Farms |
| Al Ain Farms |
| Al Dahra Agriculture |
| Elite Agro LLC |
| Madar Farms |
| Al-Futtaim Group |
| Al Jazeera Agricultural Company |
| Al Khorayef Group |
| Others |
Pricing and Supply Chain Analysis
Closed-loop hydroponic systems with integrated nutrient monitoring are compressing production costs while concentrating supply relationships around certified technology providers. This transition simultaneously reduces water expenditure metrics that determine MOHAP subsidy eligibility and locks growers into proprietary input supply contracts that reshape procurement economics across Abu Dhabi and Dubai agri-tech zones.
Pricing Analysis
Yield-per-square-meter guarantees anchor contract pricing for hospitality and retail buyers, with premium tiers commanding spreads based on MOHAP traceability certification and year-round volume reliability. Cost compression in standard-grade vegetable supply runs through desalinated water tariff exposure and cooling energy intensity, while hypermarket buyers demonstrate highest price sensitivity and hotel procurement teams absorb premiums for certified local sourcing.
Supply Chain Analysis
Desalinated water supply rests on UAE federal electricity and water authority infrastructure, with Dutch and Spanish greenhouse technology providers feeding equipment and seed genetics into domestic facilities. Single-source vulnerability concentrates in LED spectral systems and advanced climate control hardware, while distribution runs through direct-to-hotel digital platforms and consolidated wholesale panels serving northern emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE greenhouse horticulture sector sits in a controlled-environment technology transition, with hydroponic and aeroponic systems displacing legacy soil-based cultivation across federal subsidy-eligible projects.
For Market Incumbents: Acquire MOHAP-certified production capacity to consolidate panel positioning before compliance timelines harden. Lock multi-year offtake agreements with Dubai hospitality chains to defend margin pools against Dutch import competition, while retrofitting legacy Al Ain facilities with closed-loop nutrient systems to maintain subsidy access. For New Entrants and Emerging Players: Capture pharmaceutical-grade botanical extraction white space through MOHAP GMP certification pathways for export markets. Target northern emirates spot-market vegetable supply where certification barriers limit incumbent penetration, deploying direct-to-hotel digital procurement interfaces to bypass wholesale intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale facility consolidation plays as compliance costs drive panel rationalization. Five-to-ten-year viability favors technology-integrated operators with locked hospitality contracts over commodity spot-market exposure. Watch MOHAP substrate approval timelines as inflection signal for commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Traceability Certification Investment | Unlocks hypermarket panel inclusion and hospitality procurement scorecard priority under National Food Security Strategy 2051 guidelines. |
| Closed-Loop Hydroponic System Deployment | Reduces water consumption metrics that determine federal subsidy eligibility while eliminating substrate replacement costs. |
| Direct-to-Hotel Distribution Platform Launch | Bypasses wholesale margin extraction and captures value previously allocated to trading house intermediaries in Dubai. |
| Al Ain Production Corridor Expansion | Leverages groundwater access to reduce desalination dependency for leafy green supply chains serving Abu Dhabi retail networks. |
| Pharmaceutical-Grade Botanical Cultivation Pivot | Opens high-value export pathways through MOHAP GMP certification for medicinal plant extraction markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across greenhouse operations managers, hospitality procurement directors, agri-tech equipment suppliers, and MOHAP compliance officers. UAE Ministry of Climate Change and Environment publications, Emirates Authority for Standardization and Metrology technical standards, and federal subsidy disclosure documents supplied validation benchmarks. Bottom-up facility capacity modeling triangulated against top-down consumption estimates from retail and hospitality sector reports.
Segment-level granularity modeled cultivation technology, product type, end-user category, and distribution channel across the projection horizon. CAGRs derived from facility commissioning schedules, subsidy allocation trajectories, and contract volume disclosures. Water tariff sensitivity and cooling energy intensity served as scenario inputs for operational cost projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to desalination capacity expansion and EU import subsidy policy shifts. Assumptions reflect current MOHAP regulatory frameworks and federal agricultural incentive structures. A small set of triggers—MOHAP substrate approval timelines, emirate-level sustainability mandate tightening, and Dutch CAP export pricing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dry Onion Market
Vegetables
Artichokes Market
Vegetables
Acorn Squash Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
IQF Vegetables Market
Vegetables
UAE Tomato Market
Vegetables
Garden Cress Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Global Mushroom Market
Vegetables
South America Peas Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Qatar Greenhouse Market
Vegetables
Field Peas Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Sweet Potatoes Market