
 Argentina Maize Market | 2026-2036
Argentina Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Maize Market Outlook
Agronomic technician availability is bifurcating the Argentina maize value chain, with large operators securing trained crop advisors while smaller growers face yield gaps. Cargill Argentina leverages its Rosario terminal network to sustain export throughput during harvest peaks. Bioceres Crop Solutions specializes in drought-tolerant seed genetics that anchor productivity in marginal rainfall zones. Vicentin competes through vertically integrated oilseed and grain origination across Santa Fe and Córdoba provinces.
Maize in Argentina denotes Zea mays grain cultivated across the humid Pampas and western expansion zones, typically achieving 10–12 metric tons per hectare under irrigation, with protein content averaging 8–9 percent and moisture specifications capped at 14.5 percent for commercial trade. The crop serves as the primary carbohydrate base for broiler and hog feed formulations, as well as for wet-milling into starches and sweeteners. Yellow maize dominates export flows and domestic feed compounding, while white maize occupies premium food-processing channels for cornmeal and snack production. Animal feed represents the deepest demand pool, though biofuel blending mandates are redirecting volume toward ethanol distilleries in Tucumán and Salta.
Argentina's national agricultural food safety and quality service, SENASA, enforces export phytosanitary protocols that shape market access timing and certification costs for shipments to Brazil and Southeast Asia. The Secretariat of Agriculture, Livestock and Fisheries oversees biotech approval timelines that determine which stacked-trait varieties reach commercialization. Stakeholders must monitor how Buenos Aires province freight rate differentials and crushing margin volatility reshape origination incentives ahead of each planting season.
Market Dynamics
SENASA phytosanitary certification tightening is compressing origination timelines across the Argentina maize value chain, forcing exporters to front-load traceability investments before harvest peaks.
Growth Catalysts
- Biofuel blending mandates:Provincial ethanol requirements in Tucumán and Salta redirect maize volume toward distillery offtake, deepening domestic demand pools beyond traditional feed channels.
- Pampas feed miller expansion:Poultry and swine integrators in Buenos Aires province scale yellow maize procurement, concentrating volume demand near Rosario crushing clusters.
- Biotech trait commercialization:Stacked-trait varieties approved by the Secretariat of Agriculture accelerate yield density in western expansion zones with marginal rainfall.
Market Restraints
- Freight rate volatility:Buenos Aires province trucking costs swing with fuel price shocks, eroding farmgate-to-port margins for growers outside the Rosario radius.
- Input cost concentration:Fertilizer and crop protection sourcing depends on import channels through Bahía Blanca, exposing producers to currency-driven price spikes.
- Phytosanitary compliance friction:SENASA traceability documentation adds certification lag days that compress export windows for time-sensitive Southeast Asian shipments.
Strategic Opportunities
- Córdoba province origination:Underdeveloped silo and rail infrastructure in this western belt creates first-mover advantage for logistics investors building direct-to-port corridors.
- Drought-tolerant genetics:Seed technology convergence with precision moisture monitoring opens acreage in La Pampa and San Luis where dryland abandonment previously dominated.
- Vertical integration into food processing:White maize premiums for cornmeal and snack channels incentivize crush-and-mill investments bypassing commodity export pathways.
Industry Challenges
- Agronomic technician scarcity:Crop advisor training programs lag operator expansion, bifurcating yield outcomes between large managed farms and smaller unassisted holdings.
- Certification timeline compression:SENASA inspection queue bottlenecks during March-May harvest peaks force exporters to pre-position inventory or risk vessel demurrage.
- Legacy storage inadequacy:On-farm silo capacity deficits in Santa Fe and Entre Ríos force rapid post-harvest sales, stripping producers of price timing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Maize Market |
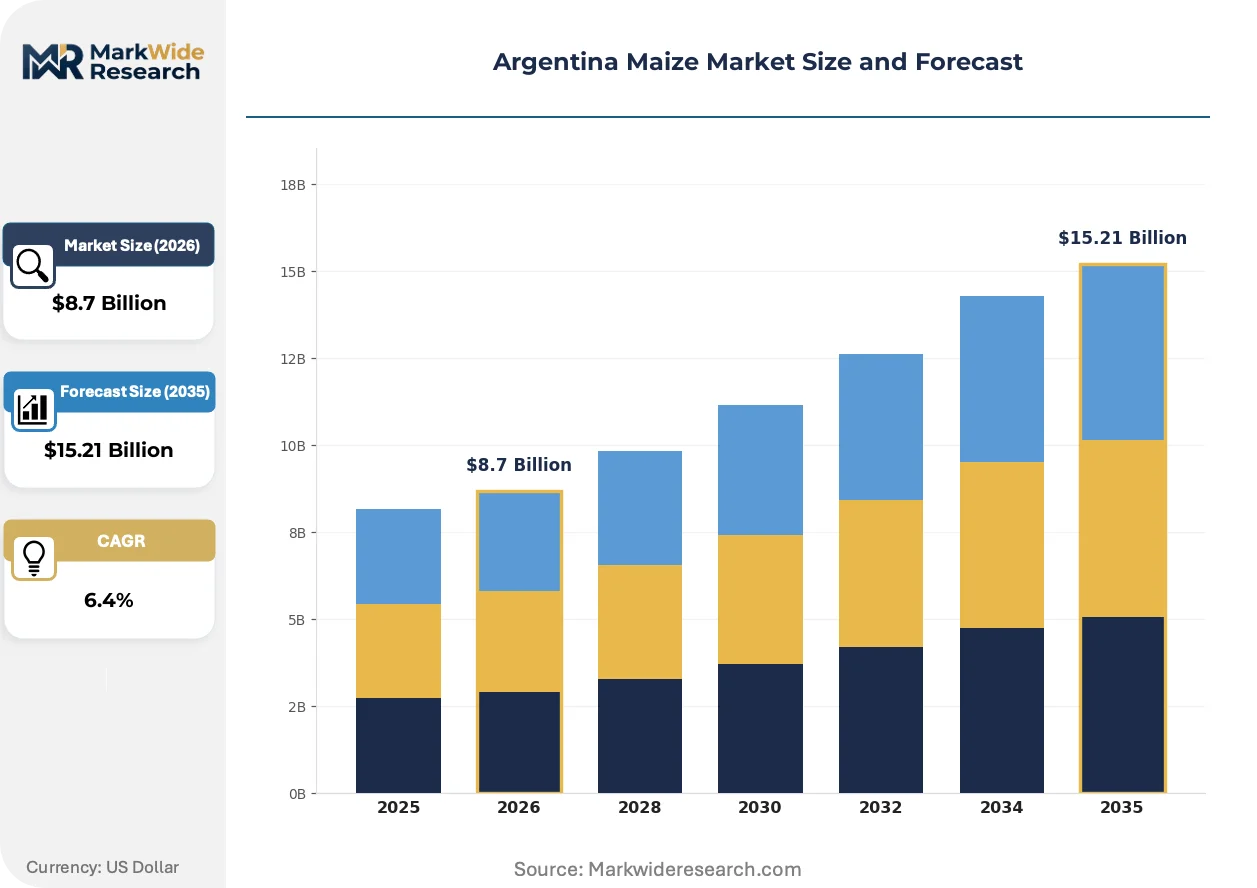
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Maize, White Maize, Sweet Maize, Popcorn End Use Industry: Food Processing, Animal Feed, Biofuel, Starch Production Distribution Channel: Direct Sales, Wholesalers, Retailers, Exporters Packaging Type: Bags, Bulk, Pallets, Containers |
| Companies Covered | Louis Dreyfus Company Argentina, Vicentin, ADM Argentina, Adeco Agro, Los Grobo, Cargill Argentina, Nidera Argentina, Bioceres Crop Solutions, Bunge Argentina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Maize Market Strategic Shifts
Digital traceability platforms and genetic trait stacking are compressing traditional origination hierarchies across the Argentina maize belt, redistributing competitive advantage toward data-integrated operators.
Gene-edited drought-tolerance traits developed by Bioceres Crop Solutions is fragmenting yield risk geography across the Pampas. Large operators with irrigation infrastructure adopt these varieties fastest, while dryland growers face displacement pressure in marginal rainfall zones. The technology is fragmenting traditional seed market share held by conventional hybrid suppliers.
SENASA electronic phytosanitary certification mandates reshape export documentation workflows for shipments bound for Brazil and Southeast Asia. The regulation forces real-time lot tracking from farm to vessel, raising compliance costs for smaller traders lacking integrated ERP systems. Buenos Aires province exporters with captive laboratory partnerships adapt fastest, widening their certification speed advantage.
Direct contracting between poultry integrators and farm cooperatives is displacing spot-market origination in the Rosario hinterland. Feed millers now lock multi-month supply agreements before planting, transferring price risk backward to growers. This pattern concentrates most visibly in Buenos Aires province, where vertically integrated broiler operations source sixty percent of volume through pre-harvest contracts.
Argentina Maize Market Segmentation
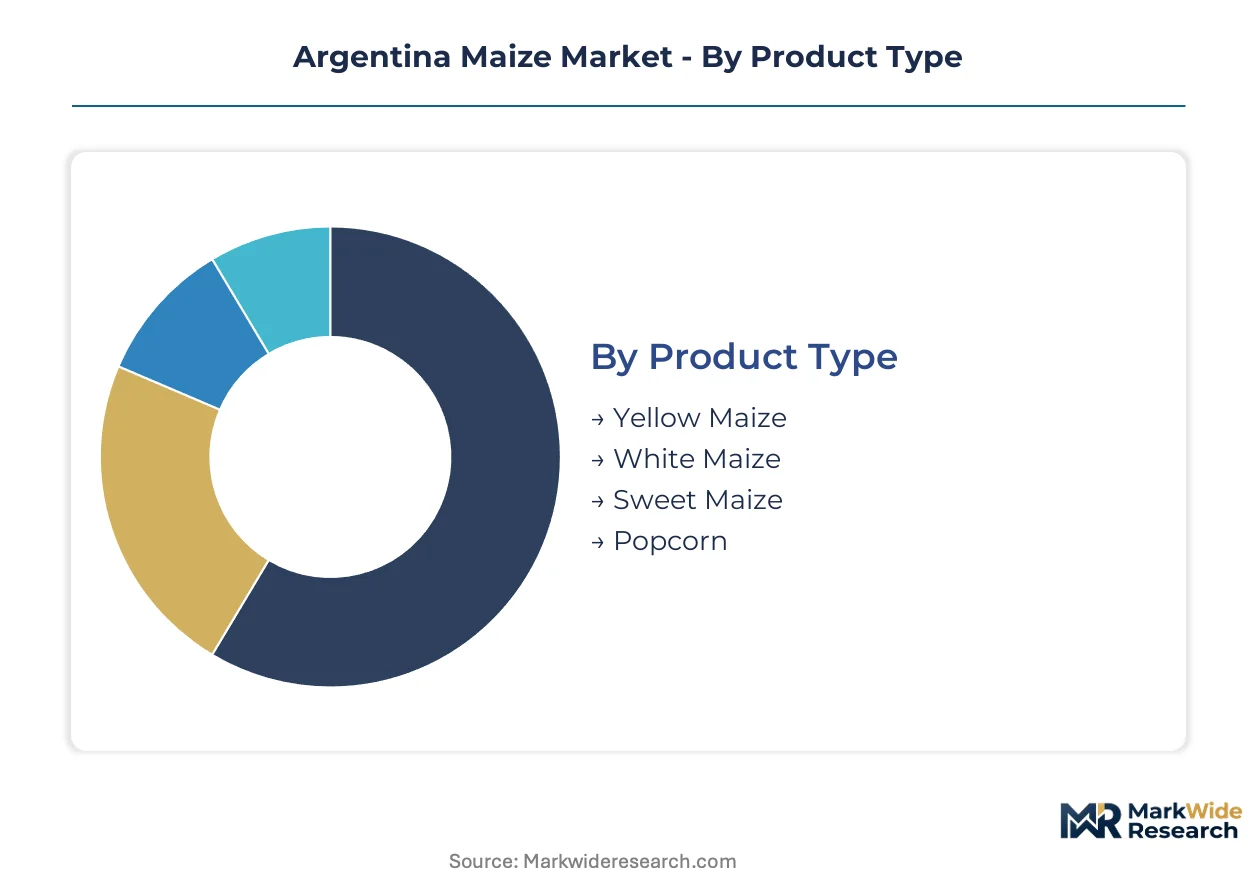
Segmentation in Argentina's maize market reflects distinct regulatory pathways and infrastructure requirements that shape how value flows from Pampas production zones to end-use destinations. Understanding these divisions clarifies why certain channels command premium positioning while others compete on throughput volume.
Product Type:
SENASA phytosanitary protocols differentiate export eligibility across grain categories, with color-based specifications triggering distinct certification timelines and destination market access.
- Yellow Maize:High-yield dent varieties with 8–9 percent protein content and 14.5 percent moisture caps serve as the standard specification for export shipments and poultry feed formulations. Rosario crushing clusters concentrate procurement of this grade, with Buenos Aires province feed millers scaling direct origination agreements to secure supply ahead of harvest peaks.
- White Maize:Food-grade varieties with superior milling characteristics and lower oil content command premiums in cornmeal and snack production channels. Demand concentrates in specialized processing facilities that bypass commodity export pathways, though volume remains constrained by limited dedicated storage infrastructure outside Córdoba province.
- Sweet Maize:Higher sugar content varieties for fresh consumption and canning operations occupy niche domestic channels with perishability-driven logistics requirements.
- Popcorn:Small-kernel hard endosperm types for snack expansion require specific expansion ratio certifications that limit supplier pools to established seed programs.
Established volume favors Yellow Maize; emerging adoption favors White Maize.
End Use Industry:
Application-driven demand pools diverge sharply in their sensitivity to price volatility, biofuel policy mandates, and protein specification requirements.
- Food Processing:White maize milling for cornmeal, grits, and snack base materials demands consistent granulation and mycotoxin controls that exceed feed-grade tolerances. Santa Fe province processors source through dedicated origination channels that bypass spot-market volatility.
- Animal Feed:Yellow maize constitutes the primary carbohydrate base for broiler and hog rations, with Pampas integrators locking multi-month supply contracts before planting to transfer price risk backward to growers.
- Biofuel:Provincial ethanol blending mandates in Tucumán and Salta redirect volume toward distillery offtake, creating domestic demand competition that tightens exportable surplus availability.
- Starch Production:Wet-milling operations require specific amylose-amylopectin ratios and low-protein specifications that limit eligible supply to contract-grown varieties with identity preservation protocols.
Feed applications dominate current throughput; biofuel offtake is climbing the fastest.
Distribution Channel:
Channel selection determines exposure to SENASA certification lag days and freight rate volatility across the Buenos Aires province logistics network.
- Direct Sales:Large operators with captive logistics infrastructure bypass intermediary margins by contracting directly with Rosario terminal operators and crushing facilities. This channel compresses origination timelines but requires integrated ERP systems for real-time traceability compliance.
- Wholesalers:Regional grain merchants aggregate volume from smaller holdings lacking direct port access, concentrating in Santa Fe and Entre Ríos where on-farm storage deficits force rapid post-harvest sales.
- Retailers:Bagged product distribution for small-scale livestock operations and food processors serves fragmented demand with higher per-unit logistics costs.
- Exporters:Terminal operators with SENASA laboratory partnerships achieve fastest certification speeds, widening competitive advantage for Southeast Asian and Brazilian shipments during March-May harvest compression.
Direct sales capture margin efficiency; exporter channels gain share fastest through certification speed advantages.
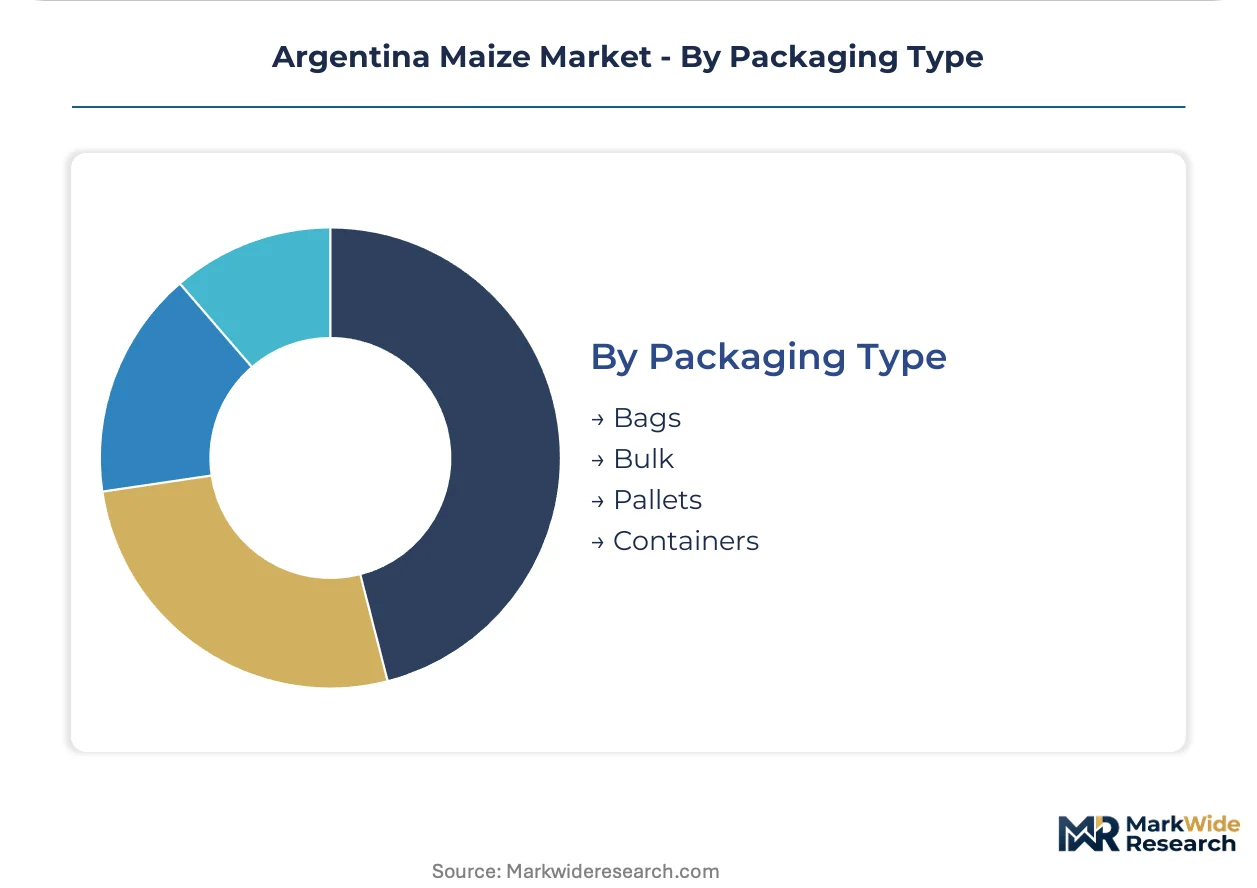
Packaging Type:
Packaging selection reflects downstream customer scale and contamination risk tolerance across handling stages.
- Bags:25–50 kilogram woven polypropylene units serve small-scale feed compounders and food processors requiring inventory flexibility without bulk handling infrastructure.
- Bulk:Unpackaged grain movement through dedicated hopper trucks and river barges minimizes per-unit handling costs for Rosario terminal shipments exceeding 5,000 metric tons.
- Pallets:Unitized bag stacks for containerized export reduce loading labor and enable intermodal transfer efficiency at intermediate consolidation points.
- Containers:Sealed twenty-foot equivalent units with controlled atmosphere options protect against moisture ingress for high-value food-grade shipments to distant markets.
Bulk handling dominates export volume; containerization is expanding most quickly for premium food-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SENASA phytosanitary protocols anchor export logistics across Argentina's maize belt, with provincial freight differentials and crushing capacity clustering reshaping origination incentives seasonally.
Buenos Aires Province
Poultry and swine integrators scale yellow maize procurement near Rosario crushing terminals. The Secretariat of Agriculture oversees biotech approval timelines that determine stacked-trait variety deployment. Port logistics concentrate around Rosario, where feed millers lock multi-month supply agreements before planting.
Santa Fe Province
On-farm silo capacity deficits force rapid post-harvest sales from smaller holdings. SENASA electronic certification mandates compress documentation workflows for export shipments. Regional grain merchants aggregate volume through wholesaler channels lacking direct port access.
Córdoba Province
Underdeveloped rail infrastructure creates first-mover advantage for logistics investors building direct-to-port corridors. The Secretariat of Agriculture regulates drought-tolerant seed commercialization timelines. White maize premiums for food processing concentrate in specialized milling facilities bypassing commodity export pathways.
Entre Ríos Province
Legacy storage inadequacy strips producers of price timing flexibility during harvest peaks. SENASA inspection queue bottlenecks force exporters to pre-position inventory or risk vessel demurrage. Provincial ethanol blending mandates compete for volume with traditional feed channels.
Argentina Maize Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Argentina maize value chain. Large trading houses with captive terminal infrastructure dominate export throughput, while specialized seed developers anchor productivity gains in marginal rainfall zones. The market structure fragments between integrated origination platforms and regional cooperatives. Dominant competitive moves include backward integration into crushing assets and strategic partnerships with SENASA-certified laboratories.
Among integrated trading houses, Cargill Argentina, Louis Dreyfus Company Argentina, and Vicentin occupy positions defined by logistics scale and origination reach. Cargill Argentina exemplifies the terminal-network archetype through Rosario infrastructure. Louis Dreyfus Company Argentina represents the diversified-commodity-trading tier. Vicentin anchors vertically integrated oilseed and grain origination across Santa Fe and Córdoba provinces.
| Leading Market Players |
|---|
| Louis Dreyfus Company Argentina |
| Vicentin |
| ADM Argentina |
| Adeco Agro |
| Los Grobo |
| Cargill Argentina |
| Nidera Argentina |
| Bioceres Crop Solutions |
| Bunge Argentina |
| Others |
Value Chain & Pricing Dynamics
Harvest-to-vessel lead times averaging 45–60 days compress pricing power for growers outside the Rosario logistics radius, concentrating margin capture among terminal operators with pre-positioned inventory and SENASA-certified laboratory partnerships. Buenos Aires province feed millers exploit this concentration through multi-month pre-planting contracts that transfer price risk backward to originators.
Pricing Analysis
Buenos Aires province farmgate-to-port spreads widen during March-May harvest peaks when trucking capacity tightens and SENASA inspection queues bottleneck. Contract-based long-term offtake dominates, with price differentiation driven by certification grade (SENASA phytosanitary tier) and volume scale (bulk terminal access versus bagged wholesaler channels). Cost compression in spot-market tiers is intensifying because smaller holdings lacking direct port access must accept rapid-fire sales to regional merchants. Poultry integrators with captive crushing assets exhibit lowest price sensitivity; dryland growers in marginal rainfall zones face highest sensitivity due to yield volatility and input cost spikes.
Supply Chain Analysis
Strategic stockpiling prevails among Rosario terminal operators who pre-position inventory ahead of SENASA certification peaks, while just-in-time procurement characterizes feed millers with direct cooperative contracts. Geographic supply concentration centers on Argentina's Pampas belt, with secondary flows from Brazil and Paraguay shaping regional arbitrage. Raw material dependencies include imported fertilizer through Bahía Blanca, crop protection chemicals, and diesel fuel for provincial trucking networks. Single-source vulnerability runs through the Rosario riverine logistics corridor where barge and terminal capacity concentrates. Distribution runs through vertically integrated origination platforms, regional grain cooperatives, and SENASA-certified export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
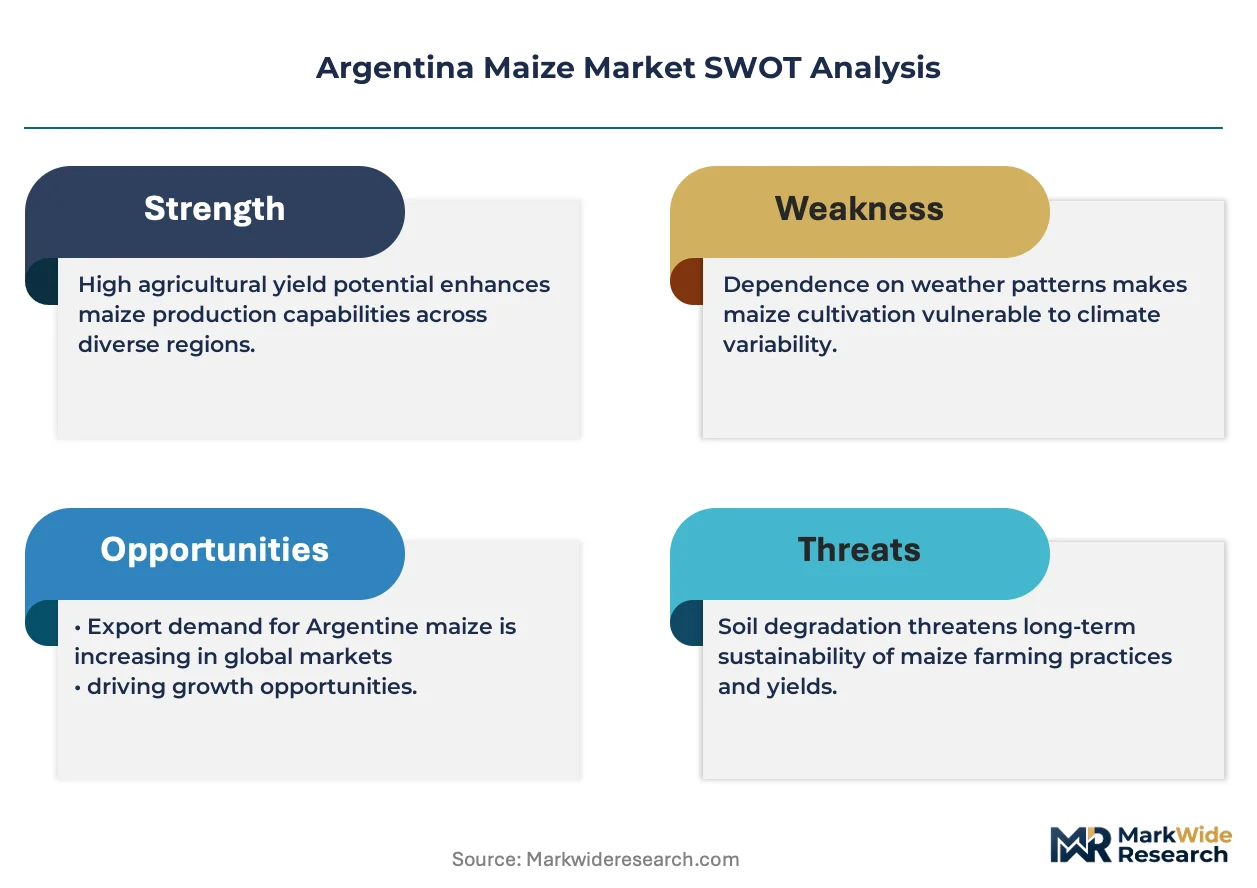
This market demands substitution defense against Brazilian maize export expansion, which threatens Argentina's traditional Southeast Asian market share through superior port logistics and currency advantages.
For Market Incumbents: Consolidate origination control through backward integration into cooperative equity stakes in Córdoba and Santa Fe provinces, locking volume ahead of harvest peaks. Deepen SENASA laboratory partnerships to compress certification lag days and defend terminal throughput against Brazilian port competition. Prioritize drought-tolerant genetics licensing to anchor productivity in western expansion zones where Brazilian originators lack comparable seed technology.
For New Entrants and Emerging Players: SENASA electronic certification fast-track programs offer regulatory arbitrage for logistics investors building direct-to-port rail corridors from underdeveloped Córdoba silo networks. Target white maize food processing channels where premium milling specifications and limited dedicated storage infrastructure create margin capture opportunities bypassing commodity export pathways. Pursue poultry integrator partnerships as the most penetrable demand anchor, offering pre-harvest contract structures that transfer price risk management services to growers.
For Investors and Strategic Acquirers: Long-term, this sits as a logistics-infrastructure play because origination margin capture increasingly depends on captive terminal and rail assets rather than trading expertise alone. Acquisition targets should emphasize operators with SENASA-certified laboratory partnerships and Rosario riverine access. Watch Brazilian real exchange rate volatility as the critical inflection signal—material depreciation would accelerate export share loss and compress Argentine farmgate pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Equity | Locks origination volume in Santa Fe and Córdoba ahead of harvest peaks. |
| SENASA Laboratory Partnership Expansion | Compresses phytosanitary certification timelines for Southeast Asian export windows. |
| Drought-Tolerant Genetics Licensing | Opens acreage in La Pampa and San Luis where dryland abandonment previously dominated. |
| Direct-to-Port Rail Corridor Development | Bypasses Rosario congestion for Córdoba originators seeking terminal access. |
| Pre-Harvest Contract Structuring | Transfers price risk from poultry integrators to farm cooperatives in Buenos Aires province. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the Argentina maize value chain, including grain trading executives at Rosario terminal operators, agronomic advisors managing large Pampas farms, SENASA certification specialists, poultry procurement managers at Buenos Aires integrators, and logistics directors at riverine barge operators. Secondary validation drew from Argentina's Secretariat of Agriculture biotech approval databases, SENASA phytosanitary export statistics, Buenos Aires province freight rate indices, and crushing margin reports from Rosario commodity exchanges. Bottom-up volume estimates from provincial production surveys were triangulated against top-down export flow data through Bahía Blanca and Rosario port authorities.
Across the analysis window, forecasts reflect segmentation across product type (yellow, white, sweet, popcorn maize), end-use industry (animal feed, biofuel, food processing, starch production), and distribution channel (direct sales, wholesalers, exporters). CAGRs were derived from trend extrapolation of planted area, yield density improvements from biotech trait adoption, and domestic demand growth from provincial ethanol blending mandates. Key inputs included Secretariat of Agriculture approval timelines for stacked-trait varieties and SENASA electronic certification implementation rates.
Decision-makers should treat outputs as directional under assumptions of stable biotech regulatory pathways and no major currency devaluation; material deviation would warrant model refresh. Specific risk factors include Brazilian export competition intensification, drought frequency in western expansion zones, and SENASA inspection capacity constraints during harvest peaks. Revision becomes warranted when Brazilian port logistics investments cross thresholds that permanently displace Argentine market share in Southeast Asia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
South America Rice Market
Grains
Global Cassava Flour Market
Grains
Global Maize Market
Grains
Whole-Wheat Flour Market
Grains
Corn Market
Grains
Mesquite Flour Market
Grains
North America Maize Market
Grains
Wheat Bran Market
Grains
Europe Wheat Protein Market
Grains
China Maize Market
Grains
Oat Bran Market
Grains
Barley Grass Market
Grains
Asia-Pacific Wheat Market
Grains
South Africa Grain Market
Grains
Soya Flour Market
Grains
India Rice Market