
 Europe Herbicide Market | 2026-2036
Europe Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Herbicide Market Insights
Generic herbicide margin pools is narrowing as patent-protected formulations reclaim value. Bayer AG leverages its glyphosate manufacturing scale across German production hubs. BASF SE anchors its position through sulfonylurea chemistry leadership. Syngenta Group competes via integrated seed-and-crop-protection platforms in Southern Europe.
Herbicides are chemical agents formulated to inhibit or destroy unwanted vegetation through metabolic interference, typically applied at rates measured in grams of active ingredient per hectare. Their primary commercial purpose is to protect crop yields by eliminating weed competition for water, nutrients, and sunlight. Glyphosate-based formulations retain the largest volume position, though regulatory pressure is shifting margin pools toward bio-based alternatives. Pre-emergence application methods are gaining traction among cereal crop growers seeking residual weed control. Liquid formulations dominate procurement channels due to ease of tank-mixing and spray application compatibility.
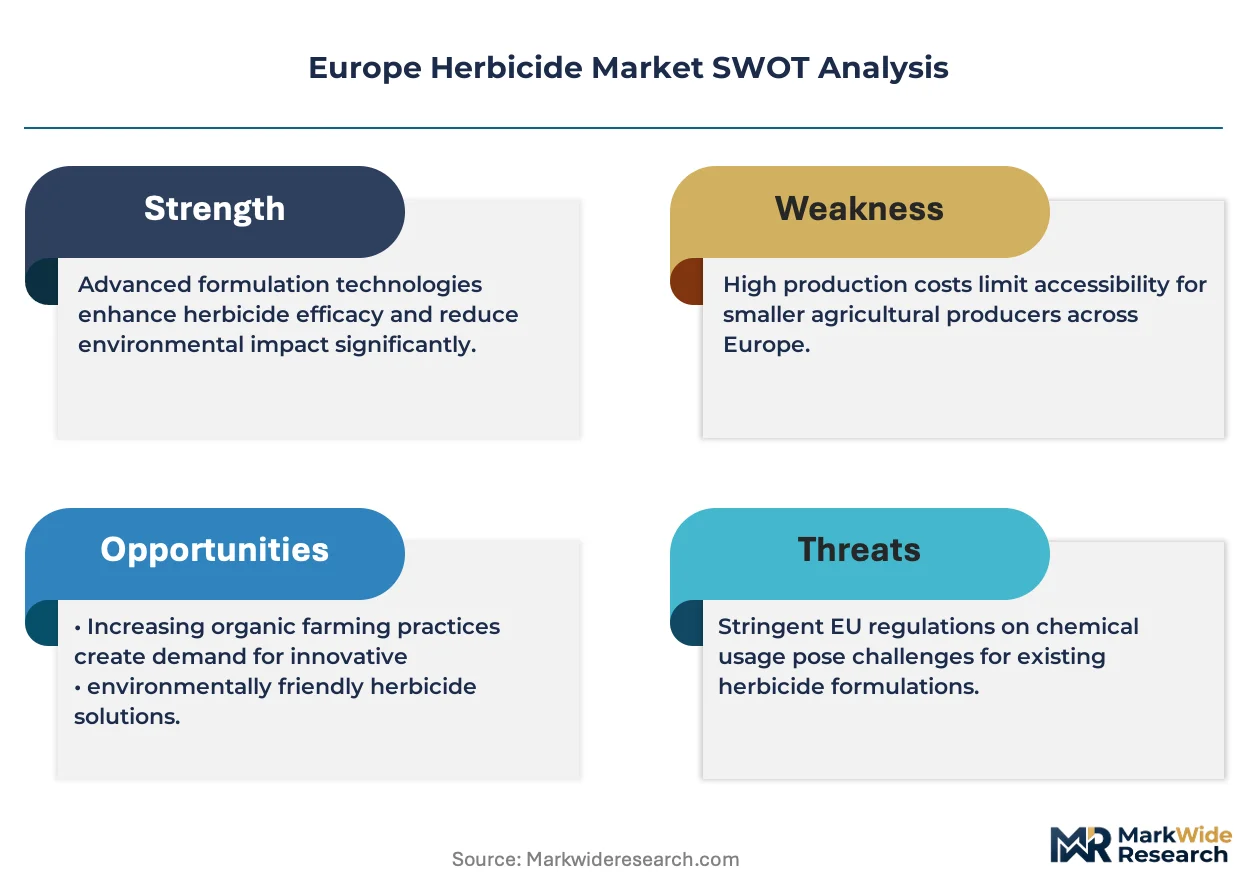
EMA, ECHA, and the EU Green Deal collectively restrict active ingredient approvals and mandate environmental risk assessments for all new herbicide registrations. REACH compliance costs are filtering smaller formulators from the market while favoring integrated multinationals with dedicated regulatory affairs divisions. Stakeholders must monitor the EU's sustainable use of pesticides regulation for upcoming buffer-zone and application-rate mandates that will reshape product portfolios and distribution networks.
Market Dynamics
EU Green Deal mandates are compressing synthetic herbicide approval timelines while redirecting R&D budgets toward bio-based formulations. REACH compliance costs and buffer-zone restrictions are reshaping competitive positioning across the continent.
Growth Catalysts
- Precision agriculture hardware:Variable-rate sprayers equipped with computer vision are enabling site-specific herbicide application in French cereal operations. Adoption reduces input volumes while maintaining efficacy.
- Farm-to-Fork Strategy targets:The EU's pesticide reduction goals are accelerating investment in microbial bioherbicide pipelines. Research consortia in the Netherlands and Denmark are advancing fermentation-based production.
- Specialty crop expansion:Spanish and Italian vegetable producers are expanding selective herbicide programs for high-value crops. These segments command premium pricing relative to commodity grains.
Market Restraints
- Active ingredient cost volatility:Petrochemical feedstock fluctuations are squeezing margins on synthetic auxin production. Formulators lack pricing power to pass through input spikes.
- Regulatory friction from ECHA:Candidate list additions for endocrine-disrupting properties are forcing reformulation of established sulfonylurea products. Re-registration timelines extend 18-36 months.
- Mechanical weeding substitution:Robotic cultivators are displacing pre-emergence applications in organic-certified vineyards. German equipment manufacturers are scaling autonomous hoe platforms.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European arable farming is consolidating faster than precision spraying adoption. Equipment-as-a-service models could accelerate technology diffusion.
- RNA interference biochemistry:Spray-induced gene silencing is converging with drone application systems. Early field trials in Portuguese citrus orchards demonstrate target specificity.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are creating procurement preference for certified low-residue programs. Food processors are vetting supplier chemical inventories.
Industry Challenges
- Formulation chemistry expertise scarcity:European universities are producing fewer graduates with specialized training in adjuvant-surfactant interactions. Recruitment pipelines for industrial formulation roles have narrowed.
- Legacy equipment incompatibility:Bioherbicide suspensions require modified tank-cleaning protocols and nozzle specifications. Farm service providers face retraining costs for application crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Herbicide Market |
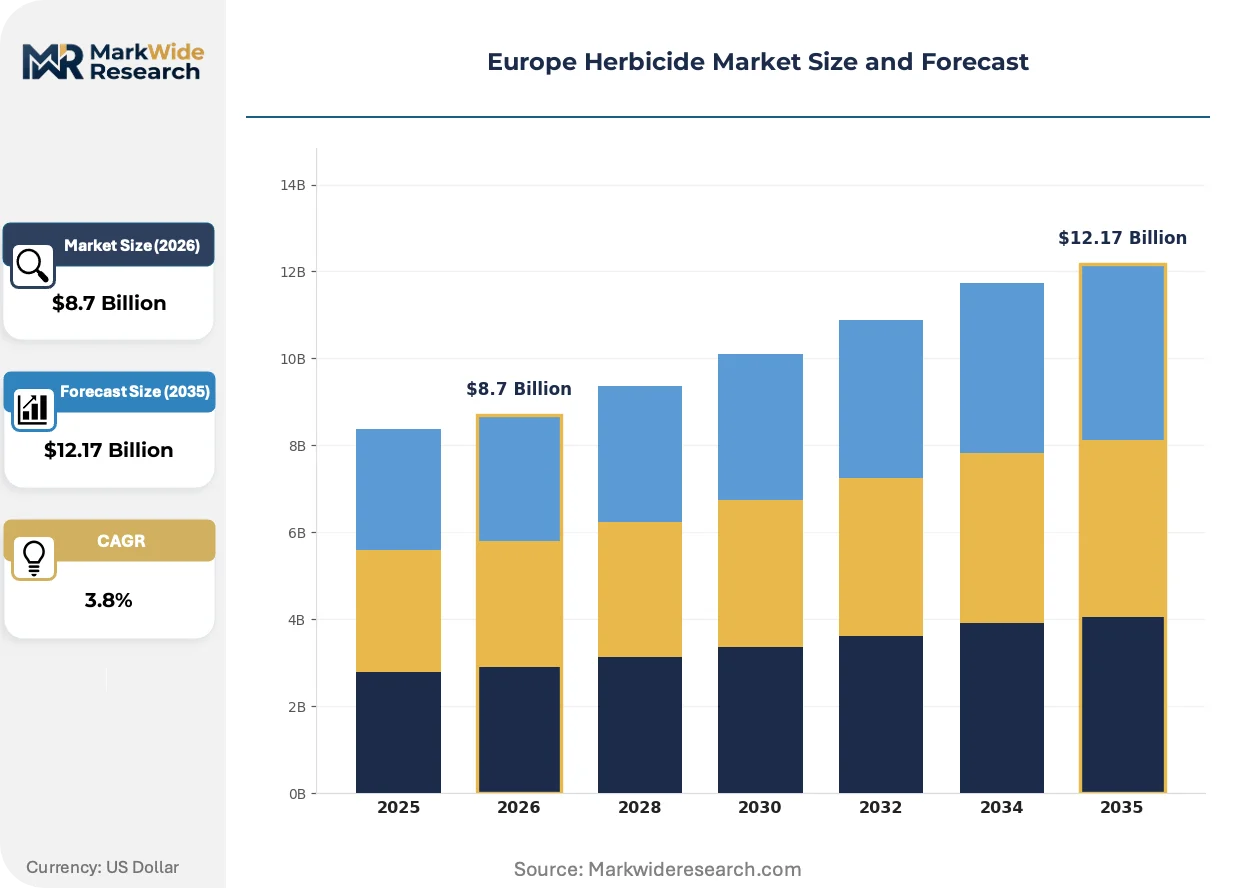
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glyphosate, Atrazine, Sulfonylureas, Dinitroaniline Crop Type: Cereal Crops, Pulses, Fruits, Vegetables Application Method: Pre-emergence, Post-emergence, Soil Treatment, Foliar Application Formulation Type: Liquid, Granular, Emulsifiable Concentrates, Wettable Powder |
| Companies Covered | Bayer AG, BASF SE, Syngenta Group, Corteva Agriscience, FMC Corporation, Nufarm Ltd, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical, UPL Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Herbicide Market Trends and Innovations
Digital sensing technologies and biological discovery platforms are converging to displace calendar-based spraying schedules. Formulation science is advancing toward bio-based actives with synthetic-equivalent field persistence.
Computer vision integrated with unmanned aerial vehicles is digitizing weed detection workflows across German sugar beet operations. Growers are adopting real-time prescription maps that adjust nozzle output by species density. The technology is digitizing agronomic decision-making that previously relied on field-walking scouts.
REACH authorization requirements for persistent organic pollutants are tightening residue thresholds for aquatic ecosystems. ECHA evaluations are disqualifying several organophosphate candidates from renewal. Southern European rice cultivation faces the steepest compliance burden due to floodplain runoff sensitivity.
Consolidated farm enterprises in France are unbundling application services from product procurement. Large cooperatives are contracting directly with aerial spraying fleets while sourcing chemistry through tender platforms. This behavior is most pronounced in the Paris Basin where operational scale supports dedicated logistics coordination.
Europe Herbicide Market Segmentation
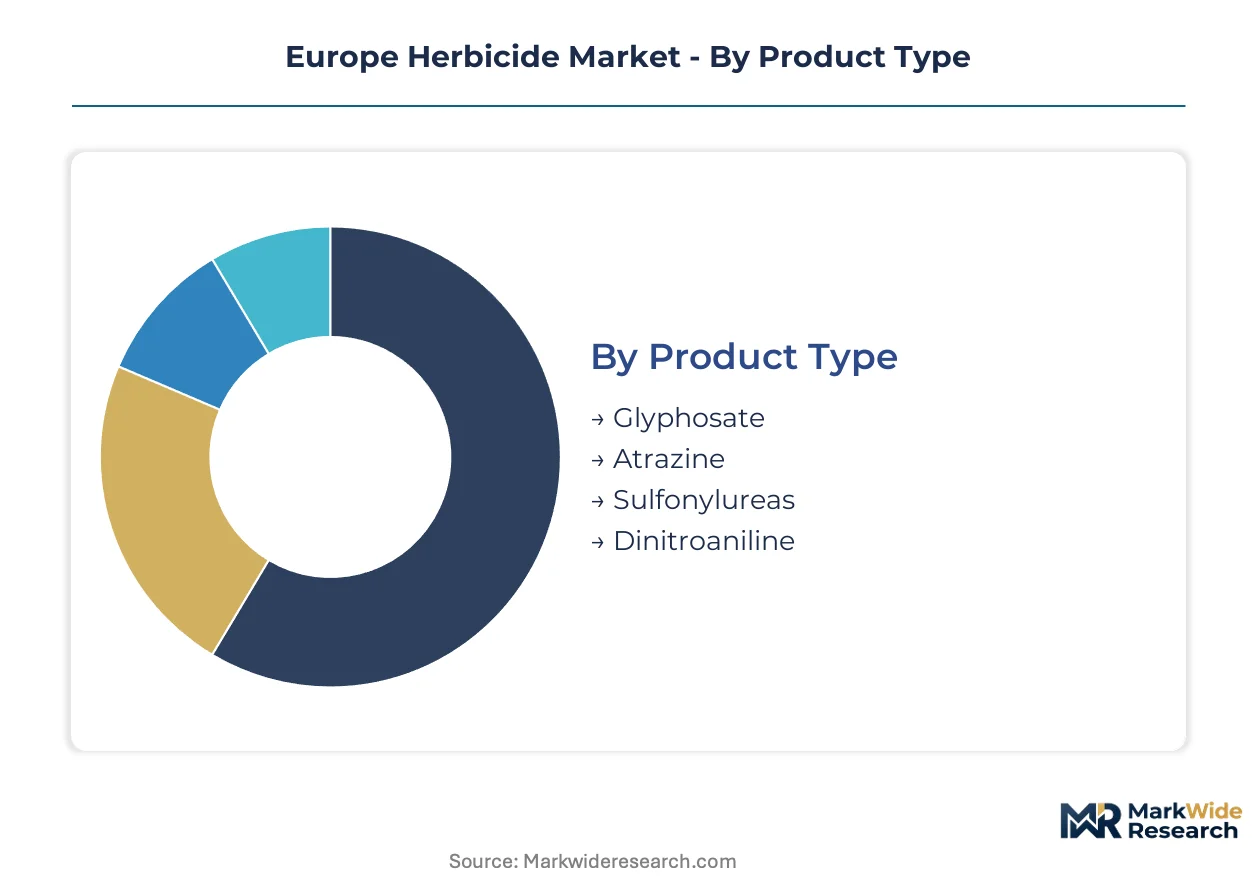
Herbicide procurement patterns diverge sharply across crop systems and application technologies. Formulation chemistry and regulatory compliance costs fragment supplier strategies across European agricultural zones.
Product Type:
Active ingredient selection spans broad-spectrum control agents to specialized selective chemistries, each carrying distinct registration burdens under ECHA evaluation frameworks.
- Glyphosate:Non-selective systemic herbicide with phosphonomethylglycine chemistry disrupts the shikimate pathway in plants. French and German cereal growers deploy it for pre-harvest desiccation despite mounting regulatory pressure from EFSA residue reassessments.
- Sulfonylureas:Acetolactate synthase inhibitors deliver post-emergent control at gram-per-hectare application rates. Spanish specialty crop producers favor these compounds for their crop selectivity and low environmental loading, though ECHA candidate list scrutiny is forcing reformulation investments.
- Atrazine:Triazine herbicide restricted to specific authorizations under REACH persistent organic pollutant thresholds, with declining acreage coverage in maize-growing regions.
- Dinitroaniline:Microtubule-inhibiting pre-emergent chemistry used in Mediterranean vegetable production for residual grass control.
The dominant share belongs to Glyphosate, while Sulfonylureas is closing the gap fastest.
Crop Type:
Volume concentration tracks the arable land distribution across the continent's major agricultural belts.
- Cereal Crops:Wheat and barley cultivation in the Paris Basin and North German Plain generates the largest herbicide consumption volumes, with autumn pre-emergence applications dominating procurement calendars.
- Vegetables:High-value protected cultivation in Italy's Po Valley and Spain's Murcia region commands premium selective chemistries with stricter residue limits under EU maximum residue level regulations.
- Fruits:Vineyard and orchard operations in Bordeaux and Rioja prioritize mechanical weeding alternatives, compressing chemical herbicide acreage.
- Pulses:Pea and lentil rotations in Eastern European crop sequences require specialized legume-tolerant formulations with narrower supplier options.
Cereal Crops absorbs the majority of volume, though Vegetables generates the steepest margin expansion trajectory.
Application Method:
Timing relative to crop and weed emergence determines equipment compatibility and labor scheduling requirements.
- Pre-emergence:Residual chemistry applied before crop germination creates weed-free establishment windows. German sugar beet growers rely heavily on this approach for annual grass management.
- Post-emergence:Targeted application after crop emergence demands precise growth-stage timing. French cooperatives are integrating drone-based spot-spraying to reduce blanket treatment costs.
- Soil Treatment:Incorporation into seedbed preparation addresses persistent perennial weed banks in Dutch bulb cultivation.
- Foliar Application:Contact and systemic uptake through leaf surfaces serves desiccation protocols in Polish cereal harvesting.
Pre-emergence retains the largest installed base, while Post-emergence precision methods are expanding most quickly.
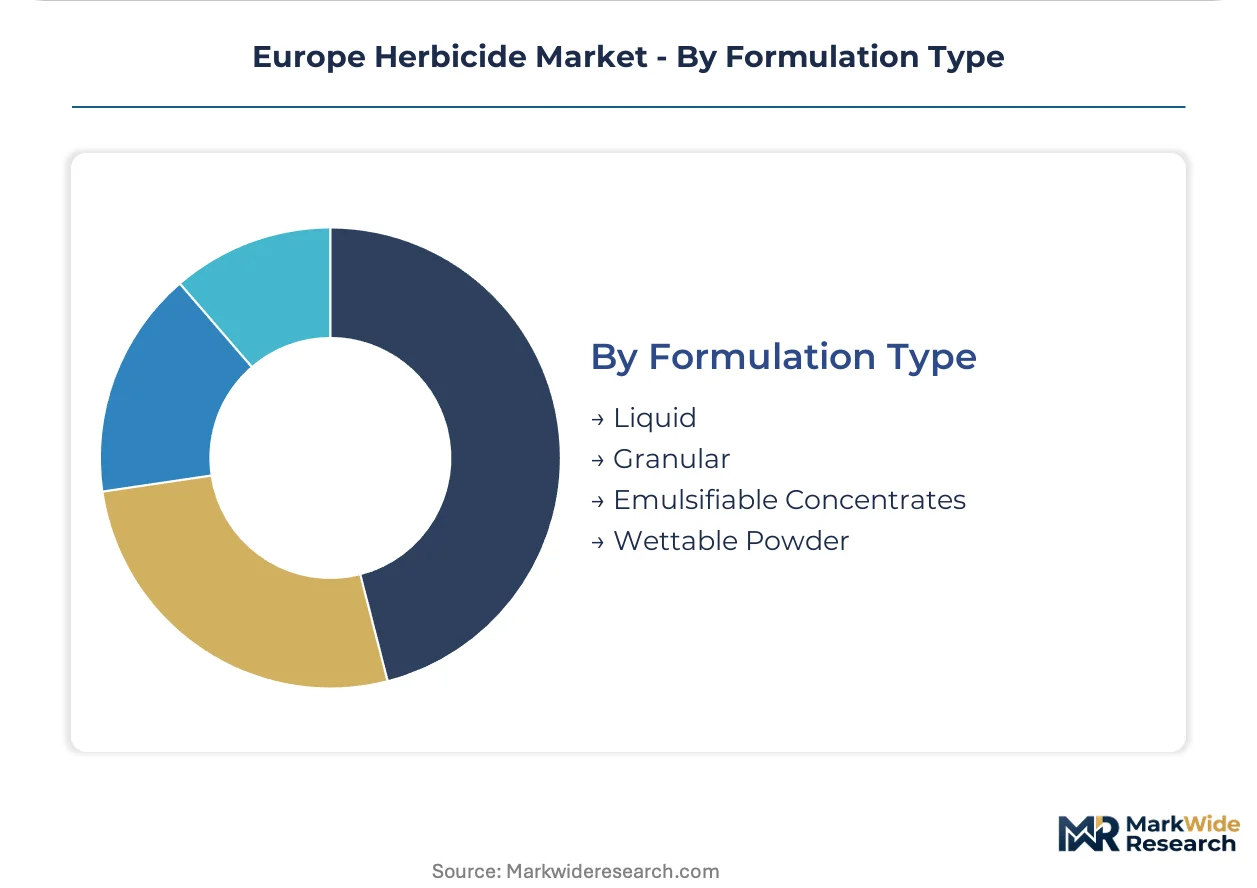
Formulation Type:
Physical form factors govern storage stability, mixing protocols, and drift mitigation profiles under national buffer-zone regulations.
- Liquid:Soluble concentrates and suspension concentrates dominate commercial channels for their tank-mix compatibility and rapid field preparation. Italian distributor networks prioritize liquid SKUs for logistics efficiency.
- Emulsifiable Concentrates:Oil-in-water systems deliver lipophilic active ingredients with enhanced cuticle penetration. Portuguese citrus operators favor these for waxy leaf coverage.
- Granular:Dry broadcast formulations serve rice paddy applications in Southern Europe where aquatic ecosystem restrictions limit spray drift.
- Wettable Powder:Solid dispersible granules retain niche use in organic transition buffers and smallholder equipment configurations.
Liquid formulations command the dominant procurement share, while Emulsifiable Concentrates is gaining share fastest in specialty crop segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Eastern European grain belts contrasts sharply with premium tolerance among Mediterranean specialty crop growers. German and French buyers prioritize precision application economics over per-liter chemistry costs. Southern European vegetable producers absorb higher input prices to secure residue-compliant export certifications.
Germany
Precision spraying hardware adoption drives herbicide demand efficiency in cereal operations across Lower Saxony and Bavaria. The country's Federal Office of Consumer Protection and Food Safety enforces strict buffer-zone mandates under national implementation of EU sustainable use directives. Bayer AG maintains formulation manufacturing concentration in Leverkusen and Monheim production corridors.
France
Consolidated farm cooperatives in the Paris Basin are unbundling application services from chemical procurement. EFSA residue reassessments are compressing glyphosate approval timelines for pre-harvest desiccation protocols. Bordeaux vineyard operators are displacing chemical herbicides with mechanical weeding platforms.
Italy
Protected vegetable cultivation in the Po Valley commands premium selective chemistries with narrow residue windows. REACH compliance costs are filtering smaller formulators from distribution networks in Emilia-Romagna. Syngenta Group competes through integrated seed-and-crop-protection platforms in Southern European specialty segments.
Spain
Murcia region high-value horticulture expansion is accelerating selective herbicide program adoption. The EU Green Deal Farm-to-Fork targets are redirecting R&D investment toward microbial bioherbicide fermentation. Corteva Agriscience maintains market presence through sulfonylurea and auxin chemistry portfolios.
Poland
Arable farm consolidation is outpacing precision spraying technology diffusion across Masovian and Greater Poland voivodeships. ECHA candidate list scrutiny is forcing reformulation of established chemistries with 18-36 month re-registration delays. Equipment-as-a-service models present acceleration opportunities for variable-rate application adoption.
Europe Herbicide Market Competitive Landscape
Capability concentration sits with patent-protected formulation specialists; scale advantage sits with integrated multinationals with captive manufacturing. The market structure tiers between global agrochemical conglomerates and regional distribution-focused formulators. Three archetypes dominate: chemistry innovators with regulatory affairs depth, generic manufacturers competing on cost, and integrated seed-chemistry platform operators. Competitive moves center on bioherbicide pipeline investment and precision agriculture technology partnerships.
Within the integrated multinational tier, Bayer AG and BASF SE exemplify archetypes combining manufacturing scale with regulatory compliance infrastructure. Bayer AG leverages glyphosate production concentration across German hubs. BASF SE anchors positioning through sulfonylurea chemistry leadership. Syngenta Group occupies a platform-integrated position spanning Southern European specialty crop segments. These three entities represent distinct strategic postures: manufacturing scale, chemistry specialization, and seed-crop protection integration.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm Ltd |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine Corridor freight costs for active ingredient shipments from German manufacturing hubs to Italian distributors directly shape margin structures across formulation tiers. Bayer AG and BASF SE leverage captive production capacity to buffer petrochemical feedstock volatility, while smaller formulators absorb logistics surcharges that compress pricing flexibility in generic segments.
Pricing Analysis
After-sales service contracts for precision spraying equipment calibration and nozzle maintenance now drive lifetime value capture beyond initial chemistry sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by operational scale and residue certification requirements. Cost compression in economy-tier glyphosate formulations is intensifying because Chinese generic manufacturers are expanding European registration portfolios. Large French cooperatives exhibit lowest price sensitivity due to unbundled procurement models, while Polish smallholders face acute margin pressure from input cost volatility.
Supply Chain Analysis
Extended payment terms from 60 to 90 days for distributor networks in Southern Europe are straining working capital for mid-tier formulators. Active ingredient production concentrates in Germany, China, and India, with formulation finishing distributed across regional hubs in France, Spain, and Poland. The supply chain draws from petrochemical feedstocks, phosphonomethylglycine intermediates, and sulfonylurea precursors. Single-source vulnerability for glyphosate technical material from Chinese manufacturers creates exposure to tariff and regulatory friction. Distribution runs through agricultural cooperatives and specialized crop protection distributors rather than direct farm sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's herbicide sector sits in early-cycle expansion as precision agriculture hardware penetration in French and German cereal operations creates demand for compatible formulation chemistries. Bioherbicide R&D pipelines are advancing from laboratory to field trial stages, opening new value pools beyond synthetic actives.
For Market Incumbents: Entrench formulation chemistry leadership through captive adjuvant-surfactant production and ECHA regulatory affairs infrastructure. Bayer AG and BASF SE should expand backward integration into bioherbicide fermentation capacity to preempt microbial platform competition. Patent-protected sulfonylurea portfolios require defense against ECHA candidate list reformulation mandates that extend re-registration timelines. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian precision spraying equipment-as-a-service models where arable consolidation outpaces technology adoption. RNA interference biochemistry for specialty crops offers the most penetrable application segment given early Portuguese citrus trial results. Partner with Dutch and Danish research consortia for microbial bioherbicide pipeline access rather than building de novo R&D capabilities. For Investors and Strategic Acquirers: Regional formulators with ECHA registration dossiers and established distributor relationships in Italy and Spain represent priority acquisition targets. Long-term viability hinges on bioherbicide portfolio transition speed relative to EU Green Deal synthetic reduction mandates. Monitor EFSA glyphosate residue reassessment timelines as inflection indicator for generic margin pool compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioherbicide Fermentation | Captures margin from microbial active production as EU Green Deal redirects R&D budgets. |
| Precision Agriculture Technology Partnership | Aligns formulation portfolios with variable-rate sprayer adoption in French cereal operations. |
| ECHA Regulatory Affairs Infrastructure Investment | Accelerates re-registration timelines for sulfonylurea products facing candidate list scrutiny. |
| Equipment-as-a-Service Model Expansion | Accelerates precision spraying diffusion in underpenetrated Eastern European grain belts. |
| CSRD-Compliant Low-Residue Program Certification | Secures procurement preference from food processors vetting supplier chemical inventories. |
Research Methodology
Operator-level perspectives from crop protection distributors, precision agriculture equipment manufacturers, farm cooperative procurement managers, and ECHA regulatory consultants anchored the qualitative base. Secondary validation drew from EU pesticide authorization databases, REACH registration dossiers, Cefic chemical industry reports, and national customs trade data for active ingredient imports. Bottom-up field-level consumption estimates triangulated against top-down manufacturer shipment data across the analysis window.
Scenario-bracketing framed projections across regulatory acceleration and bioherbicide adoption variants. The analytical framework modeled segmentation dimensions spanning active ingredient chemistry, crop system, application timing, and formulation physical form. CAGRs were derived from volume-weighted growth rates across these segments. Forecast inputs incorporated EU sustainable use directive implementation timelines and precision agriculture hardware penetration curves.
Stress conditions across ECHA active ingredient renewal rejection rates, petrochemical feedstock price bands, and bioherbicide field efficacy thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation speed and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Crop Bactericides Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Grain Fumigants Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Europe Fungicide Market
Crop Protection
Organic Pesticides Market
Crop Protection
North America Insecticide Market
Crop Protection
Global Insect Growth Regulators Market