
 Latin America Conveyors Market | 2026-2036
Latin America Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Conveyors Market Foresight
Multi-source procurement among mining and automotive buyers is repositioning vendor relationships across the Latin America Conveyors Market. Metso Corporation leverages its minerals-handling heritage to dominate heavy-duty belt installations in Chilean copper operations. Siemens AG competes through integrated automation architectures that combine conveyor controls with plant-wide digital infrastructure. Daifuku Co. Ltd anchors its regional presence with modular material-handling systems serving Mexican automotive assembly plants.
Conveyors are mechanical handling devices engineered to transport bulk or unit loads along predetermined paths, typically constructed from steel frames with rollers, belts, chains, or screws rated for specific load capacities and throughput speeds measured in tons per hour or units per minute. Their primary industrial purpose centers on eliminating manual material movement, reducing labor costs, and synchronizing production flow across sequential operations. Belt conveyors sustain the largest installed base across Latin American mining corridors due to their efficiency over long distances with heavy bulk loads. Automated technology segments are expanding fastest as Brazilian food processors and Mexican automotive plants retrofit lines for synchronized material flow and reduced touch labor. Roller conveyors occupy mature demand positions in warehousing applications where gravity-fed or powered roller systems handle standardized pallet and carton dimensions.
Brazil's ANVISA mandates sanitary design standards for food-contact conveyor surfaces, compelling stainless steel construction and clean-in-place compatibility across the Food & Beverage end user segment. Mexico's NOM energy efficiency standards and Chile's SEC electrical safety certifications shape motor and drive system specifications, creating compliance barriers for non-certified equipment imports. Stakeholders must monitor evolving Mercosur technical regulations and country-level customs procedures that increasingly tie duty preferences to local content thresholds in conveyor system procurement.
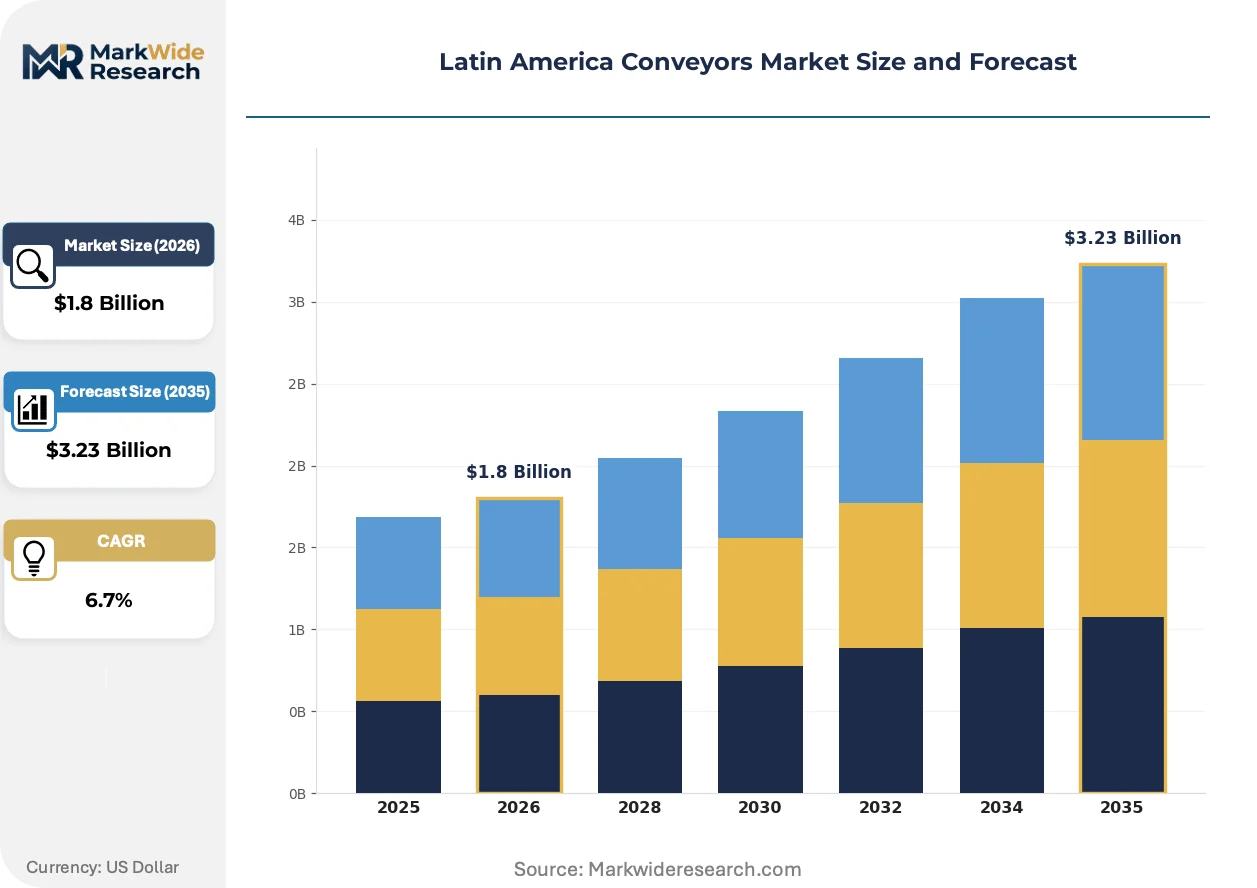
Market Dynamics
Mining automation mandates and ANVISA sanitary compliance are restructuring procurement priorities across Latin American conveyor buyers, forcing vendors to reconfigure product portfolios around certified stainless steel systems and integrated digital controls.
Growth Catalysts
- Chilean copper expansion:State-backed mining investments in the Atacama Desert are driving demand for heavy-duty overland belt systems capable of moving ore across extreme elevation changes.
- ANVISA sanitary mandates:Brazil's food-contact equipment regulations now require clean-in-place compatible conveyor surfaces, compelling processors to replace legacy painted-steel installations.
- Mexican automotive integration:Assembly plants in Querétaro and Guanajuato are retrofitting lines with synchronized roller and chain conveyor networks to match just-in-sequence supplier delivery windows.
Market Restraints
- Steel price volatility:Fluctuations in global hot-rolled coil prices directly compress margins for frame and roller manufacturers operating on fixed project bids.
- Drive component import dependence:Precision gearmotors and variable frequency drives concentrate supply from German and Japanese sources, exposing buyers to currency risk and extended lead times.
- SEC electrical certification delays:Chile's safety compliance testing creates six-to-nine month approval bottlenecks for non-standard motor configurations.
Strategic Opportunities
- Peruvian mining greenfield projects:Untapped copper deposits in the Apurímac region offer first-mover positioning for bulk material handling system providers.
- Colombian port modernization:Pacific coast container terminal expansions require high-capacity ship-loading conveyors with dust suppression systems.
- Mercosur local content incentives:Duty preference thresholds for regional value-added components reward assembly operations in Argentina and Brazil.
Industry Challenges
- Automation engineering scarcity:Mexican and Brazilian plants report acute shortages of technicians capable of programming PLC-based conveyor synchronization with plant MES systems.
- Legacy mechanical integration:Retrofitting variable-speed drives onto existing fixed-speed roller conveyors demands custom mechanical adapters that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Conveyors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyors, Belt Conveyors, Chain Conveyors, Screw Conveyors End User: Food & Beverage, Pharmaceuticals, Automotive, Warehousing Technology: Automated, Manual, Semi-Automated, Modular Application: Assembly Line, Packaging, Shipping, Material Handling |
| Companies Covered | Dorner Mfg. Corp., Metso Corporation, Daifuku Co. Ltd, Honeywell International Inc., Siemens AG, SSI Schaefer AG, BEUMER Group, Correias Mercúrio, Mecalux SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Conveyors Market Shifts & Advancements
Digital predictive maintenance and modular sanitary designs are displacing reactive service models and welded-frame construction across Latin American conveyor procurement. Equipment buyers now prioritize sensor-enabled uptime guarantees over initial capital cost minimization.
Condition monitoring systems with vibration analysis and thermal imaging sensors are overtaking scheduled maintenance contracts in Chilean mining operations. Codelco and Antofagasta Minerals have standardized on IoT-enabled belt health monitoring that flags splice degradation before catastrophic failure. This technology is compressing aftermarket service revenue into upfront platform subscriptions.
Brazil's ANVISA Resolution RDC 275 now mandates documented surface roughness standards for food-contact conveyor belts. Processors must validate cleanability through standardized soil challenge testing, forcing belt suppliers to certify materials at third-party laboratories. The dairy and ready-to-eat meat segments have responded fastest, with São Paulo-based cooperatives leading compliance adoption.
Automotive tier-one suppliers in Mexico's Bajío region now specify conveyor-as-a-service arrangements with guaranteed throughput uptime rather than capital purchases. This unbundles equipment ownership from operational responsibility, shifting balance sheet treatment and vendor risk allocation. German and Japanese automotive parent companies have exported this procurement template from their domestic operations.
Latin America Conveyors Market Segmentation
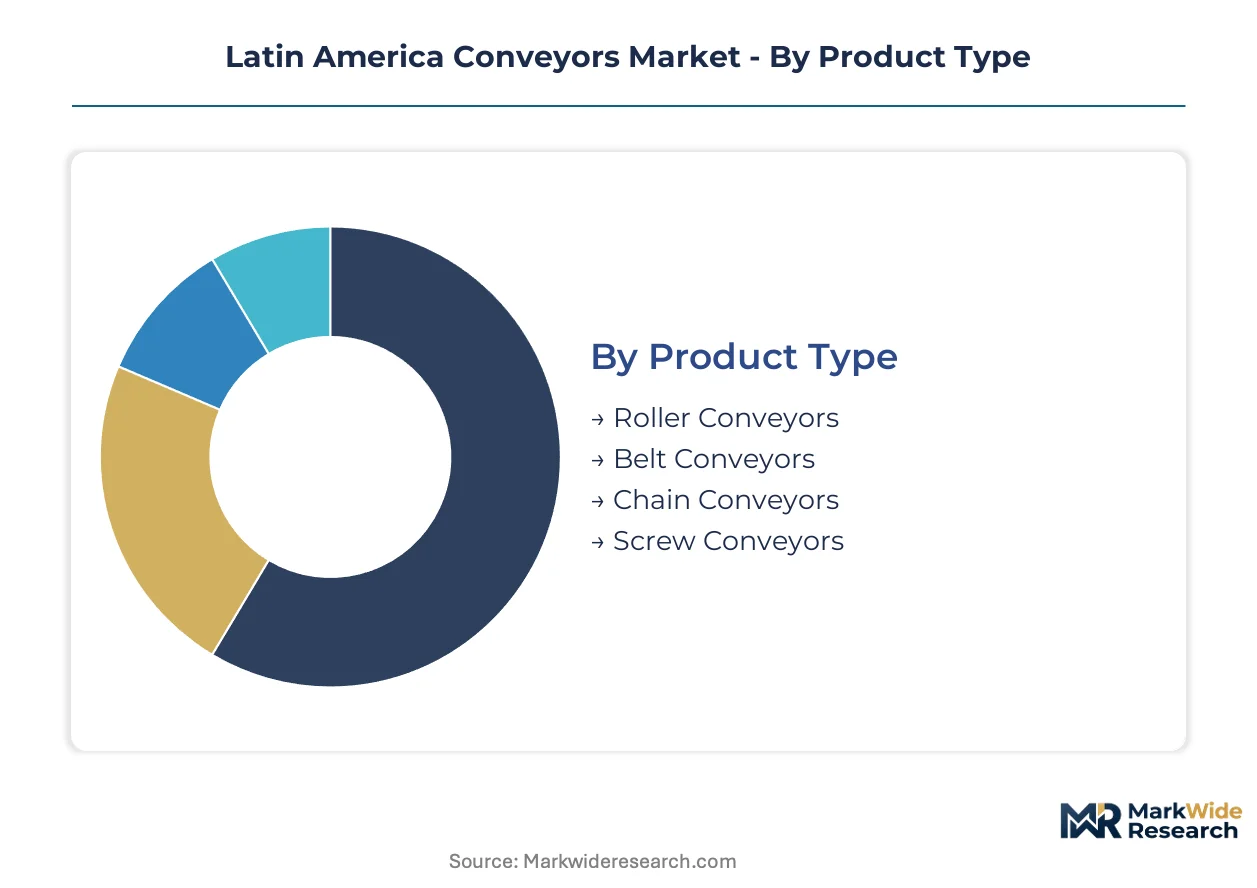
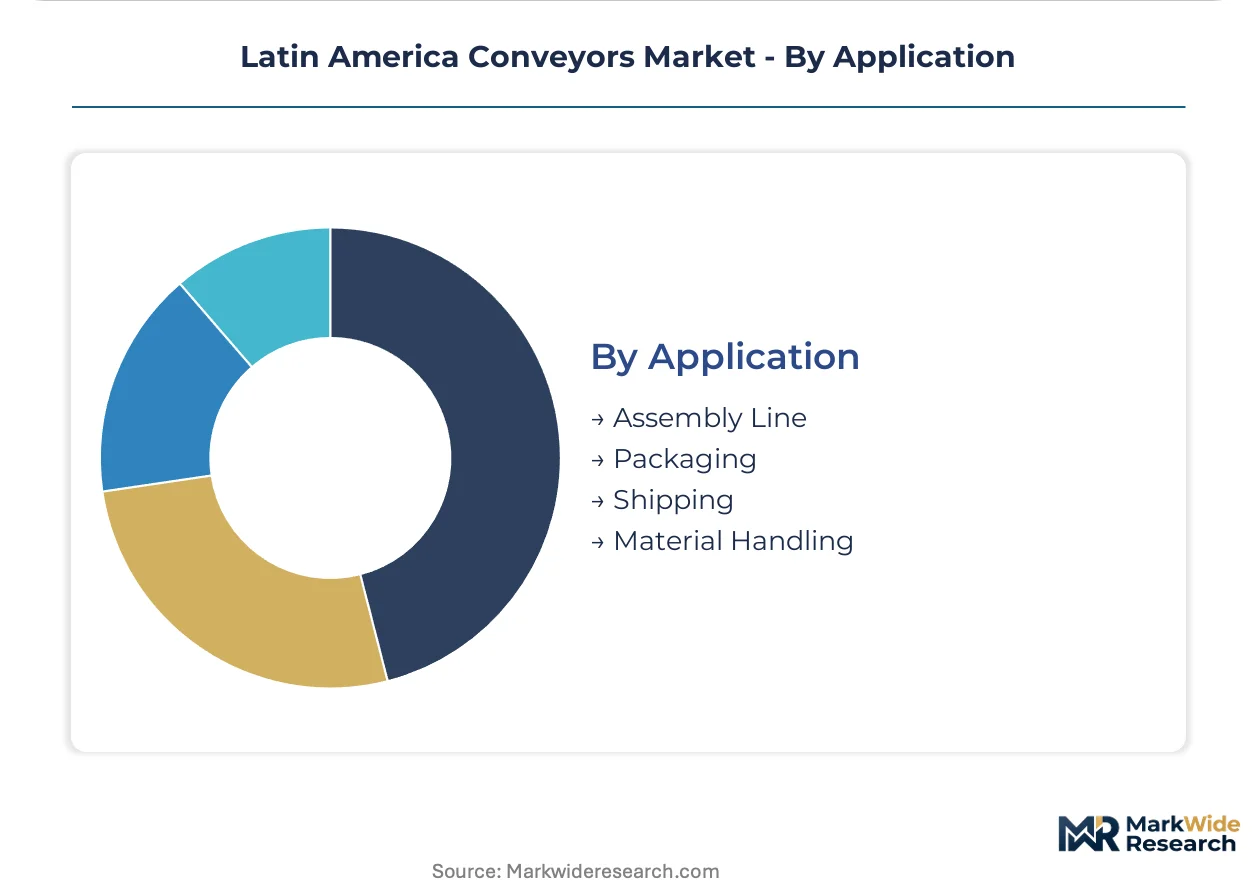
Conveyor procurement across Latin America fragments sharply by operational intensity and regulatory exposure. Mining corridors demand ruggedized bulk-handling architectures while automotive and food plants prioritize precision synchronization and sanitary compliance.
Product Type:
Steel-frame construction and drive mechanism specifications define performance ceilings across Chilean copper belts and Brazilian protein processing halls.
- Belt Conveyors:Fabric-reinforced rubber or steel-cord belts span extreme distances with minimal elevation loss. Chilean state mining investments in the Atacama Desert specify these systems for ore transport across 10+ kilometer corridors with 1,000-meter vertical drops.
- Roller Conveyors:Gravity-fed or powered roller arrays handle standardized pallet and carton dimensions in Mexican automotive supplier parks. Querétaro assembly plants retrofit these with variable-frequency drives to match just-in-sequence delivery windows from tier-one suppliers.
- Chain Conveyors:Engineered steel or plastic chain configurations manage heavy unit loads and accumulation zones in automotive body shops.
- Screw Conveyors:Helical flighting within enclosed troughs moves semi-fluid bulk materials in grain handling and cement plants.
Mature deployment sits with Roller Conveyors in warehousing and distribution. Newer deployment is concentrated in Belt Conveyors as Peruvian and Chilean greenfield mining projects commission overland systems.
End User:
Regulatory stringency and automation maturity create divergent procurement patterns across sectoral buyers.
- Automotive:Assembly plants in Guanajuato and Querétaro specify synchronized roller and chain networks with PLC integration to plant MES systems. Parent companies from Germany and Japan have exported conveyor-as-a-service procurement templates that unbundle ownership from operational responsibility.
- Food & Beverage:ANVISA Resolution RDC 275 mandates documented surface roughness standards and clean-in-place compatibility. São Paulo dairy cooperatives lead compliance adoption, replacing legacy painted-steel installations with stainless steel modular systems.
- Pharmaceuticals:Containment and washdown requirements drive specification of sealed bearings and crevice-free construction in Brazilian sterile manufacturing.
- Warehousing:Gravity-fed roller systems dominate e-commerce fulfillment centers where standardized carton dimensions permit minimal-touch sorting.
Pharmaceuticals and Food & Beverage segments are expanding most quickly on regulatory retrofit cycles. Automotive maintains the largest installed base of automated conveyor networks.
Technology:
Control architecture sophistication determines labor substitution potential and integration depth with plant digital infrastructure.
- Automated:Sensor-enabled belt health monitoring with vibration analysis and thermal imaging now standard in Chilean mining. Codelco operations compress aftermarket service into upfront platform subscriptions through IoT-enabled predictive maintenance.
- Semi-Automated:Variable-speed drives retrofitted onto fixed-speed mechanical systems bridge legacy assets toward digital control without full replacement.
- Manual:Hand-crank or gravity-fed configurations persist in low-throughput agricultural processing where labor costs remain below automation thresholds.
- Modular:Plug-and-play stainless steel sections enable rapid reconfiguration for seasonal product changeovers in Brazilian protein plants.
Manual systems retain share in peripheral agricultural zones. Automated platforms are gaining share fastest in mining and automotive corridors where uptime guarantees dominate procurement criteria.
Application:
Process stage positioning dictates load characteristics, speed requirements, and integration complexity with upstream and downstream equipment.
- Material Handling:Bulk ore movement from pit to port in Chile and Peru defines the heaviest load specifications. Overland systems must sustain continuous operation across seismic zones and extreme temperature differentials.
- Assembly Line:Precision indexing and accumulation control synchronize multi-station operations in Mexican automotive plants. Line balancing requirements specify conveyor speeds matched to takt time calculations.
- Packaging:Sanitary design and quick-release components dominate Brazilian food-contact specifications for primary and secondary packaging operations.
- Shipping:High-capacity ship-loading conveyors with dust suppression systems serve Colombian Pacific coast terminal expansions.
Material Handling commands the deepest automation investment. Assembly Line applications are climbing the fastest on automotive reshoring and supplier park densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean copper deposits and Brazilian iron ore basins anchor conveyor demand across Latin America, with procurement patterns diverging sharply between mining corridors and manufacturing clusters.
Brazil
ANVISA sanitary mandates drive stainless steel modular system replacements in São Paulo dairy cooperatives and Minas Gerais protein processing plants. The Mercosur local content framework rewards regional value-added assembly operations. Rio Grande do Sul's meatpacking corridor leads compliance adoption with documented surface roughness validation.
Mexico
Automotive reshoring from parent companies in Germany and Japan concentrates precision roller and chain conveyor demand in Guanajuato and Querétaro assembly plants. NOM energy efficiency standards shape motor and drive specifications for tier-one supplier parks. The Bajío region's conveyor-as-a-service procurement templates now dominate just-in-sequence integration projects.
Chile
State-backed Codelco and Antofagasta Minerals investments in the Atacama Desert specify heavy-duty overland belt systems across 10+ kilometer ore transport corridors. SEC electrical certification requirements create six-to-nine month approval bottlenecks for non-standard motor configurations. The Calama mining cluster sustains the deepest automation engineering demand for IoT-enabled predictive maintenance platforms.
Peru
Untapped Apurímac copper deposits attract bulk material handling system providers for greenfield pit-to-port installations. The national mining regulator enforces seismic zone construction standards for continuous overland operation. Arequipa's engineering services cluster supports commissioning timelines for extreme elevation change systems.
Colombia
Pacific coast container terminal expansions require high-capacity ship-loading conveyors with integrated dust suppression systems. Port authority modernization programs specify throughput guarantees for bulk mineral export facilities. Buenaventura's logistics corridor anchors procurement for multi-modal material handling integration.
Latin America Conveyors Market Competitive Landscape
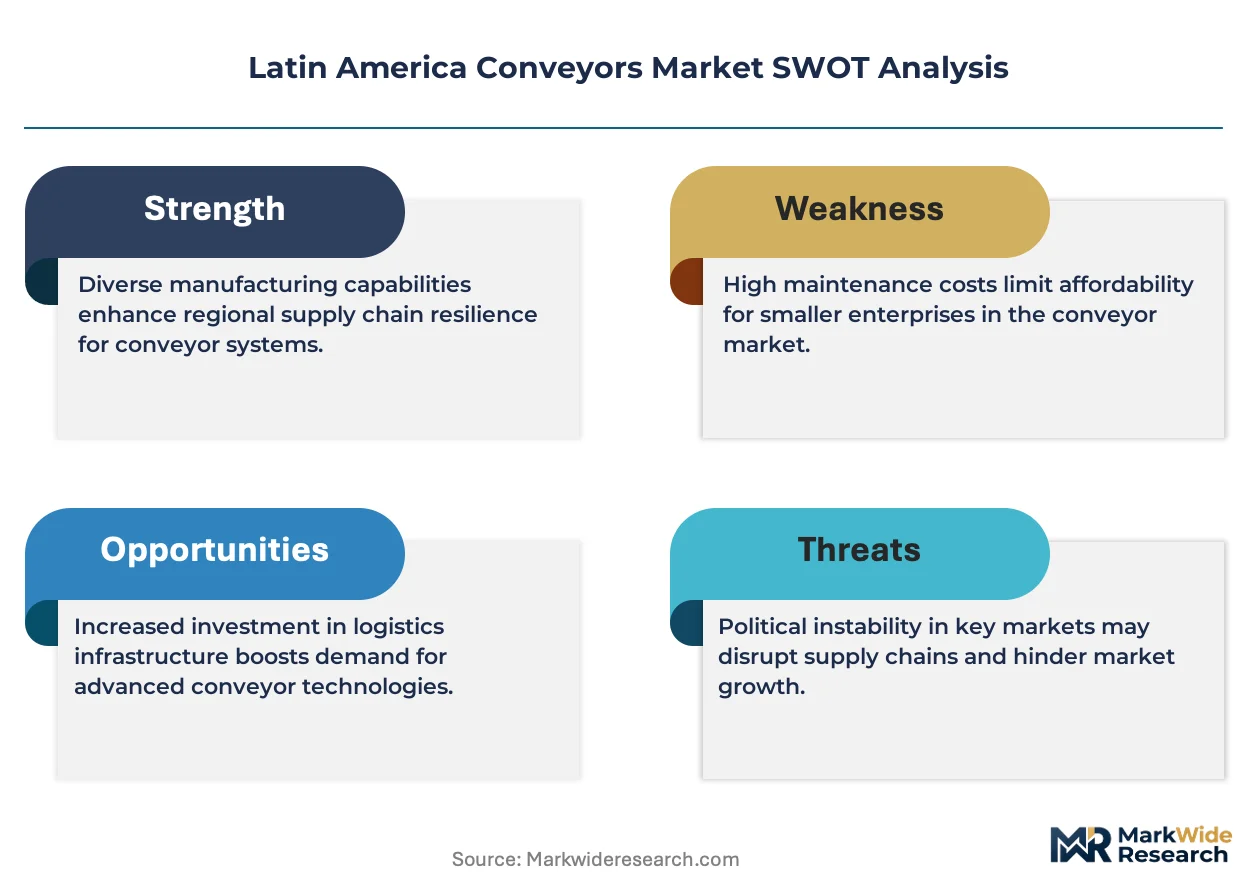
Global majors compete with regional champions across certification compliance and local content thresholds, creating a tiered structure where European and Japanese conglomerates anchor premium automation segments while Brazilian and Mexican fabricators defend mid-market positions. Three archetypes dominate: integrated minerals-handling specialists, modular automation platform providers, and regional belt fabricators with Mercosur duty advantages. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as vendors address ANVISA sanitary mandates and SEC electrical certification requirements.
Among the integrated minerals-handling specialists, Metso Corporation exemplifies the heavy-duty belt installation archetype through its heritage in copper corridor operations. Siemens AG occupies a position within the automation platform tier, representing the control architecture integration archetype that combines conveyor systems with plant-wide digital infrastructure. Daifuku Co. Ltd sits within the modular material-handling segment, anchoring the precision synchronization archetype for automotive assembly applications.
| Leading Market Players |
|---|
| Dorner Mfg. Corp. |
| Metso Corporation |
| Daifuku Co. Ltd |
| Honeywell International Inc. |
| Siemens AG |
| SSI Schaefer AG |
| BEUMER Group |
| Correias Mercúrio |
| Mecalux SA |
| Others |
Supply & Pricing Matrix
Mexican automotive OEM procurement teams concentrate purchasing power for precision roller and chain systems, anchoring project-based pricing with unbundled service contracts that separate equipment capital from commissioning and aftermarket support.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium automation vendors from standard fabricators across Chilean mining corridors. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA certification grade and SEC electrical compliance status. Cost compression in mid-market belt systems intensifies as Brazilian food processors demand stainless steel construction without absorbing full material pass-through. Mining operators show least price sensitivity given uptime guarantee requirements, while warehousing buyers prioritize lowest capital outlay per linear meter.
Supply Chain Analysis
Precision gearmotor supply rests on German and Japanese specialty manufacturers, with VFD controllers drawing from South Korean and Chinese electronics assembly. Hot-rolled steel coil feeds from Brazilian and Mexican integrated mills, while rubber belt compounds hinge on Southeast Asian synthetic polymer producers. Single-source vulnerability in high-torque drive components exposes buyers to currency fluctuation and extended replenishment cycles. Distribution runs through regional system integrators who bundle mechanical installation with PLC programming services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conveyor vendors face a vertical-integration race to capture margin from precision drive components and certified fabrication, with backward integration into motor manufacturing and stainless steel processing emerging as the decisive upstream lever.
For Market Incumbents: Acquire precision gearmotor engineering capabilities to reduce exposure to German and Japanese supply bottlenecks. Secure captive stainless steel fabrication capacity in São Paulo or Minas Gerais to capture Mercosur local content incentives and defend against emerging Brazilian fabricators with duty advantages. ANVISA certification delays for non-standard motor configurations threaten margin compression for vendors without in-house compliance engineering. For New Entrants and Emerging Players: Launch via conveyor-as-a-service arrangements with guaranteed throughput uptime rather than capital sales, targeting Mexican automotive tier-one suppliers in Guanajuato who have adopted this procurement template from German and Japanese parent operations. Peruvian greenfield mining projects in Apurímac offer first-mover positioning for bulk material handling providers without incumbent relationship baggage. Focus initial penetration on semi-automated retrofit systems that bridge legacy fixed-speed assets toward variable-frequency control. For Investors and Strategic Acquirers: The window for entry favors modular automation platform providers with proven PLC-MES integration capabilities and established ANVISA or SEC certification track records. Long-term viability hinges on subscription-based revenue streams displacing transactional equipment sales. Monitor Chilean state mining investment announcements as the primary inflection signal for heavy-duty belt system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Manufacturing | Captures margin from German and Japanese gearmotor suppliers while compressing lead times for Chilean mining projects. |
| ANVISA Certification Pre-Investment | Accelerates Brazilian food processor sales cycles by eliminating third-party laboratory validation bottlenecks. |
| Conveyor-as-a-Service Platform Launch | Aligns with Mexican automotive OEM procurement templates that unbundle ownership from operational responsibility. |
| Peruvian Greenfield Project Partnership | Secures first-mover positioning in Apurímac copper deposits before incumbent minerals-handling specialists establish presence. |
| Predictive Maintenance Subscription Buildout | Compresses aftermarket service revenue into upfront platform subscriptions as demonstrated by Codelco standardization. |
Research Methodology
Trade association filings, customs import records, and SEC regulatory disclosures formed the secondary backbone, cross-referenced against primary interviews with plant engineers at Chilean copper operations, maintenance directors at São Paulo dairy cooperatives, procurement leads at Mexican automotive tier-one suppliers, and aftermarket service heads at Brazilian protein processors. Bottom-up installation counts by conveyor type and length were triangulated against top-down capital expenditure estimates from mining and manufacturing sector reports.
Historical trendline analysis of belt conveyor installations in Atacama Desert corridors and roller conveyor retrofits in Querétaro assembly plants established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-use sector, automation technology tier, and application stage. CAGRs were derived from slope analysis of indexed investment flows, with specific adjustment for ANVISA regulatory retrofit cycles and Chilean state mining program commitments.
The model assumes a particular technology adoption path; alternative pathways for IoT-enabled predictive maintenance platform diffusion would alter the outlook for aftermarket revenue distribution. Forecasts reflect assumptions regarding copper price stability, automotive reshoring momentum, and Brazilian sanitary regulation enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Cable Conduit Market