
 Australia Forklift Rental Market | 2026-2036
Australia Forklift Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Forklift Rental Market Insights
Market Context
AS 2359.1 forklift licensing compliance is unwinding the competitive landscape, elevating barriers for undercapitalized rental providers. Toyota Material Handling Australia leverages its national service network to sustain fleet availability across major capital cities. Coates Hire anchors its position through integrated plant and equipment rental platforms serving construction and resources clients. Kennards Hire competes via dense metropolitan branch networks that reduce equipment mobilization times.
Technical Definition and Segment Structure
Australia forklift rental denotes the short-to-medium-term lease of powered industrial trucks designed to lift, move, and stack materials with load capacities ranging from one to over ten metric tons, primarily serving warehousing, manufacturing, and construction operations where capital expenditure avoidance and fleet flexibility outweigh ownership economics. Electric forklifts now lead product type demand as battery chemistry improvements extend shift durations and eliminate hydrocarbon emissions in enclosed facilities. The 3-5 ton capacity bracket captures the broadest cross-industry application base, while short-term rental durations expand fastest among third-party logistics providers managing seasonal inventory surges.
Regulatory Environment
Safe Work Australia administers the Model Work Health and Safety Regulations, which mandate operator competency verification and equipment inspection protocols that directly shape rental fleet maintenance schedules and documentation requirements. The Australian Competition and Consumer Commission enforces consumer guarantees and unfair contract terms provisions that influence rental agreement structures and liability allocation between lessors and lessees. Stakeholders must monitor evolving carbon disclosure obligations under the National Greenhouse and Energy Reporting scheme, as Scope 3 emissions tracking begins to filter into procurement criteria for large warehousing and retail tenants evaluating rental partners.
Market Dynamics
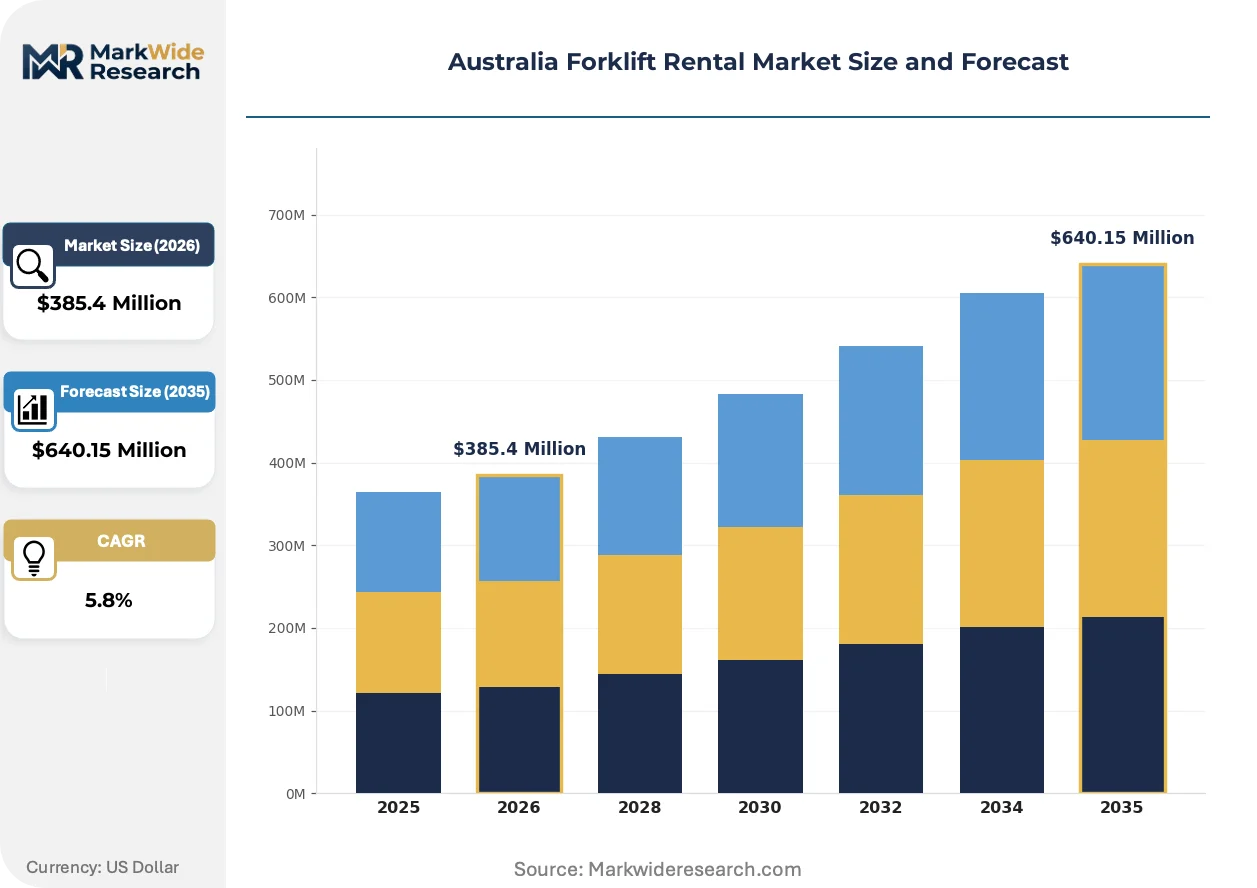
AS 2359.1 certification mandates are compressing the competitive landscape, forcing rental providers to restructure fleet maintenance protocols and operator training programs around Safe Work Australia compliance timelines.
Growth Catalysts
- E-commerce fulfillment peaks:Third-party logistics operators in New South Wales are expanding short-term rental contracts to manage seasonal inventory surges without capital deployment.
- Lithium-ion battery chemistry:Extended shift durations and zero-emission operation in enclosed warehousing facilities are accelerating electric forklift preference over internal combustion units.
- Work Health and Safety Act enforcement:Tightened operator competency verification is redirecting demand toward rental providers with documented maintenance schedules and inspection protocols.
Market Restraints
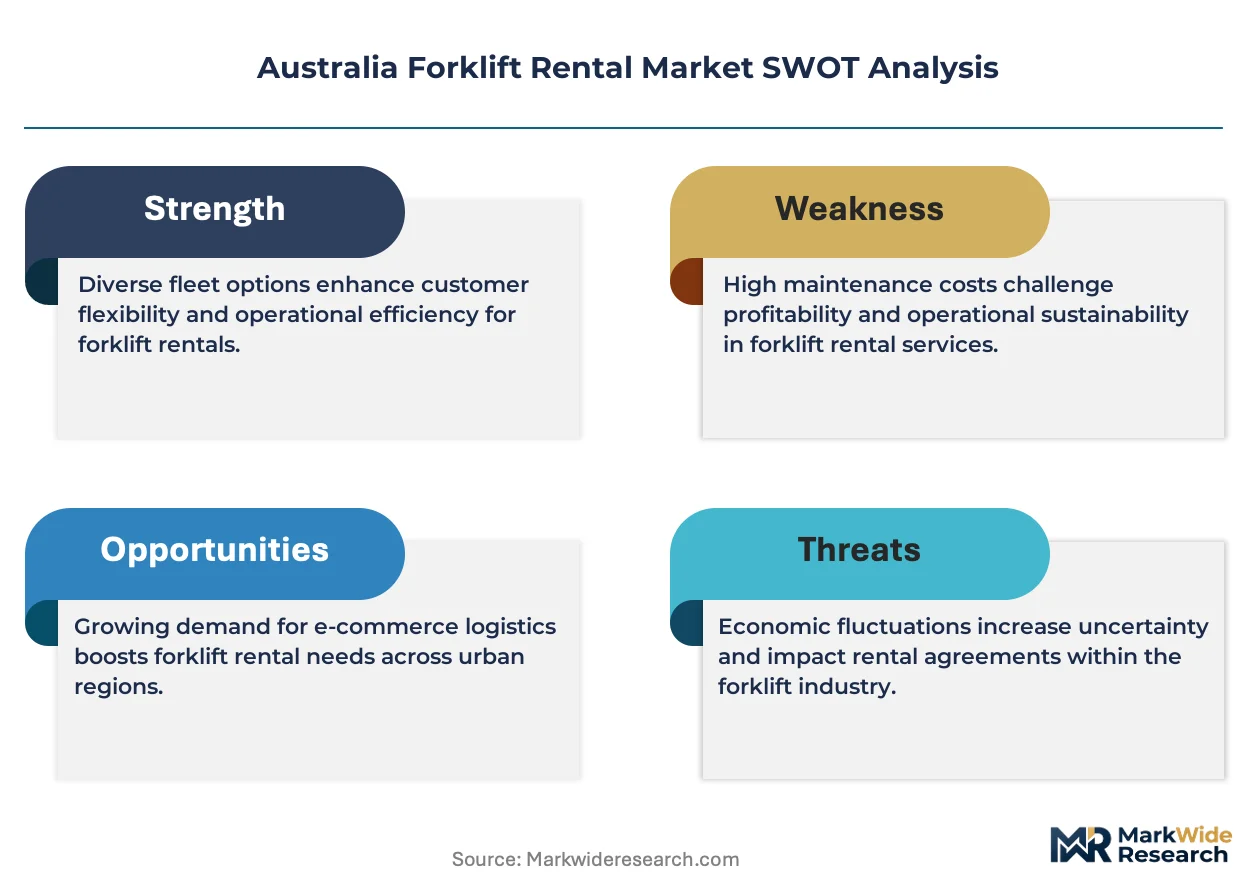
- Steel and battery input volatility:Forklift chassis fabrication and energy storage system costs fluctuate with commodity markets, compressing rental margin predictability.
- Service network concentration:Fleet availability depends on sparse authorized technician coverage outside Sydney, Melbourne, and Brisbane metropolitan corridors.
- Autonomous mobile robot substitution:Warehouse automation vendors are displacing manual forklift operations in greenfield distribution centers with higher throughput requirements.
Strategic Opportunities
- Western Australia resources corridor:Mining and LNG construction projects in the Pilbara region remain underserved by rental fleets optimized for urban warehousing.
- Telematics-ERP convergence:Real-time fleet utilization data integrated with tenant inventory systems enables usage-based billing models.
- National Greenhouse and Energy Reporting tailwind:Scope 3 emissions tracking mandates are elevating electric forklift rental partners in procurement criteria for large retail tenants.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion battery service and thermal management repair skills outpace vocational training pipeline output.
- Multi-site certification coordination:Operators working across state boundaries face inconsistent recognition of competency credentials between jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Forklift Rental Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, IC Engine Forklifts, Reach Trucks, Pallet Jacks End User: Manufacturing, Warehousing, Construction, Retail Capacity: 1-3 Tons, 3-5 Tons, 5-10 Tons, Above 10 Tons Rental Duration: Short-Term, Long-Term, Seasonal, Daily |
| Companies Covered | United Forklift and Access Solutions, Linde Material Handling Australia, Toyota Material Handling Australia, Kennards Hire, Lencrow Forklifts, Crown Equipment, ForkForce Australia, Coates Hire, Adaptalift Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Forklift Rental Market Trends and Innovations
Fleet digitalization and energy transition are restructuring how rental providers compete on availability, pricing transparency, and emissions accountability across Australian logistics corridors.
Lithium-iron-phosphate battery systems are fragmenting the traditional diesel-electric product hierarchy in Australian rental fleets. Cold storage operators in Victoria and Queensland are adopting these units for multi-shift continuous operation without battery swap infrastructure. The technology is fragmenting capital allocation patterns, as providers must choose between retrofitting existing electric fleets or accelerating full fleet replacement cycles.
Safe Work Australia's Model Work Health and Safety Regulations are mandating documented pre-operational inspection protocols with digital record retention. Rental providers must now integrate telematics-based fault logging with operator competency verification systems. Small regional operators lacking integrated compliance platforms face exclusion from tenders issued by national warehousing chains.
Usage-based rental contracts are displacing fixed-term agreements among third-party logistics providers managing volatile e-commerce volumes. Major retail tenants now specify hourly utilization thresholds with automatic rate adjustments rather than minimum commitment periods. This pattern concentrates in Sydney's Port Botany logistics corridor, where seasonal demand swings exceed forty percent between peak and trough months.
Australia Forklift Rental Market Segmentation
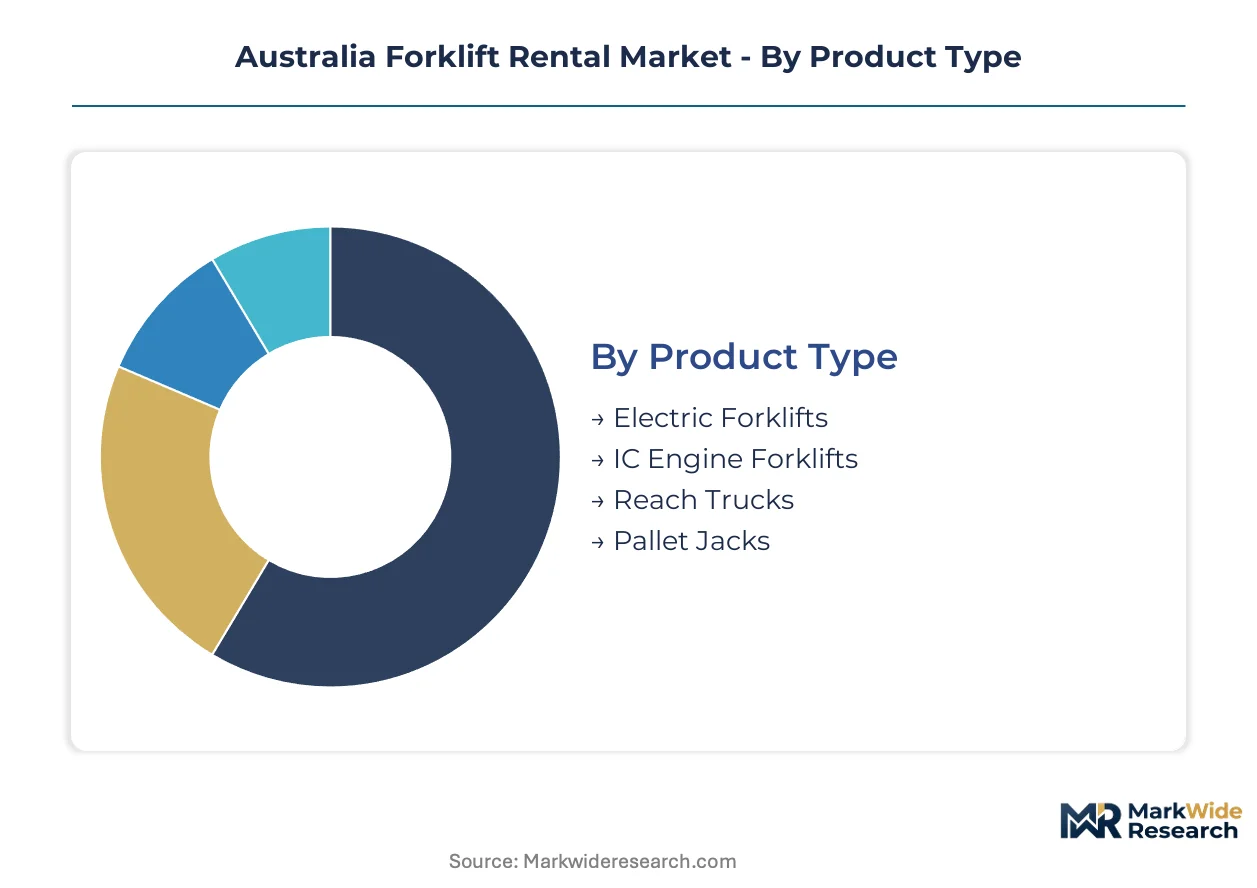
Forklift rental segmentation in Australia tracks how capital avoidance preferences and operational constraints reshape equipment procurement patterns across distinct operational contexts. Channel mix varies sharply by segment, with electric units and short-term contracts flowing through metropolitan branch networks while heavy-capacity diesel units mobilize through project-based construction channels.
Product Type:
Metropolitan rental branches push electric and reach truck volumes through warehousing channels, while IC engine units and pallet jacks concentrate in construction and retail spot-hire networks.
- Electric Forklifts:Lithium-iron-phosphate battery systems power these zero-emission units for multi-shift continuous operation in enclosed facilities. Demand concentrates in Sydney's Port Botany corridor and Melbourne's west where cold storage operators face Safe Work Australia ventilation compliance pressures. AS 2359.1 inspection documentation requirements favor rental providers with integrated telematics platforms.
- IC Engine Forklifts:Diesel and LPG combustion engines deliver torque for outdoor yard operations and heavy-load intermittent use. Western Australia mining contractors and Queensland construction projects drive demand where charging infrastructure is absent and load weights exceed electric unit ratings. Service network coverage outside capital cities constrains availability.
- Reach Trucks:Narrow-aisle mast designs maximize vertical storage density in high-rack distribution centers. National retail chains specify these for automated warehouse fitouts.
- Pallet Jacks:Manual and electric walk-behind units handle last-meter pallet movement in retail backrooms and small warehousing operations. Kennards Hire's metropolitan density captures this spot-hire volume.
By volume, IC engine units still lead in rental fleet composition. By growth pace, electric forklifts are climbing the fastest as battery chemistry extends shift durations.
End User:
Cost tier differentiation separates capital-intensive manufacturing contracts from margin-compressed retail spot-hire, with warehousing and construction occupying intermediate positions on contract duration and service bundling.
- Manufacturing:Continuous production lines demand reliable fleet availability with preventive maintenance schedules and rapid breakdown response. Toyota Material Handling Australia's national service network secures these multi-year agreements. Victorian automotive suppliers and New South Wales food processors prioritize uptime guarantees over rate minimization.
- Warehousing:Third-party logistics operators manage seasonal e-commerce surges through flexible rental terms. Sydney's Port Botany corridor hosts the densest concentration of short-term contracts with automatic rate adjustment clauses tied to hourly utilization thresholds.
- Construction:Project-based demand fluctuates with civil engineering and commercial building cycles. Coates Hire's integrated plant rental platform bundles forklifts with excavators and aerial work platforms.
- Retail:Store-level backroom operations generate fragmented, short-duration demand for pallet jacks and small-capacity units. Dense metropolitan branch networks reduce mobilization costs for these low-margin transactions.
Manufacturing commands the highest contract values per unit. Warehousing shows the steepest expansion trajectory as e-commerce fulfillment peaks intensify.
Capacity:
Application requirements and site constraints segment the market across load weight thresholds, with mid-range capacities capturing cross-industry standardization benefits.
- 3-5 Tons:This bracket serves general-purpose material handling across manufacturing floors, distribution centers, and commercial construction sites. Standardized mast configurations and attachment compatibility reduce operator training costs. New South Wales warehousing operators and Victorian manufacturers specify this range for fleet flexibility.
- 1-3 Tons:Compact chassis dimensions navigate confined retail backrooms and light manufacturing assembly areas. Queensland food processors and Sydney metropolitan logistics operators favor these for maneuverability in legacy facilities with narrow aisles.
- 5-10 Tons:Heavy-duty applications in steel distribution, port operations, and mining support services require reinforced masts and stability systems. Western Australia resources projects and Port Botany container handling drive demand.
- Above 10 Tons:Specialized heavy-lift operations in LNG construction, mining maintenance, and infrastructure projects require custom engineering and escorted transport. Limited rental fleet availability concentrates supply with national providers.
3-5 ton units dominate rental transaction volume. Above 10 ton capacity is gaining share fastest as resources sector capital projects resume.
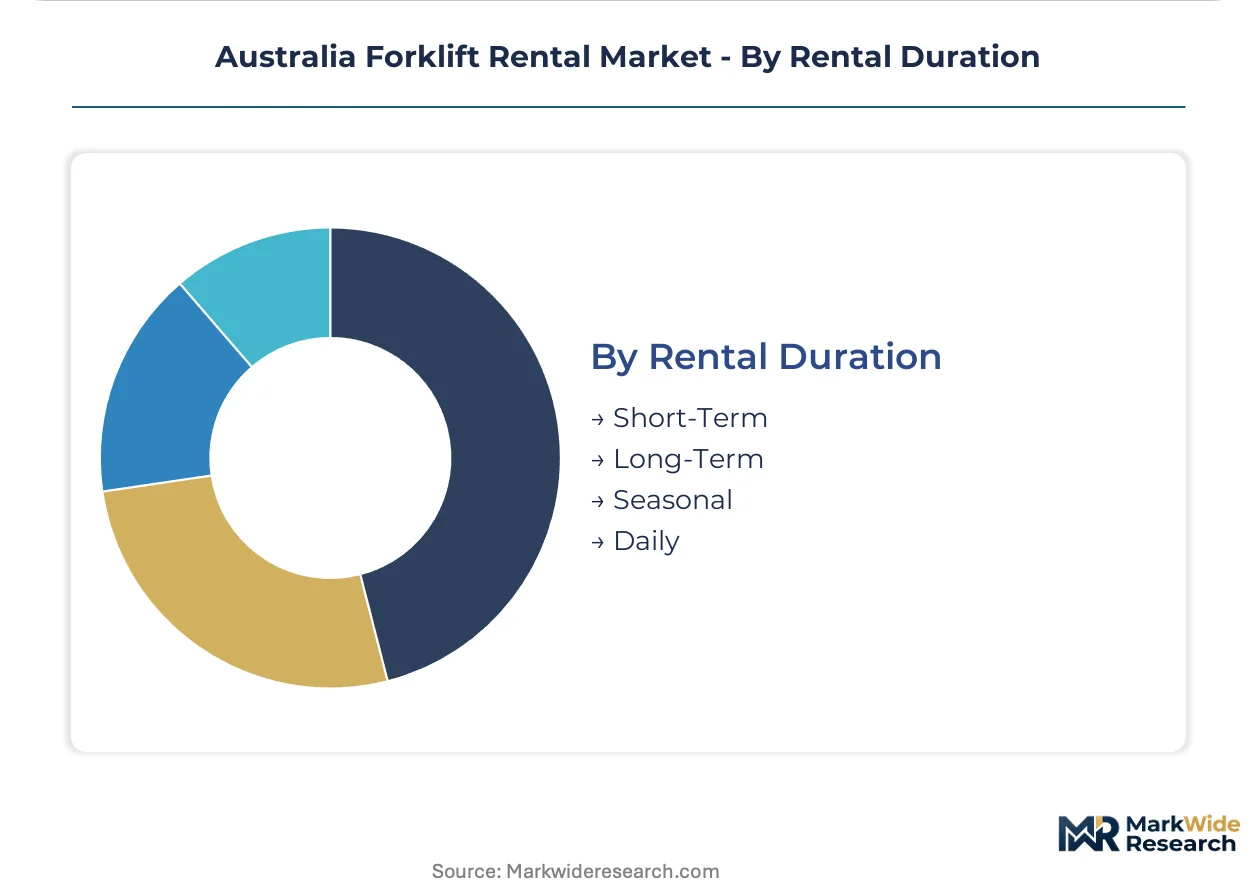
Rental Duration:
Customer type and demand predictability determine contract structure, with seasonal and daily terms expanding among volatile e-commerce logistics operators.
- Short-Term:Contracts spanning one week to three months accommodate inventory surges, equipment failure coverage, and project ramp-up phases. Third-party logistics providers in Sydney and Melbourne specify these for e-commerce peak seasons with forty percent demand swings between trough and peak months.
- Long-Term:Multi-year agreements with fixed monthly rates suit manufacturing operations with stable throughput. Toyota Material Handling Australia and Coates Hire compete on service response time and fleet refresh commitments.
- Seasonal:Pre-negotiated peak-season access rights with guaranteed availability premiums. Retail distribution centers specify these for November-January fulfillment surges.
- Daily:Spot-hire for emergency replacement and unplanned demand spikes. Dense metropolitan branch networks capture this transactional volume.
Long-term contracts generate the largest revenue share. Short-term duration is expanding most quickly as logistics operators prioritize capital flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warehouse operators and construction contractors drive rental demand across Australia's eastern seaboard, while resources projects in the west create specialized heavy-lift requirements. State-level Work Health and Safety Act enforcement varies in timing and inspection intensity.
New South Wales
Port Botany logistics corridors host Australia's densest concentration of third-party logistics warehousing. Safe Work NSW enforces operator competency verification with documented inspection protocols. Sydney's west and Wollongong industrial zones absorb short-term rental spikes during November-January e-commerce peaks.
Victoria
Food processing and automotive component manufacturing sustain multi-year rental agreements with uptime guarantees. WorkSafe Victoria mandates pre-operational digital record retention for fleet maintenance. Melbourne's west and Geelong logistics parks favor electric units for cold storage compliance with ventilation standards.
Queensland
Construction activity and retail distribution centers generate fragmented spot-hire demand for compact units. Workplace Health and Safety Queensland coordinates cross-border operator credential recognition. Brisbane's south and Gold Coast warehousing corridors adopt lithium-iron-phosphate systems for tropical climate durability.
Western Australia
Mining maintenance and LNG construction projects require above-ten-ton capacity with escorted transport logistics. WorkSafe WA inspection schedules align with remote site access windows. Pilbara resources corridors and Kwinana industrial zone remain underserved by rental fleets optimized for urban warehousing.
Queensland
Regional logistics operators face sparse authorized technician coverage outside metropolitan cores. The state's electrical safety regulator monitors high-voltage battery service compliance. Townsville and Cairns distribution hubs experience seasonal agricultural export surges that strain local rental availability.
Australia Forklift Rental Market Competitive Landscape
Player mix skews toward national equipment rental platforms with integrated service networks. Three provider archetypes dominate: metropolitan branch networks optimized for rapid mobilization, national service platforms bundling forklifts with broader plant fleets, and specialized material handling dealers focusing on long-term manufacturing contracts. Competitive positioning hardens around M&A consolidation of regional operators and telematics integration into tenant ERP systems.
Among national-scale rental platforms, Toyota Material Handling Australia, Coates Hire, and Kennards Hire occupy distinct positioning vectors. Toyota Material Handling Australia exemplifies the service-network archetype with preventive maintenance capabilities spanning capital cities. Coates Hire anchors the integrated-plant-rental tier, bundling material handling equipment with construction and resources machinery. Kennards Hire represents the metropolitan-density model, compressing mobilization times through branch proximity to urban demand clusters.
| Leading Market Players |
|---|
| United Forklift and Access Solutions |
| Linde Material Handling Australia |
| Toyota Material Handling Australia |
| Kennards Hire |
| Lencrow Forklifts |
| Crown Equipment |
| ForkForce Australia |
| Coates Hire |
| Adaptalift Group |
| Others |
Pricing and Supply Chain Analysis
Short-term utilization-based contracts with automatic rate adjustment clauses lock in both fleet access for third-party logistics operators and revenue visibility for rental providers during Port Botany corridor demand peaks. These structures transfer commodity price volatility risk from lessees to lessors while embedding Safe Work Australia compliance documentation costs into base rates.
Pricing Analysis
Cost-plus contracts indexed to steel and lithium carbonate commodity benchmarks dominate long-term manufacturing agreements. Three-tier pricing structure across premium telematics-integrated, standard maintenance-bundled, and economy spot-hire levels separates Toyota Material Handling Australia's uptime-guaranteed offerings from Kennards Hire's transactional density. Cost compression in the economy tier is intensifying because undercapitalized regional operators discount daily rates to cover fixed branch costs. Retail backroom operators exhibit highest price sensitivity, while Victorian automotive suppliers prioritize service response commitments over rate minimization.
Supply Chain Analysis
Strategic stockpiling of lithium-iron-phosphate battery modules by national rental platforms contrasts with just-in-time chassis fabrication schedules at Toyota Material Handling Australia's assembly facilities. Forklift manufacturing draws from China, Japan, and South Korea for drive motors, controllers, and battery cells. Australian fleet operators face single-source vulnerability in high-voltage technician training pipelines. Distribution runs through metropolitan branch networks for warehousing customers and project-based mobilization logistics for Western Australia resources contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including telematics integration and AS 2359.1 compliance documentation are expanding faster than base rental rates as large warehousing tenants bundle procurement criteria. This shifts competitive advantage toward providers with integrated digital platforms rather than fleet scale alone.
For Market Incumbents: Consolidate regional operators in Queensland and Western Australia to extend authorized technician coverage beyond Sydney-Melbourne-Brisbane corridors. Acquire specialized high-voltage battery service capabilities before vocational training pipeline output catches lithium-ion fleet penetration. Autonomous mobile robot substitution in greenfield distribution centers threatens traditional forklift rental volumes, making vertical integration into telematics-ERP convergence essential for contract retention. For New Entrants and Emerging Players: AS 2359.1 certification fast-track partnerships with Safe Work Australia accredited training bodies enable rapid credential recognition across state boundaries. Target Western Australia Pilbara resources corridor where mining maintenance demand for above-ten-ton capacity exceeds optimized urban warehousing fleet availability. Deploy project-based heavy-lift mobilization capabilities as primary go-to-market angle, bundling escorted transport with equipment rental to differentiate from metropolitan branch competitors. For Investors and Strategic Acquirers: Capital is best deployed toward metropolitan-density specialists with proven short-term rental transaction economics and integrated compliance platforms. Over a five-to-ten year viability window, providers lacking telematics-ERP integration face exclusion from national warehousing chain tenders. Watch for Safe Work Australia enforcement intensity divergence across states as early signal of competitive consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-ERP Platform Integration | Enables usage-based billing models for Port Botany logistics operators managing forty percent seasonal demand swings. |
| Lithium-Iron-Phosphate Fleet Conversion | Captures National Greenhouse and Energy Reporting compliance premiums from large retail tenants tracking Scope 3 emissions. |
| Western Australia Resources Corridor Expansion | Addresses underserved above-ten-ton demand from Pilbara mining maintenance and LNG construction projects. |
| High-Voltage Technician Training Pipeline Investment | Secures service network differentiation as battery chemistry outpaces vocational training output across all states. |
| Metropolitan Branch Network Densification | Compresses mobilization times for retail spot-hire transactions where Kennards Hire currently holds proximity advantage. |
Research Methodology
A standing panel of fleet maintenance directors, third-party logistics procurement managers, Safe Work Australia compliance officers, and OEM aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from Australian Bureau of Statistics capital expenditure surveys, Safe Work Australia incident reporting databases, National Greenhouse and Energy Reporting scheme filings, and customs import records for industrial machinery. Bottom-up rental transaction modeling triangulated against top-down warehousing and construction sector equipment demand estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, capacity bracket, rental duration tier, end-use industry, and state-level regulatory enforcement intensity. CAGRs were derived from fitted trend extrapolation with elasticity adjustments for e-commerce fulfillment peak seasonality. Industry-specific forecast inputs included lithium-ion battery cost curves and Safe Work Australia inspection protocol adoption timelines.
Decision-makers should treat outputs as directional under assumptions of stable Work Health and Safety Act enforcement intensity and continued e-commerce logistics expansion; material deviation in commodity input costs or autonomous mobile robot substitution rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market