
 Global Air Cannon System Market | 2026-2036
Global Air Cannon System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Cannon System Market Analysis
A capital-intensity divergence between large incumbents and regional challengers is rotating competitive dynamics in the air cannon system landscape. Martin Engineering leverages decades of bulk material handling expertise to sustain premium positioning across North American mining corridors. Jost GmbH anchors European demand through specialized foundry and steel mill applications. VAC-U-MAX competes on pneumatic system integration, occupying niche pharmaceutical and food-grade segments where contamination protocols dominate procurement criteria.
An air cannon system is a pressurized discharge device that releases stored compressed air through a fast-acting valve to dislodge bulk material accumulations from vessel walls, chutes, and hoppers, typically operating at tank pressures between 80 and 125 psi with discharge durations under 250 milliseconds. Its primary industrial purpose is to restore mass flow in silos, bunkers, and preheater towers without manual intervention or equipment shutdown. Stationary air cannons dominate installed base value owing to permanent integration into cement kiln preheater systems and coal-fired boiler hoppers, while automated air cannon arrays represent the fastest-expanding technology tier as facilities retrofit PLC-triggered firing sequences to reduce compressed air consumption. Pneumatic technology retains overwhelming share in heavy industrial settings where explosion-proof requirements preclude electric actuation, though hybrid systems combining pneumatic force with electric valve control are gaining traction in food processing plants seeking precise discharge timing.
OSHA combustible dust standards and EPA National Emission Standards for Hazardous Air Pollutants shape product design requirements, forcing manufacturers to certify valve assemblies for high-temperature and abrasive environments. REACH compliance in Europe restricts certain elastomer compounds used in diaphragm seals, redirecting R&D toward fluoroelastomer alternatives with extended service intervals. Stakeholders must monitor how China's GB standards for industrial dust control and India's CEA emission directives recalibrate import certification burdens for non-domestic suppliers.
Market Dynamics
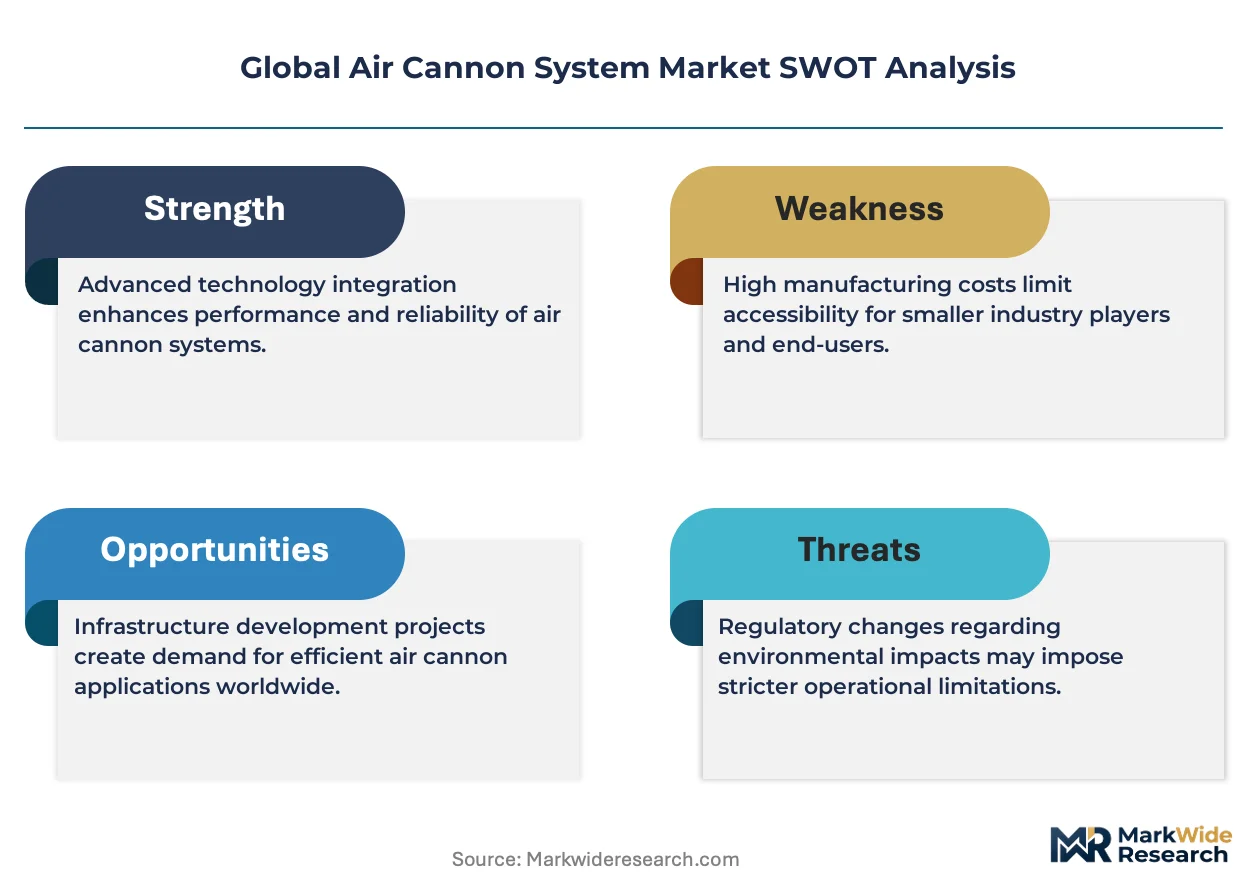
Compressed air infrastructure upgrades across heavy industry are forcing air cannon suppliers to integrate smart valve architectures that cut energy consumption while maintaining discharge force. PLC-triggered firing sequences now displace manual activation in cement and power generation facilities.
Growth Catalysts
- MIIT dust control mandates:China's Ministry of Industry and Information Technology requires industrial particulate upgrades across coal-fired power stations, mandating automated cleaning systems in boiler hoppers and precipitators.
- OSHA combustible dust enforcement:Stricter workplace safety inspections in US grain handling and wood processing plants drive replacement of manual cleaning with remote-activated air cannon arrays.
- Fluoroelastomer diaphragm advances:Extended-service seal materials reduce maintenance intervals in high-temperature cement kiln applications, lowering total cost of ownership for preheater tower installations.
Market Restraints
- Steel tank and valve input costs:Volatility in alloy steel prices compresses margins for fixed-price installation contracts in mining and bulk terminals.
- Compressed air infrastructure dependency:Facilities lacking centralized pneumatic systems face prohibitive retrofit costs, limiting penetration in older food processing and pharmaceutical plants.
- Electric vibration substitutes:Electromechanical shakers gain share in non-explosive environments where installation simplicity outweighs air cannon force advantages.
Strategic Opportunities
- India CEA emission directives:Central Electricity Authority standards for thermal power plant particulate control create certification pathways for imported air cannon systems in ash handling applications.
- Hybrid electric-pneumatic convergence:Integration of electric valve actuation with pneumatic force generation opens food-grade segments requiring precise discharge timing and contamination avoidance.
- Service unbundling models:Component-level diaphragm and valve replacement programs separate hardware from maintenance revenue, penetrating cost-sensitive Southeast Asian cement markets.
Industry Challenges
- Pneumatic technician scarcity:Specialized skills for high-pressure system commissioning and troubleshooting constrain deployment velocity in remote mining corridors.
- REACH elastomer compliance timelines:European Chemicals Agency restrictions on legacy seal compounds force rapid reformulation cycles, extending product certification periods.
- Legacy PLC integration complexity:Retrofitting automated air cannon arrays into existing distributed control systems requires custom programming interfaces, delaying project completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Cannon System Market |
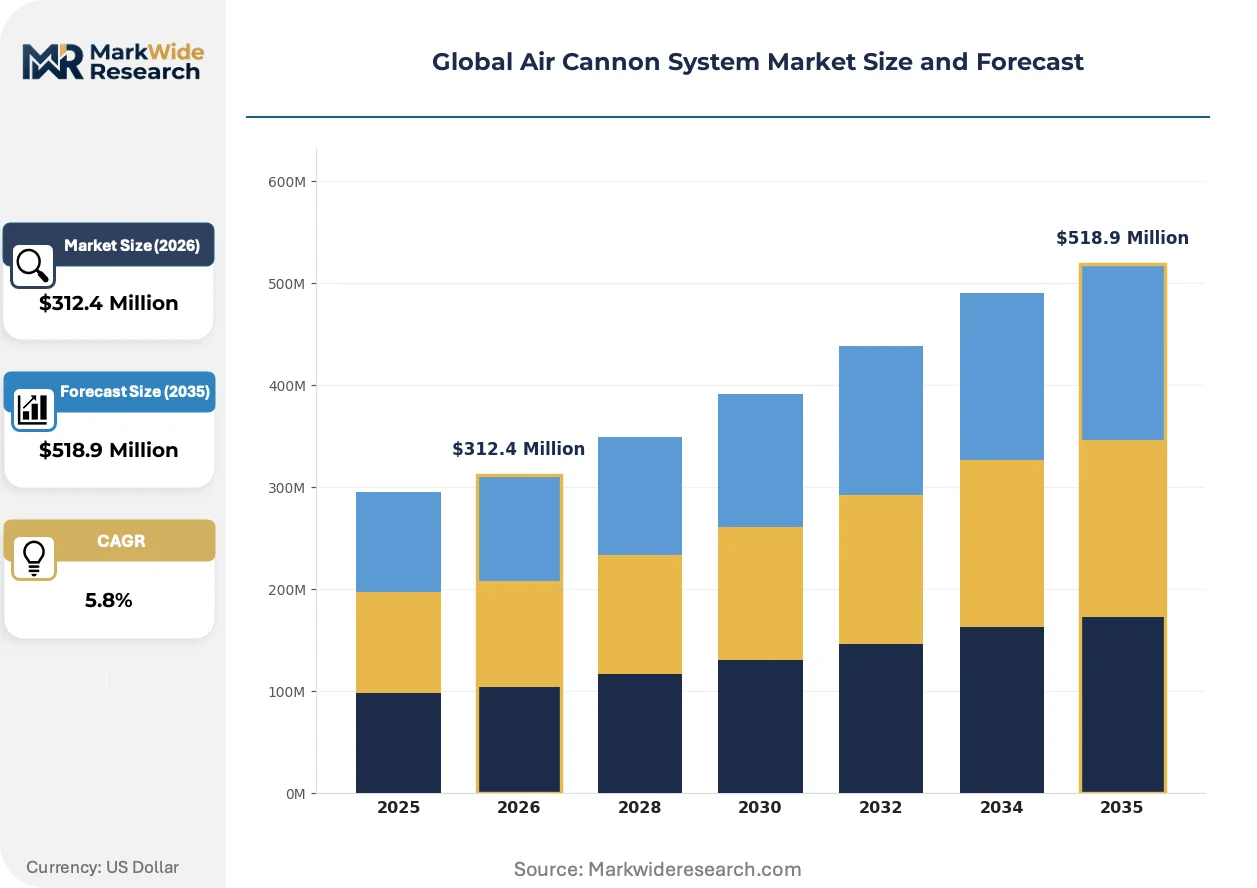
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Air Cannons, Stationary Air Cannons, Custom Air Cannons, Automated Air Cannons End User: Mining, Construction, Agriculture, Food Processing Technology: Pneumatic Technology, Electric Technology, Hybrid Technology, Mechanical Technology Application: Material Handling, Dust Control, Ash Discharge, Bulk Material Flow |
| Companies Covered | FineTek, Fike Corporation, Staminair Corporation, Global Manufacturing Inc, Jost GmbH, Martin Engineering, VAC-U-MAX, Vibco Vibrators, AIRMATIC INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Cannon System Market Emerging Trajectories
Smart actuation and predictive maintenance architectures are displacing fixed-interval service models across heavy industrial air cannon installations. Equipment suppliers now embed pressure sensors and cycle counters to enable condition-based component replacement.
Modular valve architectures are fragmenting the traditional integrated tank design. End-users in cement and steel now specify field-replaceable cartridge valves that slash downtime during diaphragm failure. European foundries lead adoption, driven by REACH-mandated service interval extensions. Component standardization is compressing supplier differentiation while expanding aftermarket parts competition.
EPA National Emission Standards for Hazardous Air Pollutants are forcing design changes in coal combustion residuals handling. Air cannon manufacturers now certify valve assemblies for abrasive fly ash environments above 400°F. US power generators face 2028 compliance deadlines for enhanced particulate capture, accelerating preheater and hopper cleaning system procurement. Equipment specifiers prioritize EPA-validated temperature ratings over generic industrial claims.
Buying committees in bulk material handling now unbundle hardware procurement from installation and maintenance contracts. Engineering-procurement-construction firms in Australian mining and Canadian oil sands increasingly specify air cannon arrays through separate technical and commercial tenders. This pattern fragments vendor relationships and compresses upfront equipment margins while expanding multi-year service agreement value pools.
Global Air Cannon System Market Segmentation
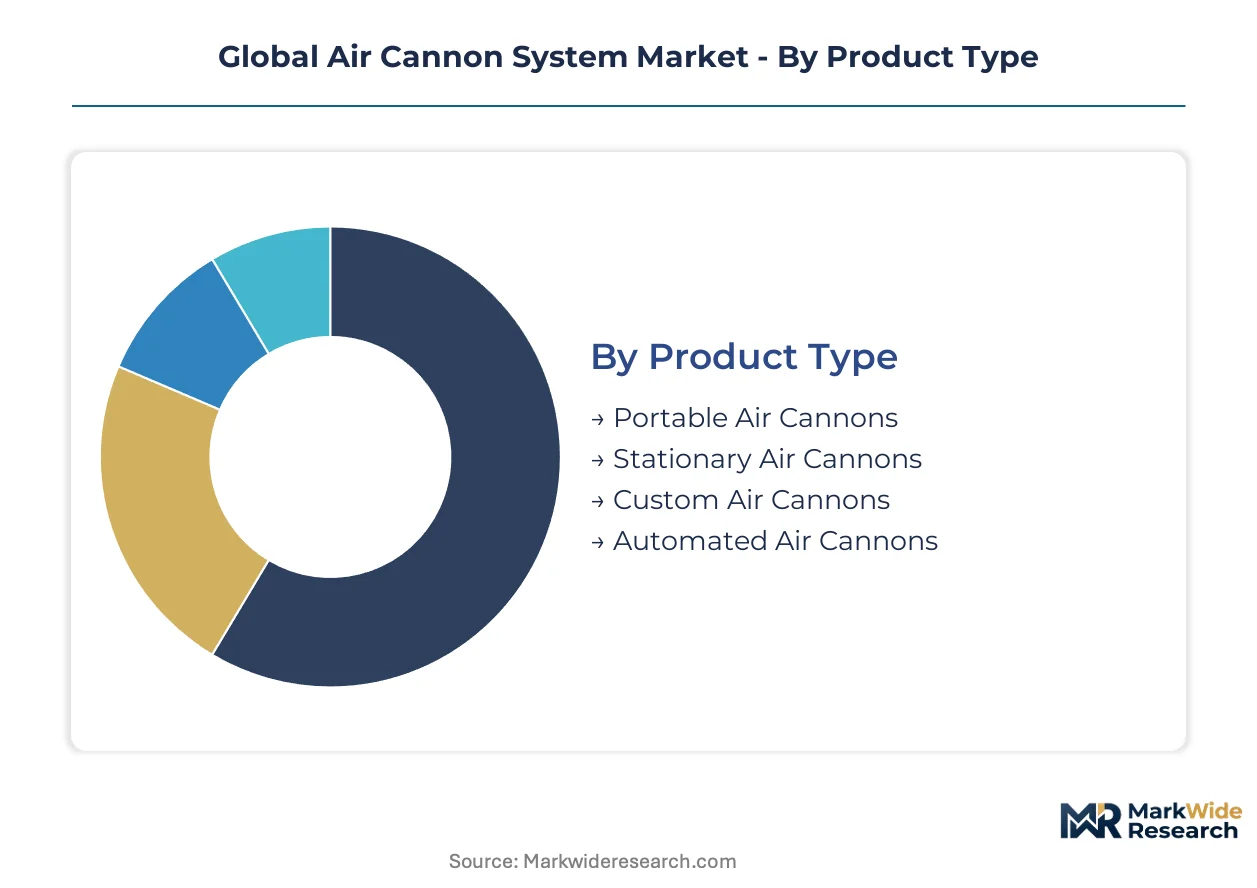
Air cannon system procurement patterns diverge sharply across product architectures, with permanent installations dominating cement and power infrastructure while portable units serve intermittent maintenance needs. End-use concentration in heavy bulk handling shapes regional manufacturing footprints and certification requirements.
Product Type:
Domestic production concentrates on stationary units for integrated industrial facilities, while portable and automated systems flow through export channels serving remote mining and retrofit markets.
- Stationary Air Cannons:Permanently mounted tank-and-valve assemblies operating at 80-125 psi integrate directly into preheater towers and boiler hoppers. Demand clusters in China's coal-fired power corridor and India's cement belt where MIIT and CEA mandates force automated cleaning retrofits.
- Automated Air Cannons:PLC-triggered firing sequences with pressure sensors and cycle counters enable condition-based maintenance architectures. Mining operations in Western Australia and Canada's oil sands specify these arrays through unbundled procurement models.
- Portable Air Cannons:Mobile units with wheeled tanks serve intermittent vessel cleaning in grain elevators and wood processing facilities facing OSHA combustible dust inspections.
- Custom Air Cannons:Engineered-to-order systems address high-temperature foundry applications above 400°F and abrasive fly ash environments in US power generation.
Stationary air cannons hold the largest share; momentum sits with automated arrays.
End User:
Customer concentration follows bulk material throughput intensity, with mining and construction absorbing high-force pneumatic systems while food processing demands contamination-controlled hybrid architectures.
- Mining:Iron ore and copper operations in Chile's Atacama and Brazil's Carajás deploy cannon arrays to maintain flow through concentrate silos and crusher feed chutes. Procurement runs through engineering-procurement-construction firms specifying separate technical and commercial tenders.
- Construction:Cement manufacturers in Vietnam and Indonesia integrate cannons into kiln preheater systems to prevent meal buildup without production shutdowns.
- Food Processing:Grain handling facilities in the US Midwest and EU member states prioritize explosion-proof pneumatic systems over electric alternatives.
- Agriculture:Fertilizer blending terminals and seed storage silos in Argentina's Pampas and Ukraine's Black Sea corridor specify mid-pressure portable units.
Mining commands the revenue base; food processing climbs fastest on regulatory compliance spending.
Technology:
Technology selection hinges on ignition risk environments, with pneumatic dominance in explosive atmospheres giving way to hybrid architectures where precise timing outweighs force requirements.
- Pneumatic Technology:Compressed air discharge through fast-acting diaphragm valves remains mandatory in coal handling, grain processing, and wood pellet manufacturing where spark containment governs specification. REACH-mandated fluoroelastomer seals extend service intervals in European installations.
- Hybrid Technology:Electric valve actuation married to pneumatic force generation penetrates dairy powder and pharmaceutical tablet coating operations requiring exact discharge timing without compressed air contamination.
- Electric Technology:Solenoid-actuated systems gain traction in non-explosive chemical processing where installation simplicity trumps air cannon force density.
- Mechanical Technology:Spring-loaded and gravity-actuated devices persist in cost-sensitive agricultural terminals lacking centralized compressed air infrastructure.
Pneumatic technology anchors installed value; hybrid configurations are expanding most quickly in food-grade segments.
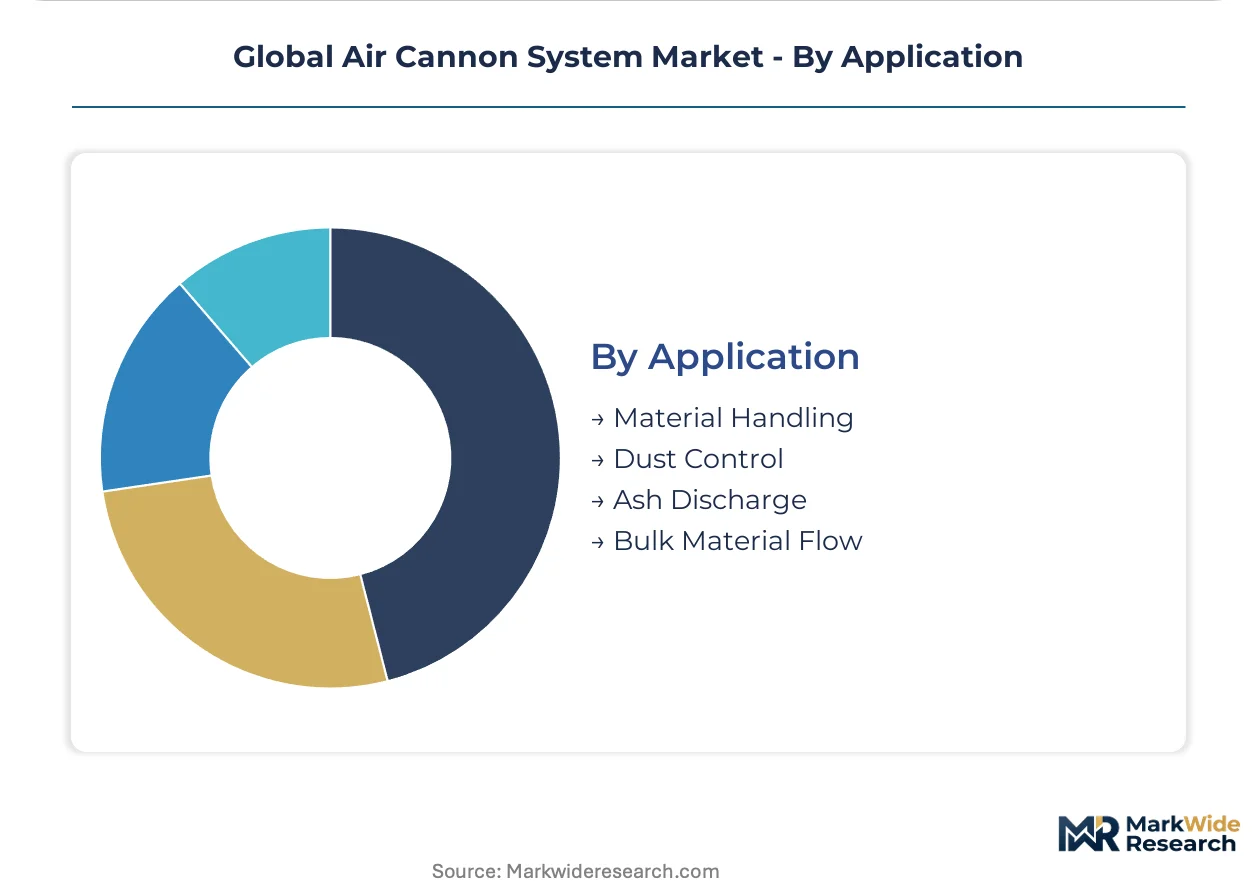
Application:
Application prioritization reflects regulatory pressure gradients, with dust control and ash discharge commanding investment in jurisdictions with tightening particulate standards.
- Dust Control:Hopper and precipitator cleaning systems in coal-fired power stations face EPA and MEE enforcement deadlines, forcing valve certifications for abrasive high-temperature environments.
- Material Handling:Conveyor transfer point maintenance in Brazilian iron ore ports and South African platinum concentrators prevents blockages that halt bulk terminal throughput.
- Ash Discharge:Bottom ash and fly ash handling in US and Chinese thermal plants requires cannon arrays certified above 400°F for combustion residual discharge.
- Bulk Material Flow:Silo and bunker mass flow restoration in cement, steel, and fertilizer storage addresses rat-holing and arching without manual entry.
Dust control captures the largest deployment value; ash discharge is gaining share fastest on power sector compliance spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cement buyers exhibit acute price sensitivity, while Australian mining operators prioritize equipment uptime over capital outlay. This elasticity divergence shapes supplier strategies across geographies.
China
MIIT mandates for industrial dust control retrofit coal-fired power stations with automated cleaning systems. GB standards for particulate emissions tighten certification requirements for valve assemblies. The Yangtze River Delta cluster concentrates procurement for preheater tower installations.
United States
OSHA combustible dust enforcement drives replacement of manual cleaning in grain elevators and wood processing plants. EPA National Emission Standards for Hazardous Air Pollutants force 2028 compliance deadlines for ash handling upgrades. Texas and Illinois power corridors dominate thermal plant retrofit activity.
India
CEA emission directives for thermal power plants create certification pathways for imported ash handling equipment. Cement manufacturers in Gujarat and Rajasthan integrate cannons into kiln systems to avoid production shutdowns. The Central Electricity Authority standards recalibrate import burdens for non-domestic suppliers.
Germany
REACH restrictions on legacy elastomer compounds redirect R&D toward fluoroelastomer diaphragm alternatives. ECHA compliance timelines extend product certification periods for seal materials. Foundries in North Rhine-Westphalia lead adoption of modular valve architectures.
Australia
Iron ore concentrate silos in Western Australia deploy cannon arrays through unbundled procurement models. Engineering-procurement-construction firms specify separate technical and commercial tenders for remote mining corridors. The Pilbara region drives demand for automated firing sequences with condition-based maintenance.
Global Air Cannon System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Pneumatic specialists with decades of bulk material handling expertise command premium positioning in heavy industrial segments. Regional fabricators compete on installation proximity and aftermarket service density. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into hybrid electric-pneumatic architectures.
Among North American bulk handling specialists, Martin Engineering and VAC-U-MAX occupy distinct positioning vectors. Martin Engineering exemplifies the premium-tier archetype anchored in mining corridor relationships. VAC-U-MAX represents the pneumatic integration specialist serving contamination-sensitive segments. German precision engineering heritage is embodied by Jost GmbH, which anchors European demand through foundry and steel mill applications. These three players collectively illustrate how geographic origin and historical specialization segment the vendor landscape.
| Leading Market Players |
|---|
| FineTek |
| Fike Corporation |
| Staminair Corporation |
| Global Manufacturing Inc |
| Jost GmbH |
| Martin Engineering |
| VAC-U-MAX |
| Vibco Vibrators |
| AIRMATIC INC |
| Others |
Supply Flow & Price Mechanics
Fluoroelastomer diaphragm substitution for legacy nitrile seals simultaneously concentrates procurement leverage in German and Japanese specialty chemical suppliers and compresses margin structures for mid-tier air cannon fabricators unable to absorb reformulation costs. This input transition reconfigures tiered pricing boundaries as REACH compliance timelines force rapid certification investments.
Pricing Analysis
Aftermarket diaphragm and valve replacement programs now generate the majority of lifetime customer value, displacing upfront equipment margins as the primary revenue anchor. Three-tier pricing structure across premium, standard, and economy levels separates Martin Engineering's mining corridor relationships from regional challengers in Southeast Asian cement markets. Price differentiation rests on EPA certification tier and geographic service density. Cost compression in standard-grade installations is intensifying because alloy steel input volatility constrains fixed-price contract viability. Indian cement buyers exhibit acute price sensitivity; Australian mining operators prioritize uptime over capital outlay.
Supply Chain Analysis
China and India anchor carbon steel tank fabrication for stationary air cannon systems, while Germany and Japan concentrate fluoroelastomer diaphragm production. Supply chains draw from alloy steel mills, pneumatic valve component foundries, and specialty seal compound manufacturers. Single-source vulnerability concentrates in high-temperature diaphragm formulations certified above 400°F. Distribution runs through engineering-procurement-construction firms in mining corridors and direct OEM relationships in cement and power generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air cannon system procurement is approaching a platform-economics inflection as PLC-triggered firing sequences and condition-based maintenance architectures create interoperability requirements between valve hardware, sensor networks, and distributed control systems.
For Market Incumbents: Secure aftermarket service density in Australian and Canadian mining corridors before EPC firms complete unbundled procurement transitions. Deepen backward integration into fluoroelastomer diaphragm production to offset REACH-mandated reformulation cost pressure. Anchor premium positioning through EPA-validated temperature certifications that regional fabricators cannot replicate.
For New Entrants and Emerging Players: CEA certification fast-tracks for Indian thermal power ash handling applications offer the most penetrable regulatory pathway for non-domestic suppliers. Target hybrid electric-pneumatic architectures in food-grade segments where precise discharge timing commands specification authority. Pursue component-level service unbundling in Vietnamese and Indonesian cement markets to bypass incumbent installation relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pneumatic component specialists lacking smart actuation capabilities. Five-to-ten year viability hinges on successful PLC integration and predictive maintenance platform deployment. Watch for MIIT enforcement acceleration in China's Yangtze River Delta power corridor as inflection indicator for automated cleaning system procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Electric-Pneumatic Product Line Expansion | Opens food-grade and pharmaceutical segments requiring precise discharge timing without contamination risk. |
| Condition-Based Maintenance Platform Launch | Embeds pressure sensors and cycle counters to enable predictive diaphragm replacement in cement preheater towers. |
| REACH-Compliant Fluoroelastomer Certification | Extends service intervals and defends European foundry market share against reformulation-lagged competitors. |
| Engineering-Procurement-Construction Partnership | Secures specification authority in Australian Pilbara and Canadian oil sands through unbundled tender participation. |
| Modular Valve Cartridge Architecture | Reduces field downtime during diaphragm failure and expands aftermarket parts competition in cost-sensitive markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with maintenance directors at cement and power generation facilities, pneumatic system engineers at mining operations, procurement leads at engineering-procurement-construction firms, and aftermarket service heads at OEM distributors. Secondary validation incorporated EPA National Emission Standards documentation, MIIT dust control mandate filings, CEA thermal power directives, REACH elastomer restriction updates, and customs trade data for pneumatic discharge equipment. Bottom-up installation base modeling and top-down industrial capital expenditure triangulation anchored market sizing.
Across the analysis window, forecasts triangulate product architecture segmentation by stationary, automated, portable, and custom configurations; technology tiers spanning pneumatic, hybrid, electric, and mechanical actuation; and application intensity across dust control, material handling, ash discharge, and bulk flow restoration. CAGRs derive from industrial compliance spending trajectories, compressed air infrastructure investment cycles, and retrofit penetration curves in coal-fired power and cement kiln systems.
Decision-makers should treat outputs as directional under sustained EPA and MIIT enforcement intensity, stable alloy steel pricing, and pneumatic technician availability assumptions; material deviation would warrant model refresh. Specific risks include accelerated electric vibration substitution in non-explosive environments, prolonged REACH certification delays, and EPC firm consolidation reducing specification channels. Recalibration cycles align with material shifts in regulatory enforcement timelines and industrial compressed air infrastructure investment waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Industrial Racking Systems Market