
 Linear Slides Market | 2026-2036
Linear Slides Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Slides Market Analysis
Market Context with Strategic Players
East Asian manufacturing corridors is fragmenting as multiple production ecosystems compete for linear motion component supply. THK Co., Ltd. anchors Japanese precision engineering heritage through captive ball screw and guideway fabrication. Bosch Rexroth AG leverages its German automation platform to integrate linear slides with servo drive systems. Hiwin Corporation dominates Taiwanese supply chains for semiconductor equipment builders requiring sub-micron positioning repeatability.
Technical Definition and Structural Segments
Linear slides are electromechanical assemblies that constrain motion to a single degree of freedom using rolling elements or sliding bearings between a rail and carriage, typically achieving positioning accuracies of 1–10 micrometers depending on preload and bearing class. These devices translate rotary motor output into precise linear displacement for CNC machine tools, robotic gantries, and automated inspection stations. Ball bearing slides command the largest revenue pool due to their load capacity and stiffness in industrial automation, while linear motion systems capture the fastest expansion as modular mechatronics replace custom-built positioning stages. Aluminum rail constructions are displacing carbon steel in cleanroom and medical applications where magnetic permeability and corrosion resistance constrain material selection.
Regulatory Frame and Forward-Looking Close
ISO 12100 machinery safety standards, EU Machinery Directive 2006/42/EC, and FDA 21 CFR Part 820 quality system regulations collectively dictate design validation, traceability, and risk documentation requirements for linear slide suppliers serving medical device and industrial automation end users. CE marking conformity assessment in Europe and FDA device master file obligations in the United States create divergent compliance pathways that favor regionally certified manufacturers. Stakeholders must monitor how evolving functional safety standards for collaborative robotics redefine load rating methodologies and lifecycle testing protocols.
Market Dynamics
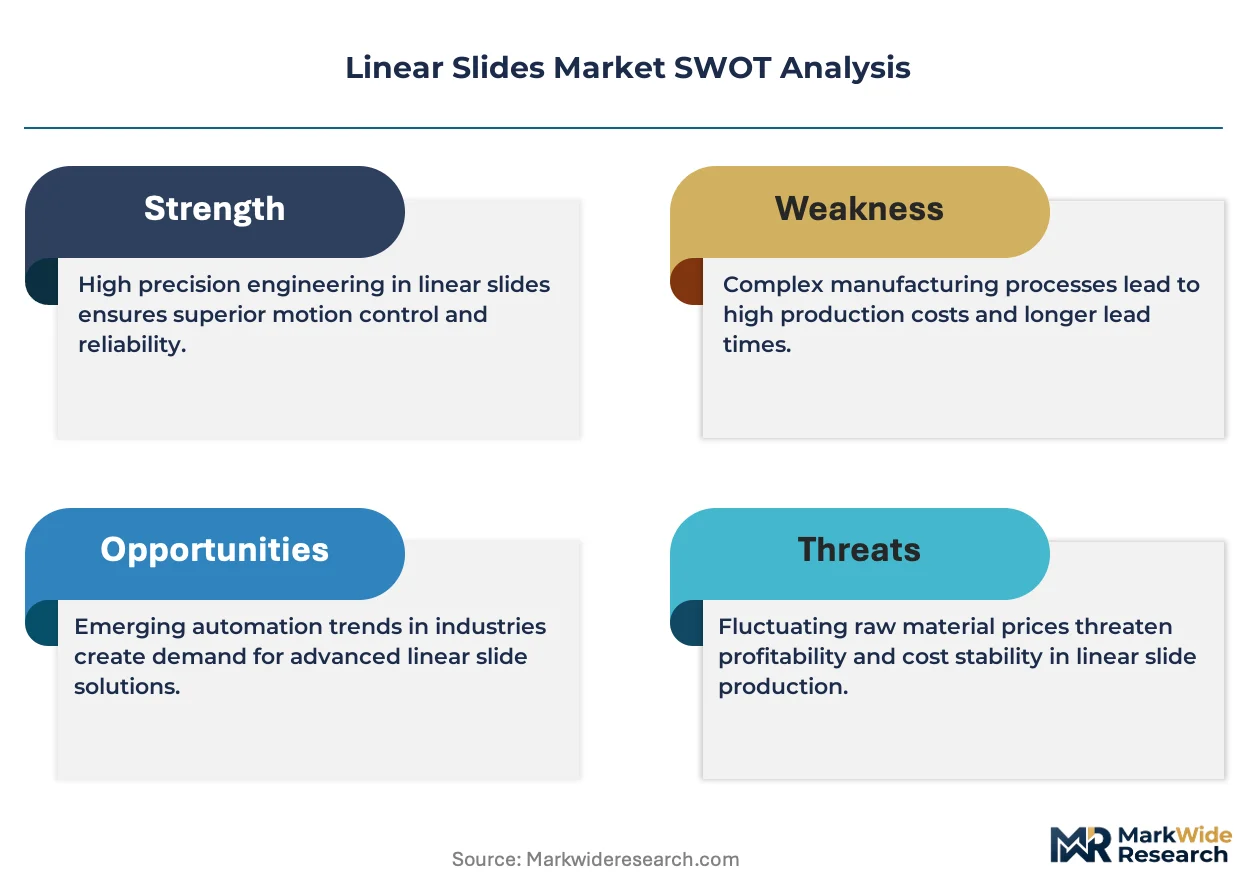
Semiconductor fabrication equipment builders in Taiwan and South Korea are expanding orders for precision linear motion components, tightening supply allocation across East Asian manufacturing corridors and forcing tier-two automation integrators to extend lead times or qualify secondary suppliers.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking conformity assessment for electromechanical positioning systems is accelerating replacement cycles in European industrial automation, particularly for collaborative robotics applications requiring validated functional safety documentation.
- Sub-micron positioning repeatability:Semiconductor lithography and inspection equipment demands are pulling precision linear slides into cleanroom environments where aluminum rail constructions displace carbon steel to satisfy magnetic permeability constraints.
- Shenzhen-Nagoya industrial corridor concentration:Contract manufacturers serving consumer electronics and automotive electronics are consolidating vendor qualification lists, privileging linear slide suppliers with localized technical service and same-day spare parts availability.
Market Restraints
- Specialized alloy input cost volatility:Chrome steel bearing quality grades and 440C stainless rod stock face price swings tied to nickel and chromium supply disruptions from Russian and South African mining operations.
- Japanese captive supply concentration:THK and NSK maintain in-house ball screw and guideway fabrication, limiting third-party access to precision rolling element technology and constraining independent slide assembly margins.
- Magnetic levitation substitution threat:Air-bearing and linear motor direct-drive stages encroach on ball-bearing slide applications below 500mm travel where frictionless motion eliminates mechanical contact wear.
Strategic Opportunities
- Indian PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and test facilities are creating first-mover advantage for linear slide vendors establishing local calibration centers and application engineering presence.
- Modular mechatronics convergence:Integration of linear slides with servo drives, encoders, and controllers into pre-engineered motion subsystems reduces customer integration labor and accelerates machine builder time-to-market.
- FDA 21 CFR Part 820 quality system alignment:Medical device manufacturers require design history file traceability and risk management documentation, favoring suppliers with established device master file submissions and validated manufacturing processes.
Industry Challenges
- Precision metrology technician scarcity:Calibration of sub-micron positioning systems requires specialized interferometry and geometric dimensioning expertise that outstrips vocational training program output in manufacturing-heavy regions.
- ISO 12100 lifecycle testing timeline:Functional safety validation for collaborative robotics applications demands extended mean-time-between-failure documentation that compresses product launch windows and strains R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Slides Market |
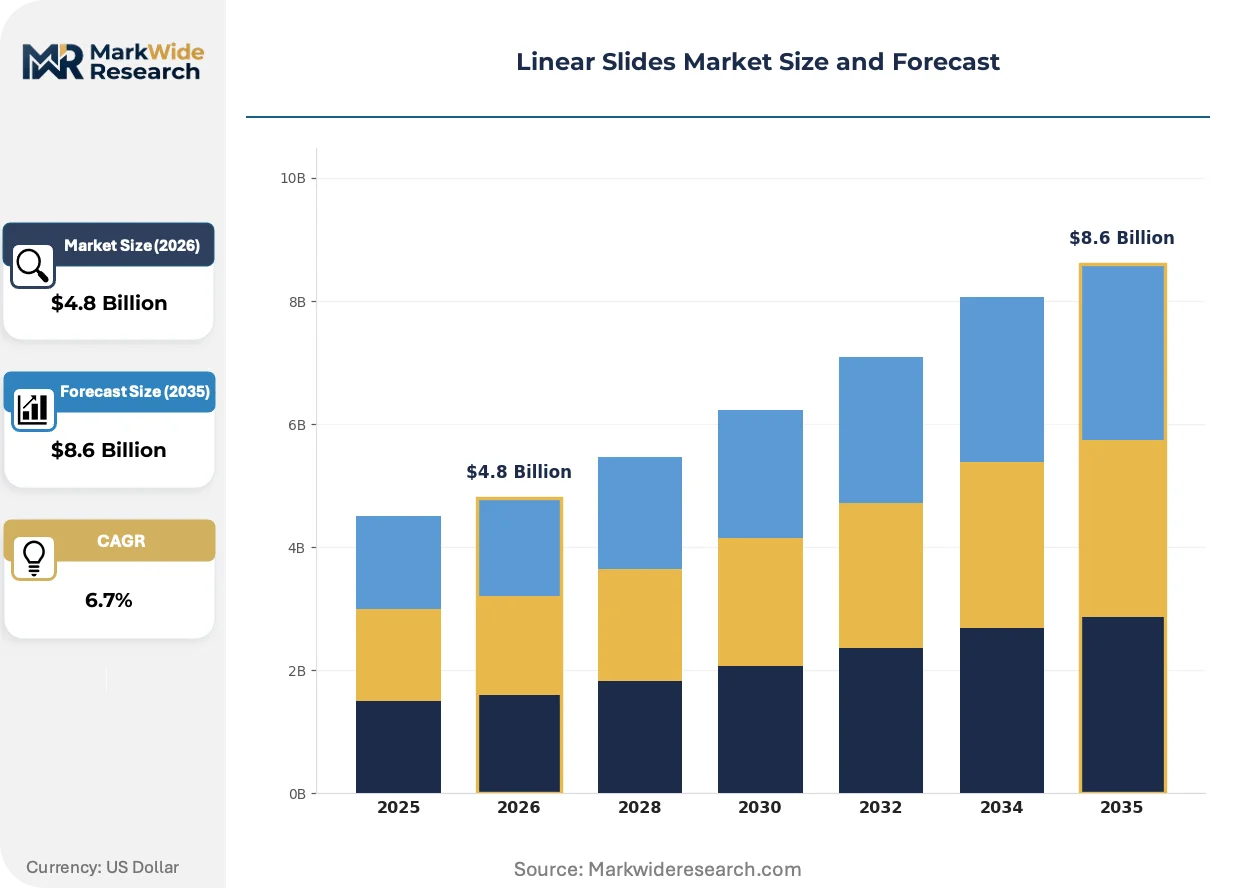
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearing Slides, Drawer Slides, Linear Motion Systems, Telescopic Slides Material: Aluminum, Stainless Steel, Plastic, Carbon Steel End User: Automotive, Aerospace, Electronics, Medical Devices Application: Industrial Automation, Furniture, Robotics, Machinery |
| Companies Covered | THK Co., Ltd., Parker Hannifin Corporation, SKF, Bosch Rexroth AG, Igus GmbH, Bishop-Wisecarver Corporation, Schaeffler AG, Hiwin Corporation, Festo AG & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Slides Market Emerging Trajectories
Linear motion technology is migrating from mechanical assemblies toward integrated mechatronic subsystems, compressing the value chain and redefining competitive advantage around software-defined positioning rather than component precision alone.
Aluminum rail constructions with hard-anodized running surfaces are migrating from specialty medical and semiconductor applications into broader industrial automation as machine builders prioritize corrosion resistance and reduced mass for high-acceleration gantry designs. Automotive battery module assembly lines in Germany and Michigan are adopting these extrusions to achieve 5m/s² acceleration profiles without magnetically induced positioning errors. The shift is migrating from premium niche specifications toward standard catalog configurations, eroding the historical steel-rail volume base.
REACH substance restrictions and RoHS recast directives are tightening permissible thresholds for hexavalent chromium in corrosion-resistant coatings and lead in bearing steels, forcing reformulation of traditional passivation processes. Suppliers serving European medical device and food packaging automation must now document full material composition through supply chain tiers. This regulatory pressure is accelerating qualification of ceramic rolling elements and stainless steel alternatives in German and Swiss machine tool markets.
Buyer consolidation among contract equipment builders is compressing vendor panels and unbundling after-sales service from hardware procurement. Large semiconductor capital equipment manufacturers in Taiwan now negotiate enterprise frame agreements covering predictive maintenance, spare parts inventory, and field calibration across multiple fabrication sites. This service integration is most visible in the Hsinchu Science Park cluster, where equipment uptime guarantees now dominate supplier selection criteria over initial component pricing.
Linear Slides Market Segmentation
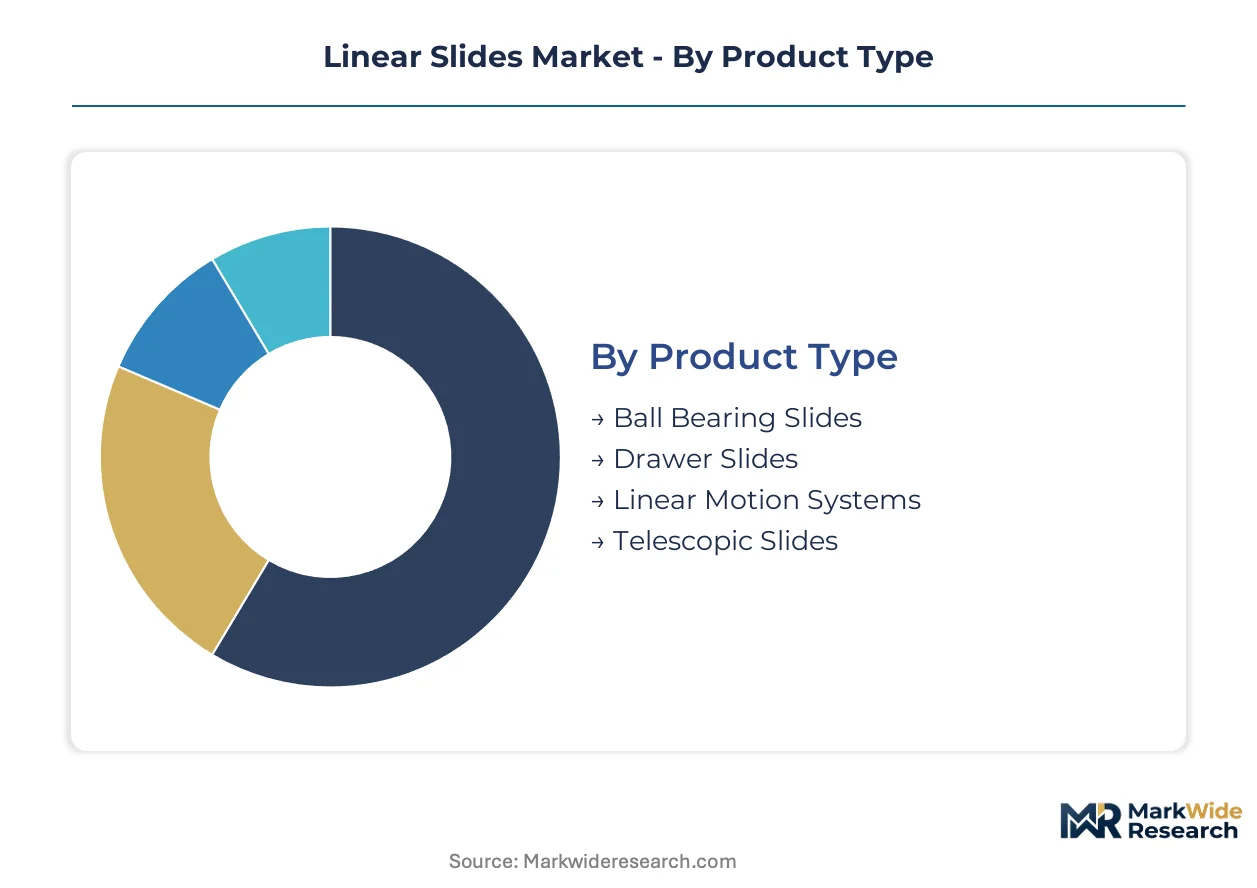
Linear slide procurement cycles vary dramatically across product architectures, with semiconductor equipment builders replacing precision motion systems every 3-5 years while furniture OEMs specify drawer slides on 10-15 year refresh horizons. Understanding these replacement rhythms helps suppliers align inventory positioning and service attach rates to customer lifecycle value.
Product Type:
Ball bearing slides turn inventory fastest in East Asian electronics manufacturing corridors, while telescopic slides linger longest in heavy machinery maintenance schedules.
- Ball Bearing Slides:Rolling element assemblies using recirculating steel balls between rail and carriage achieve 1-10 micrometer positioning accuracy depending on preload class. Taiwanese semiconductor fabrication equipment builders in Hsinchu Science Park specify these for lithography stages where sub-micron repeatability is mandatory. THK and NSK captive fabrication limits third-party access to precision rolling element supply.
- Linear Motion Systems:Modular mechatronic subsystems integrate slides with servo drives, encoders, and controllers into pre-engineered positioning stages. Shenzhen contract manufacturers serving consumer electronics assembly are consolidating vendor panels around suppliers offering same-day spare parts availability and localized calibration services. These integrated architectures reduce customer integration labor and compress machine builder time-to-market.
- Drawer Slides:Light-duty ball bearing or roller mechanisms for furniture and cabinetry applications, typically rated below 50kg load capacity with minimal precision requirements.
- Telescopic Slides:Multi-stage extension rails enabling 150-200% of closed length travel, common in vehicle storage, server racks, and industrial access panels where extended reach matters more than positioning accuracy.
Ball bearing slides anchor the volume base while linear motion systems gain share at the steepest rate.
Material:
Cost tiers separate commodity carbon steel from premium aluminum and stainless formulations, with magnetic permeability and corrosion resistance driving specification divergence.
- Aluminum:Extruded rail constructions with hard-anodized running surfaces achieve corrosion resistance and reduced mass for high-acceleration gantry designs. Automotive battery module assembly lines in Germany specify these to hit 5m/s² acceleration without magnetically induced positioning errors. REACH substance restrictions are accelerating migration from hexavalent chromium passivation toward ceramic coating alternatives.
- Carbon Steel:Through-hardened bearing quality grades offer maximum stiffness and load capacity for machine tool and heavy automation applications. Chrome steel input costs swing with nickel and chromium supply disruptions from Russian and South African mining operations, compressing margins for independent slide assemblers.
- Stainless Steel:440C and precipitation-hardened grades serve medical device and food packaging automation where FDA 21 CFR Part 820 quality system documentation and corrosion resistance are mandatory.
- Plastic:Polymer and composite rail constructions for light-load, chemically aggressive, or electrically isolating environments where metal corrosion or conductivity is prohibitive.
Carbon steel dominates shipment tonnage while aluminum climbs fastest in specification share.
End User:
Customer concentration patterns concentrate procurement power, with semiconductor capital equipment manufacturers negotiating enterprise frame agreements spanning multiple fabrication sites.
- Electronics:Semiconductor lithography and inspection equipment demands pull precision linear slides into cleanroom environments. South Korean memory chip fabricators in Pyeongtaek and Taiwanese logic foundries in Tainan Science Park are expanding orders for sub-micron positioning components, tightening supply allocation across East Asian manufacturing corridors.
- Automotive:Battery module assembly, electric powertrain testing, and automated inspection stations specify aluminum rail constructions to achieve acceleration profiles impossible with steel. Production-linked incentives for Indian electronics manufacturing are creating first-mover advantage for vendors establishing local calibration centers.
- Medical Devices:Diagnostic imaging, surgical robotics, and laboratory automation require design history file traceability and risk management documentation. FDA device master file obligations favor suppliers with validated manufacturing processes and established quality system submissions.
- Aerospace:Aircraft seating, galley systems, and cargo handling mechanisms specify lightweight, fatigue-resistant motion components with extensive qualification documentation.
Electronics commands the largest procurement volume while automotive expands most quickly.
Application:
Maturity gradients separate established industrial automation from emerging robotics applications, with functional safety standards reshaping load rating methodologies.
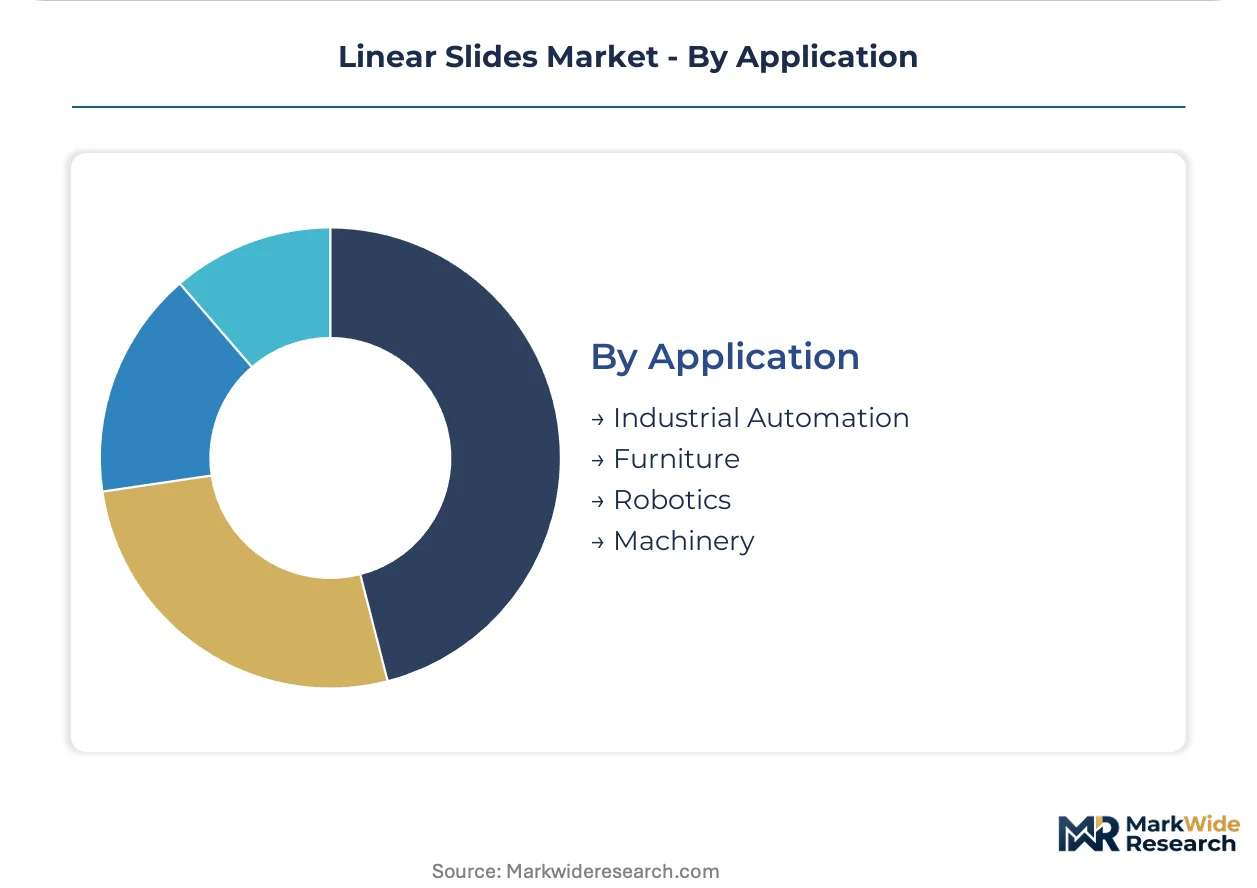
- Industrial Automation:CNC machine tools, robotic gantries, and automated inspection stations represent the installed base for ball bearing slides and linear motion systems. EU Machinery Directive 2006/42/EC compliance mandates are accelerating replacement cycles in European manufacturing, particularly for collaborative robotics requiring validated functional safety documentation.
- Robotics:Collaborative and mobile robot platforms demand compact, lightweight positioning stages with integrated force sensing and safety-rated motion control. ISO 12100 lifecycle testing protocols for collaborative applications compress product launch windows and strain R&D resource allocation.
- Machinery:General industrial equipment including packaging, printing, and material handling systems where standard catalog configurations predominate over custom engineering.
- Furniture:Residential and commercial cabinetry, office systems, and retail fixtures specifying commodity drawer slides on price-driven procurement cycles with minimal technical service requirements.
Industrial automation anchors current revenue while robotics offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's technical standards for precision machinery anchor Japanese demand for electromechanical positioning systems. The EU Machinery Directive and FDA quality system regulations create divergent compliance pathways across major manufacturing economies.
United States
FDA 21 CFR Part 820 quality system documentation shapes procurement for medical device automation in surgical robotics and diagnostic imaging. Michigan automotive battery module assembly lines specify aluminum rail constructions to achieve aggressive acceleration profiles. Greater Boston and Detroit industrial corridors concentrate demand from electric powertrain testing facilities.
Germany
EU Machinery Directive 2006/42/EC compliance mandates accelerate replacement cycles in collaborative robotics applications requiring validated functional safety. REACH substance restrictions tighten thresholds for hexavalent chromium in corrosion-resistant coatings. Bavarian and Baden-Württemberg machine tool markets drive qualification of ceramic rolling elements and stainless steel alternatives.
Japan
METI industrial standards and JIS precision machinery specifications govern sub-micron positioning repeatability requirements for semiconductor lithography equipment. Captive ball screw fabrication by domestic incumbents limits third-party access to precision rolling element technology. Nagoya and Tokyo industrial corridors concentrate demand from logic foundry capital equipment builders.
South Korea
MFDS medical device regulations and national semiconductor investment programs expand orders for precision linear motion components in memory chip fabrication. Pyeongtaek and Suwon industrial clusters tighten supply allocation as equipment builders consolidate vendor qualification lists around localized technical service capabilities.
Taiwan
Production-linked incentives for semiconductor assembly and test facilities under national technology programs pull precision slides into cleanroom environments. Hsinchu Science Park equipment manufacturers negotiate enterprise frame agreements covering predictive maintenance and field calibration across multiple fabrication sites. Tainan Science Park logic foundries specify aluminum rail constructions to satisfy magnetic permeability constraints.
Linear Slides Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Japanese and German incumbents control precision rolling element fabrication through captive supply chains, while Taiwanese and Chinese assemblers compete on modular integration speed and localized service density. Three archetypes dominate: vertically integrated precision component fabricators, modular mechatronics integrators, and regional application engineering specialists. Competitive moves center on backward integration into bearing-grade alloy supply and geographic expansion through calibration center establishment.
Among Japanese precision engineering houses, THK Co., Ltd. exemplifies the captive fabrication archetype through in-house ball screw and guideway production. Bosch Rexroth AG occupies a position bridging German automation platform integration with linear motion component supply. Hiwin Corporation anchors Taiwanese supply chain dominance for semiconductor equipment builders requiring sub-micron positioning repeatability.
| Leading Market Players |
|---|
| THK Co., Ltd. |
| Parker Hannifin Corporation |
| SKF |
| Bosch Rexroth AG |
| Igus GmbH |
| Bishop-Wisecarver Corporation |
| Schaeffler AG |
| Hiwin Corporation |
| Festo AG & Co KG |
| Others |
Supply Flow & Price Mechanics
Hsinchu Science Park fabrication corridors concentrate precision linear slide demand, concentrating procurement leverage among Taiwanese semiconductor capital equipment manufacturers who negotiate enterprise frame agreements bundling predictive maintenance and field calibration. This buyer consolidation compresses component pricing while elevating service attach rates as the dominant margin driver.
Pricing Analysis
Japanese and German origin slides command 40-60% premiums over Taiwanese and Korean equivalents due to THK and NSK captive ball screw fabrication and Bosch Rexroth integrated servo platforms. Pricing stratifies across premium, standard, and economy tiers keyed to positioning repeatability certification, preload class, and geographic delivery cost. Cost compression in standard-grade carbon steel slides is intensifying because chrome steel input volatility from Russian and South African mining disruptions squeezes independent assembler margins. Semiconductor equipment builders show lowest price sensitivity, prioritizing sub-micron repeatability guarantees and same-day spare parts availability over unit cost.
Supply Chain Analysis
Foxconn and Pegatron electronics manufacturing services anchor East Asian contract manufacturing concentration, pulling linear slide procurement into consolidated vendor panels with stringent qualification protocols. Supply draws from Japan, Taiwan, and Germany for precision rolling elements, with secondary assembly capacity in China and South Korea. Chrome steel bearing quality grades, 440C stainless rod stock, and hard-anodized aluminum extrusions constitute critical input dependencies. Single-source vulnerability concentrates in Japanese captive ball screw supply, constraining third-party access. Distribution runs through OEM direct sales for semiconductor equipment builders and industrial distributor networks for general automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated semiconductor capital equipment manufacturers in Taiwan and South Korea, fragmenting vendor access as enterprise frame agreements privilege suppliers with localized calibration infrastructure and multi-site service coverage.
For Market Incumbents: Entrench precision rolling element fabrication advantages through captive supply chain control and METI/JIS certification maintenance, while expanding application engineering presence in Hsinchu and Tainan Science Parks to defend against modular mechatronics integrators. Magnetic levitation substitution threats in sub-500mm travel applications demand accelerated development of integrated linear motor direct-drive capabilities. For New Entrants and Emerging Players: Pursue Indian PLI scheme electronics manufacturing corridors where production-linked incentives for semiconductor assembly and test facilities create first-mover advantage for vendors establishing local calibration centers. Battery module assembly automation in Michigan and Bavaria offers penetrable white-space as automotive OEMs specify aluminum rail constructions for acceleration-intensive gantry designs, with entry angle through same-day spare parts availability commitments. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because modular mechatronics convergence compresses the value chain toward software-defined positioning, favoring acquisition targets with servo drive integration capabilities and established FDA device master file submissions. Monitor FDA 21 CFR Part 820 quality system enforcement intensity and ISO 12100 collaborative robotics safety standard evolution as inflection indicators for medical device and industrial automation demand segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing-Grade Alloy Supply | Mitigates chrome steel price volatility from Russian and South African mining disruptions. |
| Calibration Center Establishment in India | Captures PLI scheme electronics manufacturing incentives for semiconductor assembly facilities. |
| Modular Mechatronics Platform Development | Compresses machine builder integration labor and accelerates time-to-market for Shenzhen contract manufacturers. |
| FDA Device Master File Submission Expansion | Qualifies suppliers for surgical robotics and diagnostic imaging procurement requiring 21 CFR Part 820 traceability. |
| Aluminum Rail Hard-Anodizing Capacity Addition | Supports automotive battery module assembly acceleration profiles without magnetic permeability errors. |
Methodological Framework
A standing panel of semiconductor equipment procurement directors, precision motion system design engineers, industrial automation integrators, and aftermarket service heads provided ongoing calibration across the analysis window. Primary interviews with THK, Bosch Rexroth, and Hiwin application engineering teams were cross-validated against secondary sources including SEC 10-K filings, Japanese METI industrial machinery statistics, EU Machinery Directive implementation reports, and Taiwan Stock Exchange semiconductor capital equipment supplier disclosures. Bottom-up shipment data from Hsinchu and Tainan Science Park equipment builders was triangulated against top-down market sizing from regional trade associations.
Scenario-bracketing framed demand projections across the analysis window, modeling ball bearing slides, linear motion systems, drawer slides, and telescopic slides by material tier and end-use concentration. Electronics, automotive, medical device, and aerospace verticals were segmented with semiconductor lithography equipment, battery module assembly, surgical robotics, and aircraft seating as application-specific demand drivers. CAGRs were derived from replacement cycle analysis intersecting with regulatory compliance mandate timelines, incorporating EU Machinery Directive replacement acceleration and FDA quality system documentation requirements as structural demand modifiers.
Macroeconomic conditions sit as an overlay; deviation in East Asian electronics manufacturing capital expenditure cycles and nickel-chromium alloy commodity pricing would shift the trajectory. Forecasts assume sustained semiconductor fabrication capacity expansion in Taiwan and South Korea, with revision risk from magnetic levitation technology cost reduction or REACH substance restriction enforcement intensification. Quarterly review of Hsinchu Science Park equipment utilization rates and German machine tool order intake is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Loaded Container Handler Market