
 Canada Co-Working Office Spaces Market | 2026-2036
Canada Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Co-Working Office Spaces Market Outlook
LEED certification requirements for commercial buildings in Canadian urban centers is bifurcating the competitive landscape between premium and standard workspace providers. CBRE Group leverages its property management scale to secure Class A inventory in major metros. Workhaus anchors its position through boutique design-forward locations targeting professional services firms. International Workplace Group plc competes via global membership portability that appeals to cross-border enterprise clients.
Co-working office spaces constitute professionally managed shared work environments offering flexible lease terms, shared amenities, and scalable square footage typically ranging from dedicated desks to multi-suite private offices. These facilities serve primary commercial purposes including cost reduction for occupiers, network effects for knowledge workers, and asset-light expansion strategies for corporations. The target audience dimension shows enterprises representing the fastest-growing membership category as Fortune 500 subsidiaries adopt hub-and-spoke models, while freelancers sustain the largest absolute user base. Service model structures reveal subscription-based plans capturing the dominant revenue share due to predictable cash flow characteristics, though pay-per-use arrangements are gaining traction among seasonal industries.
Health Canada guidelines on indoor air quality and provincial building codes across Ontario, British Columbia, and Alberta shape ventilation and density standards for shared environments. The Competition Bureau's scrutiny of lease flexibility terms influences contract transparency requirements that operators must navigate. Stakeholders should monitor municipal property tax reassessments on commercial-to-co-working conversions as these will reshape site selection economics.
Market Dynamics
LEED certification requirements from the Canada Green Building Council are bifurcating supply into premium-certified and standard-grade inventory, reshaping capital allocation and site selection economics across Toronto, Vancouver, and Calgary.
Growth Catalysts
- Municipal Zoning Reforms:Toronto, Vancouver, and Calgary have enacted adaptive reuse ordinances enabling commercial-to-co-working conversions. These frameworks accelerate inventory activation in downtown cores.
- Enterprise Hub-and-Spoke Adoption:Fortune 500 subsidiaries are deploying distributed workspace strategies. This corporate demand segment is expanding faster than traditional freelance membership bases.
- Technology Sector Freelancers:Software developers and data specialists are concentrating in shared environments. Their presence generates network effects that attract adjacent professional services firms.
Market Restraints
- Commercial Property Tax Reassessments:Municipal authorities in Ontario, British Columbia, and Alberta are recalibrating tax obligations for converted assets. This input cost volatility compresses operator margins on legacy leases.
- Ventilation Density Standards:Health Canada indoor air quality guidelines impose technical limitations on maximum occupancy per square foot. These constraints restrict revenue optimization in premium downtown locations.
- Lease Flexibility Scrutiny:The Competition Bureau's contract transparency requirements create regulatory friction. Operators must restructure membership terms to comply with disclosure mandates.
Strategic Opportunities
- Calgary Beltline Expansion:This underpenetrated sub-market offers lower entry costs than Toronto or Vancouver. Energy sector downsizing has released Class A inventory suitable for premium repositioning.
- Global Membership Portability:Cross-border enterprise clients require seamless workspace access. Operators integrating with international networks capture recurring revenue from multinational deployments.
- Seasonal Pay-Per-Use Models:Agricultural and tourism industries demonstrate latent demand for non-subscription arrangements. Flexible billing structures unlock segments excluded by annual commitments.
Industry Challenges
- Building Code Compliance Timelines:Provincial standards across Ontario, British Columbia, and Alberta require extended permitting for density modifications. These certification delays extend cash conversion cycles for new locations.
- Integration Complexity with Legacy Systems:Enterprise clients demand API connectivity with existing facility management platforms. Technical interoperability requirements strain mid-scale operator development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Co-Working Office Spaces Market |
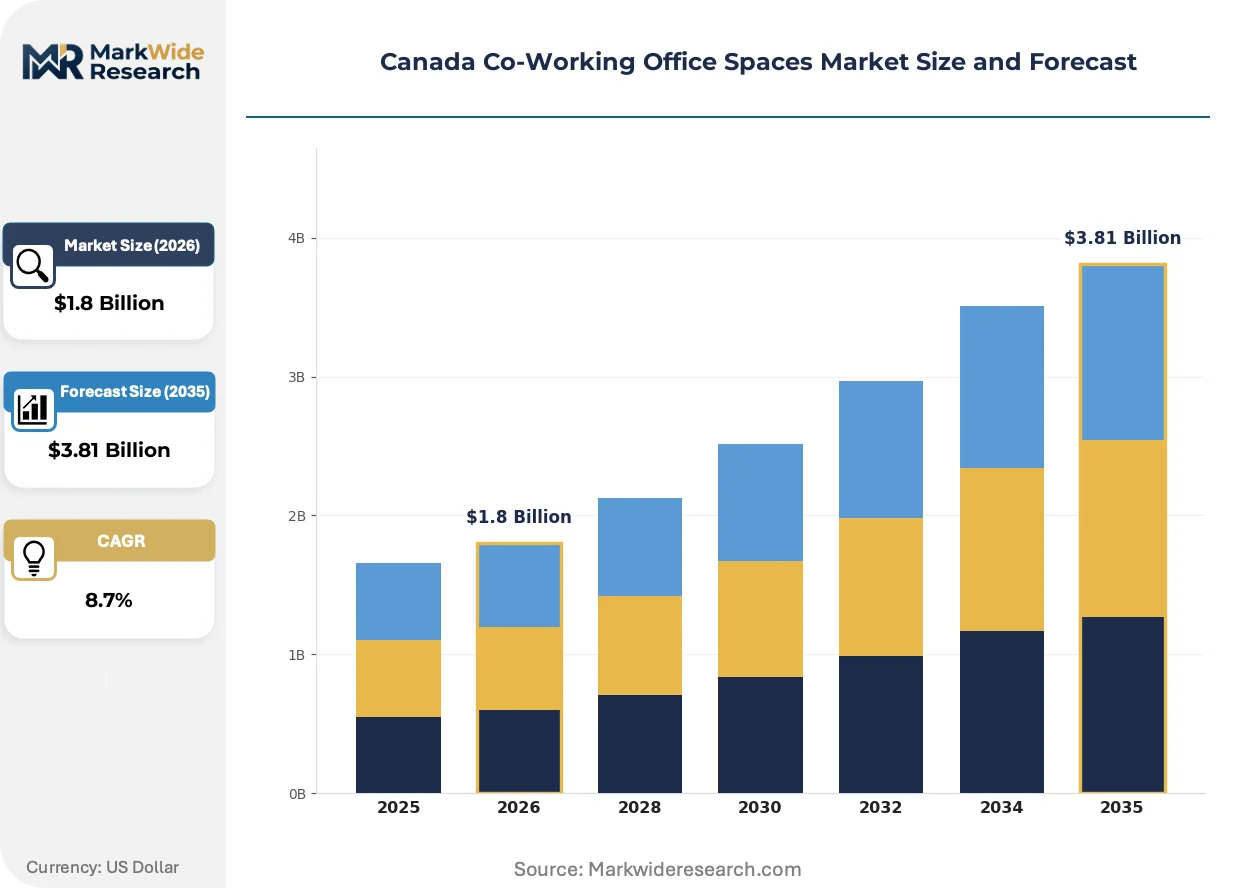
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Private Office, Dedicated Desk, Hot Desk, Meeting Rooms Target Audience: Freelancers, Startups, SMBs, Enterprises Service Model: Membership Plans, Pay-per-Use, Subscription-Based, On-Demand Interior Design: Open Space, Boutique Style, Traditional Office, Modern Minimalist |
| Companies Covered | CBRE Group, Workhaus, International Workplace Group plc, Serendipity Labs, IQ Offices, WeWork, Jones Lang LaSalle, ClickSpace, Regus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Co-Working Office Spaces Market Strategic Shifts
Workspace technology stacks are fragmenting traditional bundled offerings. Operators now compete through modular service architectures rather than fixed-amenity packages.
Sensor-based space utilization platforms are decomposing the conventional square-footage pricing model. Landlords and operators deploy IoT occupancy tracking to capture real-time density data. Enterprise clients adopt consumption-based billing for meeting rooms and hot desks. This technology is decomposing long-term lease structures into granular, event-priced transactions.
Health Canada guidelines on indoor air quality are mandating enhanced HVAC specifications for shared environments. These standards force capital expenditure on filtration and ventilation upgrades. Premium providers in Toronto's financial district absorb these costs to maintain certification status, while standard-grade competitors face member attrition.
Corporate procurement departments are consolidating vendor relationships through master service agreements. This buyer concentration shifts negotiation leverage toward volume purchasers. Professional services firms in Vancouver's Yaletown corridor now demand standardized contractual terms across multiple locations. The phenomenon is most visible in enterprise segments with centralized real estate functions.
Canada Co-Working Office Spaces Market Segmentation
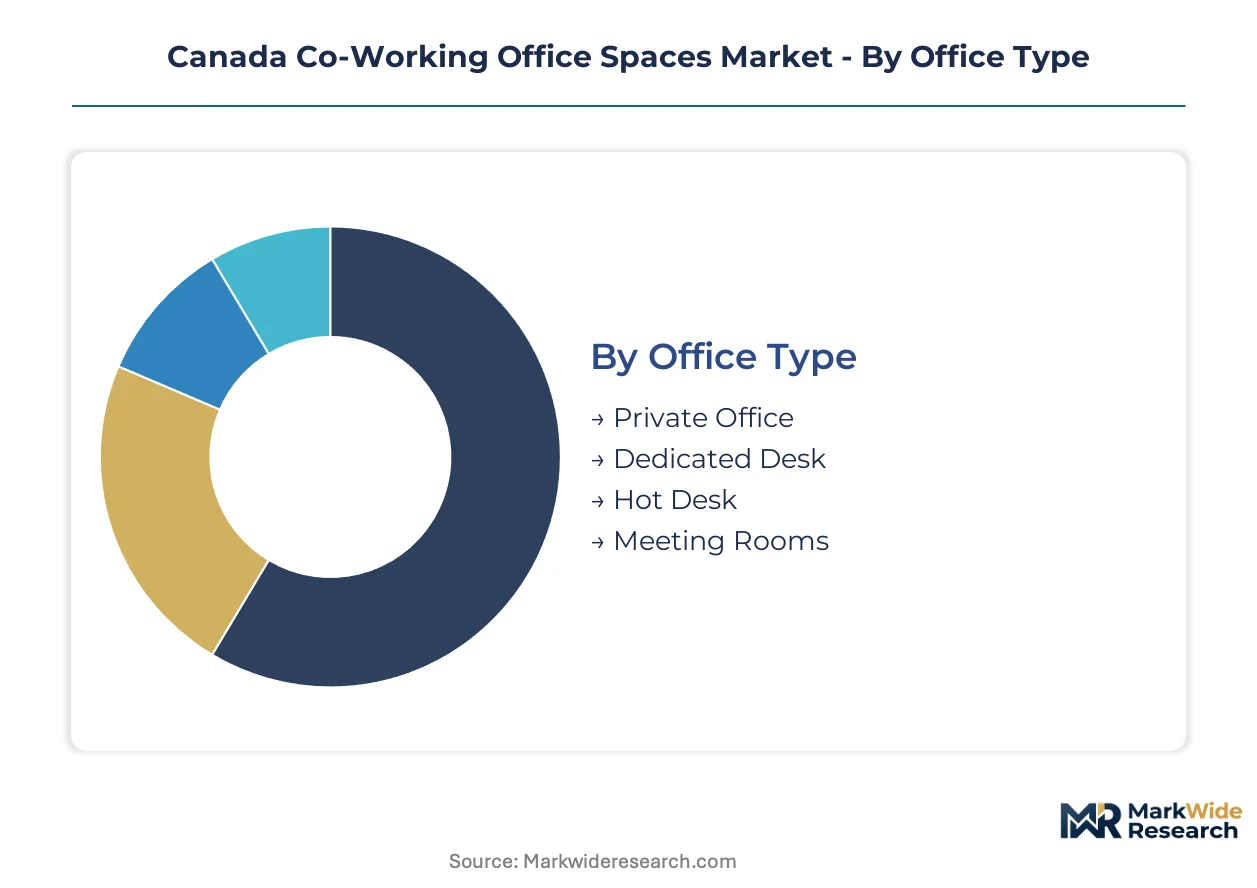
Segmentation in Canadian co-working spaces determines capital allocation, lease structuring, and amenity bundling. Operators calibrate square footage ratios and HVAC specifications differently across office types and audience tiers. Design philosophy directly influences municipal permitting timelines and property tax assessments in Toronto, Vancouver, and Calgary.
Office Type:
Substitution pressure runs strongest against meeting rooms and hot desks, where hotels, coffee chains, and home offices compete aggressively on price and convenience.
- Private Office:Enclosed suites ranging from 100 to 500 square feet with dedicated climate control and soundproofing. Demand concentrates among law firms and financial advisory practices in Toronto's financial district, driven by client confidentiality requirements and Health Canada ventilation density standards that favor lower-occupancy configurations.
- Dedicated Desk:Permanently assigned workstations within shared floorplates, typically including lockable storage and reserved seating. Technology freelancers in Vancouver's Yaletown corridor favor this format, balancing cost reduction against the network effects of proximate professional services firms.
- Hot Desk:Unassigned seating accessed through membership credentials, optimizing space utilization through staggered occupancy patterns. Seasonal workers in Calgary's energy sector use this format during project-intensive periods.
- Meeting Rooms:Bookable enclosed spaces for client presentations and team collaboration, equipped with video conferencing infrastructure. Corporate procurement departments increasingly source these through master service agreements rather than direct operator relationships.
Private offices retain volume leadership; dedicated desks hold the steepest expansion curve.
Target Audience:
Cost tier stratification separates premium concierge service from self-service automation, with enterprise clients commanding bespoke contract terms unavailable to smaller users.
- Freelancers:Individual knowledge workers purchasing single-seat memberships, representing the largest absolute user base. Software developers and data specialists generate network effects that attract adjacent professional services firms to shared environments.
- Startups:Early-stage companies requiring flexible scaling from two to twenty seats without lease renegotiation. These users prioritize month-to-month terms and proximity to venture capital clusters in downtown cores.
- SMBs:Established small and medium businesses seeking satellite locations or headquarters alternatives. This segment demonstrates the highest price sensitivity and churn rates during municipal property tax reassessment cycles.
- Enterprises:Fortune 500 subsidiaries and professional services firms deploying distributed workspace strategies. Hub-and-spoke adoption is expanding most quickly in this category, with centralized real estate functions demanding standardized contractual terms across multiple locations.
Freelancers anchor absolute membership counts; enterprises are climbing the fastest.
Service Model:
Application logic distinguishes predictable revenue streams from variable consumption patterns, with implications for operator cash flow management and capital expenditure timing.
- Membership Plans:Tiered monthly or annual commitments providing guaranteed access to specified amenity levels. CBRE Group leverages property management scale to bundle these with Class A building services in major metros.
- Pay-per-Use:Event-priced access to desks, meeting rooms, and amenities without recurring obligations. Agricultural and tourism industries demonstrate latent demand for this structure, excluded by annual commitment requirements.
- Subscription-Based:Automated recurring billing capturing dominant revenue share due to predictable cash flow characteristics. Workhaus anchors its position through boutique design-forward locations targeting this model.
- On-Demand:Real-time booking through mobile applications with dynamic pricing based on occupancy sensors. IoT utilization tracking enables this granular, event-priced transaction structure.
Subscription-based arrangements retain volume leadership; on-demand access is gaining share fastest.
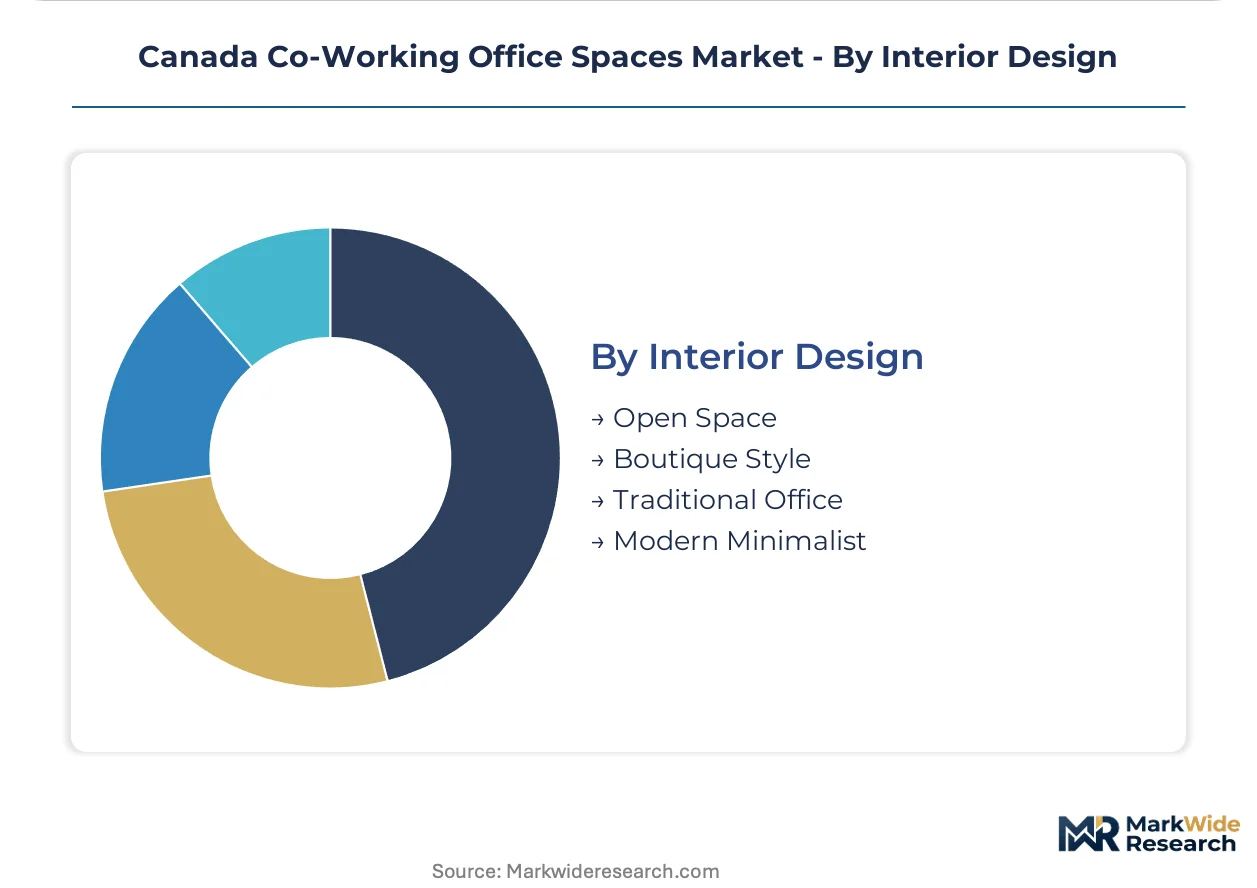
Interior Design:
Supply concentration in certified construction trades creates bottlenecks for premium design categories, extending permitting timelines in Ontario, British Columbia, and Alberta.
- Open Space:Unpartitioned floorplates maximizing density and flexibility, with modular furniture supporting rapid reconfiguration. This format faces the strongest substitution threat from home offices and hotel lobbies.
- Boutique Style:Curated aesthetic environments with custom millwork, art programming, and hospitality-grade finishes. Workhaus targets professional services firms through this differentiated positioning.
- Traditional Office:Conventional corporate aesthetics with private offices along perimeter windows and cubicle banks internally. Energy sector downsizing in Calgary has released Class A inventory suitable for this repositioning.
- Modern Minimalist:Clean-lined environments emphasizing natural light, biophilic elements, and reduced visual clutter. LEED certification requirements from the Canada Green Building Council favor this approach in premium downtown locations.
Open space retains volume leadership; modern minimalist holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal zoning reforms across Toronto, Vancouver, and Calgary are accelerating commercial-to-co-working conversions. Health Canada ventilation standards and provincial building codes in Ontario, British Columbia, and Alberta reshape site selection economics. Demand concentrates in downtown financial districts and technology corridors.
Ontario
Enterprise hub-and-spoke adoption drives demand from Fortune 500 subsidiaries in Toronto's financial district. The Ontario Building Code imposes density limitations on shared environments that favor lower-occupancy private office configurations. CBRE Group leverages property management scale to secure Class A inventory in downtown Toronto, while technology freelancers cluster in the King Street West corridor.
British Columbia
Professional services firms generate network effects that attract adjacent knowledge workers to Vancouver's Yaletown corridor. Vancouver's adaptive reuse ordinances enable faster permitting for heritage building conversions than greenfield construction. Workhaus anchors its boutique design-forward positioning in this market, targeting law firms and financial advisory practices with confidentiality requirements.
Alberta
Energy sector downsizing has released Class A inventory suitable for premium repositioning in Calgary's Beltline sub-market. Alberta's municipal property tax reassessments on commercial conversions create input cost volatility that compresses operator margins. International Workplace Group plc competes through global membership portability that appeals to cross-border enterprise clients with centralized real estate functions.
Quebec
Montreal's technology freelancers and startup ecosystem sustain demand for flexible scaling from two to twenty seats. The province's extended permitting timelines for density modifications strain mid-scale operator development resources. Serendipity Labs and IQ Offices occupy positions within the membership-plan archetype, targeting month-to-month terms without lease renegotiation.
Canada Co-Working Office Spaces Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational agility. The vendor base separates into property management conglomerates, boutique design specialists, and global network operators. Three strategic archetypes dominate: scale-driven landlords leveraging Class A building relationships, differentiation-focused boutiques emphasizing curated aesthetics, and portability-enabled multinationals serving cross-border enterprise accounts. Competitive moves concentrate on municipal zoning arbitrage for adaptive reuse sites and API integration with enterprise facility management platforms.
Within the property management scale tier, CBRE Group and Jones Lang LaSalle exemplify landlords leveraging existing Class A relationships to bundle co-working with building services. Workhaus occupies a boutique specialist position emphasizing design-forward environments. International Workplace Group plc anchors the global portability archetype, serving multinational clients requiring standardized contractual terms across multiple locations. WeWork and Regus sit within the network-scale category, while IQ Offices and Serendipity Labs represent regional specialists targeting professional services density in corridor markets.
| Leading Market Players |
|---|
| CBRE Group |
| Workhaus |
| International Workplace Group plc |
| Serendipity Labs |
| IQ Offices |
| WeWork |
| Jones Lang LaSalle |
| ClickSpace |
| Regus |
| Others |
Value Chain & Pricing Dynamics
Hotel lobby workspace substitution for meeting rooms and hot desks simultaneously reshapes supply geography toward downtown cores and compresses pricing economics for standard-grade operators in secondary locations.
Pricing Analysis
Certification level from the Canada Green Building Council creates the primary spread between premium LEED-certified and standard-grade inventory. Three-tier pricing structure across premium, standard, and economy levels captures revenue based on ventilation density compliance and amenity bundling. Pricing pressure stems from municipal property tax reassessments on commercial conversions in Ontario, British Columbia, and Alberta. SMBs demonstrate the highest price sensitivity due to margin compression during tax reassessment cycles, while enterprises absorb premiums for standardized contractual terms.
Supply Chain Analysis
Strategic stockpiling of Class A building inventory in Toronto, Vancouver, and Calgary dominates over just-in-site activation due to extended permitting timelines. Supply draws from municipal zoning authorities, heritage building owners, and energy sector landlords releasing surplus space. HVAC filtration equipment and IoT occupancy sensors constitute critical component dependencies. Single-source vulnerability concentrates in certified construction trades for boutique design categories. Distribution runs through property management conglomerates with existing landlord relationships rather than direct developer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
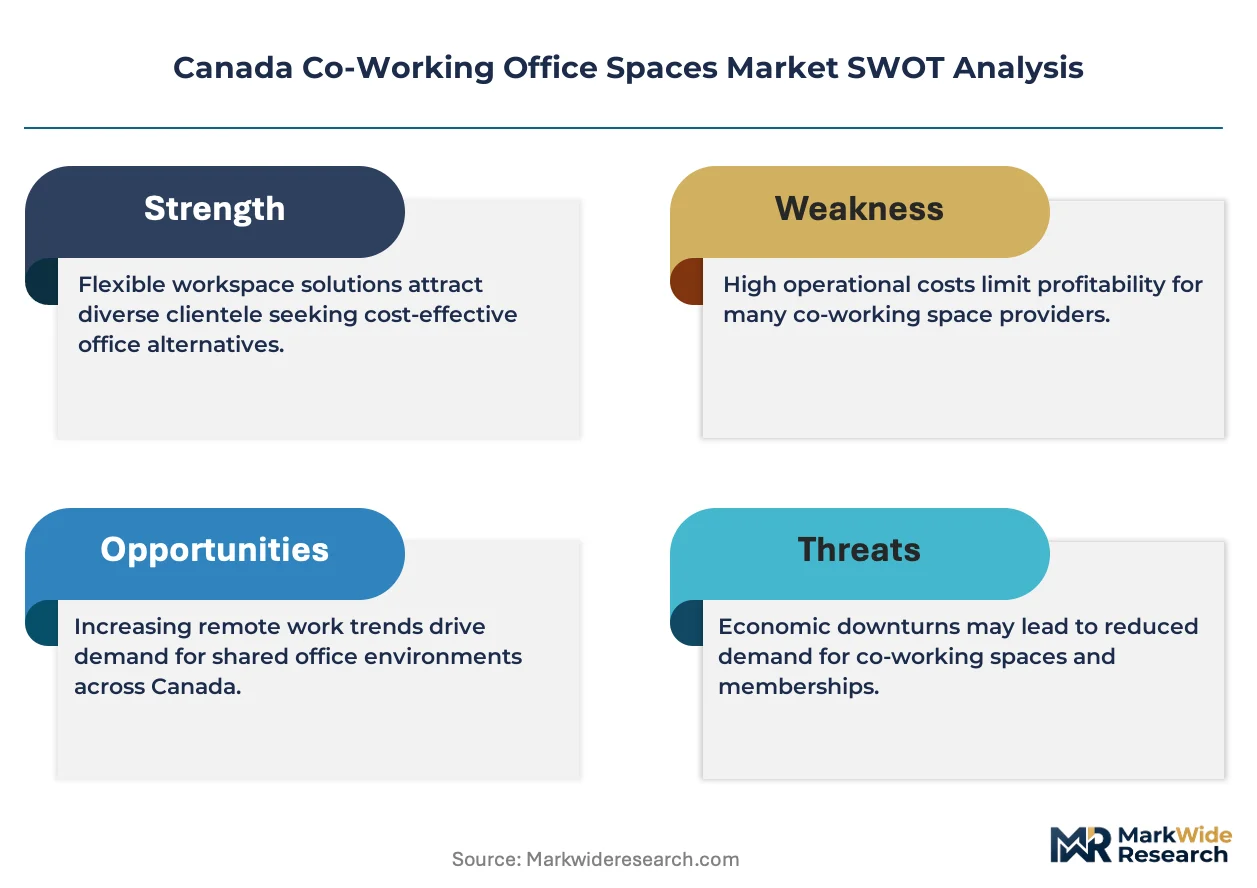
This market builds defensive moats through regulatory entrenchment: Health Canada ventilation standards and provincial building codes create compliance barriers that entrenched operators navigate more efficiently than challengers.
For Market Incumbents: Secure adaptive reuse site pipelines in Calgary's Beltline before zoning arbitrage windows close. Anchor positions through API integration with enterprise facility management platforms to raise switching costs for corporate clients. Certification investment in LEED standards defends against standard-grade competitors facing member attrition from ventilation upgrades. For New Entrants and Emerging Players: Lead with seasonal pay-per-use models targeting agricultural and tourism industries excluded by annual subscription commitments. Calgary's Beltline offers the most penetrable geography due to energy sector downsizing releasing Class A inventory. Go-to-market positioning should emphasize non-subscription billing structures unavailable from established subscription-dominant operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with boutique design-forward operators like Workhaus that have scaled regional footprints without national network integration. Long-term viability hinges on hub-and-spoke corporate adoption sustaining enterprise revenue concentration. The signal to watch is municipal property tax reassessment frequency crossing thresholds that compress operator margins on legacy leases.| Strategic Initiative | Industry Significance |
|---|---|
| LEED Certification Investment | Health Canada ventilation standards favor certified operators with pre-compliant HVAC infrastructure in Toronto. |
| API Integration with Enterprise FM Platforms | Corporate procurement departments demand standardized connectivity across distributed workspace deployments. |
| Calgary Beltline Site Acquisition | Energy sector downsizing releases Class A inventory at lower entry costs than Toronto or Vancouver cores. |
| Seasonal Pay-Per-Use Model Launch | Agricultural and tourism industries demonstrate latent demand excluded by annual membership commitments. |
| Global Network Portability Partnership | Cross-border enterprise clients require seamless workspace access across Canadian and international locations. |
Study Parameters
Initial hypotheses were tested against primary input from workspace operators, commercial real estate brokers, corporate facility managers, and municipal planning officials and refined through secondary validation. Primary interviews captured inventory activation timelines, lease structuring practices, and enterprise procurement criteria. Secondary sources included municipal zoning filings, Health Canada ventilation guidelines, provincial building code amendments, and property tax assessment records. Bottom-up location-level capacity estimates triangulated against top-down market value reconstructions.
Variance decomposition across the projection horizon isolates drivers including enterprise hub-and-spoke adoption velocity, municipal zoning reform implementation rates, and ventilation density compliance costs. Segmentation dimensions modeled encompass office type, target audience tier, service model structure, and interior design philosophy. CAGRs derive from rolling average growth rate calculations applied to membership count and revenue per member trajectories. Industry-specific forecast inputs include permitting timeline distributions and property tax reassessment schedules.
The analysis sits within stated boundaries; outcomes outside sustained municipal zoning reform momentum or stable commercial property tax regimes would require recalibration. Forecasts reflect documented assumptions regarding Health Canada guideline continuity and provincial building code harmonization. Revision becomes warranted when enterprise hub-and-spoke adoption velocity crosses thresholds that strain inventory activation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Market