
 Spain Commercial Real Estate Market | 2026-2036
Spain Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Commercial Real Estate Market Analytics
Urban planning talent and construction labor availability is bifurcating development timelines across Spain's major metros. Acciona leverages its integrated engineering-to-operations model to accelerate delivery of logistics and mixed-use assets. Hines Spain sustains institutional capital flows through core-plus positioning in Madrid's prime office submarkets. AQ Acentor differentiates via build-to-suit industrial platforms serving e-commerce fulfillment networks.
Spain commercial real estate encompasses income-producing properties including office, retail, industrial, and mixed-use assets traded on institutional, private, and public capital markets. These properties generate returns through contractual lease cash flows indexed to inflation or benchmark rates, with valuation methodologies applying discounted cash flow analysis against stabilized net operating income. Industrial and logistics assets within the property type dimension attract yield compression as last-mile delivery requirements reshape tenant requirements. Core and value-add strategies within the investment strategy dimension concentrate institutional allocation as pension funds seek inflation-hedged cash flows while opportunistic capital targets value creation through refurbishment or repositioning of aging office stock.
Spain's Ministry of Transport and Urban Agenda enforces energy certification mandates under the EU Energy Performance of Buildings Directive, compelling capital expenditure into thermal envelope upgrades and photovoltaic integration. The Bank of Spain's macroprudential guidelines on real estate lending constrain leverage availability for speculative development, filtering capital toward stabilized income-producing assets. Stakeholders must monitor regulatory tightening on operational carbon disclosure and assess how green premium dynamics redistribute tenant demand across Madrid, Barcelona, and emerging secondary logistics corridors.
Market Dynamics
Spain's Technical Building Code revision is compressing development timelines as developers front-load energy performance upgrades to secure occupancy permits ahead of enforcement deadlines.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandatory energy certification upgrades are redirecting tenant demand toward Class A buildings in Madrid and Barcelona.
- E-commerce fulfillment networks:Last-mile logistics requirements are expanding warehouse footprints across Valencia and Zaragoza corridors.
- Photovoltaic integration mandates:On-site renewable generation requirements are accelerating capital deployment into solar-ready industrial shells.
Market Restraints
- Construction labor scarcity:Skilled trades concentration in Madrid and Barcelona is extending delivery timelines for Barcelona peripheral projects.
- Bank of Spain macroprudential leverage caps:Speculative development financing constraints are filtering capital toward stabilized income-producing assets only.
- Steel and concrete input volatility:Material cost swings are compressing development margins on fixed-price contracts.
Strategic Opportunities
- Secondary logistics corridors:Underpenetrated markets around Málaga and Bilbao offer yield premiums for speculative industrial development.
- Operational carbon disclosure mandates:Upcoming EU Corporate Sustainability Reporting Directive requirements will advantage early movers with certified building portfolios.
- Life sciences conversion:Aging Barcelona office stock presents repositioning potential for laboratory and R&D facilities.
Industry Challenges
- Energy modeling expertise gap:Shortage of certified thermal envelope engineers is delaying Building Code compliance submissions.
- Utility interconnection queues:Grid connection backlogs for on-site solar are extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Commercial Real Estate Market |
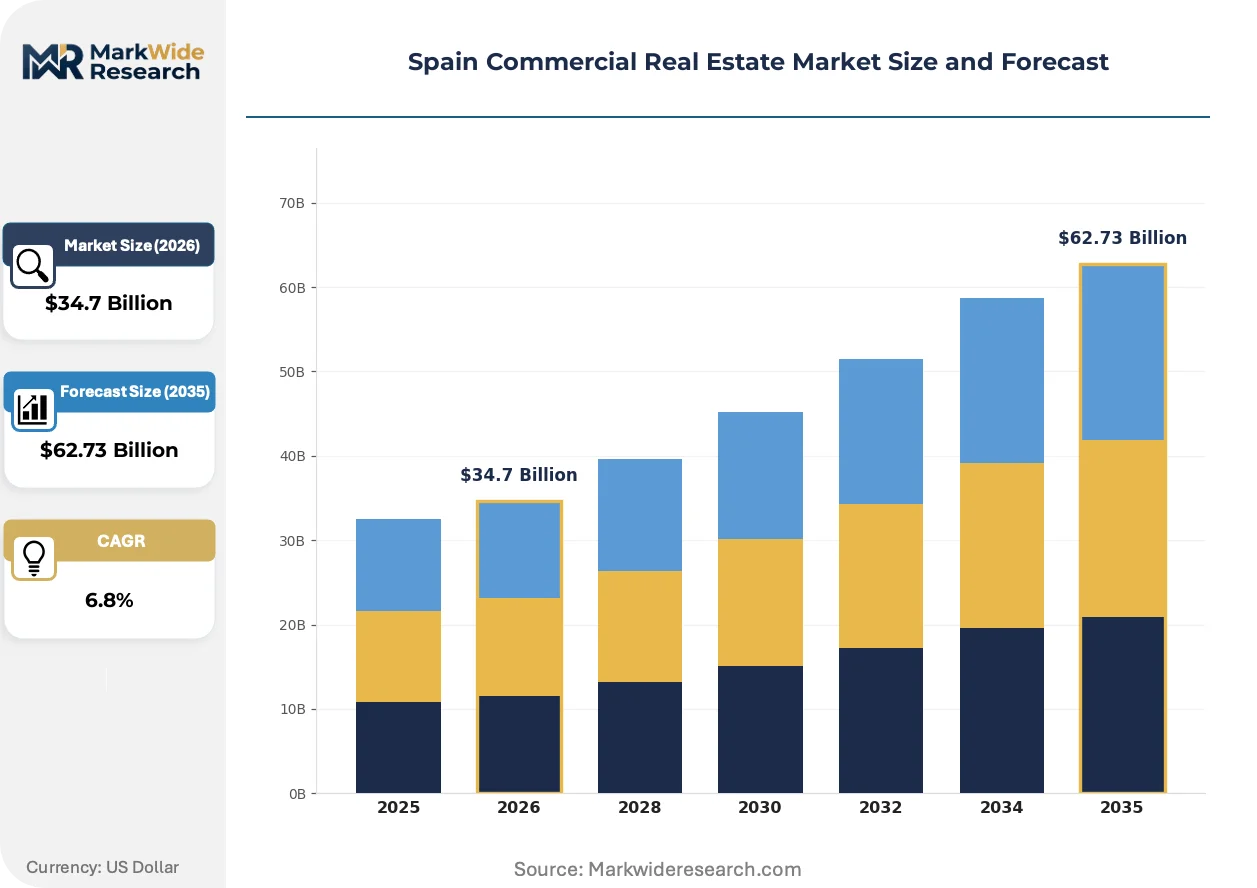
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Strategy: Core, Core-Plus, Value-Add, Opportunistic End User: Tenants, Landlords, Investors, Developers Transaction Size: Small, Medium, Large, Mega |
| Companies Covered | Acciona, Grupo FRANCA, AQ Acentor, INVERTICA-IRELS, Desarrollos Garcer, hi! Real Estate, Hines Spain, IBERIAN PROPERTY INVESTMENT PARTNERS, Realia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Commercial Real Estate Market Evolving Landscape
Digital twin platforms and predictive asset management systems are reshaping how Spanish institutional investors underwrite operational risk and optimize capital deployment across multi-asset portfolios.
Building-integrated photovoltaics is displacing conventional rooftop retrofits as the default specification for new logistics developments. Institutional developers in Madrid's northern corridor are mandating BIPV facades on speculative industrial shells to preempt tenant sustainability requirements. This specification shift is compressing cap rate spreads between certified and uncertified assets.
Spain's Ministry of Transport and Urban Agenda is accelerating energy certification enforcement timelines under transposed EU directives. Industrial developers must now submit thermal bridge calculations and airtightness testing prior to final occupancy approval. Logistics assets in Catalonia face the tightest compliance windows as regional authorities advance local implementation ahead of national deadlines.
Tenant sustainability reporting obligations are compressing lease renewal cycles for uncertified stock. Corporate occupiers in Madrid's CBD are prioritizing buildings with operational carbon disclosure platforms over traditional Class A specifications. Pharmaceutical and technology tenants demonstrate the strongest preference divergence, with some exiting secondary Barcelona submarkets lacking certification infrastructure.
Spain Commercial Real Estate Market Segmentation
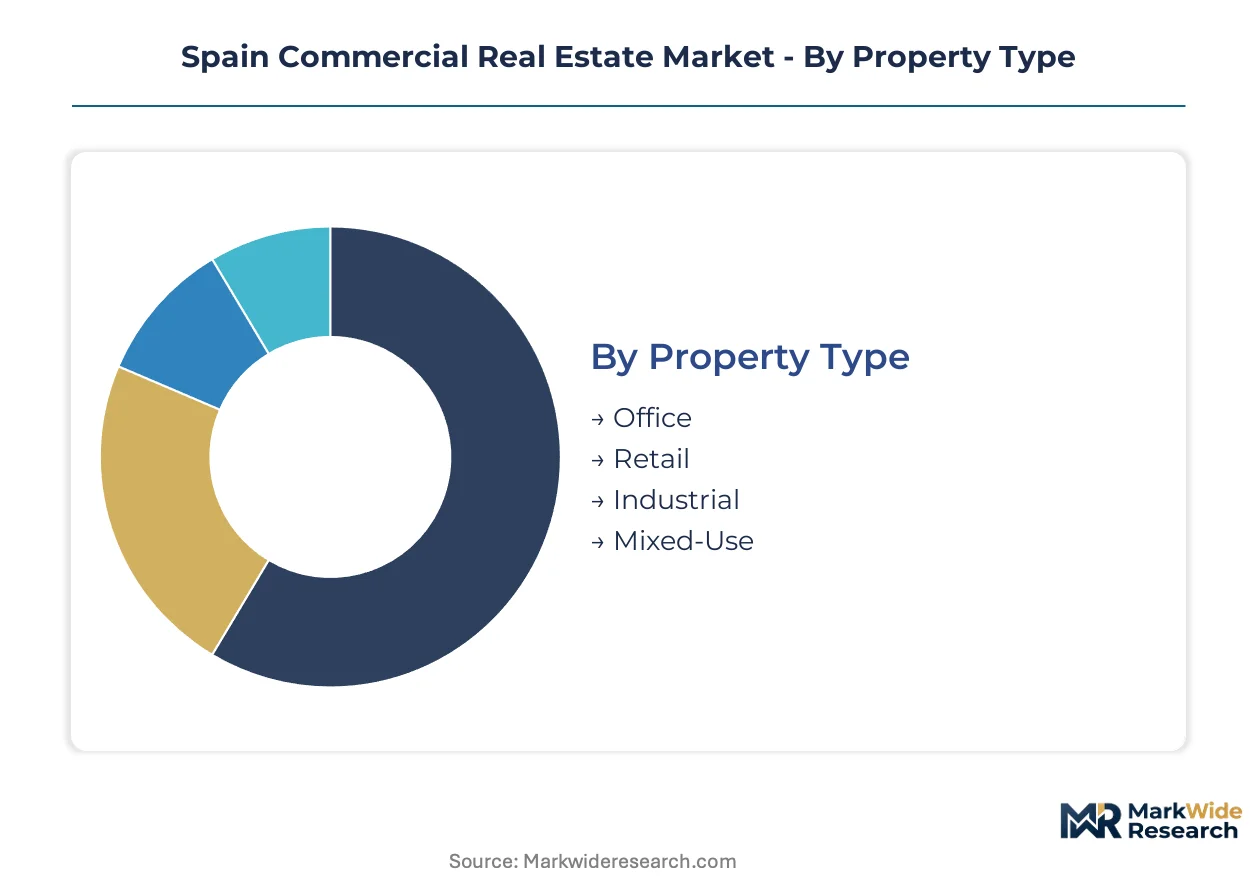
Segmentation in Spain commercial real estate reveals how capital flows bifurcate between stabilized income strategies and development risk. Each dimension captures distinct buyer profiles, financing structures, and regulatory exposure that shape transaction velocity across Madrid, Barcelona, and secondary corridors.
Property Type:
Channel mix varies sharply by property type, with institutional capital dominating office and logistics through prime Madrid submarkets while private investors concentrate in retail and mixed-use through regional broker networks.
- Office:Class A buildings in Madrid's northern business corridor and Barcelona's 22@ district command institutional allocation. Tenant demand concentrates among pharmaceutical and technology occupiers prioritizing operational carbon disclosure platforms over traditional specifications.
- Industrial:Logistics shells with solar-ready specifications and BIPV facades are displacing conventional warehouse stock. Last-mile fulfillment requirements are expanding footprints across Valencia and Zaragoza corridors where yield premiums persist.
- Retail:Neighborhood convenience formats and last-mile distribution nodes within mixed-use schemes are outperforming traditional high-street formats. Private capital dominates through value-add repositioning of aging Barcelona peripheral assets.
- Mixed-Use:Integrated office-residential-retail schemes in Madrid's CBD attract core-plus institutional flows. Development timelines extend due to Technical Building Code energy performance mandates and utility interconnection backlogs.
Office dominates installed base across institutional portfolios. Industrial is where expansion concentrates.
Investment Strategy:
Risk-return profiles stratify sharply by strategy type, with pension funds and insurance capital concentrating at the core end while sovereign wealth and opportunistic funds target value creation through refurbishment.
- Core:Stabilized assets with long-lease contracted cash flows indexed to inflation. Madrid prime office submarkets attract the deepest liquidity pools as Bank of Spain macroprudential leverage caps filter capital toward income-producing stock.
- Core-Plus:Mild value enhancement through lease rollover optimization or minor capital improvements. Barcelona 22@ assets with near-term tenant expirations offer yield pickup over pure core with controlled execution risk.
- Value-Add:Repositioning of aging office stock or industrial conversion requiring active asset management. Life sciences conversion of Barcelona peripheral office buildings presents specialized demand from pharmaceutical R&D tenants.
- Opportunistic:Ground-up development or complex restructuring with highest return thresholds. Secondary logistics corridors around Málaga and Bilbao attract speculative capital seeking yield premiums in underpenetrated markets.
Core strategies anchor institutional allocation. Value-Add is climbing the fastest as energy certification mandates create obsolescence risk in uncertified stock.
End User:
User type determines information asymmetry and transaction friction, with landlords and developers facing compressed timelines from regulatory enforcement while tenants and investors prioritize sustainability disclosure infrastructure.
- Tenants:Corporate occupiers with EU Corporate Sustainability Reporting Directive obligations are compressing lease renewal cycles for uncertified buildings. Pharmaceutical and technology tenants demonstrate strongest preference divergence toward certified assets.
- Landlords:Asset owners facing Technical Building Code compliance deadlines are front-loading thermal envelope upgrades and photovoltaic integration to secure occupancy permits.
- Investors:Institutional capital deploys through core-plus and value-add mandates seeking inflation-hedged cash flows. Due diligence now prioritizes operational carbon disclosure platforms and grid interconnection status.
- Developers:Speculative industrial developers in Catalonia face tightest compliance windows as regional authorities advance local implementation ahead of national deadlines.
Investors control transaction velocity in prime submarkets. Developers face the steepest margin compression from construction labor scarcity and material input volatility.
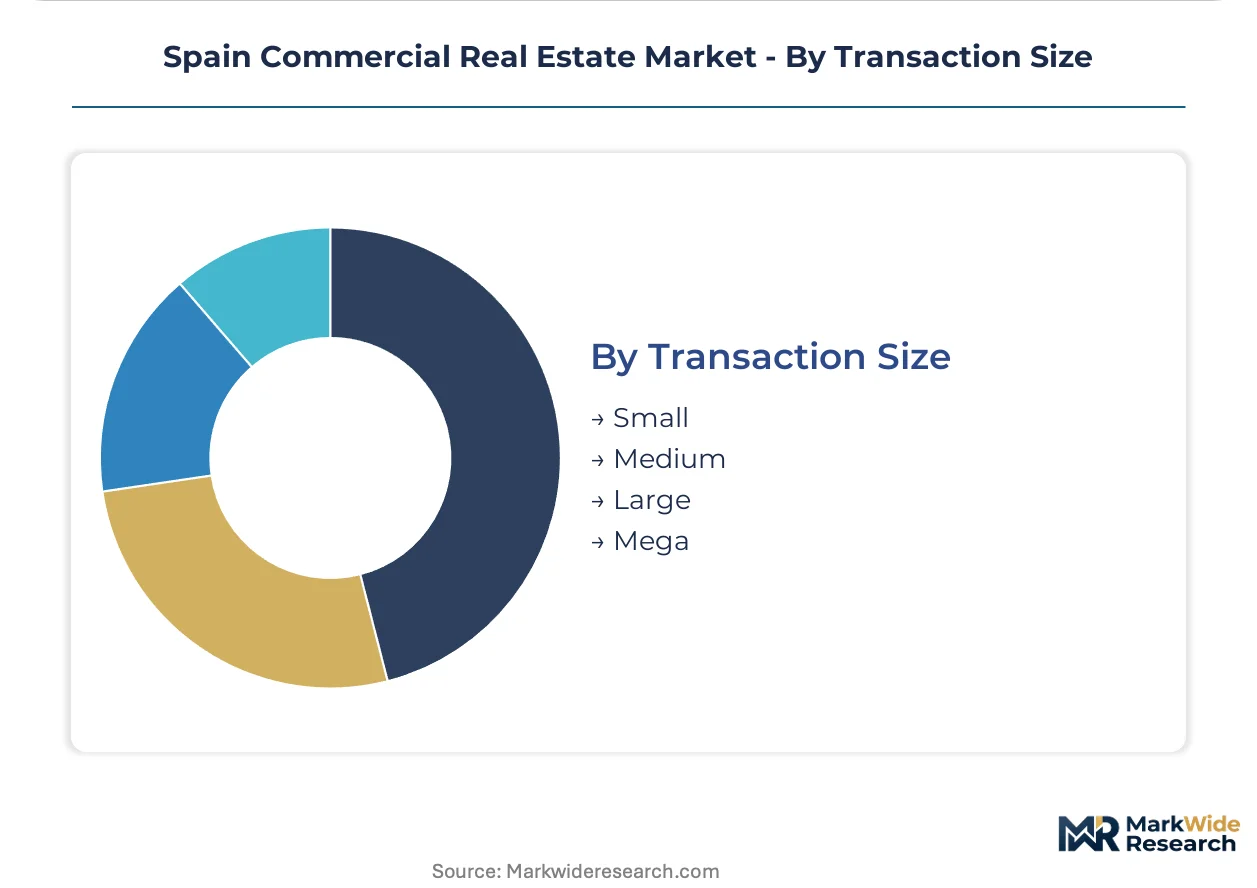
Transaction Size:
Deal size correlates with buyer type and financing source, with mega transactions requiring cross-border sovereign or pension capital while small and medium deals attract domestic private wealth and family offices.
- Small:Sub-institutional assets typically transacting through regional broker networks. Private investors concentrate here for yield in secondary retail and peripheral office markets.
- Medium:Single-asset or small portfolio acquisitions by domestic institutional capital and family offices. Logistics assets in Valencia and Zaragoza corridors frequently trade in this bracket.
- Large:Prime Madrid office buildings and stabilized logistics portfolios attracting international institutional capital. Core and core-plus strategies dominate at this threshold.
- Mega:Platform acquisitions or landmark mixed-use schemes requiring sovereign wealth or cross-border pension allocation. Limited supply in Spain relative to other European markets compresses deal flow.
Medium transactions dominate deal count. Mega deals concentrate institutional headlines but represent narrow volume share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid commands rental premiums 15-20% above Barcelona prime submarkets, while Valencia logistics corridors trade at yield spreads 75-100 basis points wider than capital region equivalents. This pricing-power asymmetry concentrates institutional allocation toward Madrid's northern business corridor and Barcelona's 22@ innovation district.
Madrid
Pharmaceutical headquarters relocations and technology R&D expansion drive Class A office absorption in the northern business corridor. Spain's Technical Building Code enforcement through the Ministry of Transport and Urban Agenda compels thermal envelope upgrades ahead of occupancy permitting. The Madrid-Barcelona logistics axis anchors national distribution networks with last-mile fulfillment nodes concentrating in Alcalá de Henares and San Fernando de Henares submarkets.
Catalonia
Life sciences conversion demand and e-commerce fulfillment requirements reshape tenant profiles across Barcelona's 22@ district and peripheral industrial zones. Regional authorities advance EU Energy Performance of Buildings Directive implementation ahead of national deadlines, compressing compliance timelines for speculative developers. Zona Franca and Sant Boi de Llobregat industrial parks attract photovoltaic-integrated logistics specifications from institutional capital seeking green-certified assets.
Basque Country
Advanced manufacturing reshoring and automotive supplier consolidation generate industrial warehouse demand around Bilbao and Vitoria-Gasteiz corridors. The Basque government's industrial decarbonization incentives accelerate capital deployment into energy-efficient production facilities. The Port of Bilbao logistics hinterland experiences yield compression as international investors target underpenetrated last-mile distribution infrastructure.
Andalusia
Tourism-related retail repositioning and residential-led mixed-use schemes concentrate development activity in Málaga and Seville metropolitan areas. Junta de Andalucía planning reforms streamline permitting for solar-ready industrial specifications in emerging logistics corridors. The Málaga-Córdoba axis attracts speculative warehouse development targeting Mediterranean shipping connectivity and Iberian Peninsula distribution reach.
Valencia
Port expansion and intermodal freight integration position Valencia as an alternative logistics gateway to saturated Mediterranean competitors. Regional energy certification mandates under transposed EU directives filter tenant demand toward Class A industrial stock. The Parc Logístic de Valencia and surrounding municipalities experience accelerated land absorption for e-commerce fulfillment platforms serving southeastern Spanish markets.
Spain Commercial Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spain's commercial real estate development ecosystem. The market structure concentrates around integrated engineering-to-operations platforms, institutional capital deployment vehicles, and specialized industrial developers. Three strategic archetypes dominate: vertically integrated infrastructure conglomerates with captive construction capabilities, global investment managers with dedicated Iberian platforms, and build-to-suit specialists serving e-commerce fulfillment networks. Competitive dynamics center on portfolio diversification into certified green assets and geographic expansion into secondary logistics corridors.
Among Madrid-based integrated developers, Acciona exemplifies the engineering-to-operations archetype through its infrastructure-to-real-estate value chain control. Hines Spain occupies a position within the global institutional capital deployment tier, channeling core-plus mandates toward prime Madrid office submarkets. AQ Acentor represents the build-to-suit specialization model, targeting industrial specifications for last-mile logistics tenants. These three anchors illustrate how divergent capabilities—construction integration, capital access, and tenant-specific development—define competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Acciona |
| Grupo FRANCA |
| AQ Acentor |
| INVERTICA-IRELS |
| Desarrollos Garcer |
| hi! Real Estate |
| Hines Spain |
| IBERIAN PROPERTY INVESTMENT PARTNERS |
| Realia |
| Others |
Value Network & Pricing Analysis
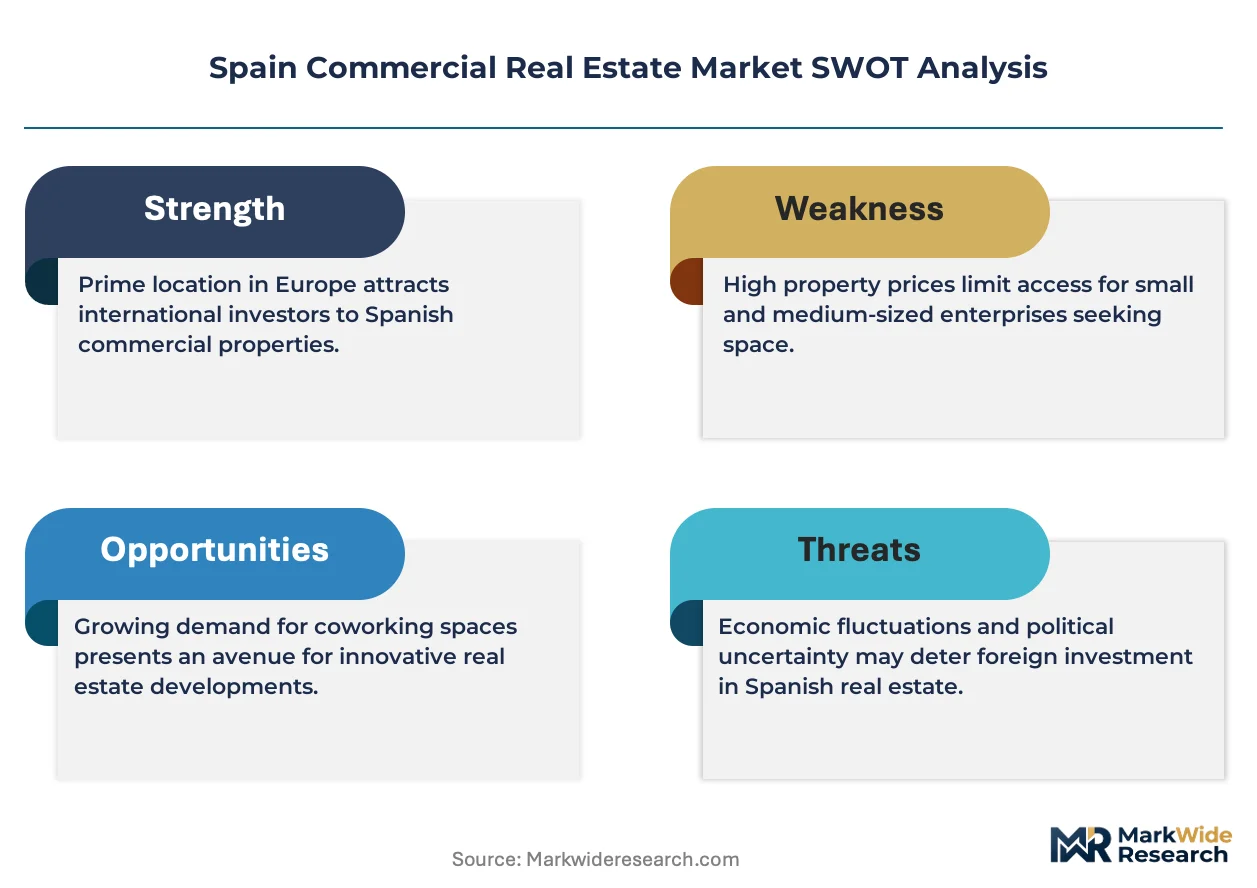
Spain's Technical Building Code certification regime gates both contractor qualification and asset price differentiation simultaneously. Developers without certified thermal envelope engineering capabilities face exclusion from prime Madrid and Barcelona submarkets while Class A buildings command rent premiums over uncertified stock.
Pricing Analysis
The customization-premium spread separates build-to-suit industrial specifications from speculative warehouse shells. Three-tier pricing structure across premium, standard, and economy levels tracks energy certification grade and photovoltaic integration depth. Cost compression in standard-tier logistics assets is intensifying because construction labor scarcity extends delivery timelines. Private investors in secondary retail markets exhibit highest price sensitivity while institutional capital in Madrid's northern corridor demonstrates lowest.
Supply Chain Analysis
Spain and Portugal anchor Iberian Peninsula construction materials production while Germany and Italy supply specialized building systems. Domestic supply draws from local steel fabrication, concrete batching, and ceramic cladding producers. Single-source vulnerability concentrates in imported photovoltaic modules and building automation controls. Distribution runs through regional construction merchant networks serving Madrid and Barcelona metropolitan areas with direct-to-site logistics for large-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain commercial real estate functions as a service-attach opportunity where facility management and energy optimization contracts expand faster than base rental income. Predictive asset management platforms and carbon disclosure infrastructure represent the fastest-growing recurring-revenue layers.
For Market Incumbents: Fortify portfolio positioning through accelerated certification of aging Barcelona office stock ahead of EU Corporate Sustainability Reporting Directive enforcement. Vertical integration into captive construction labor pools addresses skilled trades scarcity threatening development timelines. Channel control through preferred contractor networks secures priority access to thermal envelope engineering capacity. For New Entrants and Emerging Players: Operational carbon disclosure platform gaps in secondary logistics corridors offer white-space entry points where incumbents under-serve. Málaga and Bilbao industrial submarkets present the most penetrable geographies with yield premiums for speculative development. Build-to-suit specialization for pharmaceutical R&D tenants provides differentiated go-to-market positioning against generalized logistics developers. For Investors and Strategic Acquirers: Spain's EU Energy Performance of Buildings Directive transposition reshapes the acquisition landscape by obsolescing uncertified assets faster than replacement supply materializes. Long-term viability centers on stabilized income-producing stock with contracted lease escalations indexed to inflation. Platform acquisitions with integrated engineering capabilities represent optimal target archetype. Grid interconnection queue clearance rates signal inflection timing for solar-ready industrial deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Program | Front-loaded thermal envelope upgrades secure occupancy permits ahead of regional enforcement deadlines in Catalonia. |
| Photovoltaic Integration Mandate | On-site renewable generation requirements redirect tenant demand toward Class A industrial specifications in Madrid. |
| Secondary Corridor Expansion | Speculative warehouse development in Málaga and Bilbao corridors captures yield premiums in underpenetrated logistics markets. |
| Life Sciences Conversion | Repositioning of aging Barcelona office stock addresses specialized demand from pharmaceutical R&D tenants. |
| Digital Twin Platform Deployment | Predictive asset management systems optimize capital deployment across multi-asset institutional portfolios. |
Research Methodology
A spread of perspectives from development executives, asset managers, construction contractors, and tenant sustainability officers converged on the working assumptions. Primary interviews with logistics operators and pharmaceutical facility directors combined with secondary validation against Bank of Spain macroprudential reports, Ministry of Transport and Urban Agenda regulatory filings, and EU Energy Performance of Buildings Directive implementation timelines. Bottom-up project pipeline analysis and top-down capital flow tracking provided triangulation.
Segmentation dimensions modeled span property type, investment strategy, end user category, and transaction size tier across the analysis window. CAGRs derive from stabilized net operating income projections against discounted cash flow valuation benchmarks. Forecast inputs incorporate construction labor availability indices and utility interconnection queue status for solar-ready industrial specifications.
Underlying assumptions cover regulatory enforcement timelines and tenant sustainability reporting adoption rates, with deviation risk concentrated in regional implementation acceleration and material input cost volatility. Recalibration cycles align with material shifts in energy certification mandates and macroprudential leverage guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market