
 Saudi Arabia Real Estate Market | 2026-2036
Saudi Arabia Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Real Estate Market Outlook
The Saudi Building Code is broadening the cost-of-entry calculus for developers across the Kingdom. Dar Al Arkan Real Estate Development Company leverages its vertical build capabilities to control project timelines in key corridors. Red Sea Global anchors its position through tourism-integrated master planning along the western coastline. Emaar The Economic City competes by sustaining large-scale industrial and residential mixed-use footprints near King Abdullah Economic City.
Saudi Arabia real estate encompasses land, built structures, and development rights governed by technical specifications including seismic load-bearing standards of 0.15g peak ground acceleration and thermal insulation mandates for building envelopes exceeding 45°C ambient design temperatures. Its primary purpose is to facilitate residential habitation, commercial enterprise, and industrial production within a Sharia-compliant ownership framework. Residential property leads transaction volumes, while mixed-use developments capture expanding margin pools as planners integrate live-work-retail environments. Institutional investor participation in commercial assets deepens as REIT structures mature under CMA oversight, and luxury vacation properties along coastal zones represent the fastest-growing market segment.
SFDA construction material standards, the Saudi Building Code administered by the National Committee for Building Code, and CMA real estate investment fund regulations collectively shape developer compliance burdens and product specifications. These frameworks elevate quality benchmarks, restrict substandard imports, and channel capital toward regulated investment vehicles. Stakeholders must monitor permit approval velocity in Riyadh and Jeddah municipalities as an early signal of supply pipeline health and pricing trajectory direction.
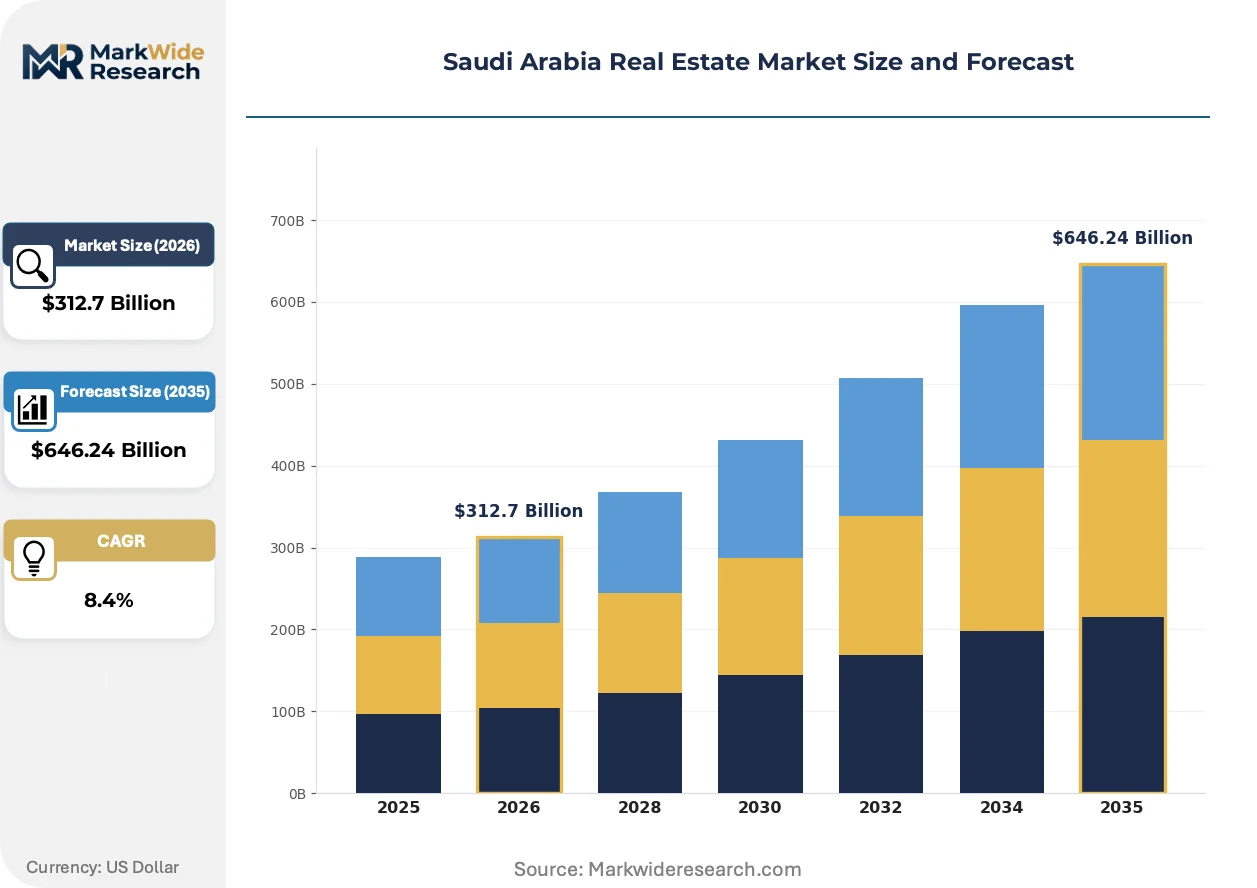
Market Dynamics
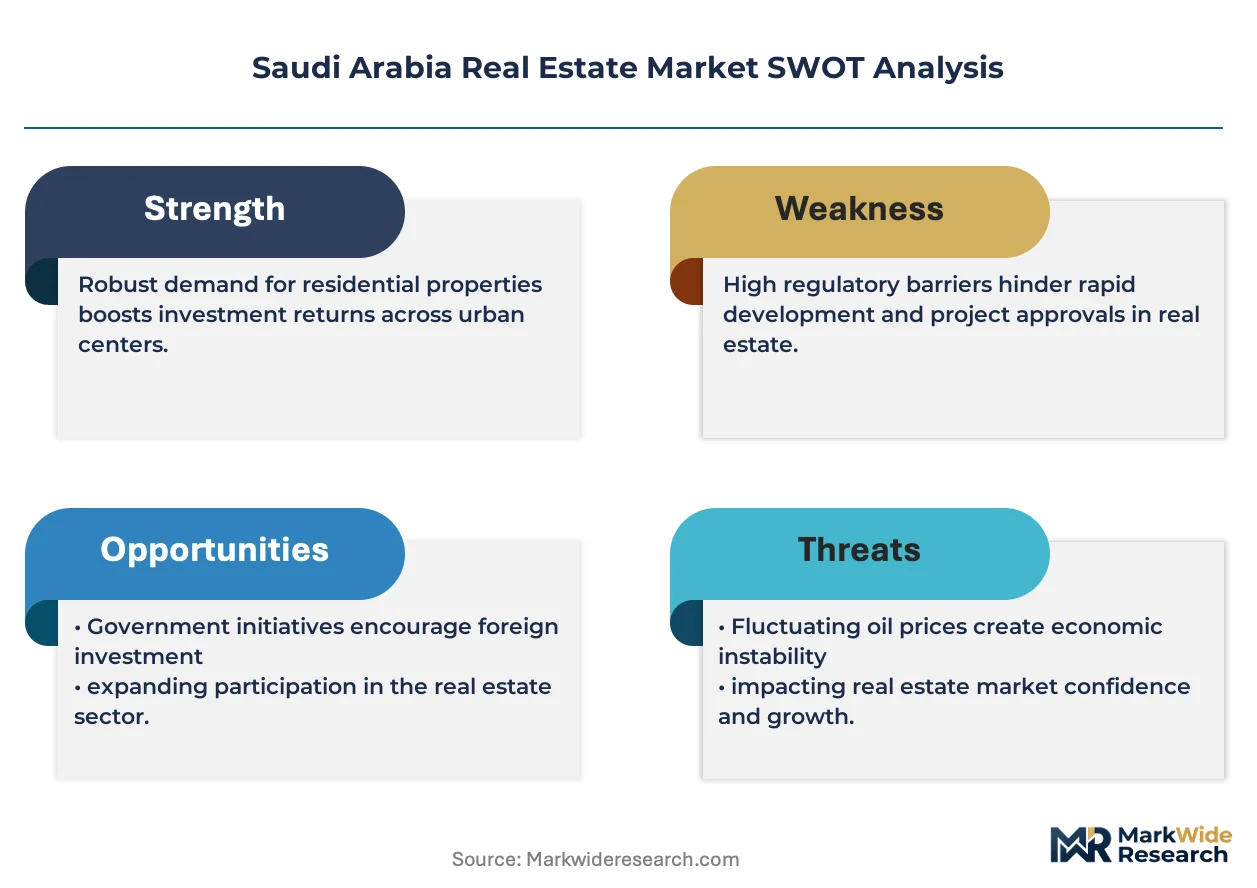
The Saudi Building Code administered by the National Committee for Building Code is tightening seismic load-bearing and thermal insulation mandates, forcing developers to recalibrate cost structures and procurement strategies across residential and commercial pipelines.
Growth Catalysts
- Vision 2030 housing targets:The government's million-unit housing program is accelerating land release and mortgage subsidy flows, pulling first-time buyers into formal ownership structures.
- REIT market maturation under CMA oversight:Real estate investment trusts are channeling institutional capital into income-generating commercial assets, deepening secondary market liquidity.
- Red Sea tourism corridor development:Master-planned coastal communities are integrating hospitality and residential inventory, creating new buyer segments among expatriate professionals and regional investors.
Market Restraints
- Construction material import dependency:SFDA-aligned certification requirements for steel and cement are restricting supplier pools and extending lead times for compliant sourcing.
- Skilled labor concentration in Riyadh and Jeddah:Project management and engineering talent clusters in two metros, inflating wage costs for developments in secondary cities.
- Financing cost sensitivity:Mortgage rate movements directly compress affordability ceilings for middle-income buyers, constraining absorption velocity in standard-grade inventory.
Strategic Opportunities
- Neom and Qiddiya master plans:Giga-project zones offer first-mover positioning for developers with vertical build capabilities and government contracting relationships.
- Elderly and assisted living housing:Demographic aging in Saudi urban centers is creating unmet demand for age-in-place residential products with integrated healthcare access.
- Green building certification adoption:LEED and Mostadam standards are unlocking preferential financing terms and municipal fast-tracking for compliant developments.
Industry Challenges
- Permit approval velocity volatility:Municipal processing timelines in Riyadh and Jeddah fluctuate unpredictably, disrupting project cash flow forecasting and construction sequencing.
- Legacy utility infrastructure gaps:Master-planned communities in northern Riyadh and Jeddah waterfront districts require co-investment in power and water distribution, elevating upfront capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Real Estate Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Mixed-Use Investor Type: Institutional, Retail, Foreign, Government Development Stage: Planning, Under Construction, Completed, Renovation Market Segment: Luxury, Mid-Range, Affordable, Vacation |
| Companies Covered | Arriyadh Development Co., Saudi Real Estate Company, Jabal Omar Development Company, RAFAL Real Estate, Knowledge Economic City, Dar Al Arkan Real Estate Development Company, Emaar The Economic City, Red Sea Global, Taiba Investments Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Real Estate Market Strategic Shifts
Digital construction workflows and modular fabrication methods are compressing project delivery timelines while regulatory pressure on building performance is elevating material specification standards.
Building information modeling integrated with drone-based site surveying is rewriting how developers coordinate multi-phase master plans. Large-scale residential operators in Riyadh's northern corridor are deploying these tools to compress design-to-handover cycles. The structural consequence is collapsing contingency buffers in construction scheduling and forcing subcontractors into tighter performance contracts.
The Saudi Building Code's thermal insulation mandates for envelopes exceeding 45°C ambient design temperatures are elevating specification costs for glazing and cladding systems. Developers are responding by front-loading energy modeling into early design phases. Mixed-use projects in Jeddah's waterfront district face the steepest compliance cost increments due to glass-intensive architectural briefs.
Institutional buyers are consolidating direct relationships with master-planned community developers, bypassing traditional brokerage channels for bulk residential acquisitions. Sovereign wealth fund affiliates and regional family offices are leading this shift in Riyadh's northern corridor. The compression of intermediary layers is visible most acutely in transactions exceeding fifty units, where developers now maintain dedicated institutional sales desks.
Saudi Arabia Real Estate Market Segmentation
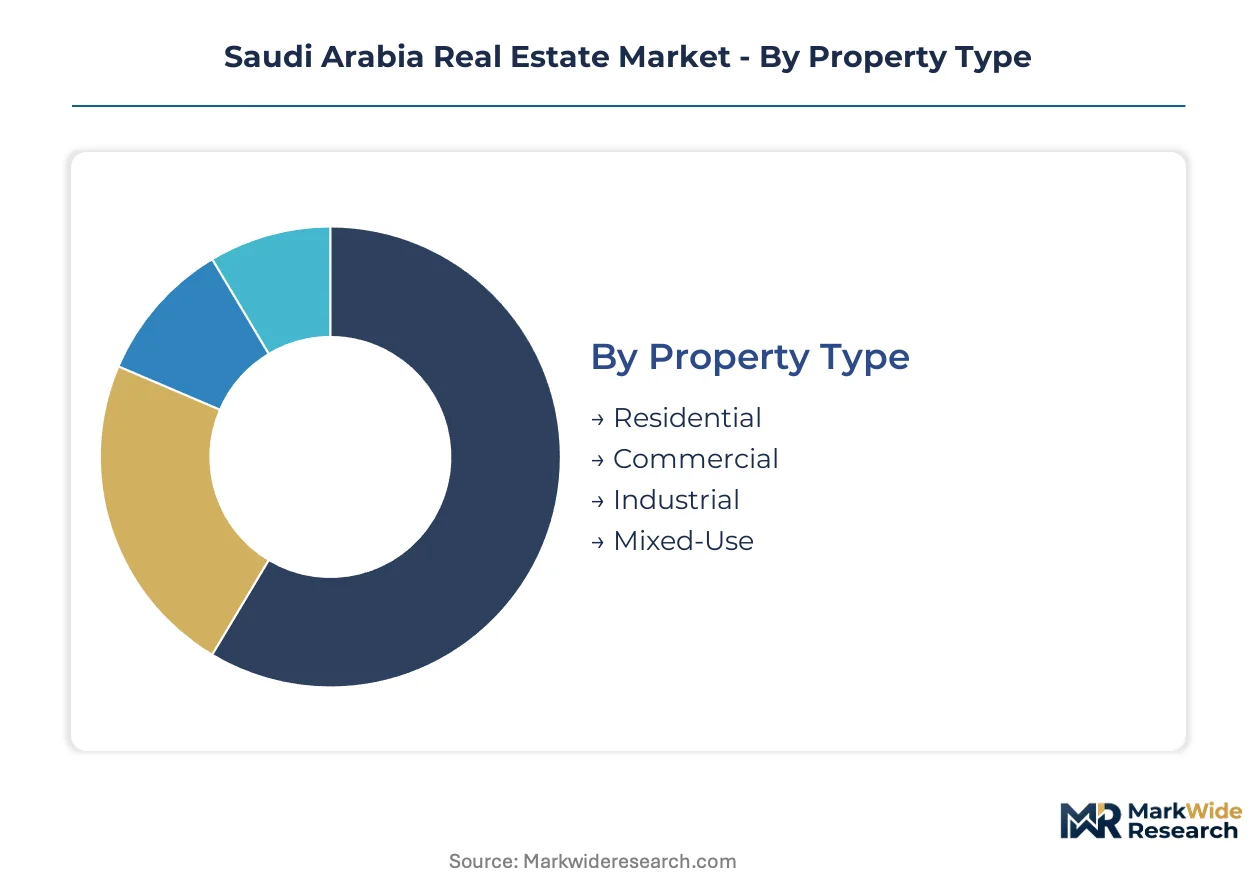
Segmentation in Saudi Arabia real estate reveals how capital flows, regulatory frameworks, and buyer demographics intersect across distinct property categories. Understanding these divides enables developers to align product specifications with compliance thresholds and financing structures.
Property Type:
Standalone residential developments dominate transaction volumes, while mixed-use and industrial assets embed into broader economic zone master plans.
- Residential:Single-family villas and apartment compounds absorb the majority of mortgage subsidy flows under Vision 2030 housing targets. Demand concentrates in Riyadh's northern corridor and Jeddah's waterfront district as master-planned communities reshape buyer preferences toward gated environments with integrated amenities.
- Commercial:Office towers and retail centers face tightening Saudi Building Code mandates for seismic load-bearing and thermal insulation. Institutional capital channels into income-generating assets through CMA-regulated REIT structures, deepening secondary market liquidity for grade-A inventory in prime districts.
- Industrial:Logistics facilities and manufacturing plants cluster near King Abdullah Economic City and Jubail Industrial City. SFDA-aligned construction material standards elevate foundation and cladding specifications for heavy-load environments.
- Mixed-Use:Live-work-retail environments capture expanding margin pools as planners integrate residential towers with ground-floor retail and co-working infrastructure. Developments in Neom and Qiddiya giga-project zones lead this format.
Residential leads volumes today; mixed-use is gaining share fastest.
Investor Type:
Capital source determines holding period expectations, leverage capacity, and regulatory compliance pathways across the Kingdom's property markets.
- Institutional:Pension funds and sovereign wealth affiliates deploy capital through regulated REIT vehicles. CMA oversight mandates disclosure standards that elevate due diligence costs but unlock preferential financing terms from Saudi banks.
- Retail:Individual buyers access mortgage subsidies through the Real Estate Development Fund. Affordability ceilings compress absorption velocity when central bank rates shift, constraining demand for standard-grade inventory.
- Foreign:Regional family offices and expatriate professionals target luxury vacation properties along the Red Sea coast. Red Sea Global's master-planned communities anchor this segment through tourism-integrated residential products.
- Government:Ministry of Housing and municipal development authorities accelerate land release in priority corridors. Public-sector contracting relationships determine pipeline access for developers with vertical build capabilities.
Retail investors anchor transaction counts; institutional capital is expanding most quickly.
Development Stage:
Stage positioning dictates cash flow profiles, risk exposure to permit volatility, and buyer financing eligibility under Saudi mortgage regulations.
- Planning:Pre-construction sales require municipal approval velocity that fluctuates unpredictably in Riyadh and Jeddah. Developers front-load Saudi Building Code compliance documentation to accelerate permitting timelines.
- Under Construction:Active sites face skilled labor concentration in Riyadh and Jeddah, inflating wage costs for developments in secondary cities. Modular fabrication methods compress delivery timelines in this phase.
- Completed:Handover-ready inventory commands premium pricing but carries holding cost exposure. REIT acquisition targets concentrate on stabilized assets with demonstrable rental income streams.
- Renovation:Existing stock upgrades align with thermal insulation mandates for envelopes exceeding 45°C ambient design temperatures. Energy modeling integration unlocks municipal fast-tracking for compliant retrofits.
Under-construction assets dominate developer pipelines; renovation activity is climbing the fastest.
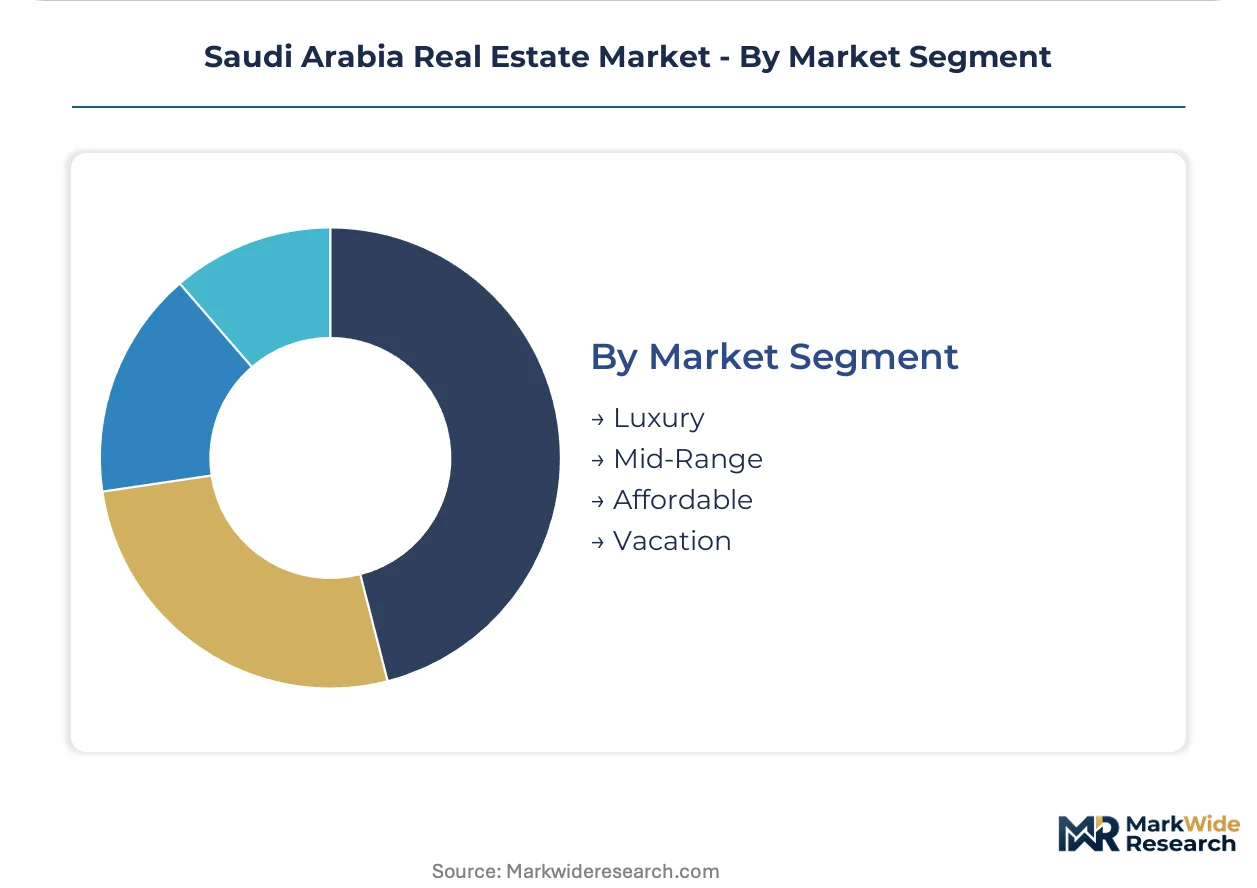
Market Segment:
Price tier alignment shapes material specifications, buyer financing structures, and marketing channel selection across Saudi development portfolios.
- Luxury:High-end villas and penthouses incorporate glazing and cladding systems meeting stringent Saudi Building Code thermal performance thresholds. Red Sea coastal developments draw heightened institutional interest for tourism-integrated hospitality hybrids.
- Mid-Range:Standard-grade apartments and townhouses absorb the bulk of first-time buyer demand. Mortgage rate sensitivity directly compresses affordability ceilings in this tier.
- Affordable:Entry-level units target Vision 2030 housing program beneficiaries. Land release acceleration in northern Riyadh and eastern Jeddah supports volume delivery.
- Vacation:Secondary residences for regional investors and expatriate professionals represent the steepest expansion trajectory. Red Sea Global's coastal master plans anchor supply growth in this segment.
Mid-Range inventory leads absorption volumes; Vacation properties show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering and project management talent concentrates in Riyadh and Jeddah, anchoring development velocity in these metros while secondary cities face wage inflation and skill shortages.
Riyadh
Vision 2030 housing targets and million-unit programs accelerate land release in the northern corridor. The Saudi Building Code administered by the National Committee for Building Code tightens seismic and thermal compliance for new developments. Master-planned communities reshape buyer preferences toward gated environments with integrated amenities.
Jeddah
Waterfront district regeneration and Red Sea tourism corridor integration pull expatriate professionals and regional investors into luxury vacation properties. SFDA-aligned construction material standards restrict supplier pools for steel and cement imports. Glass-intensive architectural briefs in mixed-use projects face steepest compliance cost increments.
Eastern Province
Industrial production and logistics facilities cluster near Jubail Industrial City as petrochemical expansion sustains demand for heavy-load construction. SFDA construction material standards elevate foundation and cladding specifications. Secondary cities here struggle with skilled labor concentration gaps that inflate project management costs.
NEOM Northwest
Giga-project zones offer first-mover positioning for developers with vertical build capabilities and government contracting relationships. CMA real estate investment fund regulations channel institutional capital toward regulated vehicles. Modular fabrication methods and digital construction workflows compress design-to-handover cycles.
Saudi Arabia Real Estate Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across residential, commercial, and tourism-integrated segments. The market structure tieres between scale-driven master-plan developers and niche operators targeting specific buyer segments. Three archetypes dominate: government-linked developers with land bank access, vertically integrated builders controlling project timelines, and tourism-focused specialists anchoring coastal zones. Competitive moves concentrate on strategic partnerships for giga-project positioning and portfolio diversification into mixed-use formats.
Among Riyadh-based developers, Arriyadh Development Co. and Saudi Real Estate Company occupy positions within the government-linked archetype, leveraging public-sector relationships for priority corridor access. Red Sea Global anchors the tourism-specialist tier through coastal master planning. Dar Al Arkan Real Estate Development Company exemplifies vertical integration capabilities that compress delivery timelines.
| Leading Market Players |
|---|
| Arriyadh Development Co. |
| Saudi Real Estate Company |
| Jabal Omar Development Company |
| RAFAL Real Estate |
| Knowledge Economic City |
| Dar Al Arkan Real Estate Development Company |
| Emaar The Economic City |
| Red Sea Global |
| Taiba Investments Co. |
| Others |
Value Chain & Pricing Dynamics
Institutional buyers consolidating bulk residential acquisitions in Riyadh's northern corridor anchor project-based pricing structures that bundle construction milestones with post-handover service commitments. This concentration grants volume purchasers leverage over unit economics while compressing intermediary margins for standard-grade inventory.
Pricing Analysis
Project-based pricing with bundled after-sales service dominates residential developments, separating luxury coastal villas with tourism-integrated hospitality features from mid-range apartments with mortgage-subsidy eligibility and affordable entry-level units. Price differentiation rests on Saudi Building Code compliance tier and seismic certification grade, with glass-intensive mixed-use projects in Jeddah's waterfront district facing steepest cost increments. Pricing pressure stems from SFDA-aligned material certification requirements restricting supplier pools. Retail investors accessing Real Estate Development Fund subsidies exhibit highest price sensitivity; sovereign wealth affiliates show lowest.
Supply Chain Analysis
SFDA certification requirements for steel and cement imports gate supplier participation, compressing qualified vendor pools and extending procurement timelines for compliant sourcing. Material supply concentrates in China, India, and UAE as primary import sources for construction-grade steel, cement, and glazing systems. Raw material dependencies center on iron ore, petrochemical feedstocks for insulation materials, and high-performance glass composites. Single-source vulnerability runs through specialized seismic-grade steel suppliers. Distribution feeds through developer-direct procurement for giga-projects and municipal-contractor networks for standard residential pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia real estate functions as a geographic-arbitrage play where developers with vertical build capabilities extract timeline premiums in Riyadh and Jeddah while secondary cities suffer wage inflation from skilled labor scarcity.
For Market Incumbents: To counter permit approval velocity volatility in Riyadh and Jeddah municipalities, front-load Saudi Building Code compliance documentation and anchor project pipelines in government-contracting relationships that accelerate municipal processing. Prioritize backward integration into modular fabrication methods to compress design-to-handover cycles and reduce exposure to skilled labor concentration gaps. For New Entrants and Emerging Players: Capture elderly and assisted living housing white-space in Saudi urban centers where demographic aging creates unmet demand for age-in-place residential products with integrated healthcare access. Target vacation property development along Red Sea coastal zones where Red Sea Global's master plans validate institutional investor appetite. Pursue green building certification adoption as primary go-to-market angle to unlock preferential financing terms and municipal fast-tracking. For Investors and Strategic Acquirers: Sovereign wealth fund affiliates are the most active acquirer in this space, consolidating direct relationships with master-planned community developers for bulk residential acquisitions exceeding fifty units. Acquisition target archetype: vertically integrated developers with government land bank access and demonstrated delivery timelines in giga-project zones. Watch permit approval velocity in Riyadh and Jeddah municipalities as inflection indicator for supply pipeline health and pricing trajectory direction.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Adoption | LEED and Mostadam standards unlock preferential Saudi bank financing terms and municipal fast-tracking for compliant developments. |
| Modular Fabrication Method Deployment | Digital construction workflows compress project delivery timelines while reducing exposure to skilled labor concentration in Riyadh and Jeddah. |
| Institutional Sales Desk Establishment | Dedicated desks capture bulk acquisition flows from sovereign wealth affiliates bypassing traditional brokerage channels. |
| SFDA Certification Investment | Construction material compliance documentation accelerates municipal permitting velocity and restricts competitor supplier pools. |
| Giga-Project Zone Positioning | Neom and Qiddiya master plans offer first-mover positioning for developers with government contracting relationships and vertical build capabilities. |
Study Parameters
Bottom-up residential transaction modeling reconciled against top-down construction permit tracking forms the analytical core of this study. Primary interviews with master-planned community developers, municipal planning officers, REIT fund managers, and Saudi bank real estate lending heads combine with secondary validation from Saudi Building Code documentation, CMA REIT regulatory filings, Ministry of Housing land release announcements, and customs import data for construction materials. Triangulation across these sources ensures supply pipeline estimates align with demand absorption metrics.
Historical trendline analysis of transaction volumes, permit approvals, and mortgage subsidy flows establishes baseline growth patterns across the projection horizon. Segmentation dimensions modeled include property type, investor category, development stage, and market price tier, with regional regulatory cluster and Saudi Building Code compliance tier as industry-specific additions. CAGRs derive from slope analysis of normalized trendlines adjusted for Vision 2030 policy intervention timing and REIT market maturation trajectories under CMA oversight. Forecast inputs incorporate thermal insulation mandate cost pass-through estimates and seismic load-bearing specification shifts.
Municipal processing timeline volatility, mortgage rate movement sensitivity, and construction material import certification delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding policy continuity for Vision 2030 housing targets and CMA regulatory framework stability. A model refresh is warranted upon material change in permit approval velocity or SFDA construction material standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Flexible Office Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Europe Office Real Estate Market