
 Brazil LNG Market | 2026-2036
Brazil LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil LNG Market Outlook
Terminal access routes in Brazil is tilting toward floating storage and regasification unit (FSRU) moorings as developers bypass onshore construction bottlenecks. Petroleo Brasileiro S.A. leverages its legacy pipeline network to dominate coastal distribution corridors. New Fortress Energy anchors greenfield terminal projects at underutilized ports. Shell plc competes through integrated LNG-to-power offerings that bundle fuel supply with generation assets.
Liquefied natural gas (LNG) consists predominantly of methane (CH₄ exceeding 85% by volume) cooled to approximately minus 162 degrees Celsius for maritime transport in cryogenic vessels, then regasified for injection into pipeline systems or direct industrial combustion. Power Generation applications lead volume absorption due to grid reliability mandates and hydroelectric shortfall coverage. Industrial Heating segments sustain premium pricing through dedicated direct-supply contracts with mining and petrochemical complexes. Marine Fuel adoption accelerates as port authorities enforce sulfur emission thresholds on coastal shipping.
ANP (Agência Nacional do Petróleo, Gás Natural e Biocombustíveis) governs LNG import licensing and terminal safety standards, while ANTT regulates pipeline interconnect tariffs that shape delivered cost economics. IBAMA environmental licensing timelines constrain brownfield expansion velocity, pushing developers toward pre-certified FSRU platforms. Stakeholders must monitor regulatory clarity on third-party access to Petrobras legacy infrastructure as this determines competitive entry economics for independent terminal operators.
Market Dynamics
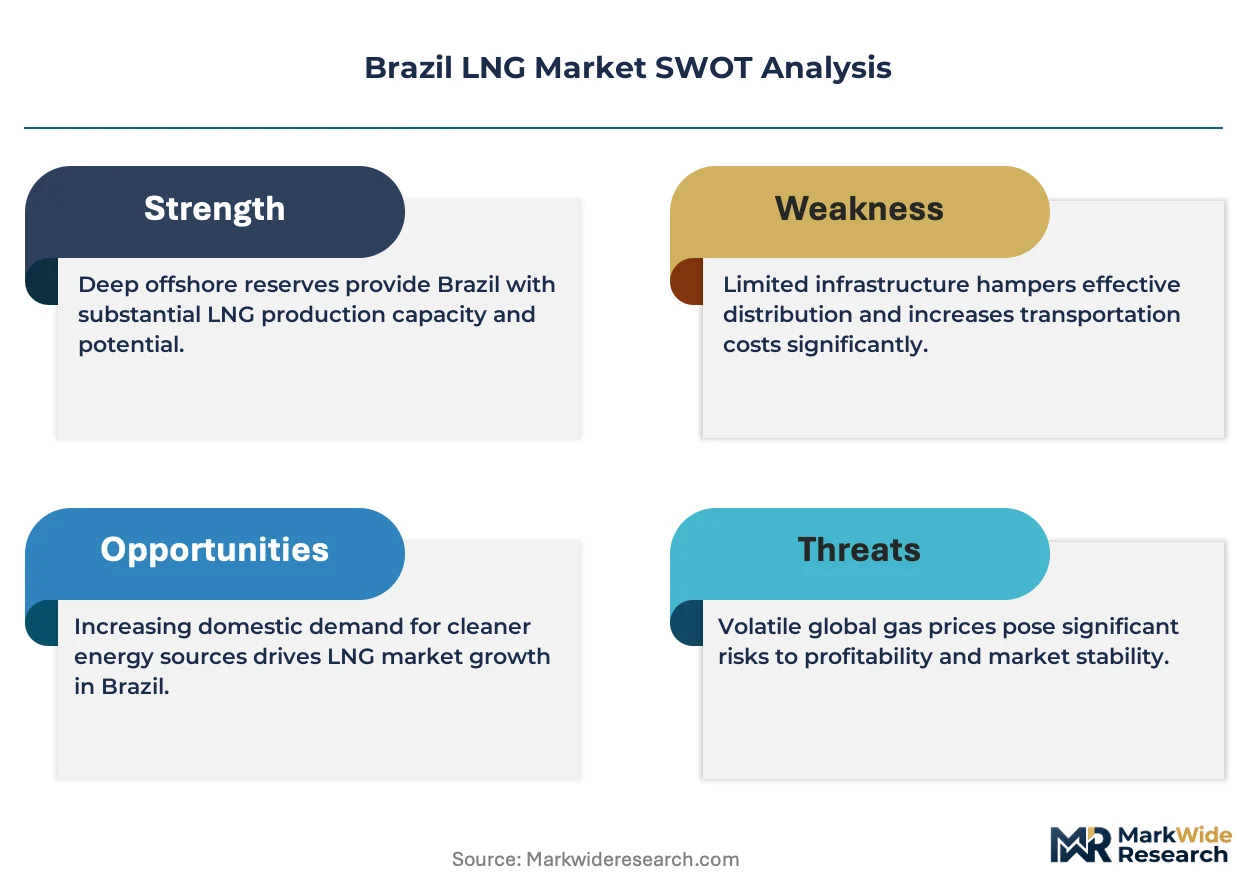
Floating regasification technology is compressing terminal construction timelines while ANP's downstream liberalization dismantles Petrobras import monopolies. This dual structural shift is redrawing competitive entry economics across Brazil's coastal corridor.
Growth Catalysts
- ANP downstream liberalization:Third-party access mandates to legacy infrastructure are unlocking import terminal development for independent operators previously blocked by vertical integration.
- Power generation reliability mandates:Grid operators must secure firm backup capacity to cover hydroelectric shortfalls during drought cycles in the Southeast industrial corridor.
- Floating storage and regasification units (FSRUs):Pre-certified offshore platforms bypass IBAMA's protracted onshore environmental licensing timelines.
Market Restraints
- Pipeline tariff structures:ANTT-regulated interconnect fees inflate delivered costs for non-Petrobras terminal operators accessing coastal distribution corridors.
- FSRU vessel availability:Global fleet concentration among a limited pool of specialized owners creates charter rate volatility and deployment bottlenecks.
- Diesel backup competition:Existing dual-fuel power plants retain operational flexibility to switch to liquid fuel when LNG spot prices spike.
Strategic Opportunities
- Marine fuel bunkering:Port authorities in Santos and Rio de Janeiro are enforcing sulfur emission thresholds that displace heavy fuel oil in coastal shipping.
- Industrial direct-supply contracts:Mining and petrochemical complexes in Minas Gerais and Bahia seek dedicated pipeline connections bypassing wholesale gas markets.
- Small-scale distribution networks:Cryogenic trucking infrastructure can extend LNG access to isolated industrial clusters beyond pipeline reach.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in minus 162-degree Celsius handling and regasification system commissioning remains concentrated among a narrow contractor base.
- Legacy pipeline integration:Physical interconnection protocols with Petrobras infrastructure require protracted technical negotiations and safety certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil LNG Market |
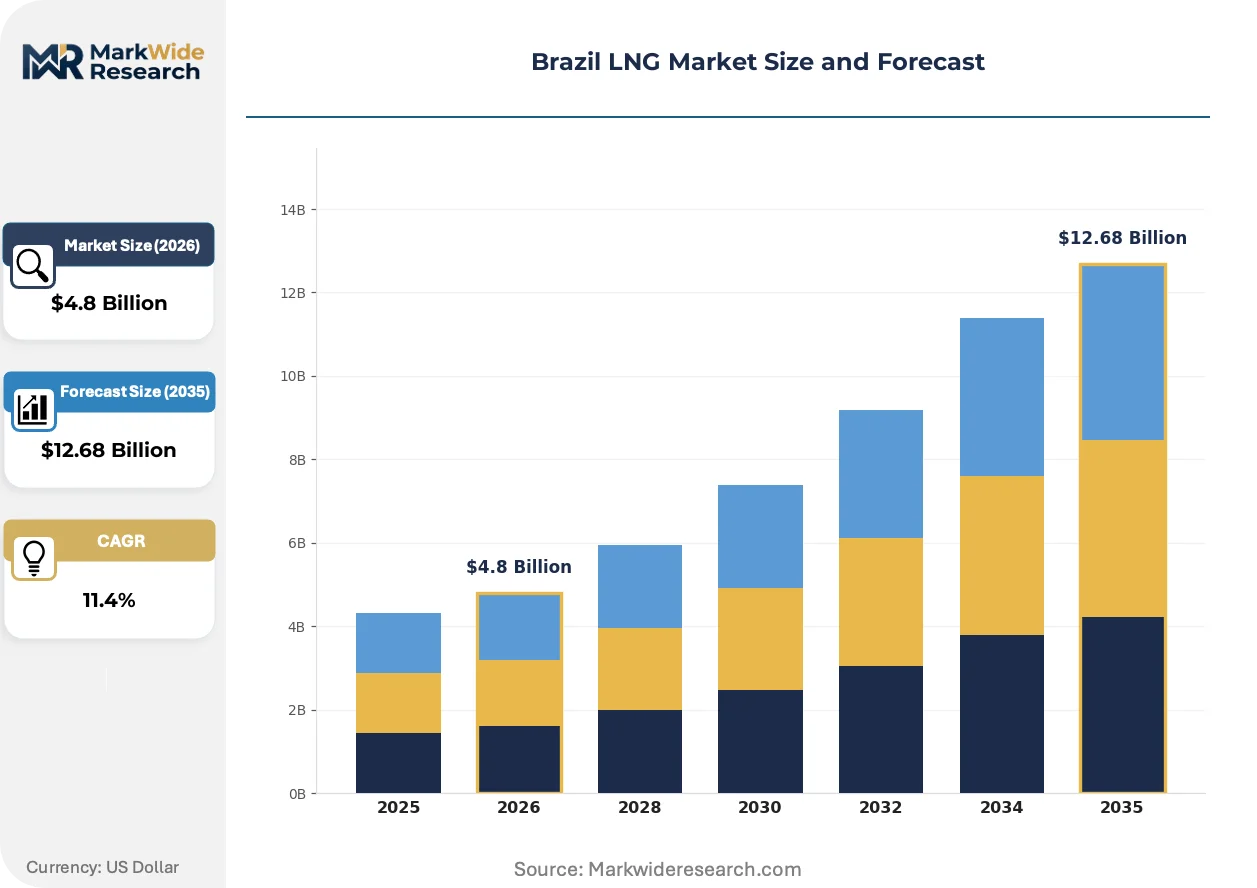
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Heating, Marine Fuel, Transportation End User: Power Plants, Mining Sector, Shipping Companies, Logistics Providers Distribution Channel: Direct Supply, Retail, B2B, Online Sales Technology: Liquefaction, Regasification, Compression, Storage Solutions |
| Companies Covered | BP plc, New Fortress Energy, Petroleo Brasileiro S.A., ENGIE Brasil Energia, Excelerate Energy, Shell plc, ExxonMobil Corporation, Equinor, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil LNG Market Strategic Shifts
Terminal operations are converging with digital infrastructure while regulatory frameworks force emission accountability across the value chain. These intersecting pressures are compressing traditional asset-heavy business models.
Integrated terminal management platforms are digitizing cargo tracking, inventory optimization, and regasification scheduling through real-time sensor networks. Independent terminal operators in Porto de Açu and Bahia are deploying these systems to match Petrobras operational visibility. The technology is digitizing contract execution speed and reducing demurrage exposure for charterers.
ANP's updated environmental licensing protocols now mandate continuous methane leak detection and flaring minimization at import facilities. Terminal developers must install optical gas imaging and closed-flare systems to secure operating permits. This regulatory shift is compressing project engineering timelines and elevating capital requirements for brownfield expansions.
Power utilities are unbundling fuel procurement from generation asset ownership to access spot LNG pricing flexibility. State distributors in São Paulo and Rio de Janeiro are signing tolling agreements rather than traditional take-or-pay supply contracts. This procurement restructuring is most visible among independent power producers seeking to arbitrage hydroelectric availability against thermal dispatch economics.
Brazil LNG Market Segmentation
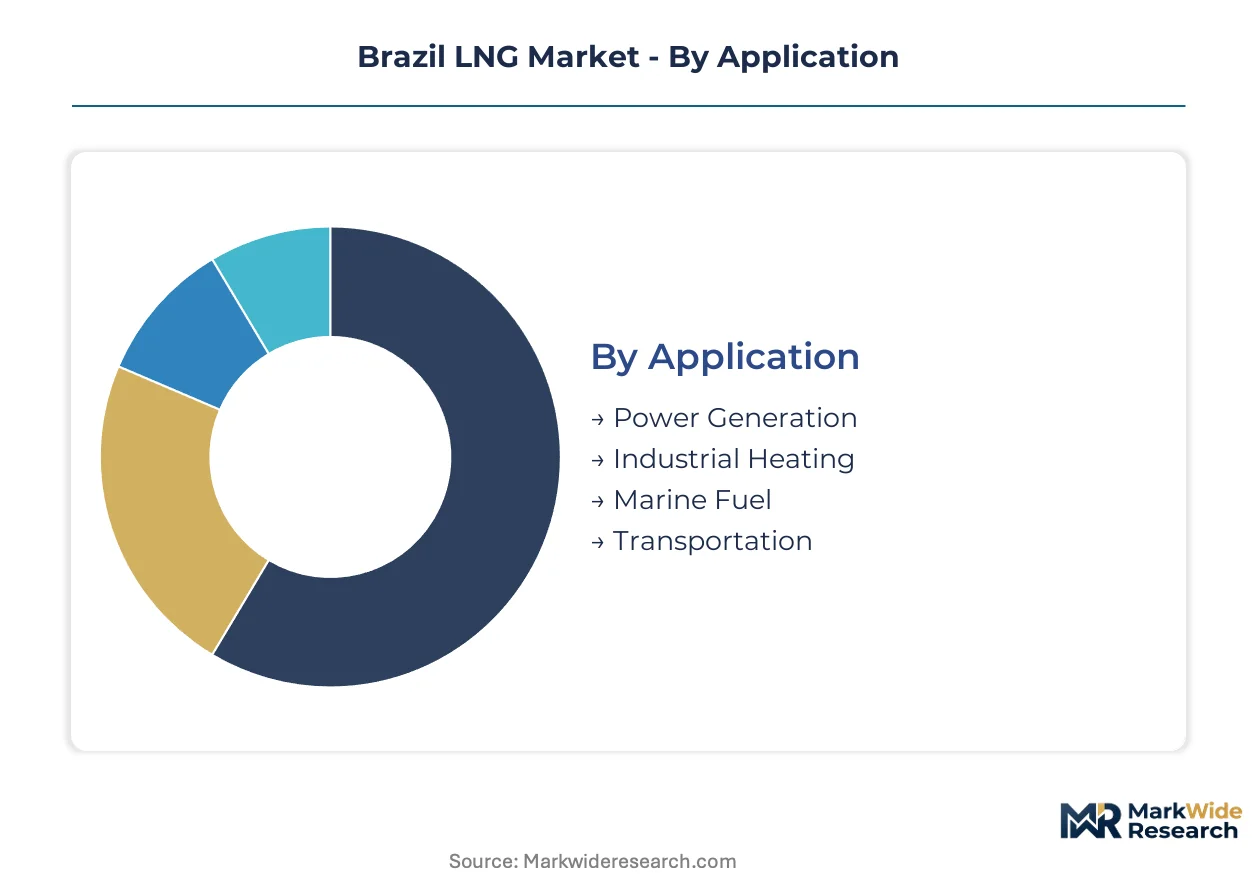
Brazil's LNG market segments reflect the tension between established power sector offtake and emerging mobility applications. Understanding these divisions reveals where infrastructure investments concentrate and where regulatory tailwinds are reshaping competitive entry economics.
Application:
Mature baseload applications anchor volume absorption while emerging segments exploit regulatory displacement of incumbent fuels.
- Power Generation:Grid operators dispatch LNG-fired turbines to cover hydroelectric shortfalls during Southeast drought cycles. São Paulo state distributors and Rio de Janeiro utilities sustain the largest procurement volumes under firm reliability mandates from ANP.
- Industrial Heating:Mining complexes in Minas Gerais and petrochemical facilities in Bahia operate dedicated direct-supply contracts bypassing wholesale markets. These installations demand consistent calorific value above standard pipeline specifications.
- Marine Fuel:Port authorities at Santos and Rio de Janeiro enforce sulfur emission thresholds that displace heavy fuel oil in coastal shipping.
- Transportation:Cryogenic trucking infrastructure extends LNG access to isolated industrial clusters beyond pipeline reach in the Northeast.
Power Generation handles the majority of throughput; Marine Fuel is the fastest mover on share.
End User:
Customer concentration tilts toward capital-intensive operators with captive energy demand and long-term contracting capacity.
- Power Plants:State-controlled distributors and independent producers in the Southeast industrial corridor operate under ANP-mandated backup capacity requirements. These facilities anchor terminal utilization rates through take-or-pay structures.
- Mining Sector:Iron ore and bauxite extraction complexes in Minas Gerais and Pará seek dedicated pipeline connections for process heat and power.
- Shipping Companies:Coastal fleet operators at Porto de Açu and Santos retrofit dual-fuel engines to comply with port authority emission protocols.
- Logistics Providers:Cryogenic transport operators build small-scale distribution networks to serve isolated industrial demand pockets.
Power Plants dominate contractual volume; Shipping Companies are expanding most quickly as fleet retrofits accelerate.
Distribution Channel:
Channel selection reflects customer scale and infrastructure access, with direct relationships commanding premium pricing power.
- Direct Supply:Large industrial offtakers negotiate dedicated pipeline connections and FSRU tolling agreements. These arrangements bypass wholesale market liquidity constraints.
- Retail:Small-scale cryogenic distribution serves isolated industrial facilities beyond pipeline networks.
- B2B:Aggregators bundle fragmented industrial demand to achieve terminal access economies.
- Online Sales:Digital procurement platforms emerge for spot cargo matching and secondary contract trading.
Direct Supply captures the value concentration; Online Sales is climbing the fastest as spot market liquidity develops.
Technology:
Technology deployment prioritizes speed-to-market over optimization, compressing traditional asset-heavy project timelines.
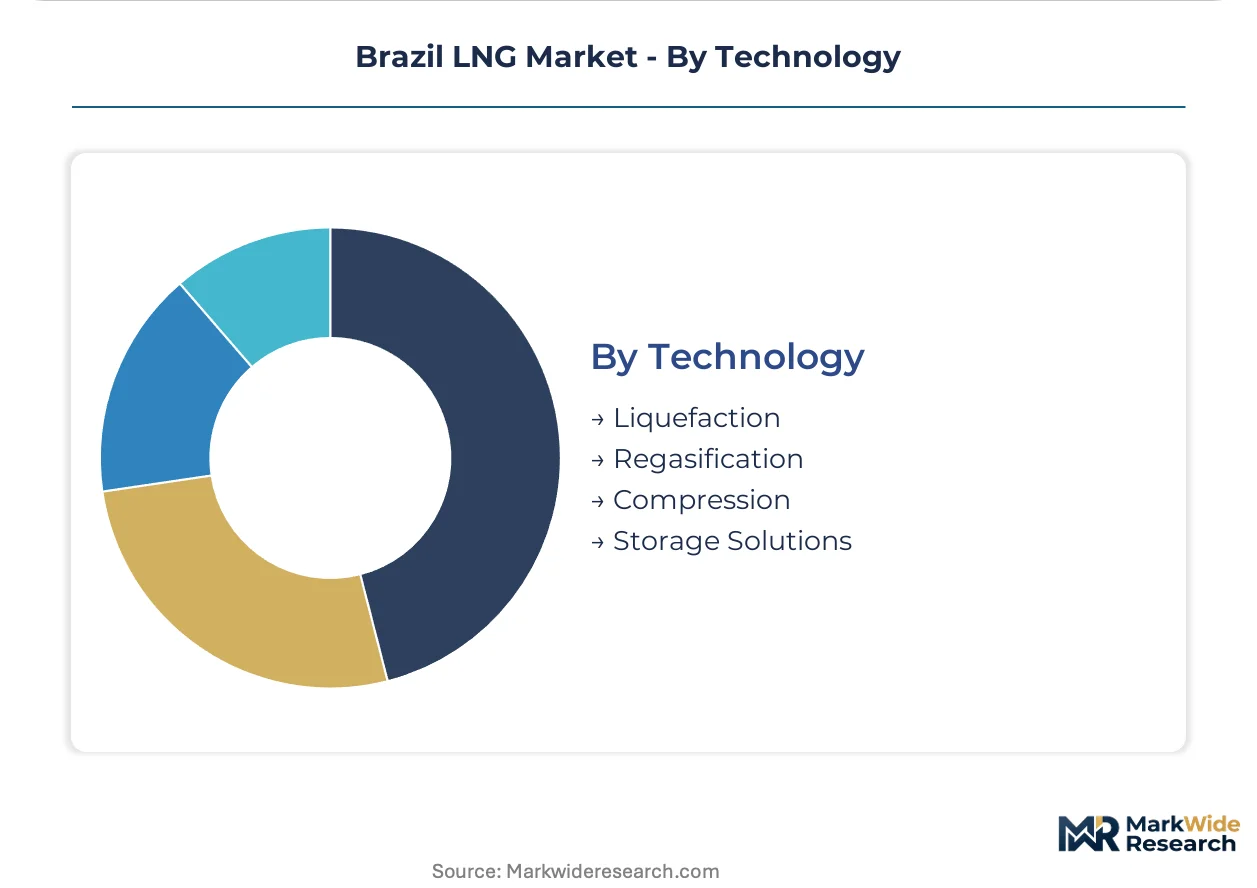
- Regasification:Floating storage and regasification units (FSRUs) bypass IBAMA's protracted onshore environmental licensing. These pre-certified offshore platforms dominate new terminal development at Porto de Açu and Bahia.
- Storage Solutions:Cryogenic tank infrastructure at coastal terminals provides inventory buffer against supply disruption.
- Liquefaction:Small-scale liquefaction units support stranded gas monetization and biogas upgrading projects.
- Compression:Pipeline injection systems enable grid interconnection at legacy Petrobras infrastructure points.
Regasification commands the deployment capital; Liquefaction is gaining share fastest as biogas integration expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state commands premium pricing power over Bahia due to concentrated industrial demand and pipeline density, while remote Northeast terminals absorb higher delivered costs from FSRU mooring premiums and sparse distribution infrastructure.
São Paulo
Power distributors and petrochemical complexes anchor the largest procurement volumes under ANP reliability mandates. State-level grid backup requirements force continuous thermal dispatch during dry seasons. The Santos port cluster hosts the densest concentration of regasification capacity and cryogenic storage infrastructure.
Minas Gerais
Iron ore mining operations and steel mills generate baseload demand for direct-supply pipeline connections. IBAMA licensing protocols for onshore terminal expansion remain protracted, pushing developers toward FSRU alternatives. The Belo Horizonte industrial corridor sustains premium pricing for firm supply contracts.
Rio de Janeiro
State-controlled utilities and independent power producers compete for terminal access along the coastal distribution network. ANTT-regulated interconnect tariffs inflate delivered costs for non-incumbent operators. The Porto de Açu cluster anchors new FSRU deployments with deepwater mooring advantages.
Bahia
Petrochemical facilities and fertilizer plants seek dedicated pipeline connections bypassing wholesale market volatility. ANP third-party access mandates are unlocking import terminal development for independent operators. The Camaçari industrial complex represents the fastest-growing demand concentration outside the Southeast corridor.
Rio Grande do Sul
Isolated industrial clusters beyond pipeline networks rely on small-scale cryogenic trucking infrastructure. State environmental licensing timelines lag national averages, compressing project development velocity. The Porto Alegre metro area sustains niche demand from food processing and ceramics manufacturing.
Brazil LNG Market Competitive Environment
National oil company incumbents and independent terminal specialists split the market between legacy infrastructure control and greenfield FSRU deployment. The competitive structure tilts toward vertical integration advantages for pipeline network owners, while new entrants compress construction timelines through floating technology adoption. Three archetypes dominate: state-backed integrated majors, independent terminal developers, and global trading houses with bundled supply offerings. Capacity expansion through FSRU chartering and strategic tolling agreements with power utilities represent the dominant competitive moves.
Among integrated energy majors, Petroleo Brasileiro S.A. anchors the incumbent position through legacy pipeline network ownership, while Shell plc and BP plc exemplify global trading-house archetypes with bundled LNG-to-power offerings. New Fortress Energy occupies the independent developer tier, representing greenfield terminal specialists deploying FSRU technology at underutilized ports.
| Leading Market Players |
|---|
| BP plc |
| New Fortress Energy |
| Petroleo Brasileiro S.A. |
| ENGIE Brasil Energia |
| Excelerate Energy |
| Shell plc |
| ExxonMobil Corporation |
| Equinor |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
FSRU utilization rates above 85 percent at Porto de Açu and Santos are compressing charter premiums while forcing terminal operators into longer-term vessel commitments that reshape spot versus contract pricing postures for power utilities.
Pricing Analysis
The customization-premium spread between dedicated pipeline connections and standard FSRU tolling agreements runs 12-18 percent for mining complexes in Minas Gerais seeking firm calorific specifications. Contract-based long-term offtake dominates procurement, with price differentiation driven by volume scale and geographic delivery cost to pipeline-constrained regions. Pricing pressure stems from diesel backup competition at dual-fuel power plants when LNG spot cargoes spike. Industrial direct-supply offtakers show least price sensitivity; small-scale cryogenic distributors face maximum margin compression.
Supply Chain Analysis
Export-control regimes on cryogenic membrane containment systems from South Korea and Japan constrain FSRU vessel deployment velocity for Brazilian terminal developers. Supply draws from specialized shipyards in South Korea, Singapore, and China, with raw material dependencies on nickel-alloy steel plate, brazed aluminum heat exchangers, and membrane containment modules. Single-source vulnerability concentrates in FSRU vessel ownership among a limited pool of specialized lessors. Distribution runs through Petrobras legacy pipeline networks for coastal corridors, with independent operators relying on chartered vessel-to-shore transfer systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANP downstream liberalization dismantling import monopolies represents a structural inflection compressing competitive entry timelines from years to months for FSRU-based terminal developers.
For Market Incumbents: Harden terminal utilization rates through exclusive tolling agreements with São Paulo state distributors facing ANP-mandated reliability requirements. Secure backward integration into cryogenic vessel chartering pools to defend against New Fortress Energy's FSRU deployment velocity. Prioritize pipeline interconnect certification with ANTT to maintain tariff advantages over independent operators. For New Entrants and Emerging Players: Marine fuel bunkering infrastructure at Santos and Rio de Janeiro represents the most penetrable entry point given port authority sulfur enforcement timelines and absence of incumbent bunkering networks. Small-scale cryogenic distribution to isolated industrial clusters in Rio Grande do Sul offers secondary white-space with lower capital intensity. Pursue tolling partnerships with independent power producers unbundling fuel procurement from generation ownership. For Investors and Strategic Acquirers: Capital is best deployed toward FSRU vessel operators with confirmed Brazil deployment slots and established relationships with ANP licensing teams. Terminal developers with secured mooring agreements at underutilized ports offer acquisition profiles with compressed regulatory timelines. Watch ANP clarity on third-party pipeline access tariffs as the signal indicating competitive parity or incumbent protection.| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Vessel Chartering | Pre-certified floating platforms bypass IBAMA licensing timelines at Porto de Açu. |
| Power Purchase Agreement Restructuring | Tolling contracts replace take-or-pay structures for spot price arbitrage flexibility. |
| Pipeline Interconnect Certification | ANTT tariff negotiations determine delivered cost economics for non-Petrobras operators. |
| Marine Fuel Bunkering Infrastructure | Port authority sulfur thresholds at Santos displace heavy fuel oil in coastal shipping. |
| Small-Scale Cryogenic Distribution | Trucking networks extend LNG access to pipeline-constrained industrial clusters. |
Study Parameters
Cross-validation between ANP import licensing records and IBAMA environmental permit databases anchors the qualitative findings on terminal development velocity. Primary interviews with FSRU project developers, ANP regulatory officers, and Petrobras infrastructure planners combined with secondary validation from ANTT tariff filings, ANP statistical bulletins, and vessel charter market reports. Bottom-up terminal capacity buildouts and top-down power sector demand projections were triangulated against hydroelectric dispatch patterns.
Calibration against historical FSRU deployment timelines in comparable emerging markets informed the analytical framework across the projection horizon. Segmentation dimensions modeled include application type, end-user sector, distribution channel, and technology deployment mode. CAGRs were derived from regression analysis of import volume trajectories against power generation reliability mandates and industrial direct-supply contract growth. Forecast inputs incorporated ANP liberalization policy implementation pace and global LNG spot price volatility bands.
Stress conditions across FSRU vessel availability, ANTT tariff renegotiation outcomes, and hydroelectric reservoir levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation timelines and infrastructure commissioning schedules. Material shifts in ANP third-party access enforcement or Petrobras pipeline divestiture pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Electric Fuel Heater Market
Fuels
Refuse Derived Fuel Market
Fuels
Global Steam Coal Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Bituminous Coal Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Emulsified Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Europe Wood Pellet Market
Fuels
Biobutanol Market
Fuels
Fuel Oxygenate Market