

Battery Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Binders Market Insights
East Asian polymer producers is consolidating capacity around fluorinated and aqueous binder platforms to serve gigafactory scale-ups. BASF leverages its Ludwigshafen R&D complex to sustain patent positions in waterborne polyacrylate formulations for silicon-anode architectures. LG Chem anchors regional supply through captive Kureha partnerships in Japan, while Arkema competes on PVDF purity grades qualified by European cell makers.
Battery binders are polymeric adhesives—typically fluoropolymers, rubbers, or cellulosic derivatives applied at 2-5 wt% in electrode slurries—that mechanically stabilize active material particles against conductive substrates during charge cycling. Polyvinylidene fluoride dominates current lithium-ion battery production due to its electrochemical stability in carbonate electrolytes, though carboxymethyl cellulose and polyacrylic acid segments are gaining structural share as water-based processing displaces N-methyl-2-pyrrolidone solvent systems. Styrene-butadiene rubber occupies a mature margin pool in nickel-metal hydride and lead-acid battery refurbishment channels where cost sensitivity overrides performance premiums.
EPA rules on per- and polyfluoroalkyl substances are pressuring PVDF producers to certify alternative chemistries or face restricted market access in US electric vehicle supply chains. REACH restrictions in Europe and China's GB standards for battery material recyclability are converging to demand full material disclosure from binder suppliers. Stakeholders must monitor how dual carbon compliance timelines in Beijing and the EU Green Deal's battery passport requirements will reshape qualification protocols and regional sourcing decisions.
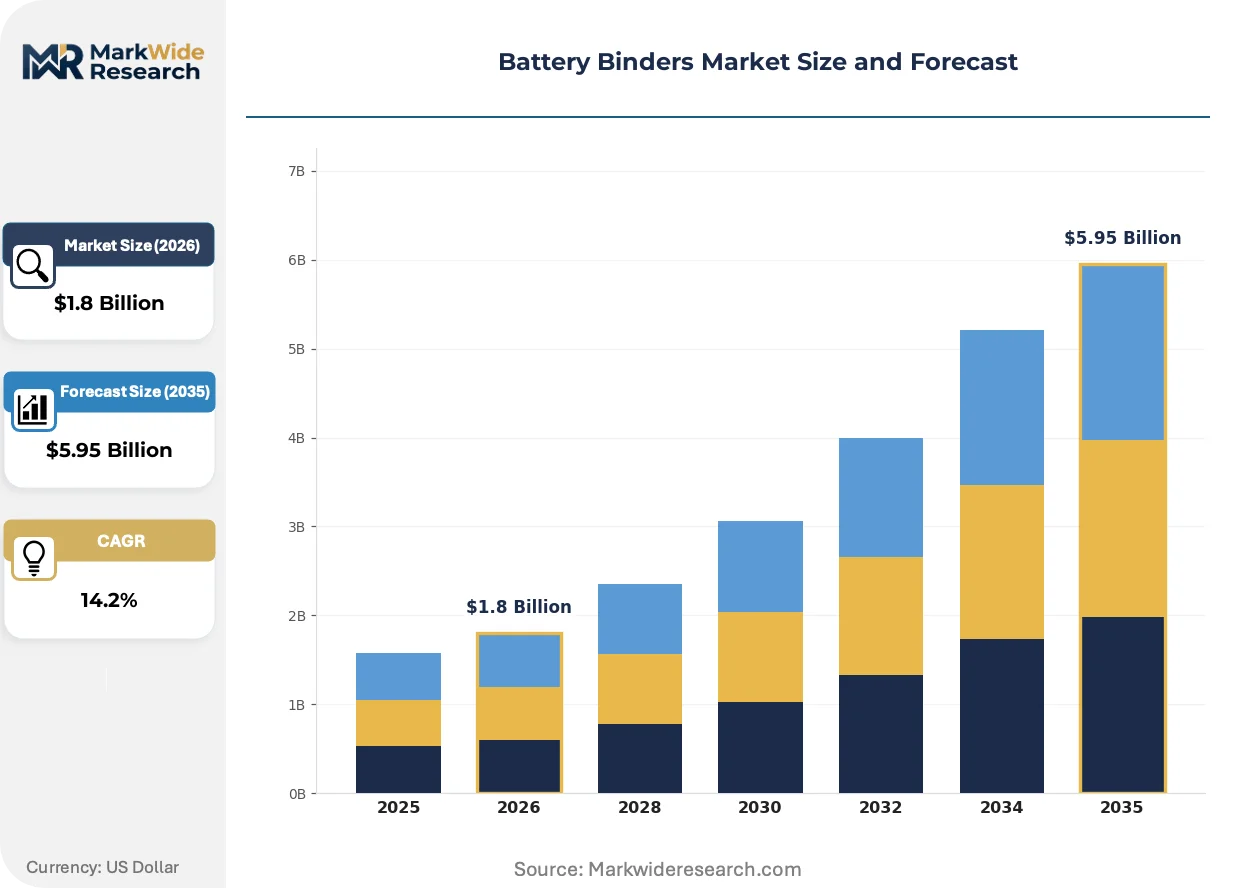
Market Dynamics
Water-based binder chemistries are displacing N-methyl-2-pyrrolidone solvent systems as China's NMPA and MIIT tighten battery material purity standards, forcing converters to retool electrode coating lines and requalify supply chains for gigafactory scale.
Growth Catalysts
- Silicon-anode proliferation:Cell makers are expanding silicon loadings beyond 10 wt% in anode formulations, driving demand for high-elongation polyacrylate binders that accommodate volumetric expansion during lithiation.
- EU Green Deal battery passport:Full material disclosure mandates under the EU Green Deal are accelerating qualification of waterborne binder platforms that eliminate perfluorinated substance residues from supply chains.
- East Asian gigafactory clustering:Production capacity concentrates in South Korea and Japan, where captive polymer supply agreements anchor regional binder demand for cylindrical and prismatic cell formats.
Market Restraints
- Fluoropolymer input cost volatility:R-142b refrigerant feedstock prices swing with HVAC refrigerant phase-down schedules, compressing PVDF binder margins for producers without backward integration into VDF monomer.
- Supply concentration risk:Kureha and Arkema control high-purity PVDF resin supply for battery grades, creating single-source vulnerability for European cell makers qualifying alternative fluoropolymer platforms.
- Water-based adhesion limits:Carboxymethyl cellulose binders exhibit inferior peel strength versus PVDF on copper current collectors above 4 mAh per square centimeter areal loading, restricting adoption in high-energy cylindrical cells.
Strategic Opportunities
- India cell manufacturing buildout:PLI scheme incentives for advanced chemistry cell production are creating first-mover advantage for aqueous binder suppliers establishing local compounding capacity ahead of 2026 qualification deadlines.
- Solid-state electrolyte convergence:Dry electrode processing for sulfide and oxide solid-state architectures eliminates solvent-based slurry coating entirely, opening demand for thermoplastic binder formats compatible with hot-rolling lamination.
- Recyclability-driven specification:China's GB standards for battery material recyclability are mandating binder chemistries that depolymerize or dissolve under mild alkaline conditions, favoring polyacrylic acid over fluorinated alternatives.
Industry Challenges
- Electrode formulation skill scarcity:Water-based slurry rheology control requires distinct expertise from NMP-PVDF systems, and cell maker R&D teams face extended retraining timelines during platform transitions.
- Dual certification timeline compression:Simultaneous qualification under China's GB standards and EU REACH restrictions demands parallel toxicology dossier preparation, straining regulatory affairs bandwidth at mid-scale binder suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Binders Market Trends and Innovations
Electrode manufacturing is bifurcating between aqueous processing for cost-sensitive volume cells and advanced fluoropolymer formulations for premium energy density applications, with equipment makers retooling coating lines for dual chemistry flexibility.
Polyacrylic acid-sodium architectures are absorbing silicon expansion stresses in next-generation anodes through dynamic hydrogen bonding networks that reform after lithiation-induced deformation. Korean cell makers are qualifying these formulations for 4680 cylindrical production at aggressive timelines. The technology is absorbing share from styrene-butadiene rubber in nickel-rich silicon-graphite blends where mechanical integrity determines cycle life.
EPA rules on per- and polyfluoroalkyl substances are compelling PVDF producers to certify alternative chemistries or face restricted market access in US electric vehicle supply chains. The industrial consequence is accelerated R&D spending on partially fluorinated copolymers that maintain electrochemical stability while reducing perfluorinated carbon chain length. European cell makers are responding most aggressively, with several disqualifying standard PVDF grades from 2026 supply agreements pending toxicity reclassification.
Cell makers are consolidating binder procurement under direct long-term contracts with polymer producers, bypassing traditional distributor channels that stocked commodity PVDF grades. Tier-one suppliers are capturing this shift through technical service agreements that embed formulation scientists at customer R&D centers. South Korea displays the most advanced procurement concentration, with LG Chem and Samsung SDI operating captive binder development programs that specify molecular weight distributions and impurity ceilings in supply contracts.
Battery Binders Market Segmentation
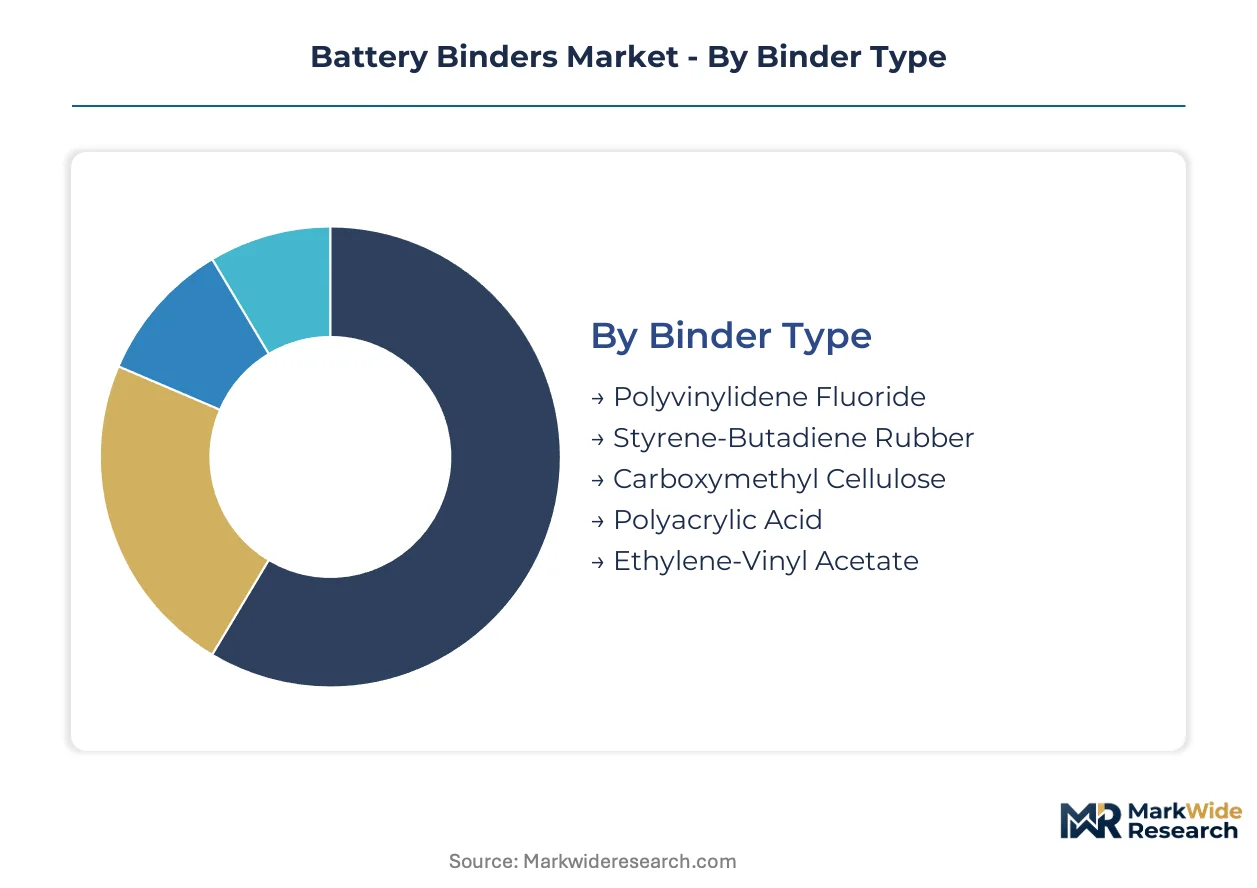
Binder selection cascades through electrode formulation, solvent recovery economics, and end-of-life recyclability obligations. Cell makers segment procurement by electrochemical stability thresholds and coating line compatibility rather than commodity polymer pricing alone.
Binder Type:
Cell makers prioritize electrochemical window compatibility against carbonate electrolytes and silicon-anode expansion tolerance when qualifying binder platforms.
- Polyvinylidene Fluoride:Fluorinated homopolymer delivering oxidative stability above 4.3 V versus Li/Li+ in high-nickel cathode formulations. Demand concentrates with cylindrical cell producers in Japan and South Korea seeking qualification for 4680 formats where cohesive strength determines cycle life.
- Carboxymethyl Cellulose:Anionic polysaccharide derived from wood pulp enabling water-based slurry processing without N-methyl-2-pyrrolidone recovery infrastructure. Chinese converters are expanding adoption fastest as NMPA purity standards tighten and gigafactory buildouts prioritize capital efficiency over coating line flexibility.
- Styrene-Butadiene Rubber:Elastomeric copolymer dominating nickel-metal hydride and lead-acid refurbishment channels where cost sensitivity overrides performance premiums.
- Polyacrylic Acid:Hydrogen-bonding network polymer absorbing volumetric expansion in silicon loadings exceeding 10 wt% through dynamic crosslink reformation.
- Ethylene-Vinyl Acetate:Thermoplastic copolymer finding niche adoption in flexible cell architectures and pouch formats requiring hot-melt lamination compatibility.
Volume sits with polyvinylidene fluoride; growth tilts toward carboxymethyl cellulose.
Application:
Application segmentation tracks cathode chemistry evolution and solid-state electrolyte convergence timelines.
- Lithium-Ion Batteries:Dominant application spanning layered oxide cathodes and graphite-silicon composite anodes. Procurement concentrates with electric vehicle manufacturers scaling cylindrical and prismatic production in East Asian gigafactory clusters.
- Solid-State Cells:Sulfide and oxide electrolyte architectures eliminating solvent-based slurry coating entirely. Korean cell makers are qualifying thermoplastic binder formats compatible with dry electrode hot-rolling lamination at aggressive commercialization timelines.
- Nickel-Metal Hydride Cells:Mature application in hybrid electric vehicle powertrains where styrene-butadiene rubber maintains cost-positioning.
- Lead-Acid Batteries:Refurbishment and stationary backup applications with minimal binder innovation requirements.
- Zinc-Air Batteries:Emerging application in hearing aid and remote sensor markets demanding aqueous electrolyte compatibility.
Revenue concentrates in lithium-ion; steepest expansion trajectory belongs to solid-state.
End User Industry:
End user segmentation reflects divergent performance thresholds across mobility, stationary storage, and consumer device markets.
- Electric Vehicle Manufacturers:Dominant demand source specifying molecular weight distributions and impurity ceilings in direct polymer supply contracts. South Korean producers operate captive binder development programs embedding formulation scientists at customer R&D centers.
- Grid Storage Facilities:Cost-optimized procurement favoring aqueous binder platforms where cycle count requirements trail mobility applications. Chinese state-owned utilities are consolidating procurement under GB standard compliance timelines.
- Consumer Electronics Makers:Pouch and prismatic cell formats for smartphones and laptops prioritizing thin-film coating uniformity.
- Renewable Energy Equipment:Residential and commercial solar-plus-storage systems with moderate energy density requirements.
- Aerospace Systems:Satellite and aviation applications demanding extreme temperature cycling tolerance and minimal outgassing.
Procurement scale sits with electric vehicle manufacturers; specification complexity peaks in aerospace.
Form:
Form factor determines coating line retrofit requirements and solvent recovery capital allocation.
- Latex:Aqueous dispersion enabling direct substitution for N-methyl-2-pyrrolidone solvent systems without slurry rheology requalification. Chinese converters are adopting fastest under MIIT water-based processing mandates.
- Powder:Dry solid requiring redispersion in organic solvents, maintaining incumbent position in high-energy cylindrical cells where peel strength thresholds exceed aqueous binder capabilities.
- Emulsion:Stabilized colloidal dispersion offering intermediate viscosity control for pilot-scale coating lines.
- Resin:Solid thermoplastic formats for solid-state dry electrode lamination processes.
- Solution:Pre-dissolved formats in organic solvents for specialty research and development applications.
Coating line compatibility sits with latex; dry electrode transition favors resin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoropolymer feedstock concentration in East Asian chemical clusters shapes regional binder procurement patterns. VDF monomer supply from Japanese and South Korean petrochemical complexes anchors high-purity PVDF production for battery grades. Regulatory divergence between China's water-based mandates and Europe's fluorinated substance restrictions is fragmenting regional formulation standards.
China
Gigafactory buildouts in Ningde and Changzhou are absorbing aqueous binder capacity at unprecedented scale. MIIT water-based processing mandates and NMPA purity standards are forcing electrode coating line retrofits across Fujian and Guangdong provinces. Yangtze River Delta chemical parks are consolidating polyacrylate compounding capacity to serve CATL and BYD supply chains.
Japan
Kureha's Iwaki complex maintains captive VDF monomer integration for battery-grade PVDF resin. METI carbon neutrality roadmaps are pressuring fluoropolymer producers to certify reduced-perfluorinated alternatives by 2026. Osaka-Kobe industrial corridor hosts formulation R&D partnerships between polymer suppliers and Panasonic's cylindrical cell operations.
South Korea
LG Chem and Samsung SDI are embedding binder scientists at customer R&D centers through technical service agreements. MFDS chemical safety notifications are tightening impurity disclosure requirements for imported polymer feedstocks. Ulsan petrochemical complex anchors regional fluoropolymer supply for 4680 cylindrical cell qualification programs.
Germany
REACH restrictions on perfluorinated substances are disqualifying standard PVDF grades from 2026 supply agreements. ECHA dossier preparation is straining regulatory bandwidth at mid-scale binder suppliers serving BMW and Volkswagen cell procurement. Ludwigshafen chemical cluster sustains waterborne polyacrylate R&D for silicon-anode architectures.
United States
EPA rules on per- and polyfluoroalkyl substances are compelling domestic qualification of alternative fluoropolymer platforms. IRA domestic content bonuses are incentivizing electrode material localization in Michigan and Ohio battery plant corridors. Texas Gulf Coast petrochemical infrastructure is attracting backward-integrated VDF monomer investments.
Battery Binders Market Competitive Landscape
Global majors compete with regional champions across fluoropolymer purity grades and aqueous formulation expertise. The vendor base organizes around three strategic archetypes: integrated petrochemical giants with captive monomer supply, specialized fluoropolymer houses with battery-grade purification capabilities, and water-based polymer specialists attacking cost-sensitive volume segments. Capacity expansion and strategic partnerships dominate competitive moves, with technical service agreements replacing distributor relationships for tier-one cell maker procurement.
Within the integrated petrochemical tier, BASF and LG Chem exemplify divergent regional strategies. BASF anchors European waterborne innovation through its Ludwigshafen R&D complex, while LG Chem leverages captive Kureha partnerships in Japan to secure high-purity PVDF resin for South Korean cylindrical cell producers. Arkema occupies a position between these archetypes, competing on fluoropolymer purity grades qualified by European cell makers facing REACH timeline compression. DuPont and Solvay represent North American-European hybrids navigating EPA fluorinated substance restrictions through partially fluorinated copolymer development.
| Leading Market Players |
|---|
| Arkema |
| BASF |
| Daikin Industries |
| DuPont |
| Kureha |
| LG Chem |
| Resonac Holdings |
| Solvay |
| Zeon Corporation |
| Others |
Pricing and Supply Chain Analysis
R-142b refrigerant feedstock price volatility cascades through VDF monomer costs into PVDF binder pricing tiers, compressing margins for producers without backward integration while amplifying procurement leverage for integrated petrochemical majors serving East Asian gigafactory clusters.
Pricing Analysis
Technical service agreements bundle formulation scientist embedment and joint R&D access with base polymer pricing, leaving unbundled commodity PVDF grades exposed to spot-market swings. Three-tier pricing structure across premium, standard, and economy levels separates qualification-grade fluoropolymers certified for 4680 cylindrical cells from water-based polyacrylates for cost-optimized prismatic formats. Cost compression in standard-grade PVDF intensifies because Kureha and Arkema control high-purity resin supply. Grid storage procurement teams at Chinese state-owned utilities exhibit highest price sensitivity, while South Korean EV manufacturers prioritize electrochemical stability over unit cost.
Supply Chain Analysis
Electrode coating line retrofits and solvent recovery infrastructure decommissioning generate reverse-logistics flows of spent NMP solvent systems and obsolete powder-handling equipment toward refurbishment channels in Southeast Asia. Fluoropolymer supply concentrates in Japan, South Korea, and China, where VDF monomer production anchors battery-grade PVDF resin output. Binder formulation draws from R-142b refrigerant feedstock, wood pulp cellulose derivatives, and acrylate monomer streams. Single-source vulnerability pervades high-purity PVDF qualification for European cell makers. Distribution runs through direct long-term contracts with polymer producers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery binders represents a consolidation play as dual certification timelines under REACH and China's GB standards force mid-scale suppliers without regulatory bandwidth to exit or sell.
For Market Incumbents: Lock in captive VDF monomer supply through backward integration or strategic offtake agreements with Japanese petrochemical complexes before refrigerant phase-down schedules tighten feedstock access. Expand waterborne polyacrylate compounding capacity in Yangtze River Delta chemical parks to capture CATL and BYD procurement consolidation. Threat: EPA fluorinated substance restrictions disqualifying standard PVDF grades from US EV supply chains. For New Entrants and Emerging Players: Direct technical service partnerships with Indian cell manufacturers offer lowest barrier to entry, as PLI scheme incentives create qualification deadlines without incumbent embedding relationships. Target aqueous binder supply for grid storage applications where GB standard compliance suffices and electrochemical performance thresholds trail mobility specifications. Go-to-market angle: alkaline-depolymerizable polyacrylic acid formulations aligned with China's recyclability mandates. For Investors and Strategic Acquirers: The window for entry favors water-based polymer specialists with existing compounding infrastructure in East Asian chemical parks and regulatory dossier preparation underway for both REACH and GB standards. Mid-cap targets with technical service agreements already embedded at tier-one cell maker R&D centers offer strongest 5-10 year viability. Signal to watch: Korean cell maker announcements on 4680 cylindrical silicon-anode qualification timelines, which will accelerate procurement consolidation around qualified binder suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VDF Monomer | Captive R-142b feedstock access insulates margin compression from HVAC refrigerant phase-down schedules. |
| Water-Based Processing Line Retrofit | MIIT mandates in Fujian and Guangdong provinces force coating line requalification for aqueous slurry compatibility. |
| Technical Service Agreement Expansion | LG Chem and Samsung SDI embedding programs set procurement precedent for direct polymer supply relationships. |
| Dual Certification Dossier Preparation | Parallel REACH and GB standard compliance opens access to both European and Chinese EV manufacturer supply chains. |
| Alkaline-Depolymerizable Formulation Development | China's battery material recyclability standards favor polyacrylic acid binders over fluorinated alternatives. |
Research Methodology
Independent corroboration across primary interviews with electrode formulation scientists, polymer procurement leads at tier-one cell makers, and regulatory affairs directors at mid-scale binder suppliers underwrites the qualitative findings. Secondary validation drew from MIIT processing mandate filings, ECHA REACH dossier registrations, customs data on fluoropolymer trade flows, and SEC disclosures from integrated petrochemical majors. Bottom-up segmentation modeling triangulated against top-down demand projections from electric vehicle production forecasts.
Rate-of-change decomposition across binder type, application, end-user industry, and form factor dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs included silicon-anode loading adoption curves and solid-state electrolyte commercialization timelines from Korean cell maker qualification programs.
The model holds under stable refrigerant feedstock pricing and regulatory timeline adherence; deviation in EPA fluorinated substance reclassification or Chinese dual carbon policy acceleration would shift qualification priorities and regional sourcing patterns. Practitioners should monitor Korean 4680 cylindrical production ramp schedules and European cell maker PVDF disqualification announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.