
 India Lead-Acid Battery Separator for SLI Applications Market | 2026-2036
India Lead-Acid Battery Separator for SLI Applications Market Size, Share, and Industry Trends Forecast 2026-2036
India Lead-Acid Battery Separator for SLI Applications Market Insights
High-purity polyethylene separator grades is reorganizing competitive dynamics among domestic and multinational suppliers. Sumitomo Chemical Co. Ltd leverages its polymer science heritage to sustain premium positioning in automotive OEM channels. Freudenberg Performance Materials anchors its presence through localized technical service capabilities. Amer SIL competes on cost-optimized PVC separator formulations for aftermarket replacement demand.
A lead-acid battery separator for SLI applications is a microporous membrane interposed between positive and negative plates, typically manufactured from polyethylene, PVC, or polyester via extrusion or casting processes, with pore sizes ranging from 0.1 to 10 microns to facilitate ionic conduction while preventing electrical shorting. Its primary function is to enable cranking power delivery and shallow cycling durability in starter-lighting-ignition battery systems. Polyethylene separators command the dominant volume share due to superior oxidation resistance and backweb integrity under engine-bay thermal stress. The two-wheeler end-user segment represents the fastest-expanding demand pool as rural electrification gaps sustain dependence on ICE-powered personal mobility. Extrusion technology leads manufacturing adoption for its throughput consistency and gauge control precision.
BIS standards enforcement and the Automotive Industry Standard AIS-048 shape separator material approvals and testing protocols for domestic battery manufacturers. The Central Pollution Control Board's hazardous waste handling directives influence recycling-linked separator procurement criteria among organized battery producers. Stakeholders must monitor evolving PLI scheme localization thresholds and their impact on import-dependent specialty polymer supply chains.
Market Dynamics
BIS certification tightening for automotive battery components is forcing separator manufacturers to upgrade material purity and testing protocols, compressing margins for non-compliant domestic suppliers while opening premium channels for certified producers.
Growth Catalysts
- Passenger Vehicle OEM Expansion:Domestic automakers in Maharashtra and Tamil Nadu are scaling separator procurement for enhanced battery cycle life in new vehicle platforms.
- PLI Scheme Localization:The government's production-linked incentive thresholds are pulling specialty polymer supply chains toward domestic manufacturing.
- Rural Electrification Gaps:Two-wheeler ICE dependence in underserved regions sustains replacement battery demand and aftermarket separator consumption.
Market Restraints
- Specialty Polymer Import Dependence:High-purity polyethylene feedstock concentrates among multinational resin suppliers, exposing converters to currency and freight volatility.
- PVC Oxidation Limitations:PVC separator formulations degrade faster under engine-bay thermal stress, restricting their adoption in OEM channels despite cost advantages.
- Hazardous Waste Directives:Central Pollution Control Board recycling mandates add compliance layers that organized producers absorb while informal competitors evade.
Strategic Opportunities
- Extrusion Technology Upgrades:Gauge control precision improvements enable domestic manufacturers to match imported separator consistency for automotive OEM qualification.
- Aftermarket Channel Digitization:E-commerce platforms for battery components are compressing distributor tiers and expanding reach to tier-2 and tier-3 cities.
- AIS-048 Alignment:Early compliance with the Automotive Industry Standard testing protocols positions suppliers for accelerated BIS certification cycles.
Industry Challenges
- Polymer Science Talent Scarcity:Microporous membrane R&D capabilities concentrate among a limited pool of specialists with extrusion process expertise.
- Backweb Integrity Certification:OEM qualification timelines for oxidation resistance testing extend 18-24 months, delaying revenue conversion for new entrants.
- Legacy PVC Asset Stranding:Domestic producers with sunk costs in PVC casting equipment face capex burdens to pivot toward polyethylene extrusion lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lead-Acid Battery Separator for SLI Applications Market |
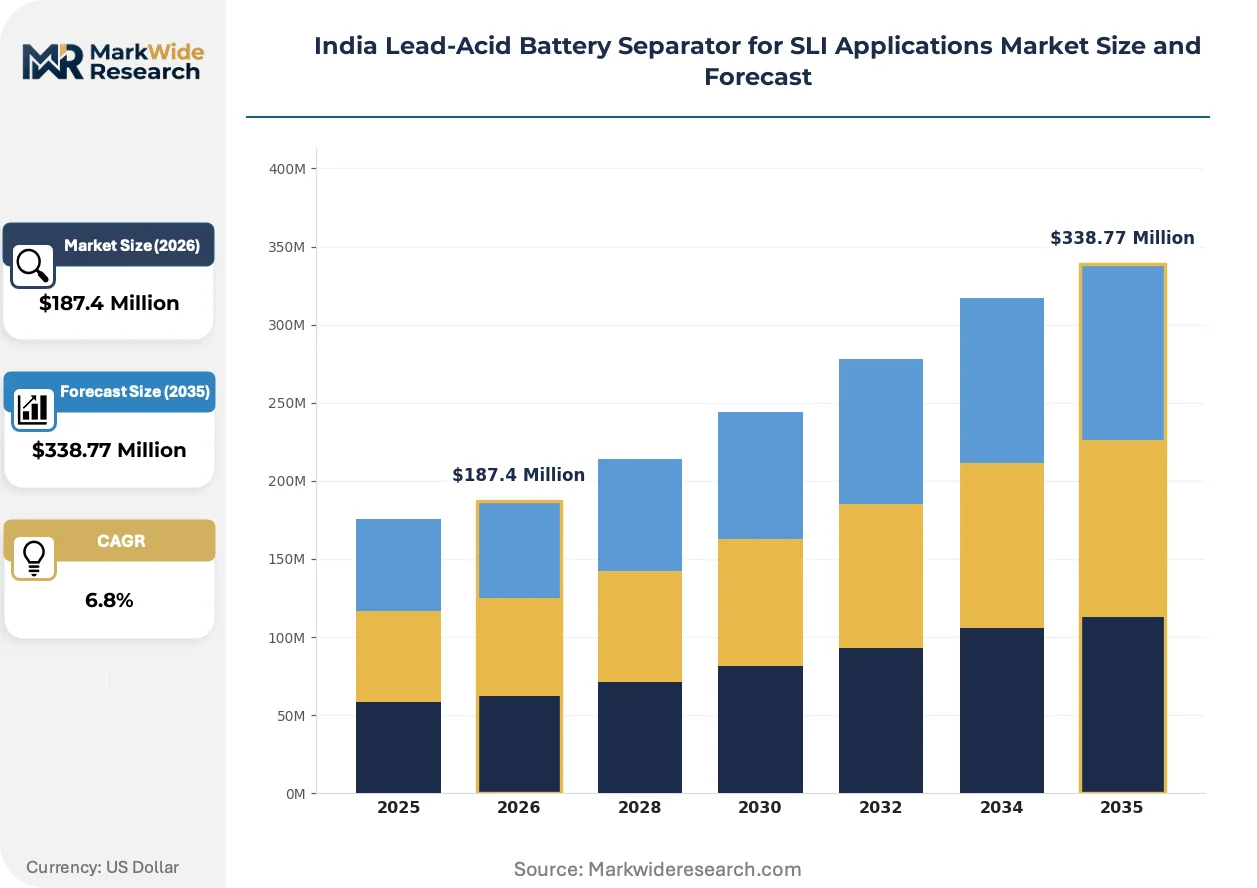
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyester, PVC, Others End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Technology: Extrusion, Injection Molding, Casting, Others Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Sumitomo Chemical Co. Ltd, Asahi Kasei Corporation, Daramic LLC, SK ie Technology Corporation Ltd, Toray Battery Separator Film Co. Ltd, Freudenberg Performance Materials, Amer SIL, Ube Maxell Co. Ltd, Entek International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lead-Acid Battery Separator for SLI Applications Market Trends and Innovations
Separator technology evolution in India centers on material purity advancement, regulatory compliance automation, and procurement model compression as battery assemblers consolidate supplier bases.
Polyethylene microporous membrane technology is decomposing the traditional PVC-Polyester duopoly in SLI applications. Passenger vehicle OEMs in Tamil Nadu are specifying PE grades exclusively for new platforms. The shift is compressing PVC separator margins to aftermarket replacement volumes while elevating PE converter qualification barriers.
BIS certification mandates for automotive battery components are tightening material specification enforcement. Domestic manufacturers must now submit batch-level oxidation resistance documentation. Maharashtra-based battery assemblers are responding by pre-qualifying separator suppliers against AIS-048 protocols ahead of formal audits.
Buyer consolidation among organized battery producers is compressing distributor networks. Tier-1 assemblers in automotive clusters now contract separator suppliers directly, bypassing regional trading houses. This channel disintermediation is most visible in Pune and Chennai, where procurement teams negotiate annual volume agreements with certified converters.
India Lead-Acid Battery Separator for SLI Applications Market Segmentation
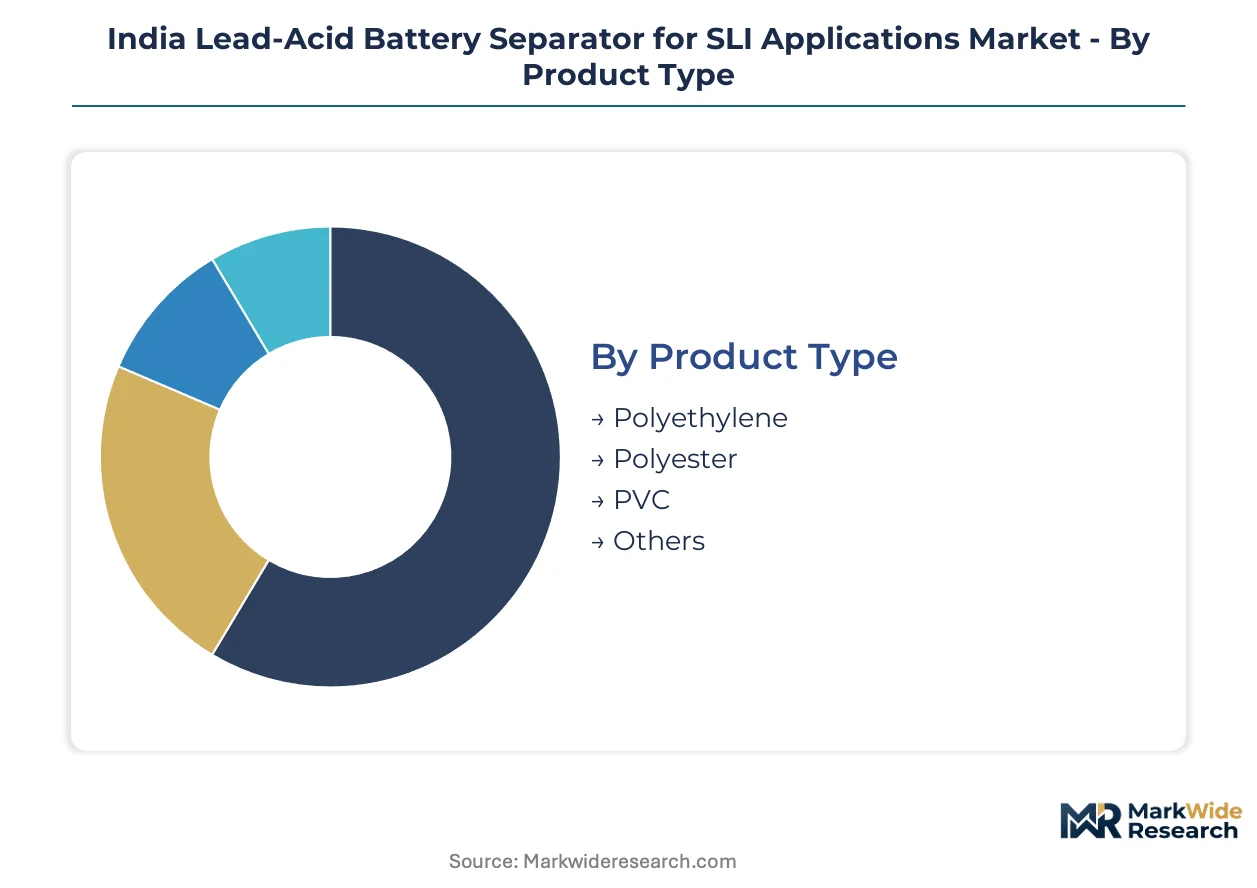
Separator procurement patterns in India diverge sharply across material grades, vehicle platforms, and channel structures. Understanding these fault lines reveals where pricing power concentrates and where commoditization threatens converter margins.
Product Type:
Margin pools sit thickest in oxidation-resistant polymer grades that qualify for OEM direct supply agreements.
- Polyethylene:Microporous membranes manufactured via high-density polyethylene extrusion deliver superior backweb integrity under engine-bay thermal stress. Maharashtra-based passenger vehicle OEMs specify PE separators exclusively for new platform launches, compressing PVC converters to aftermarket channels.
- PVC:Cost-optimized formulations dominate replacement battery demand in rural two-wheeler markets. Tamil Nadu aftermarket distributors stock PVC grades for price-sensitive consumers, though oxidation limitations restrict OEM adoption despite 30-40% material cost advantages.
- Polyester:Woven fabric separators serve niche deep-cycle applications in commercial vehicle auxiliary batteries. Limited volume traction in SLI configurations due to higher unit economics versus polyethylene.
- Others:Rubber-saturated cellulose and composite hybrid materials occupy legacy industrial battery segments with minimal automotive penetration.
Polyethylene holds installed capacity. PVC is rotating up the share rankings in aftermarket replacement volumes.
End User:
Volume concentration tracks automotive assembly cluster geography rather than national dispersion.
- Two-Wheelers:Rural electrification gaps sustain ICE dependence across tier-2 and tier-3 markets. BIS-certified separators for motorcycle batteries command premium pricing in organized retail channels versus unbranded alternatives.
- Passenger Vehicles:OEM qualification timelines extending 18-24 months create defensive moats for incumbent polyethylene suppliers. Tamil Nadu and Maharashtra assemblers consolidate supplier bases to three certified converters per battery platform.
- Commercial Vehicles:Fleet operators in Gujarat and Karnataka prioritize total cost of ownership, driving separator procurement toward high-cycle-life PE grades despite upfront premiums.
- Heavy-Duty Trucks:Long-haul logistics electrification remains distant, preserving SLI battery demand for engine starting and cabin power. Separator specifications emphasize vibration resistance and electrolyte retention under chassis mounting stress.
Passenger vehicles anchor premium pricing. Two-wheelers are climbing the fastest in absolute volume expansion.
Technology:
Process capability gaps separate qualified automotive suppliers from commodity converters.
- Extrusion:Continuous sheet production with computerized gauge control enables ±5% thickness tolerance compliance for AIS-048 testing protocols. Domestic equipment upgrades in Pune and Chennai manufacturing parks are closing consistency gaps with imported separators.
- Casting:Batch-processed PVC separators serve cost-driven aftermarket demand. Slower throughput and wider thickness variation limit qualification for OEM supply agreements despite lower capital intensity.
- Injection Molding:Peripheral application in battery case and vent component production; negligible separator membrane manufacturing adoption due to pore structure limitations.
- Others:Phase-inversion and stretching modifications for specialty microporous structures remain experimental at commercial scale.
Extrusion holds process dominance. Casting is rotating up the share rankings in price-sensitive replacement channels.
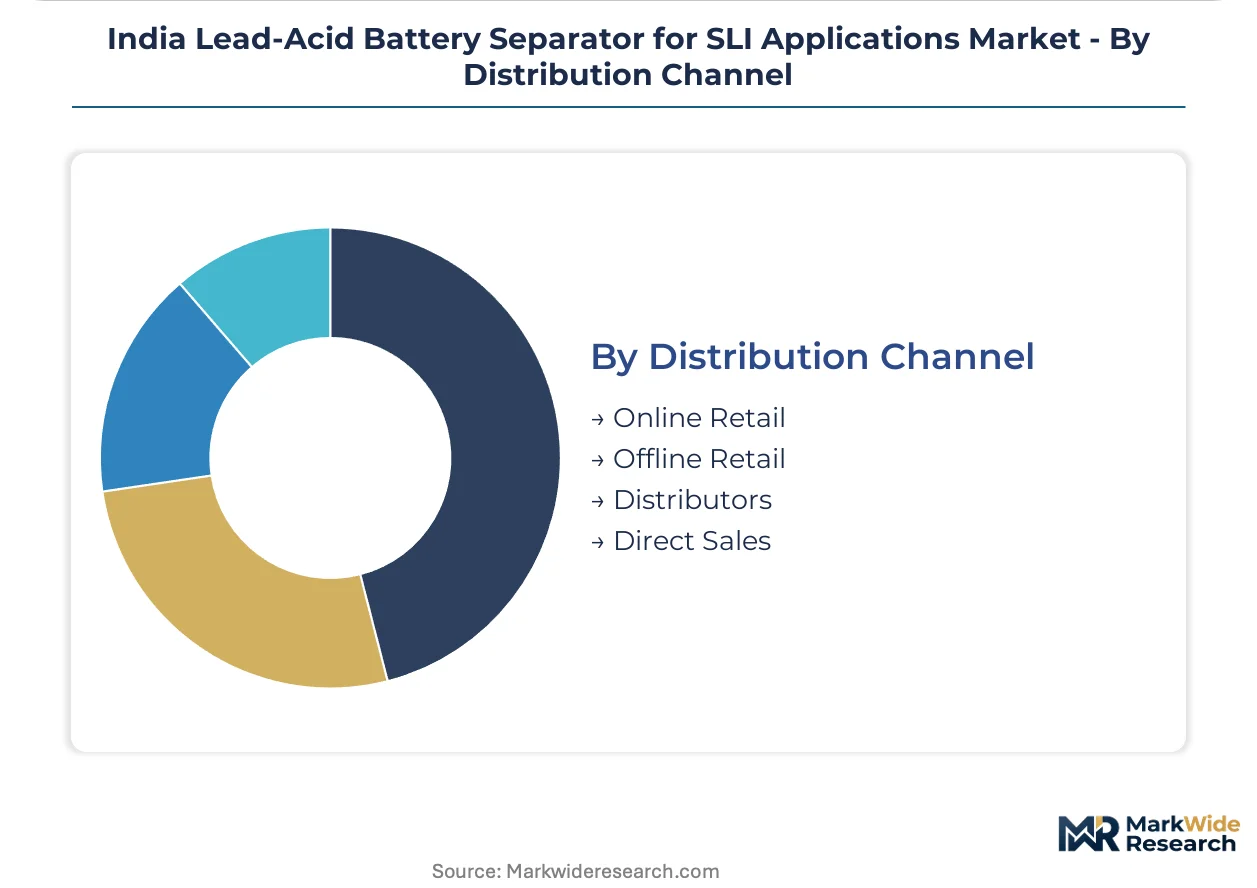
Distribution Channel:
Channel disintermediation is compressing distributor margins while expanding supplier control over pricing.
- Direct Sales:Tier-1 battery assemblers in automotive clusters now contract separator converters through annual volume agreements. Pune and Chennai procurement teams bypass regional trading houses, capturing 8-12% cost reductions through tier elimination.
- Distributors:Legacy network coverage persists in tier-3 cities and rural aftermarket nodes. Inventory carrying costs and credit exposure compress net margins for trading houses serving fragmented battery workshops.
- Offline Retail:Authorized dealer networks for branded battery replacement maintain separator pull-through demand. Counterfeit detection challenges favor organized retail with BIS traceability documentation.
- Online Retail:E-commerce platforms for battery components are expanding reach to secondary cities. Procurement teams at independent workshops source certified separators through B2B marketplaces, compressing traditional distributor tiers.
Direct sales holds margin concentration. Online retail is gaining share fastest in aftermarket channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Separator manufacturing clusters concentrate in western and southern India where automotive battery assembly ecosystems have matured over two decades. State-level industrial policies and BIS enforcement intensity create divergent competitive conditions across sub-regions.
Maharashtra
Passenger vehicle OEMs in Pune and Chakan industrial corridors drive premium polyethylene separator procurement. The state government's electric vehicle manufacturing policy indirectly sustains SLI battery demand through hybrid transition platforms. Aurangabad and Nashik host organized battery assembly operations that pre-qualify suppliers against AIS-048 protocols.
Tamil Nadu
Two-wheeler battery exports from Chennai and Sriperumbudur clusters sustain high-volume separator consumption. BIS certification mandates from the Bureau of Indian Standards enforcement cells in Chennai tighten material documentation requirements. Hosur and Coimbatore manufacturing parks attract specialty polymer converters seeking proximity to OEM qualification centers.
Gujarat
Commercial vehicle fleet operators in Ahmedabad and Vadodara prioritize total cost of ownership in separator selection. The state's production-linked incentive scheme thresholds pull specialty resin supply chains toward domestic manufacturing. Sanand and Halol automotive zones concentrate aftermarket battery distribution networks serving western India.
Karnataka
Bengaluru's technology ecosystem spurs R&D partnerships between separator converters and polymer science institutes. The Karnataka State Pollution Control Board's hazardous waste handling directives exceed national baselines, filtering supplier participation. Peenya industrial area hosts legacy PVC casting operations facing equipment upgrade pressures.
Haryana
Manesar and Gurgaon automotive corridors anchor northern India battery assembly capacity. Proximity to Delhi-NCR aftermarket distribution nodes reduces logistics costs for separator suppliers. The Haryana government's industrial cluster development scheme supports extrusion technology upgrades among domestic converters.
India Lead-Acid Battery Separator for SLI Applications Market Competitive Landscape
Concentration sits with multinational polymer specialists and diversified materials conglomerates that have secured OEM qualification through sustained technical service investment. Domestic converters occupy aftermarket tiers where BIS compliance costs create defensive barriers against informal competitors. Two strategic archetypes dominate: technology licensors with proprietary microporous membrane patents, and scale-driven fabricators optimizing throughput for price-sensitive replacement channels. Competitive moves center on extrusion capacity expansion in Pune and Chennai manufacturing parks, and backward integration into specialty polyethylene resin sourcing.
Within the multinational specialist tier, Sumitomo Chemical Co. Ltd and Asahi Kasei Corporation exemplify polymer science heritage positioning. Freudenberg Performance Materials anchors the technical service archetype through localized application engineering. Among cost-optimized domestic suppliers, Amer SIL occupies the PVC formulation segment serving aftermarket replacement demand. These three patterns—heritage R&D, service anchoring, and cost specialization—structure competitive rivalry across OEM and aftermarket channels.
| Leading Market Players |
|---|
| Sumitomo Chemical Co. Ltd |
| Asahi Kasei Corporation |
| Daramic LLC |
| SK ie Technology Corporation Ltd |
| Toray Battery Separator Film Co. Ltd |
| Freudenberg Performance Materials |
| Amer SIL |
| Ube Maxell Co. Ltd |
| Entek International |
| Others |
Pricing and Supply Chain Analysis
Extrusion capacity utilization at Pune and Chennai manufacturing parks concentrates margin pools among qualified polyethylene converters while compressing price floors for PVC-dependent competitors. Scale economies in microporous membrane production tether pricing power to BIS certification status and OEM direct-contract access, with uncertified domestic suppliers absorbing cost compression in aftermarket tiers.
Pricing Analysis
BIS certification mandates dictate the pricing tier structure across the India lead-acid battery separator landscape. Three-tier pricing stratifies across OEM-qualified polyethylene grades, BIS-compliant standard formulations, and uncertified economy PVC alternatives. Price differentiation hinges on oxidation resistance documentation and AIS-048 testing compliance, with passenger vehicle OEMs absorbing premiums for batch-traceable supply. Cost compression in PVC aftermarket tiers is intensifying because informal competitors evade hazardous waste directive compliance costs. Two-wheeler replacement channels exhibit highest price sensitivity, while commercial vehicle fleet operators prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Inventory carrying periods for specialty polyethylene resin extend operational lead times for domestic converters dependent on multinational feedstock suppliers. Geographic supply concentration centers on South Korea, Japan, and Singapore for high-purity polymer resin, with India-based extrusion operations drawing from these hubs. Raw material dependencies rest on high-density polyethylene pellets, microporous membrane additives, and oxidation stabilizer chemistries. Single-source vulnerability from concentrated resin suppliers exposes converters to currency and freight volatility. Distribution runs through direct annual volume agreements with tier-1 battery assemblers in Maharashtra and Tamil Nadu, bypassing legacy trading house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against lithium-ion penetration in two-wheeler electrification, where rural charging infrastructure gaps currently preserve SLI battery relevance but technology cost curves threaten incumbent positioning.
For Market Incumbents: Shield qualified supplier status through accelerated AIS-048 pre-certification investments ahead of formal BIS audits. Backward integration into specialty polyethylene resin sourcing reduces exposure to multinational supplier pricing power. Priority defensive moves center on extrusion capacity expansion in Hosur and Aurangabad manufacturing corridors to capture passenger vehicle OEM platform wins.
For New Entrants and Emerging Players: Lead with aftermarket channel digitization targeting tier-2 and tier-3 city battery workshops through B2B e-commerce platforms. The most penetrable white space sits in certified PVC separator segments serving price-sensitive rural two-wheeler replacement demand. Go-to-market execution should emphasize BIS traceability documentation as counterfeit detection differentiator against unbranded competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extrusion-technology converters holding OEM direct-supply agreements with 18-24 month qualification moats. Long-term viability across the projection horizon favors acquisition targets with proven oxidation resistance certification and localized technical service capabilities. The signal to watch is PLI scheme localization threshold adjustments impacting specialty polymer import economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive supply of high-purity polyethylene reduces currency exposure and secures batch consistency for OEM qualification. |
| Extrusion Capacity Expansion | Gauge control precision investments in Pune and Chennai close consistency gaps with imported separator benchmarks. |
| AIS-048 Pre-Certification Investment | Early compliance positioning accelerates BIS audit cycles and defends qualified supplier status against new entrants. |
| Aftermarket Channel Digitization | B2B platform reach to tier-2 and tier-3 cities compresses distributor tiers and expands margin capture. |
| Technical Service Localization | Localized application engineering in Tamil Nadu and Maharashtra anchors OEM relationships beyond commodity supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association publications. Primary interviews engaged separator manufacturing plant managers, procurement leads at automotive battery OEMs, distribution channel partners, and technical R&D directors at polymer converters. Secondary validation drew from BIS certification records, Central Pollution Control Board hazardous waste directives, PLI scheme documentation, and customs import data for specialty polyethylene resin. Bottom-up volume modeling triangulated against top-down market sizing from automotive production and battery replacement cycle analysis.
Segmentation dimensions modeled include material grade tier, end-user vehicle platform, manufacturing process technology, and distribution channel structure across the analysis window. CAGRs were derived from regression analysis of historical procurement patterns and projected platform-level battery content. Industry-specific forecast inputs incorporated rural electrification gap persistence, passenger vehicle OEM localization trends, and BIS enforcement intensity trajectories.
The analysis sits within stated boundaries; outcomes outside sustained ICE vehicle production, stable BIS certification timelines, or continued PLI scheme support would require recalibration. Forecasts reflect documented assumptions regarding specialty polymer supply chain localization and hazardous waste directive enforcement uniformity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
N-Type Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Primary Lithium Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Molten Salt Battery Market
Batteries
Forklift Battery Rental Market
Batteries
North America Industrial Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Cobalt-Free Battery Market
Batteries
North America Battery Market
Batteries
India Battery Market
Batteries
Atomic Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Myanmar Battery Market
Batteries
India SLI Battery Market