
 HIT Battery Market | 2026-2036
HIT Battery Market Size, Share, and Industry Trends Forecast 2026-2036
HIT Battery Market Insights
Chinese cylindrical cell producers is decoupling from legacy cobalt-dependent supply chains. Contemporary Amperex Technology Co. Limited leverages integrated cathode precursor operations to secure feedstock access. LG Energy Solution anchors its competitive stance through proprietary dry-electrode pilot lines in South Korea. BYD dominates vertically integrated cell-to-pack architectures for automotive applications.
HIT batteries deploy heterojunction silicon wafers paired with lithium-based electrochemical storage to achieve superior round-trip efficiency above 95% in commercial installations. Solid-state technology segments command premium positioning due to thermal stability advantages in stationary deployments. Lithium-ion chemistry leads volume absorption across renewable energy end users, while flow battery systems occupy niche utility-scale duration storage roles with extended cycle life.
Japan's METI enforces stringent JIS standards on thermal runaway propagation, compelling manufacturers to redesign cell barriers. China's SAMR integrates GB standards with dual carbon targets to restrict carbon-intensive production methods. South Korea's MFDS coordinates with industrial regulators to align battery passport traceability with EU CSRD disclosure requirements. Stakeholders must monitor evolving cross-border certification reciprocity between Asian production hubs and European import frameworks.
Market Dynamics
Heterojunction silicon wafer integration with lithium-based electrochemical storage is compressing round-trip efficiency thresholds above 95%, forcing incumbent manufacturers to retool cell barrier architectures and abandon legacy cobalt-dependent chemistries.
Growth Catalysts
- Germany utility-scale procurement:Renewable energy storage projects in Bavaria and North Rhine-Westphalia are accelerating high-efficiency battery system tenders. Grid operators specify heterojunction performance benchmarks in RFP documentation.
- Japan METI thermal runaway standards:JIS certification mandates on cell barrier redesign are creating technical differentiation for compliant suppliers. Domestic integrators prioritize certified modules in stationary deployments.
- China dual carbon alignment:SAMR GB standards restricting carbon-intensive production methods are redirecting capacity toward low-carbon precursor operations. Cathode material suppliers are retrofitting smelters to meet intensity thresholds.
Market Restraints
- Cobalt feedstock volatility:DRC concentrate supply interruptions and Indonesian nickel processing bottlenecks are amplifying cathode precursor cost swings. Cell producers lack price pass-through mechanisms in fixed-price utility contracts.
- South Korean dry-electrode concentration:Proprietary pilot line capacity in Ulsan and Gwangju industrial corridors creates single-source dependency for high-density anode coatings. Equipment lead times extend beyond 18 months.
- Solid-state manufacturing yield limits:Ceramic electrolyte sintering defects and lithium metal dendrite formation constrain commercial-scale production. Thermal stability advantages remain laboratory-demonstrated rather than field-proven.
Strategic Opportunities
- Australia grid-scale duration storage:Flow battery hybridization with heterojunction silicon buffers offers 8-12 hour discharge profiles for solar-smoothing applications. AEMO procurement frameworks favor multi-technology bids.
- South Korea MFDS-EU CSRD traceability alignment:Battery passport interoperability creates first-mover advantage for export-oriented cell producers. Integrated digital twin systems satisfy dual jurisdiction disclosure requirements.
- Automotive cell-to-pack convergence:BYD-style vertical architectures are penetrating commercial vehicle segments previously served by modular rack systems. Thermal management simplification reduces pack-level mass and assembly labor.
Industry Challenges
- Dry-electrode process engineering talent scarcity:Solvent-free coating expertise concentrates among former Maxwell Technologies engineers and Korean national laboratory alumni. Compensation premiums exceed 40% for qualified candidates.
- Cross-border certification reciprocity gaps:Japan METI JIS acceptance of China SAMR GB test data remains partial, forcing redundant cell-level testing. Timeline extensions compress project financing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIT Battery Market |
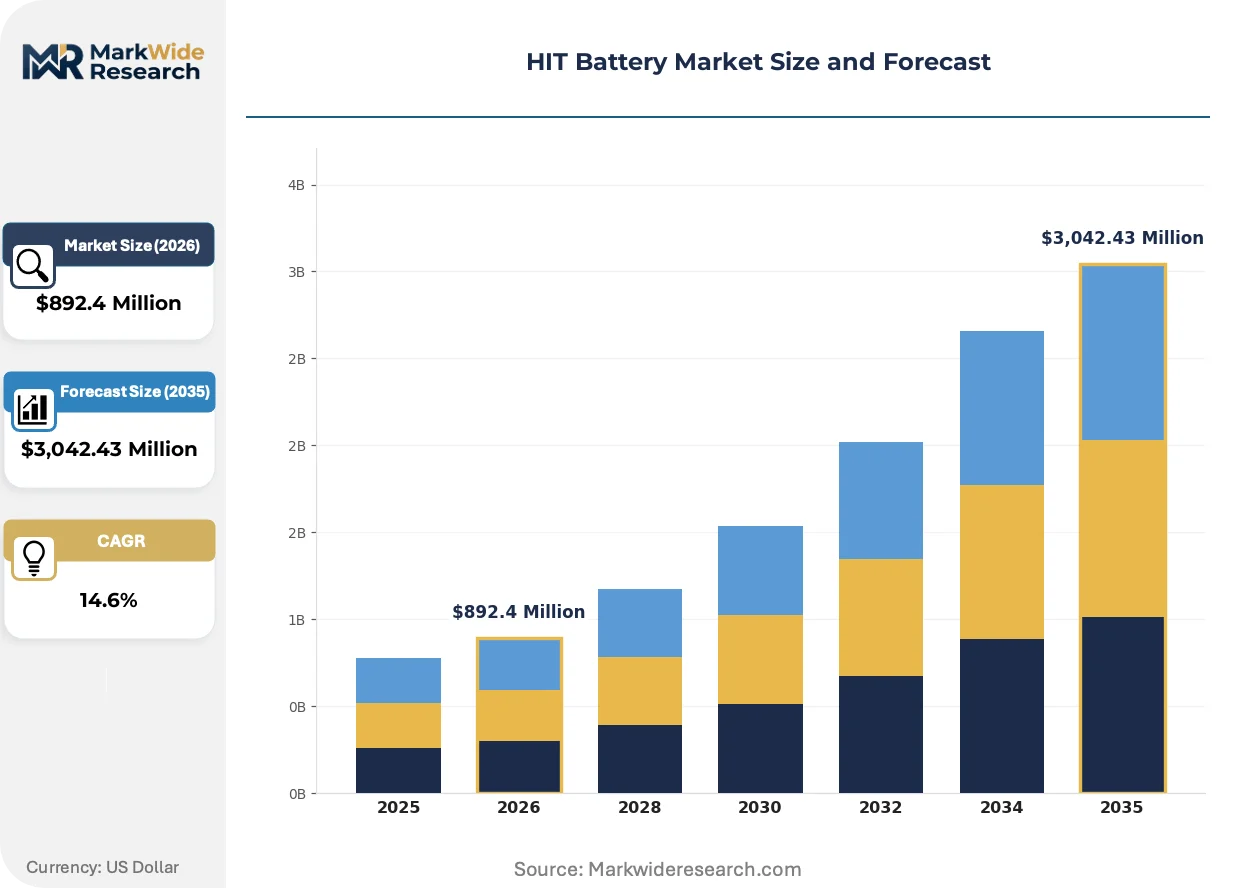
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $3,042.43 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Flow Battery Technology: Solid-State, Lithium Polymer, Ultra Capacitors, Hybrid End User: Automotive, Consumer Electronics, Industrial Equipment, Renewable Energy Deployment: On-grid, Off-grid, Portable, Stationary |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, BYD, Panasonic Holdings Corporation, Samsung SDI, SK On, Sunwoda Electronic, EVE Energy, REPT Battero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIT Battery Market Trends and Innovations
Silicon heterojunction electrochemistry is forcing simultaneous advances in wafer passivation, electrolyte formulation, and thermal management, collapsing previously sequential R&D cycles into integrated development programs.
Solid-state electrolyte architectures are unifying ceramic and polymer composite approaches into hybrid systems that retain lithium-ion manufacturing compatibility. Stationary storage developers in Germany and Japan are piloting these configurations for 10,000+ cycle targets. The technology is unifying thermal stability requirements with existing cylindrical cell form factors, compressing commercialization timelines from decade-scale to half-decade horizons.
EU CSRD sustainability disclosure mandates are compelling Asian cell producers to deploy blockchain-traceable cobalt and nickel sourcing documentation. South Korean manufacturers are retrofitting supply chain visibility systems to satisfy German importer due diligence requirements. Battery passport standardization under IEC 63333 is creating technical interoperability pressure across previously siloed national certification regimes.
Utility procurement committees are consolidating vendor qualification lists around integrated heterojunction-plus-storage system providers. Australian and German grid operators now specify single-point performance warranties spanning photovoltaic conversion and electrochemical storage. This concentration is displacing discrete component sourcing strategies that separated module and battery procurement functions.
HIT Battery Market Segmentation
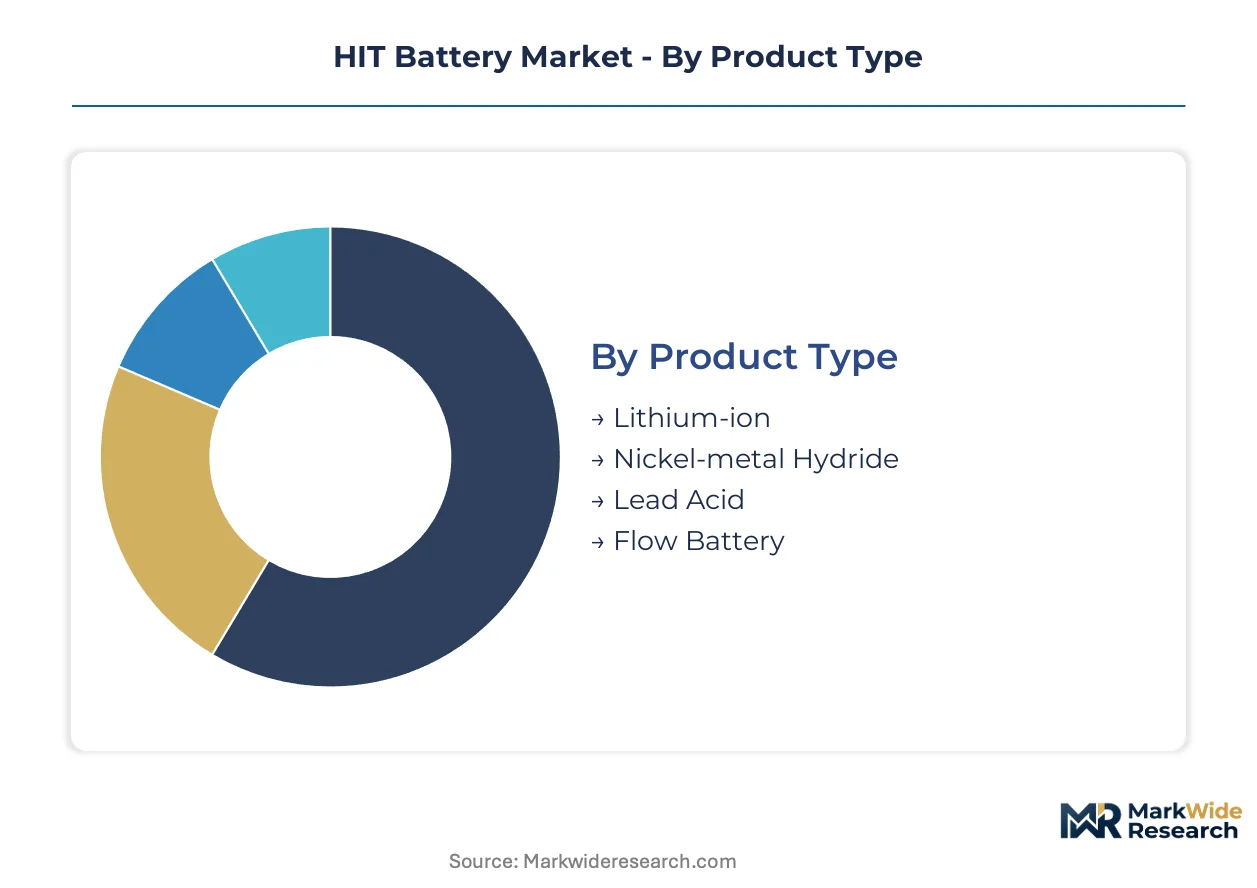
Heterojunction silicon wafer integration with lithium-based storage creates distinct performance tiers across electrochemical configurations. Procurement committees in Germany and Australia now specify segment-level efficiency benchmarks in unified RFP documentation rather than discrete component sourcing.
Product Type:
Upgrade cycles in utility-scale installations are compressing replacement timelines as heterojunction efficiency thresholds render legacy chemistries economically obsolete.
- Lithium-ion:Dominates commercial installations through cylindrical and prismatic form factors paired with heterojunction silicon buffers. Grid operators in Bavaria specify this chemistry for 95%+ round-trip efficiency in renewable smoothing applications. Thermal runaway propagation concerns under Japan METI JIS standards are accelerating cell barrier redesign investments.
- Flow Battery:Vanadium redox and zinc-bromide systems occupy utility-scale duration storage roles with 8-12 hour discharge profiles. AEMO procurement frameworks in Australia favor hybrid bids combining flow technology with heterojunction silicon integration for solar-smoothing. Extended cycle life offsets higher capital intensity in stationary deployments.
- Nickel-metal Hydride:Retains niche positioning in industrial backup power where temperature stability outweighs energy density requirements.
- Lead Acid:Concentrated in cost-sensitive portable applications with limited cycle depth requirements.
Lithium-ion sits at the top of the volume ranking, with flow battery climbing the fastest.
Technology:
Cost tier differentiation separates laboratory-demonstrated configurations from field-proven manufacturing platforms.
- Solid-State:Ceramic and polymer composite electrolytes achieve thermal stability advantages in stationary deployments. Sintering defects and lithium metal dendrite formation currently constrain yield rates at commercial scale. Germany and Japan are piloting hybrid configurations targeting 10,000+ cycle lifespans.
- Hybrid:Combines heterojunction silicon wafer integration with lithium-based electrochemical storage in unified system architectures. Australian and German grid operators now specify single-point performance warranties spanning photovoltaic conversion and storage functions. This configuration is displacing discrete component procurement strategies.
- Lithium Polymer:Flexible form factors penetrate consumer electronics and portable deployment segments.
- Ultra Capacitors:High-power density applications in industrial equipment requiring rapid charge-discharge cycles.
Hybrid technology commands the premium pricing tier, while solid-state represents the steepest expansion trajectory.
End User:
Application-specific thermal management requirements are fragmenting cell architecture specifications across customer types.
- Renewable Energy:Utility-scale solar and wind integration drives demand for heterojunction-plus-storage systems with unified performance warranties. Procurement in Germany's North Rhine-Westphalia and Australia's AEMO jurisdictions specifies multi-technology bids. Duration requirements of 4-8 hours favor lithium-ion volume absorption.
- Automotive:Cell-to-pack architectures are penetrating commercial vehicle segments previously served by modular rack systems. BYD-style vertical integration reduces pack-level mass through simplified thermal management. South Korea's Ulsan industrial corridor anchors production concentration.
- Industrial Equipment:Forklift and material handling applications prioritize cycle life over energy density.
- Consumer Electronics:Portable power requirements favor lithium polymer flexibility and form factor adaptability.
Renewable energy anchors volume absorption, with automotive gaining share fastest.
Deployment:
Customer type concentration varies sharply across grid-connected versus autonomous power architectures.
- Stationary:On-grid and off-grid installations in Germany and Australia specify heterojunction performance benchmarks in tender documentation. Japan METI JIS certification mandates on thermal runaway propagation are creating technical differentiation for compliant suppliers. Single-point warranties now span photovoltaic conversion and electrochemical storage.
- On-grid:Utility-scale renewable projects in Bavaria and North Rhine-Westphalia accelerate high-efficiency battery system procurement. Grid operators require 95%+ round-trip efficiency thresholds.
- Off-grid:Remote industrial and residential applications in Australia favor flow battery hybridization for extended duration requirements.
- Portable:Consumer and light industrial applications where mass and form factor flexibility predominate.
Stationary deployment leads volume concentration, with on-grid configurations expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting HIT battery production toward jurisdictions with lower carbon-intensity compliance costs. Manufacturers are relocating precursor processing capacity to exploit gaps between China's SAMR GB standards and Japan's METI JIS certification timelines.
China
SAMR GB standards restricting carbon-intensive production methods are forcing cathode material suppliers to retrofit smelters. The dual carbon goals framework redirects capacity toward low-carbon precursor operations in the Yangtze River Delta. Contemporary Amperex Technology leverages integrated cathode precursor operations in Fujian to secure feedstock access under tightened intensity thresholds.
Germany
Utility-scale renewable storage projects in Bavaria and North Rhine-Westphalia accelerate high-efficiency battery system tenders. Grid operators specify heterojunction performance benchmarks in RFP documentation requiring 95%+ round-trip efficiency. The KBA coordinates with EU CSRD disclosure frameworks to align battery passport traceability with import due diligence requirements.
Japan
METI enforces stringent JIS standards on thermal runaway propagation, compelling manufacturers to redesign cell barriers. Domestic integrators prioritize certified modules in stationary deployments. The Kanto region around Tokyo anchors demand concentration for compliant heterojunction-plus-storage systems in commercial installations.
Australia
AEMO procurement frameworks favor multi-technology bids combining flow battery hybridization with heterojunction silicon buffers for 8-12 hour discharge profiles. Solar-smoothing applications in New South Wales and Victoria drive grid-scale duration storage demand. The country's national energy regulator coordinates technical standards with IEC 63333 battery passport protocols.
South Korea
MFDS coordinates with industrial regulators to align battery passport traceability with EU CSRD disclosure requirements. The Ulsan and Gwangju industrial corridors concentrate proprietary dry-electrode pilot line capacity for high-density anode coatings. LG Energy Solution anchors production gravity through solvent-free coating expertise concentrated among national laboratory alumni.
HIT Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state thermal stability advantages and dry-electrode process differentiation. The vendor base stratifies across three tiers: integrated cathode precursor operators, proprietary coating technology holders, and cell-to-pack architecture specialists. Strategic archetypes include backward-integrated material suppliers, equipment-constrained process innovators, and vertically assembled system integrators. Dominant competitive moves center on capacity expansion in low-carbon precursor zones and technology licensing for solvent-free electrode coating.
Within the integrated precursor tier, Contemporary Amperex Technology Co. Limited occupies a position exemplifying captive supply chain control. LG Energy Solution and BYD anchor opposite ends of the competitive spectrum: the former represents proprietary process innovation concentrated in Korean industrial corridors, while the latter exemplifies vertical assembly architectures penetrating automotive segments. These three entities collectively illustrate how geographic regulatory alignment and manufacturing topology determine competitive positioning in heterojunction electrochemical storage.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| BYD |
| Panasonic Holdings Corporation |
| Samsung SDI |
| SK On |
| Sunwoda Electronic |
| EVE Energy |
| REPT Battero |
| Others |
Pricing and Supply Chain Analysis
Germany's 95% round-trip efficiency mandates in utility RFPs are forcing cathode precursor suppliers to absorb certification costs, compressing margins for non-integrated producers while rewarding backward-integrated operators with captive smelter capacity.
Pricing Analysis
Distributor markups in the HIT battery channel stratify across three tiers: premium configurations carrying Japan METI JIS certification, standard hybrid systems meeting China SAMR GB baselines, and economy lithium-ion packs for portable applications. Price differentiation hinges on thermal runaway test documentation and heterojunction silicon wafer integration depth. Pricing pressure stems from fixed-price utility contracts in Germany and Australia that block cathode cost pass-through. Renewable energy developers exhibit highest price sensitivity, while automotive OEMs prioritize performance warranties over unit economics.
Supply Chain Analysis
Workforce scarcity for solvent-free coating expertise concentrates in South Korea's Ulsan corridor, where Maxwell Technologies alumni command compensation premiums exceeding 40%. Geographic supply concentration centers on China for cathode precursor smelting, South Korea for dry-electrode pilot lines, and Japan for heterojunction silicon wafer processing. Raw material dependencies draw from Indonesian nickel processing, DRC cobalt concentrate, and Australian lithium spodumene. Single-source vulnerability pervades proprietary dry-electrode equipment with lead times extending beyond 18 months. Distribution runs through integrated system providers offering unified photovoltaic-plus-storage warranties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HIT battery market functions as a regulatory compounder where Japan METI JIS thermal runaway standards and China SAMR GB carbon intensity rules are accelerating replacement demand for certified systems.
For Market Incumbents: Acquire solvent-free coating engineering talent pools concentrated among Korean national laboratory alumni and former Maxwell Technologies specialists. Secure captive cathode precursor capacity in China's Yangtze River Delta to defend against SAMR carbon intensity thresholds. Prioritize JIS certification investment to maintain access to Japan's stationary deployment market against emerging solid-state challengers. For New Entrants and Emerging Players: Digital-channel routes through battery passport interoperability platforms offer low-friction entry into EU CSRD-aligned procurement flows. Target Australia's AEMO multi-technology bidding frameworks where flow battery hybridization with heterojunction silicon remains underpenetrated. Pursue white-space in 8-12 hour duration storage for solar-smoothing applications where incumbent lithium-ion configurations lack optimal economics. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated precursor operators possessing captive smelter capacity under tightening carbon intensity regimes. Long-term viability favors entities controlling both heterojunction silicon wafer supply and certified cell barrier architectures. Watch for IEC 63333 battery passport standardization completion as inflection signal for supply chain visibility premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Operations | Contemporary Amperex Technology leverages Fujian smelter retrofitting to secure feedstock access under China SAMR intensity thresholds. |
| Dry-Electrode Process Licensing | LG Energy Solution's proprietary pilot line expertise in Ulsan creates technology transfer opportunities for automotive cell-to-pack architectures. |
| Battery Passport Traceability Deployment | South Korean MFDS-EU CSRD alignment enables export-oriented producers to satisfy German KBA import due diligence requirements. |
| Flow Battery Hybridization Development | Australia AEMO procurement frameworks favor multi-technology bids combining vanadium redox systems with heterojunction silicon buffers. |
| JIS Certification Acceleration | Japan METI thermal runaway standards create technical differentiation for cell barrier redesign investments in stationary deployments. |
Research Methodology
Coverage spans Germany, Japan, China, South Korea, and Australia, with primary inputs from each jurisdiction triangulated against secondary validation. The research combines interviews with utility procurement officers, battery system integrators, cathode material plant managers, and dry-electrode process engineers with secondary sources including SAMR GB standard filings, METI JIS certification databases, AEMO tender documentation, and EU CSRD disclosure frameworks. Bottom-up project pipeline analysis and top-down regulatory impact modeling were cross-referenced for triangulation.
Granularity-level modeling addressed product type, technology configuration, end-user application, and deployment architecture across the analysis window. Segmentation dimensions included electrochemical chemistry, heterojunction integration depth, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements, tender award trajectories, and carbon intensity compliance cost projections. Forecast inputs incorporated dry-electrode yield improvement curves and solid-state ceramic electrolyte sintering defect rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state lithium metal architectures would alter the outlook if manufacturing yield constraints resolve faster than projected. Forecasts reflect assumptions on regulatory reciprocity timelines between Asian production hubs and European import frameworks. Material deviation in cobalt feedstock supply interruptions or dry-electrode equipment delivery schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Consumer Battery Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Lead Carbon Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Tubular Batteries Market
Batteries
Floor Scrubber Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Portable Battery Station Market
Batteries
Battery Separators Market
Batteries
High Voltage Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Electric Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
SLI Battery Market
Batteries
Battery-Powered Riveter Market