
 Global Cylindrical Lithium Battery Pack Market | 2026-2036
Global Cylindrical Lithium Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cylindrical Lithium Battery Pack Market Analysis
Specialized battery engineering talent is bifurcating between legacy consumer electronics and automotive-grade pack design, constraining OEMs seeking IEC 62660-certified production teams. LG Chem leverages its Korean R&D base to dominate cylindrical NMC supply for premium EV platforms. Panasonic Energy Co., Ltd. anchors North American capacity through its Nevada operations. Samsung SDI Co., Ltd. competes on high-nickel chemistry iterations for performance segments.
A cylindrical lithium battery pack is an electrochemical energy storage system comprising multiple cylindrical cells—typically 18650, 21700, or 4680 form factors—arranged in series-parallel configurations with integrated battery management systems and thermal regulation hardware; these assemblies deliver specified voltage and capacity outputs for motive, stationary, or portable power applications. NMC chemistry occupies the premium tier in EV traction applications where energy density governs range economics, while LFP formulations are penetrating energy storage systems and mid-range electric vehicles on cost and cycle-life advantages. Pack assembly and quality assurance stages capture disproportionate margin pools as OEMs insource these functions to secure traceability under emerging supply-chain due diligence rules.
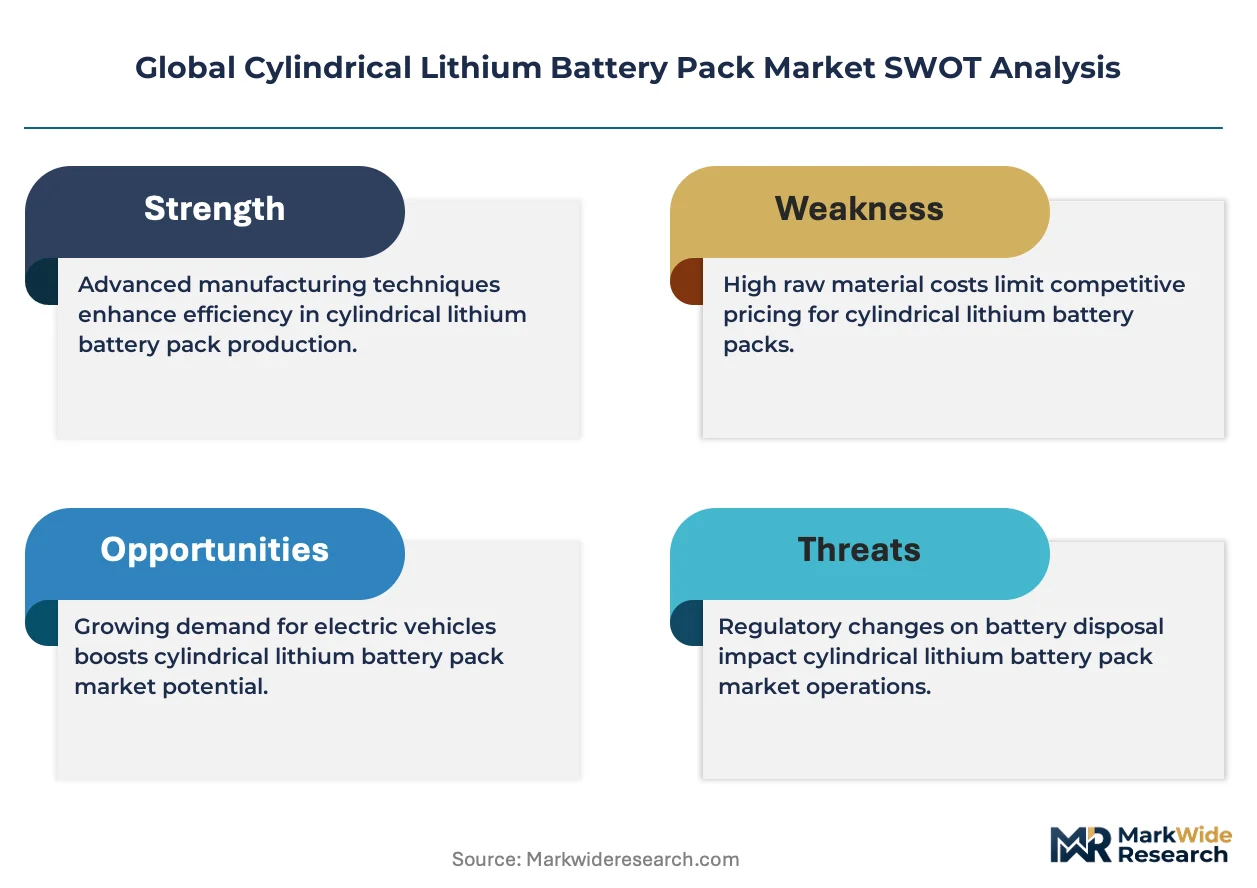
China's SAMR enforces GB/T standards for cell safety and recycling accountability, while the EU's Battery Regulation mandates carbon footprint declarations and recycled-content quotas that reshape import competitiveness. The US IRA domestic-content provisions are redirecting cell and pack assembly location decisions for suppliers serving North American EV demand. Stakeholders must monitor how divergent compliance timelines across Beijing, Brussels, and Washington alter capital allocation for new cylindrical pack capacity.
Market Dynamics
The cylindrical lithium battery pack market is reconfiguring around cell-to-pack architecture adoption, which eliminates module housings and compresses BOM costs while demanding precision thermal management at the cell level.
Growth Catalysts
- IRA Domestic Content Credits:US tax incentives for North American-assembled packs are redirecting capacity investments toward Nevada and Michigan manufacturing zones.
- High-Nickel Cathode Maturation:NMC 811 and 9½½ formulations are extending EV range thresholds, pulling demand from premium automotive platforms.
- China's Dual Carbon Mandate:MEE enforcement of carbon intensity caps is accelerating replacement of fossil-heavy production with renewable-powered cell manufacturing.
Market Restraints
- Cobalt Supply Concentration:DRC mining dominance creates price volatility and ESG audit exposure for NMC chemistry supply chains.
- Electrolyte Salt Bottleneck:LiPF6 production capacity in Japan and China is constraining pack output expansion regardless of cell fabrication readiness.
- Prismatic Format Substitution:Blade and cell-to-chassis designs from BYD and CATL are capturing share in cost-sensitive EV segments.
Strategic Opportunities
- India PLI Scheme Window:Cell and pack manufacturing incentives are opening first-mover positioning for cylindrical suppliers targeting two-wheeler electrification.
- Stationary Storage Convergence:Second-life EV packs are entering grid-scale applications, creating circular revenue streams outside automotive OEM contracts.
- EU Battery Regulation Recycled Content Mandates:Pre-2030 compliance pathways favor pack assemblers with closed-loop feedstock partnerships.
Industry Challenges
- IEC 62660 Certification Backlog:Testing laboratory capacity constraints are extending automotive qualification timelines by 8-14 months.
- Thermal Runaway Simulation Expertise:Finite-element modeling for cell-to-pack architectures requires rare cross-disciplinary talent combining electrochemistry and CFD.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cylindrical Lithium Battery Pack Market |
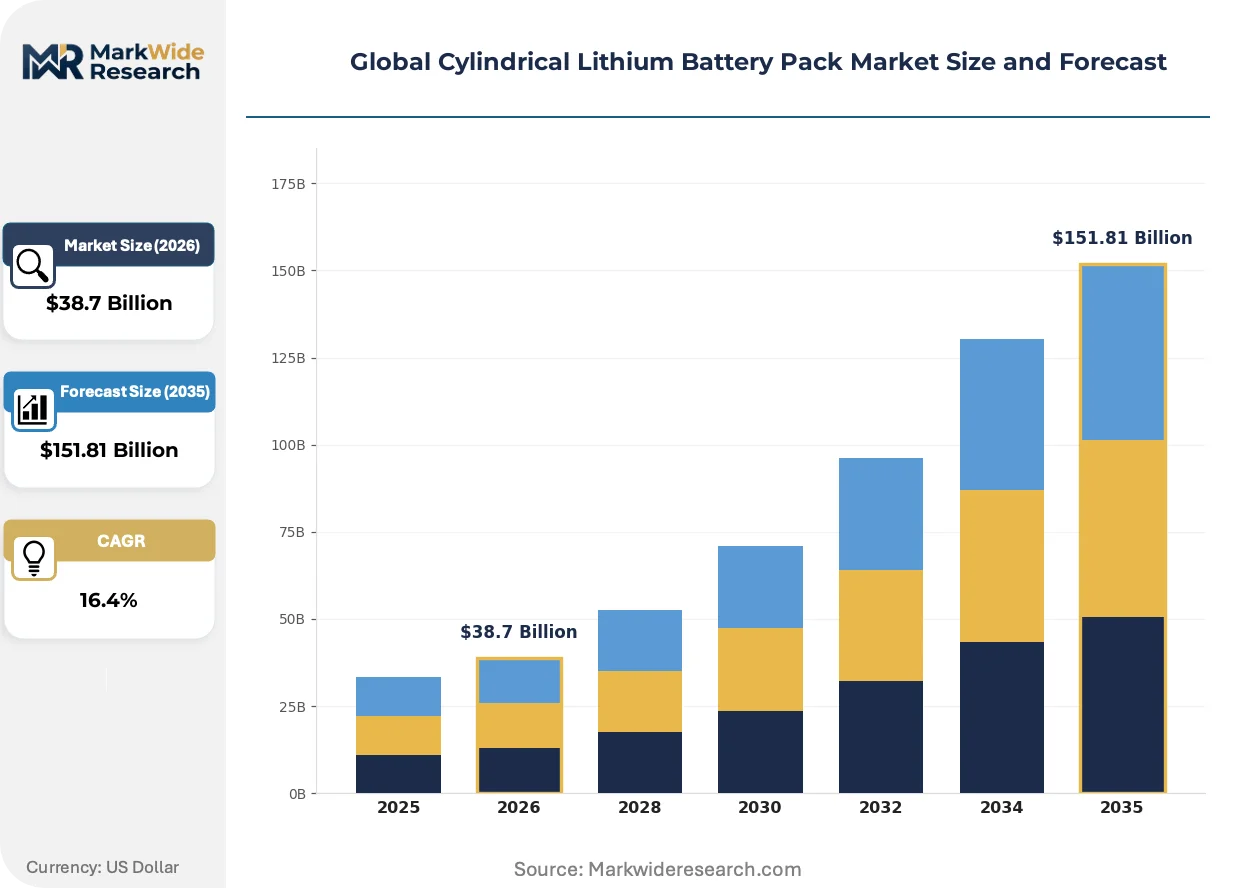
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, LTO, NCA End User: Consumer Electronics, Electric Vehicles, Industrial Equipment, Energy Storage Systems Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Manufacturing Stage: Raw Material Sourcing, Cell Production, Pack Assembly, Quality Assurance |
| Companies Covered | LG Chem, Sony Corporation, Contemporary Amperex Technology Co., Limited, Murata Manufacturing Co., Ltd., Hitachi, Ltd., Panasonic Energy Co., Ltd., EVE Energy Co., Ltd., Tianjin Lishen Battery Joint-Stock Co., Ltd., Samsung SDI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cylindrical Lithium Battery Pack Market Emerging Trajectories
Silicon-anode integration and dry electrode coating are compressing manufacturing energy intensity while pushing energy density boundaries. These process shifts are redrawing competitive advantage around materials science rather than scale alone.
Silicon-dominant anodes are decomposing the graphite supply chain's grip on energy density ceilings. Korean and Chinese cell makers are qualifying 10-15% silicon oxide blends for 21700 formats destined for performance EV platforms. The technology is decomposing incumbent cost structures by reducing cobalt dependence per kilowatt-hour.
EU Battery Regulation carbon footprint declarations are forcing pack-level lifecycle accounting from mining through recycling. Manufacturers must submit verified GHG intensity data to place products on the European market. Premium EV assemblers are responding by sourcing cells from Nordic hydropower-powered facilities to meet class thresholds.
Fleet operators and energy storage developers are consolidating procurement into multi-year offtake agreements with embedded price collars. Direct contracting is displacing spot market purchasing for volumes above 500 MWh annually. This pattern is most visible in California and Texas, where utility-scale storage developers seek supply certainty ahead of interconnection queues.
Global Cylindrical Lithium Battery Pack Market Segmentation
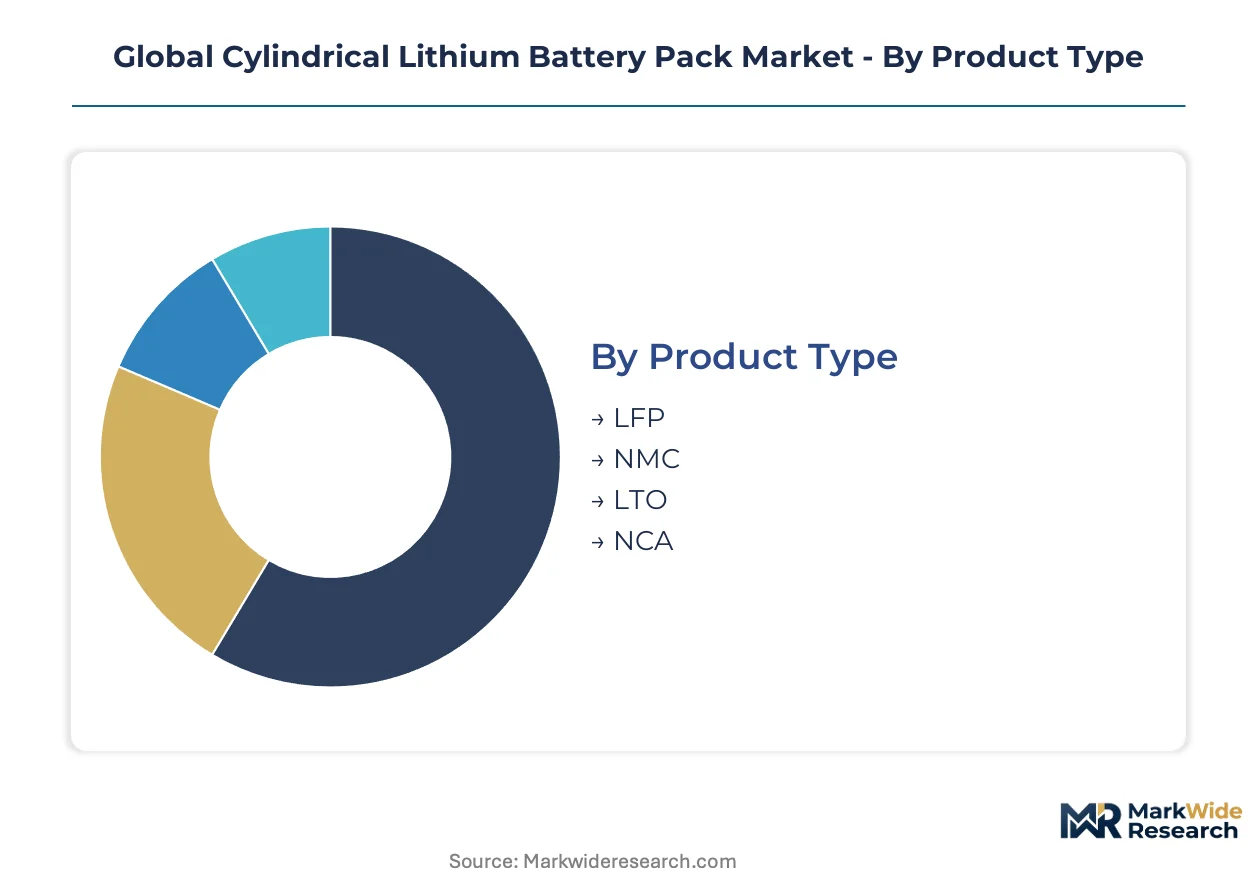
Cylindrical lithium battery pack segmentation reveals how chemistry choices, capacity tiers, and manufacturing stages allocate margin pools across divergent end-use channels. Channel economics differ sharply between automotive OEM direct procurement and industrial distributor networks.
Product Type:
LFP and NMC formulations dominate contrasting channel pathways—LFP flows heavily through energy storage integrators and mid-range EV platforms, while NMC commands premium automotive OEM direct contracts.
- NMC:Nickel-manganese-cobalt cathodes deliver the highest energy density among commercial cylindrical formats, typically 250-300 Wh/kg. Automotive OEMs in Germany and South Korea specify NMC 811 and 9½½ variants for premium EV platforms where range thresholds determine purchase decisions. IRA domestic-content provisions are redirecting NMC pack assembly toward Nevada manufacturing zones to secure tax credits.
- LFP:Lithium iron phosphate chemistry sacrifices energy density for thermal stability and cycle life, achieving 3000-6000 cycles versus 1000-2000 for NMC. Energy storage developers in Texas and California favor LFP for grid-scale projects where capital cost per kWh outweighs volumetric constraints. China's BYD and CATL are driving LFP cost curves down through massive scale.
- LTO:Lithium titanate anodes enable extreme fast-charging capabilities, charging to 80% in under 10 minutes.
- NCA:Nickel-cobalt-aluminum formulations serve niche high-performance applications requiring maximum specific energy.
By volume, LFP leads. By growth pace, NMC is ahead.
End User:
Cost tier stratification separates these segments—consumer electronics operates on thin margins with high volume, while energy storage systems command project-finance pricing with extended warranty terms.
- Electric Vehicles:Battery electric and plug-in hybrid platforms consume cylindrical packs in 50-100 kWh configurations for passenger cars and 200-800 kWh for commercial vehicles. Tesla's 4680 cell program and legacy 21700 supply chains anchor North American demand. High-nickel cathode maturation is extending range thresholds, pulling procurement toward 300+ mile platforms.
- Energy Storage Systems:Grid-scale and behind-the-meter installations deploy cylindrical packs in containerized 2-4 MWh units, with second-life EV packs entering this channel at 60-70% of new-cell cost. California utility-scale developers are consolidating procurement into multi-year offtake agreements with embedded price collars to secure supply ahead of interconnection queues.
- Consumer Electronics:Power tools, laptops, and personal mobility devices utilize 18650 and 21700 formats in 2-10 cell configurations.
- Industrial Equipment:Forklifts, automated guided vehicles, and mining equipment require ruggedized packs with IP67+ enclosures.
Electric Vehicles capture the largest revenue pool. Energy Storage Systems are expanding most quickly.
Capacity:
Application requirements and customer type determine capacity selection—automotive OEMs concentrate in high and ultra-high tiers, while industrial distributors stock medium-capacity SKUs for replacement markets.
- High Capacity:Packs rated 10-50 kWh serve commercial EV platforms and stationary storage cabinets, balancing energy density with thermal management complexity. South Korean cell makers are qualifying these formats for European premium automotive platforms subject to EU Battery Regulation carbon footprint declarations.
- Ultra High Capacity:Systems exceeding 50 kWh dominate long-range passenger EVs and utility-scale storage containers, where cell-to-pack architecture eliminates module housings. China's MEE enforcement of carbon intensity caps is accelerating renewable-powered manufacturing for this tier.
- Low Capacity:Sub-5 kWh packs power e-bikes, power tools, and portable electronics.
- Medium Capacity:5-10 kWh configurations serve light commercial vehicles and residential storage systems.
High Capacity generates current margin concentration. Ultra High Capacity shows the steepest expansion trajectory.
Manufacturing Stage:
Supply concentration and margin capture diverge across these stages—raw material sourcing and pack assembly concentrate in China, while quality assurance functions are regionalizing to meet local content rules.
- Pack Assembly:Module integration, battery management system installation, and thermal hardware mounting occur in automated facilities requiring IEC 62660 certification. OEMs are insourcing this stage to secure traceability under emerging supply-chain due diligence rules from the EU and US.
- Quality Assurance:Cell screening, cycle testing, and safety validation stages capture disproportionate margin pools as qualification timelines extend. Testing laboratory capacity constraints are extending automotive qualification timelines by 8-14 months.
- Raw Material Sourcing:Cathode active materials, anode graphite, and electrolyte salts originate from concentrated geographic sources.
- Cell Production:Electrode coating, winding, and formation processes represent the most capital-intensive manufacturing stage.
Pack Assembly commands strategic attention from OEMs. Quality Assurance faces the tightest capacity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards enforcement has concentrated cell-to-pack manufacturing in China's Ningbo and Gumi industrial corridors, redirecting capital flows toward IEC 62660-certified facilities as South Korea's MFDS tightens automotive-grade qualification timelines.
China
Electric vehicle OEM procurement of high-capacity NMC packs is accelerating in the Yangtze River Delta, with Ningbo manufacturing clusters absorbing the bulk of cell-to-pack capacity investments. MEE carbon intensity caps under the dual carbon mandate are forcing renewable-powered retooling of legacy fossil-heavy electrode coating lines. Tianjin Lishen and CATL-affiliated pack assemblers dominate the high-volume tier serving domestic EV platforms.
South Korea
Gumi's battery engineering talent pool is bifurcating between consumer electronics legacy and automotive-grade pack design, constraining OEM recruitment for IEC 62660-certified production teams. MFDS enforcement of cell safety documentation is extending qualification timelines by 8-14 months. Samsung SDI and LG Chem anchor the premium NMC supply chain for German and US automotive OEMs.
United States
IRA domestic-content provisions are redirecting cylindrical pack assembly decisions toward Nevada and Michigan manufacturing zones to secure tax credits. Tesla's 4680 program and Panasonic Energy's Nevada operations anchor North American high-nickel cathode demand. FERC interconnection queue pressures are driving California utility-scale storage developers into multi-year offtake agreements with embedded price collars.
Germany
Premium automotive OEMs in Bavaria and Baden-Württemberg specify NMC 811 and 9½½ variants for 300+ mile EV platforms where range thresholds determine purchase decisions. EU Battery Regulation carbon footprint declarations are forcing pack-level lifecycle accounting from mining through recycling. KBA enforcement of traceability requirements is accelerating OEM insourcing of pack assembly functions.
Japan
METI's battery supply chain resilience initiatives are subsidizing domestic electrode material production to reduce LiPF6 import dependence from Chinese and Japanese suppliers. Murata Manufacturing and Hitachi occupy positions in the precision electronics and industrial equipment pack tiers. Osaka-Kobe manufacturing corridors concentrate quality assurance functions serving ASEAN export markets.
Global Cylindrical Lithium Battery Pack Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with high-nickel chemistry specialists commanding premium margins in automotive OEM direct contracts while LFP-scale operators capture energy storage volume. The vendor base separates into three strategic tiers: Korean and Japanese incumbents with automotive qualification heritage, Chinese scale-driven integrated cell-pack producers, and mid-cap specialists focused on second-life circular applications. Dominant competitive moves include strategic partnerships for recycled-content feedstock security and geographic expansion into India PLI scheme windows.
Within the premium-tier vector, LG Chem and Samsung SDI Co., Ltd. represent the Korean automotive-grade archetype, leveraging domestic R&D infrastructure for high-nickel chemistry iterations. Panasonic Energy Co., Ltd. anchors the Japanese position in North American cylindrical supply, with Nevada-based operations exemplifying IRA-driven capacity relocation. Contemporary Amperex Technology Co., Limited occupies the scale-driven end of the LFP and integrated cell-to-pack spectrum, with cost curve compression capabilities that define the mid-range EV and energy storage channels.
| Leading Market Players |
|---|
| LG Chem |
| Sony Corporation |
| Contemporary Amperex Technology Co., Limited |
| Murata Manufacturing Co., Ltd. |
| Hitachi, Ltd. |
| Panasonic Energy Co., Ltd. |
| EVE Energy Co., Ltd. |
| Tianjin Lishen Battery Joint-Stock Co., Ltd. |
| Samsung SDI Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements with embedded price collars lock in supply access for utility-scale storage developers while compressing margin visibility for pack assemblers serving spot-market purchasers. California and Texas developers use these structures to secure cylindrical NMC and LFP volumes ahead of interconnection queue pressures, while IRA domestic-content provisions reshape location economics for North American contract premiums.
Pricing Analysis
Price spreads between Nordic hydropower-sourced cells and fossil-heavy Asian supply run 12-18% at pack level under EU Battery Regulation carbon footprint thresholds. Three-tier pricing structure across premium automotive-grade, standard industrial, and economy consumer tiers separates IEC 62660-certified production from distributor SKUs. Cost compression in mid-range LFP packs is intensifying because BYD and CATL scale advantages depress per-kWh benchmarks. Energy storage integrators exhibit highest price sensitivity; premium German OEMs show lowest.
Supply Chain Analysis
Strategic stockpiling of LiPF6 electrolyte salt dominates inventory strategy as Japanese and Chinese production constraints extend lead times regardless of cell fabrication readiness. Cathode active materials concentrate in China, South Korea, and Japan; anode graphite feeds from Chinese spherical graphite facilities. Single-source vulnerability in DRC cobalt creates ESG audit exposure for NMC chemistry supply chains. Distribution runs through automotive OEM direct procurement for premium tiers and industrial distributor networks for replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle management services represent the fastest-expanding revenue layer as second-life EV pack refurbishment and grid-scale redeployment outpace new hardware growth. Recurring revenue from performance monitoring, thermal management optimization, and end-of-life recovery contracts now commands margin multiples above cell manufacturing.
For Market Incumbents: Consolidate control over closed-loop feedstock partnerships to defend margin position against EU Battery Regulation recycled-content mandates. Expand IEC 62660-certified pack assembly capacity in Nevada and Michigan manufacturing zones to capture IRA tax credit eligibility. Deepen backward integration into cathode active material production to reduce LiPF6 and cobalt price volatility exposure.
For New Entrants and Emerging Players: Thermal runaway simulation expertise gaps among incumbent engineering teams open white-space for CFD-electrochemistry cross-disciplinary specialists. Target India's two-wheeler electrification segment under PLI scheme windows where cylindrical format dominance persists against prismatic substitution. Deploy performance-guarantee service contracts as primary go-to-market mechanism to differentiate from established hardware suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap pack assemblers with captive recycling partnerships and automotive qualification heritage. Long-term viability across the analysis window favors players with dual carbon mandate compliance pathways and renewable-powered manufacturing footprints. Watch for carbon footprint declaration threshold enforcement in Brussels as inflection indicator for Nordic cell sourcing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Partnership | EU Battery Regulation recycled-content mandates favor assemblers with pre-2030 feedstock security. |
| IEC 62660 Certification Investment | Automotive qualification timelines extend 8-14 months due to testing laboratory capacity constraints. |
| Cell-to-Pack Architecture Adoption | Eliminates module housings and compresses BOM costs while demanding precision thermal management. |
| Silicon-Anode Integration | Korean and Chinese cell makers qualify 10-15% silicon oxide blends for 21700 performance EV formats. |
| India PLI Scheme Manufacturing Entry | First-mover positioning opens for cylindrical suppliers targeting two-wheeler electrification volumes. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cylindrical pack engineering directors, automotive OEM procurement leads, energy storage project developers, and thermal management specialists; and secondary validation against SEC 10-K filings, customs and trade databases, IEA battery supply chain reports, and SAMR GB standards documentation. Bottom-up cell production and pack assembly capacity estimates were triangulated against top-down EV and stationary storage demand projections.
Across the projection horizon, the analytical framework modeled chemistry formulation, capacity tier, manufacturing stage, and end-use channel segmentation dimensions. CAGRs were derived from installed base growth curves and replacement cycle assumptions. Industry-specific inputs included IRA domestic-content credit eligibility thresholds, EU Battery Regulation carbon footprint class boundaries, and MEE dual carbon mandate enforcement timelines.
Forecasts assume regulatory continuity in US IRA provisions, EU Battery Regulation implementation, and China's GB/T standards enforcement; material policy shifts would require re-modeling. Specific risks include prismatic format substitution acceleration, LiPF6 supply disruption, and DRC cobalt supply chain ESG exclusions. Revision becomes warranted when cell-to-pack architecture adoption rates or silicon-anode qualification timelines cross threshold assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Portable Battery Pack Market
Batteries
Global Industrial Battery Market
Batteries
Italy SLI Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
US Motive Lead Acid Battery Market
Batteries
North America Industrial Battery Market
Batteries
Battery Anode Materials Market
Batteries
UAV Battery Pack Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
United States SLI Battery Market
Batteries
Europe Battery Market
Batteries
Advanced Batteries Market
Batteries
HIT Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Iron-Chromium Flow Battery Market