
 Europe Chip Mounter Market | 2026-2036
Europe Chip Mounter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chip Mounter Market Intelligence
The gap between premium high-speed automatic mounters and entry-level semi-automatic equipment is repositioning how European electronics manufacturers allocate capital. ASM Pacific Technology leverages its placement accuracy leadership to dominate automotive tier-one supplier lines. Yamaha Motor sustains competitive pressure through modular platform architectures that reduce retooling downtime. Mycronic differentiates via jet-printing integration that bypasses stencil constraints for low-volume, high-mix production.
Europe chip mounters are precision assembly machines that place surface-mount devices onto printed circuit boards at speeds exceeding 100,000 components per hour with placement accuracy below 35 microns, serving as the backbone of electronics manufacturing across automotive, medical, and telecommunications sectors. Automatic mounters command the dominant share of installed capacity, while 3D packaging technology represents the fastest-expanding segment as European semiconductor packaging houses invest in advanced heterogeneous integration. Surface mount technology anchors the majority of current demand, though mixed technology configurations are gaining traction among medical device manufacturers requiring through-hole reliability alongside miniaturized SMD components.
CE marking and the EU Green Deal shape equipment procurement criteria, with REACH compliance and energy efficiency benchmarks now embedded in vendor qualification processes across German, French, and Italian manufacturing bases. The F-Gas Regulation further constrains thermal management system choices in high-speed mounter designs. Stakeholders must monitor how the EU AI Act and evolving MDR requirements for connected medical devices redirect R&D spending toward traceability and validation capabilities.
Market Dynamics
Automotive electronics miniaturization is compressing placement tolerance requirements while simultaneously expanding throughput demands across European contract manufacturers serving EV powertrain and ADAS module assembly.
Growth Catalysts
- EU Green Deal manufacturing mandates:REACH compliance and energy efficiency benchmarks now embed directly into vendor qualification processes across German, French, and Italian production bases.
- Heterogeneous integration packaging:European semiconductor packaging houses are expanding 3D packaging capacity, creating parallel demand for precision mounters handling advanced substrates.
- Bavaria-Baden-Württemberg industrial corridor concentration:Tier-one automotive suppliers cluster in southern Germany, generating localized demand density for high-speed automatic equipment.
Market Restraints
- Specialized component supply concentration:High-precision linear motors and granite base frames concentrate among a limited supplier base in Switzerland and Japan, creating input vulnerability.
- F-Gas Regulation thermal constraints:The EU F-Gas Regulation limits refrigerant choices for thermal management systems in high-speed mounters, compressing cooling efficiency options.
- Plasma cleaning substitution threat:Laser ablation systems for PCB surface preparation are displacing traditional chemical flux processes, altering upstream equipment pairing requirements.
Strategic Opportunities
- Poland-Czech Republic manufacturing expansion:Automotive electronics producers are establishing captive assembly capacity in central Europe, creating greenfield equipment demand outside established German clusters.
- EU AI Act traceability requirements:Connected medical device manufacturers must embed component-level tracking, opening retrofit and validation service revenue streams.
- Jet-printing convergence with mounter platforms:Integration of solder paste deposition directly onto placement heads eliminates stencil constraints for high-mix, low-volume medical device production.
Industry Challenges
- Multi-axis motion control expertise scarcity:European manufacturers face acute shortages of engineers proficient in simultaneous five-axis kinematics for sub-35-micron placement accuracy.
- MDR validation timeline compression:Medical device regulation certification cycles for connected manufacturing equipment now extend 14-18 months, delaying revenue recognition on medical segment orders.
- Legacy Siemens S7 integration friction:Brownfield automotive plants running legacy PLC architectures require costly middleware development to interface with modern mounter control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chip Mounter Market |
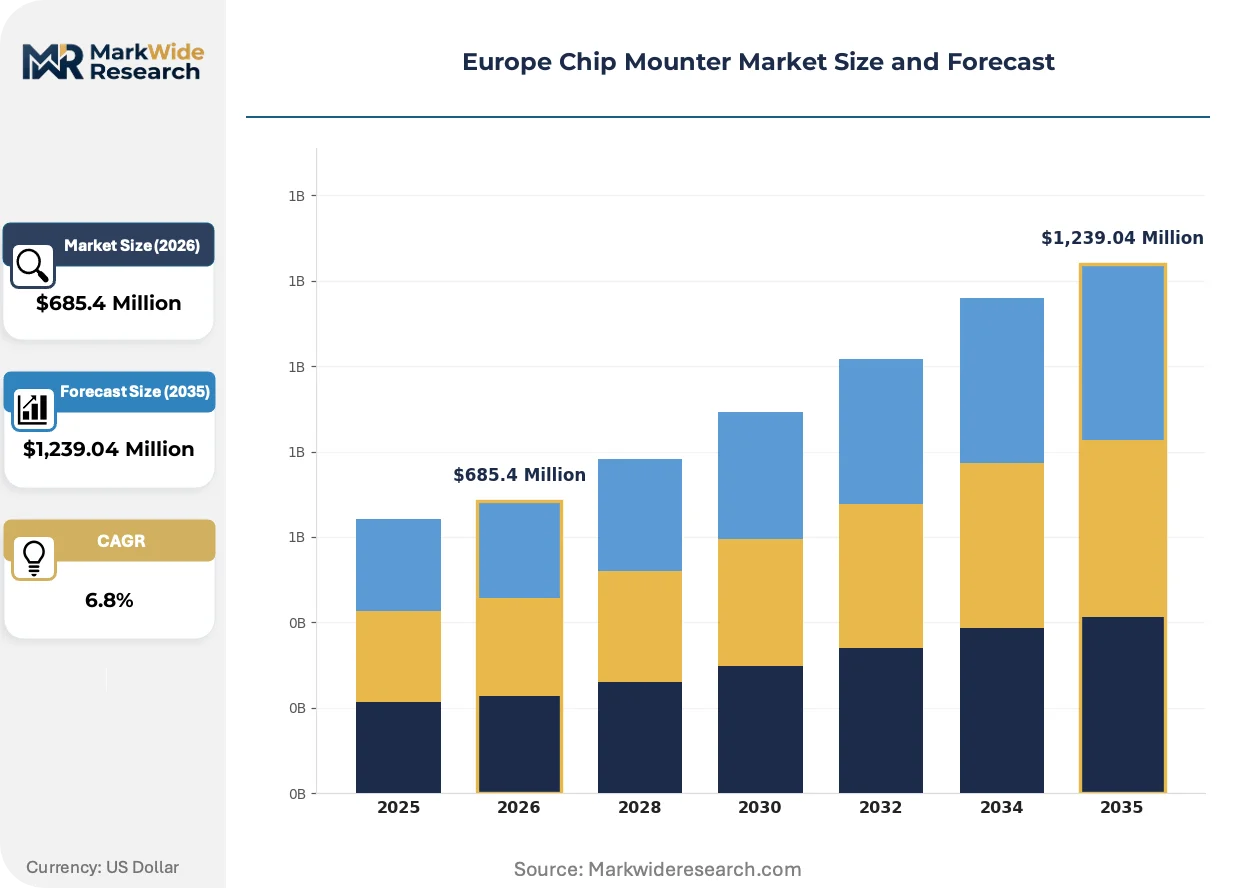
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Mounters, Semi-Automatic Mounters, Manual Mounters, Hybrid Mounters End User: Telecommunications, Consumer Electronics, Automotive, Medical Devices Technology: Surface Mount Technology, Through-Hole Technology, Mixed Technology, 3D Packaging Application: Smartphones, Tablets, Wearables, IoT Devices |
| Companies Covered | ASM Pacific Technology, Fuji Corporation, Yamaha Motor, Panasonic, JUKI, Mycronic, Essemtec AG, Hanwha Precision Machinery, Nordson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chip Mounter Market Strategic Shifts & Innovations
Machine vision convergence with real-time placement correction is redefining accuracy benchmarks while regulatory traceability mandates are forcing architectural changes in control software design.
Multi-nozzle placement heads equipped with independent Z-axis control are automating simultaneous component handling across varying board topographies. Medical device manufacturers in Switzerland and southern Germany are adopting these configurations fastest, compressing changeover intervals from hours to minutes for high-mix production environments. The technology is automating the elimination of dedicated changeover stations, reducing floor space requirements by integrating setup functions directly into the placement module.
EU AI Act algorithmic transparency requirements now govern machine learning-based placement optimization in connected medical device production. Manufacturers must document training data provenance and decision pathways for regulatory audits, adding software architecture costs. German medical electronics specialists are responding by segregating AI-enabled modules into isolatable subsystems that can be disabled without halting production.
Contract manufacturers are unbundling after-sales service agreements from initial equipment purchases, shifting toward per-placement or uptime-based service models. This disrupts traditional distributor channels that previously captured multi-year service contract margins. The pattern is most visible among mid-sized EMS providers in France and Italy seeking to align operating expenditures with production volume volatility rather than absorbing fixed maintenance commitments.
Europe Chip Mounter Market Segmentation
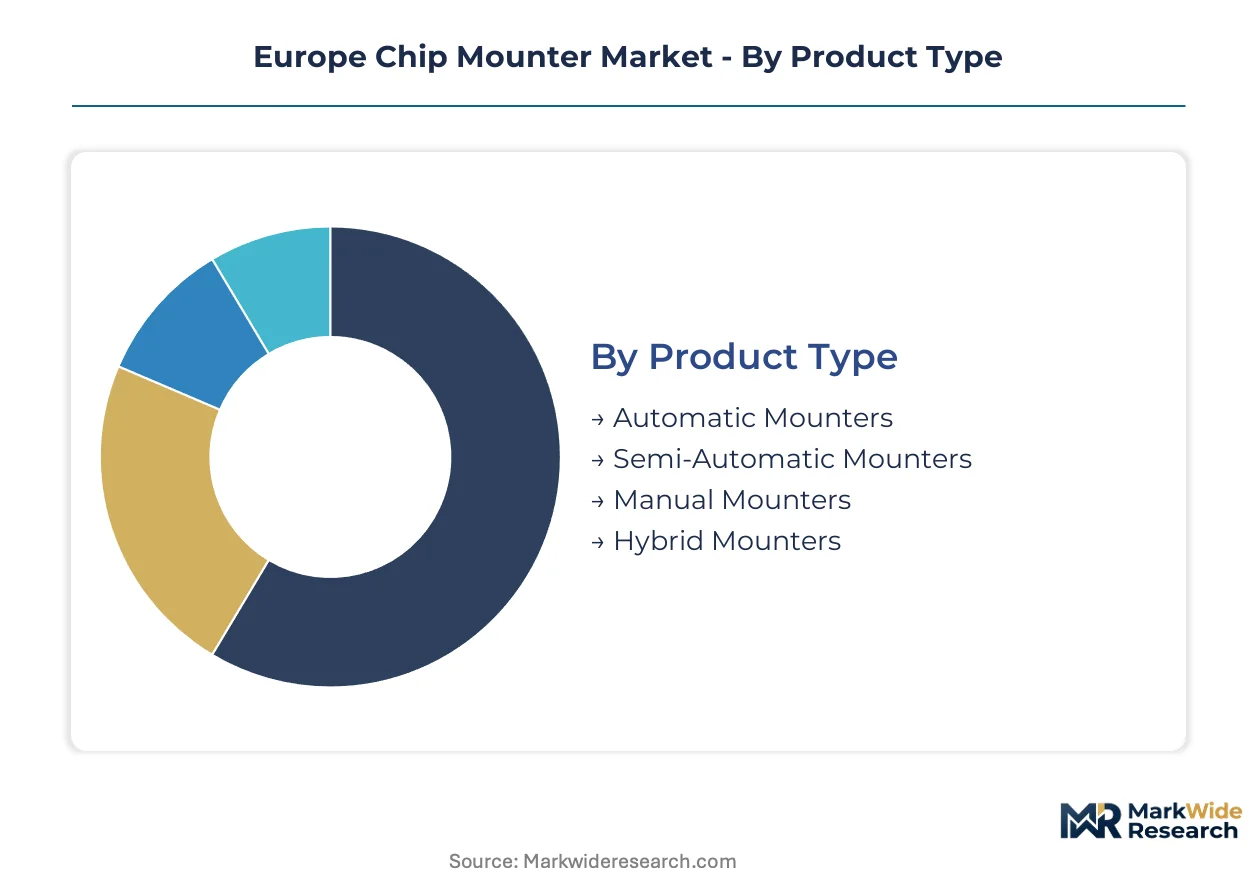
European chip mounter procurement splits sharply across regulatory intensity tiers, with CE marking and EU Green Deal compliance creating divergent qualification pathways for equipment categories. Segmentation reveals how automotive and medical end-users impose fundamentally different validation burdens than consumer-facing buyers.
Product Type:
CE marking requirements and REACH substance restrictions apply differentially across automation tiers, with high-speed automatic systems facing the most intensive conformity assessment protocols.
- Automatic Mounters:High-speed placement systems achieving sub-35-micron accuracy with throughput exceeding 100,000 components per hour dominate Bavarian and Baden-Württemberg automotive corridors. F-Gas Regulation thermal constraints compress cooling system choices for these energy-intensive platforms.
- Semi-Automatic Mounters:Modular platforms with reduced retooling downtime serve mid-volume EMS providers in France and Italy seeking flexibility without full automation capital commitment. REACH compliance costs weigh less heavily here than on fully automatic lines.
- Manual Mounters:Entry-level benchtop units for prototype and repair operations face minimal regulatory overhead.
- Hybrid Mounters:Configurations blending automatic and semi-automatic modes accommodate high-mix medical device production in Switzerland.
Automatic Mounters sits at the top of the volume ranking, with Hybrid Mounters climbing the fastest.
End User:
Margin structures diverge dramatically across buyer categories, with regulatory validation timelines directly compressing profitability on medical and automotive contracts versus telecommunications.
- Automotive:EV powertrain and ADAS module assembly drives demand for simultaneous five-axis kinematics among tier-one suppliers clustered in southern Germany. EU Green Deal manufacturing mandates embed energy efficiency benchmarks directly into vendor qualification.
- Medical Devices:Connected equipment manufacturers face 14-18 month MDR certification cycles and EU AI Act traceability requirements. Swiss and German specialists segregate AI-enabled modules into isolatable subsystems for audit compliance.
- Telecommunications:Base station and network infrastructure producers prioritize throughput over placement tolerance.
- Consumer Electronics:Polish and Czech Republic manufacturing expansion creates greenfield demand outside established German clusters.
Automotive commands the dominant revenue share, with Medical Devices expanding most quickly.
Technology:
Application maturity separates legacy surface mount dominance from emerging heterogeneous integration formats requiring fundamentally different capital deployment.
- Surface Mount Technology:Established SMD placement anchors current installed capacity across European contract manufacturers. The technology serves high-volume smartphone and tablet production with proven reliability.
- 3D Packaging:Advanced heterogeneous integration for semiconductor packaging houses demands precision handling of complex substrates. European facilities are expanding capacity fastest in this segment.
- Mixed Technology:Configurations combining SMD and through-hole reliability gain traction among medical device manufacturers requiring legacy component compatibility.
- Through-Hole Technology:Declining share confined to specialized industrial and military applications with extreme reliability requirements.
Surface Mount Technology holds the largest installed base, with 3D Packaging gaining share fastest.
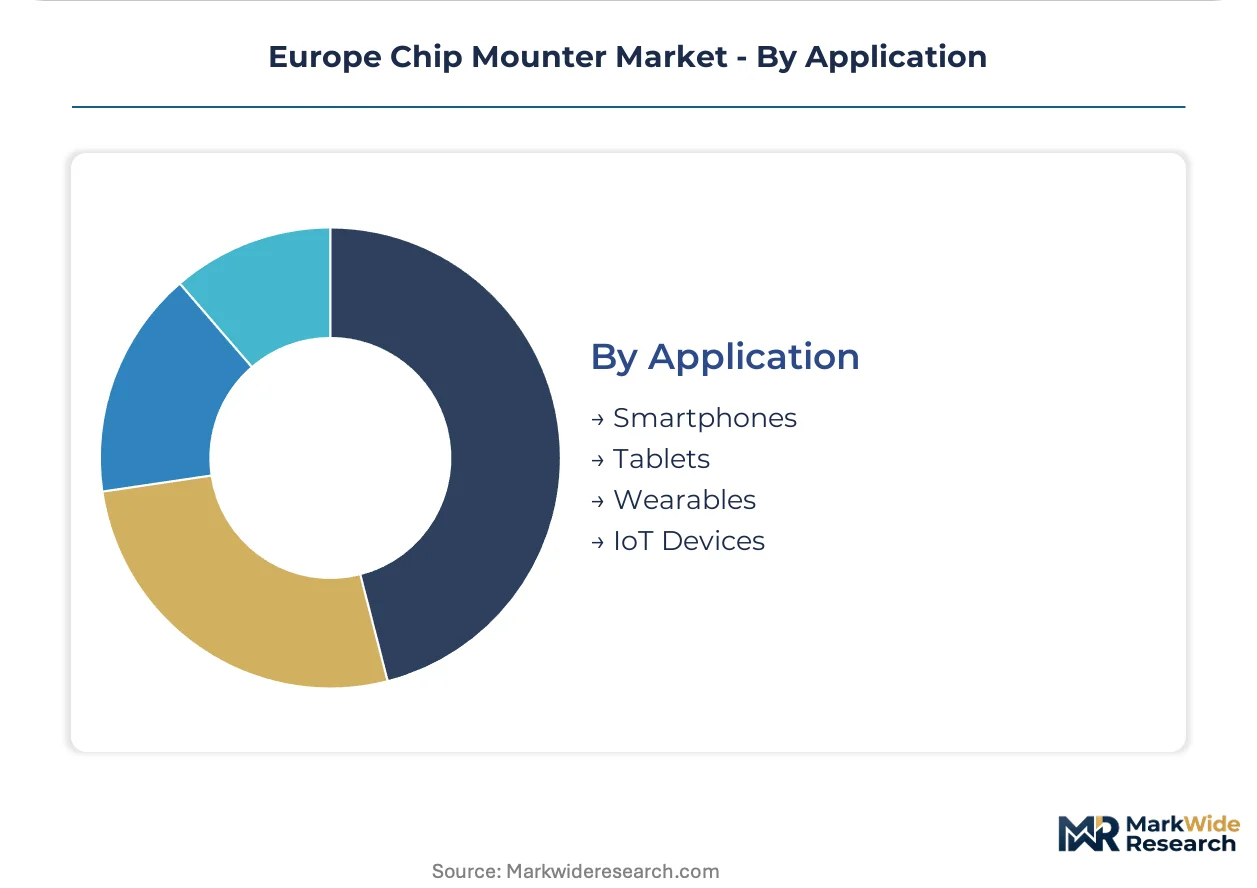
Application:
Device miniaturization trajectories and production scale economics determine equipment specification priorities across consumer and industrial endpoints.
- Smartphones:Extreme component density and placement speed requirements drive specification of the most advanced automatic mounters. Production concentrates among large EMS providers with dedicated high-volume lines.
- IoT Devices:Fragmented demand across industrial, medical, and consumer endpoints favors flexible semi-automatic and hybrid configurations. The category spans the widest range of volume and mix requirements.
- Tablets:Mature demand curve with established supply chains limits new equipment procurement to replacement cycles.
- Wearables:Miniaturized form factors and specialized sensor integration create niche demand for high-precision placement.
Smartphones leads absolute unit demand, with IoT Devices showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision motion control engineers concentrate in southern Germany's industrial corridor, anchoring Europe's densest cluster of chip mounter expertise. Bavarian technical universities feed specialized talent directly into automotive electronics assembly lines. CE marking and REACH compliance requirements shape vendor qualification across all manufacturing bases.
Germany
Tier-one automotive suppliers in Bavaria and Baden-Württemberg drive demand for sub-35-micron placement accuracy in EV powertrain modules. The EU Green Deal embeds energy efficiency benchmarks into procurement criteria for high-speed automatic equipment. Stuttgart's industrial corridor hosts the continent's densest concentration of ADAS module assembly capacity.
Switzerland
Medical device manufacturers in Basel and Zurich require MDR-validated equipment with 14-18 month certification cycles for connected production lines. Swissmedic oversight and EU AI Act traceability mandates force architectural changes in control software design. Geneva-area packaging houses specialize in high-mix, low-volume heterogeneous integration.
France
Mid-sized EMS providers in the Île-de-France and Auvergne-Rhône-Alpes regions favor modular semi-automatic platforms to align operating expenditures with production volatility. ANSM medical device regulations and CE marking protocols apply differentially across automation tiers. Grenoble's semiconductor research cluster generates adjacent demand for advanced substrate handling.
Italy
Telecommunications infrastructure producers in Lombardy and Emilia-Romagna prioritize throughput over placement tolerance for base station assembly. REACH substance restrictions weigh less heavily on semi-automatic lines than on fully automatic systems. Bologna's industrial automation district supports regional equipment integration capabilities.
Poland
Automotive electronics producers establish captive assembly capacity in the Silesian and Greater Poland voivodeships, creating greenfield equipment demand outside German clusters. EU structural funds accelerate manufacturing modernization in central European locations. Wrocław's emerging electronics hub attracts contract manufacturers serving German automotive supply chains.
Europe Chip Mounter Market Key Industry Players
Top-tier vendors anchor high-speed automatic placement, while mid-tier specialists occupy modular semi-automatic niches. The vendor base stratifies across three archetypes: precision accuracy leaders serving automotive validation requirements, platform modularity providers reducing retooling downtime, and jet-printing integrators bypassing stencil constraints. M&A activity concentrates on motion control technology acquisitions, while geographic expansion targets Poland-Czech Republic manufacturing greenfields.
Within the precision-tier segment, ASM Pacific Technology and Yamaha Motor occupy positions exemplifying divergent technical strategies, with the former representing placement accuracy leadership and the latter platform modularity architectures. Mycronic sits within the specialized tier, its jet-printing convergence approach illustrating how solder paste deposition integration eliminates stencil dependencies for medical device production. Panasonic and JUKI anchor the scale-driven mid-market, their geographic distribution reflecting broader Asia-Pacific manufacturing equipment penetration into European automotive corridors. Fuji Corporation exemplifies the vertically integrated precision motion control archetype, while Hanwha Precision Machinery represents Korean manufacturing equipment expansion into central European greenfield sites.
| Leading Market Players |
|---|
| ASM Pacific Technology |
| Fuji Corporation |
| Yamaha Motor |
| Panasonic |
| JUKI |
| Mycronic |
| Essemtec AG |
| Hanwha Precision Machinery |
| Nordson |
| Others |
Cost & Logistics Intelligence
Multi-axis motion control engineers concentrated in Bavaria and Baden-Württemberg command wage premiums that compress margins on high-precision automatic mounters while widening spreads between premium and standard equipment tiers.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across European chip mounter procurement. Contract manufacturers unbundle after-sales agreements from initial purchases, shifting toward per-placement or uptime-based models that align operating expenditures with production volatility. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked medical-validated systems from automotive-grade equipment and entry-level semi-automatic platforms. Price differentiation hinges on MDR certification status and energy efficiency benchmarking under EU Green Deal mandates. Mid-sized EMS providers in France and Italy exhibit highest price sensitivity, while tier-one automotive suppliers in southern Germany absorb premium positioning for sub-35-micron accuracy systems.
Supply Chain Analysis
Freight cost escalation on precision granite base frames and linear motor assemblies from Switzerland and Japan compresses landed cost predictability for European mounter assemblers. Component sourcing draws from specialized suppliers concentrated in Switzerland, Japan, and Germany for high-precision motion systems, with control electronics anchored in South Korean and Taiwanese manufacturing bases. Raw material dependencies span rare-earth magnet alloys for linear motors, vibration-dampening granite substrates, and thermal management refrigerants constrained by F-Gas Regulation limits. Single-source vulnerability concentrates in Swiss and Japanese precision component suppliers. Distribution runs through authorized distributor networks capturing service contract margins, though direct OEM relationships are expanding among large automotive contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's chip mounter market functions as a regulatory compounder where MDR certification timelines and EU AI Act traceability mandates create durable demand for validated equipment architectures.
For Market Incumbents: Extend platform modularity architectures to compress retooling downtime for high-mix medical device production, defending against jet-printing substitution threats from Mycronic's solder paste deposition integration. Deepen backward integration into precision motion control components to offset supply concentration risk from Swiss and Japanese linear motor suppliers. Prioritize CE marking and REACH compliance investments as qualifying barriers against Asian equipment encroachment. For New Entrants and Emerging Players: Launch via direct OEM relationships with automotive electronics producers establishing captive assembly capacity in Poland's Silesian and Greater Poland voivodeships, bypassing entrenched German distributor channels. Target the semi-automatic modular segment serving mid-volume EMS providers in France and Italy seeking flexibility without full automation capital commitment. Emphasize per-placement service pricing to align with buyer preference for operating expenditure alignment. For Investors and Strategic Acquirers: Precision motion control technology specialists are the most active acquirer target category in this space, with Korean manufacturing equipment conglomerates and European industrial automation groups consolidating engineering talent. Long-term viability hinges on exposure to heterogeneous integration packaging expansion and medical device traceability mandates. Monitor MDR certification backlog duration at notified bodies as the critical inflection signal for equipment demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Jet-Printing Convergence Integration | Eliminates stencil constraints for high-mix Swiss and German medical device production. |
| Poland-Czech Republic Manufacturing Footprint | Captures greenfield automotive electronics demand outside saturated German industrial corridors. |
| MDR Validation Service Expansion | Opens 14-18 month certification cycle revenue streams for connected medical equipment. |
| EU AI Act Traceability Module Development | Enables algorithmic transparency compliance for machine learning-based placement optimization. |
| Precision Motion Control Acquisition | Secures scarce five-axis kinematics expertise concentrated in southern German technical universities. |
Research Approach
Bottom-up automotive and medical electronics modeling reconciled against top-down semiconductor packaging capacity tracking forms the analytical core of this study. Primary interviews with tier-one automotive supplier procurement directors, medical device manufacturing engineers, EMS provider operations heads, and precision motion control R&D specialists informed demand-side assumptions. Secondary validation drew from CE marking databases, ECHA REACH substance restriction filings, EU structural fund disbursement records for central European manufacturing, and semiconductor packaging equipment trade data. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped placement accuracy requirements to equipment specifications across the projection horizon, with segmentation modeling spanning automation tier, end-use industry, packaging technology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and heterogeneous integration investment trends. Forecast inputs incorporated F-Gas Regulation thermal constraint impacts on high-speed system design and MDR certification timeline compression effects on medical segment order recognition.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged MDR notified body backlogs or accelerated plasma cleaning substitution for traditional flux processes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
X-Ray Lithography Equipment Market