
 CO2 Laser Market | 2026-2036
CO2 Laser Market Size, Share, and Industry Trends Forecast 2026-2036
CO2 Laser Market Analysis
Integration of beam-delivery robotics with real-time seam-tracking software is tilting capital allocation toward fully automated cutting cells. Trumpf leverages in-house resonator manufacturing to control core component supply. Coherent Inc. anchors its position through deep vertical integration into laser optics and beam-delivery subsystems. IPG Photonics Corporation differentiates via fiber-laser crossover R&D that informs CO2 source efficiency gains.
A CO2 laser generates infrared light at 10.6 micrometers wavelength by electrically exciting a gas mixture of carbon dioxide, nitrogen, and helium within a resonant cavity, producing continuous or pulsed output for material removal, joining, or surface modification. Laser cutting equipment commands the largest installed base among product types, though laser welding equipment is expanding fastest as automotive lightweighting intensifies joint-quality requirements. Continuous wave technology dominates industrial throughput applications, while pulsed configurations capture margin in precision medical and micro-machining segments where heat-affected zone control determines clinical outcomes.
The FDA regulates medical CO2 lasers under 21 CFR 1040.10 laser performance standards, while the EU MDR and ISO 13485 framework govern market access for surgical devices in Europe. OSHA laser safety standards in the United States mandate enclosure interlocks and protective eyewear protocols that shape system design and facility compliance costs. Stakeholders must monitor how evolving semiconductor-laser competition and tightening energy-efficiency regulations in industrial end-use jurisdictions reshape total cost-of-ownership calculations for new CO2 installations.
Market Dynamics
Beam-delivery robotics fused with real-time seam-tracking software is redirecting capital toward fully automated cutting cells, compressing replacement cycles for standalone CO2 systems in precision manufacturing clusters.
Growth Catalysts
- EU MDR documentation mandates:The EU MDR framework tightens performance documentation requirements for medical laser devices, accelerating hospital surgical suite upgrades across Germany, France, and Italy.
- Automotive lightweighting intensity:Joint-quality specifications for aluminum and high-strength steel assemblies in electric vehicle platforms are expanding laser welding equipment demand faster than cutting systems.
- German precision manufacturing clusters:Stuttgart and Munich industrial corridors drive replacement demand for high-wattage industrial CO2 systems as fiber-laser competition forces efficiency improvements.
Market Restraints
- Gas mixture input volatility:Helium supply concentration in Qatar and Russia creates cost unpredictability for resonator gas mixtures, squeezing margins on continuous-wave systems.
- Fiber-laser substitution threat:Solid-state fiber sources at 1.06 micrometers now match CO2 cutting speeds on thin-gauge steel, eroding the installed base in sheet-metal job shops.
- OSHA enclosure compliance burden:Laser safety standards mandate interlocked enclosures and protective eyewear protocols that add facility retrofit costs for legacy system operators.
Strategic Opportunities
- Medical micro-machining white space:Pulsed CO2 configurations for stent cutting and ophthalmic applications remain underpenetrated in Japan and South Korea despite aging demographics.
- ISO 13485 certification arbitrage:Quality management system accreditation opens surgical device supply chains to European and North American hospital procurement networks.
- Beam robotics convergence:Integration of articulated-arm delivery systems with machine-vision seam tracking creates premium positioning for automated cell vendors against standalone source suppliers.
Industry Challenges
- Resonator technician scarcity:Specialized gas discharge cavity maintenance skills are concentrating at Trumpf and Coherent service centers, lengthening downtime for independent operators.
- Legacy system integration friction:Retrofitting 10.6-micron beam delivery to existing CNC motion platforms requires custom kinematic calibration that delays automated cell deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2 Laser Market |
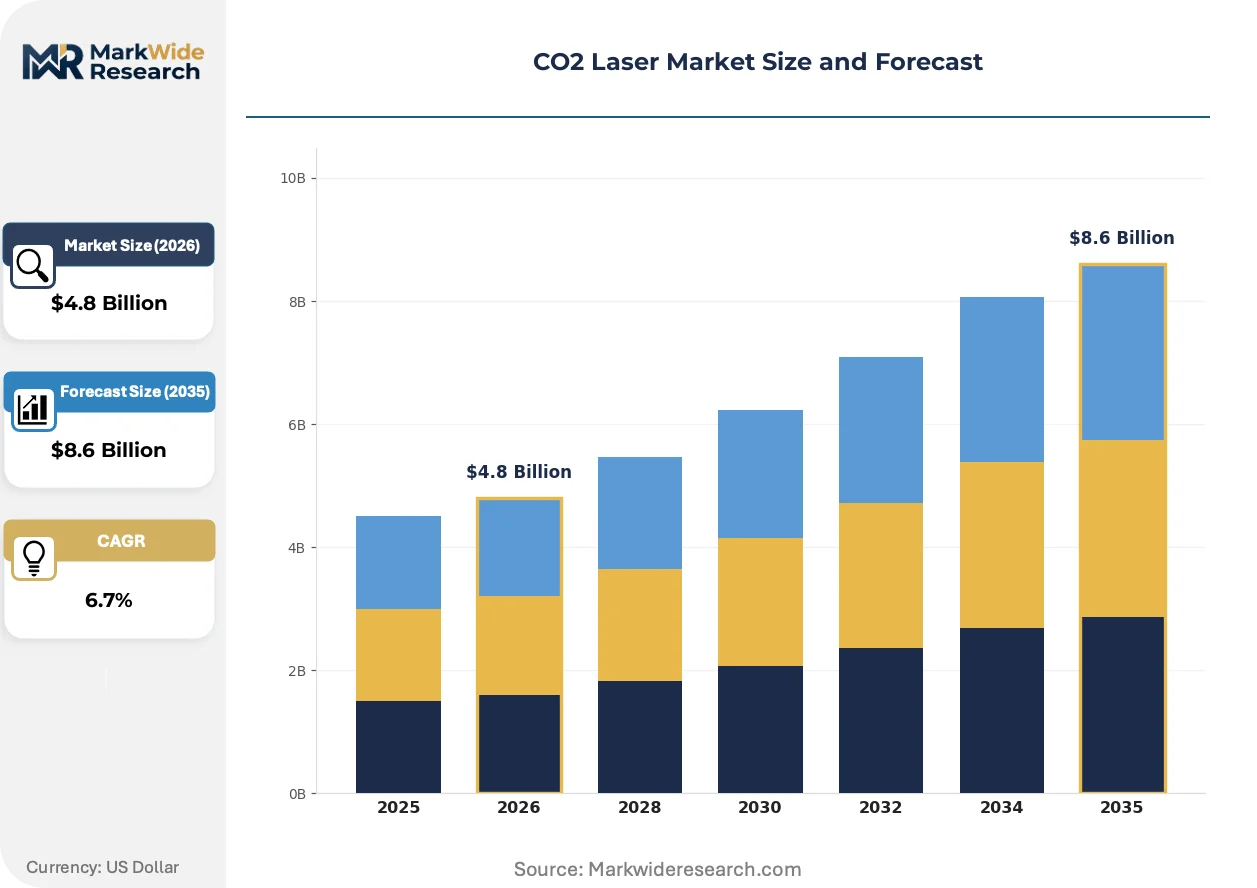
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Engravers, Laser Cutters, Laser Marking Machines, Laser Welding Equipment End User: Manufacturing, Healthcare, Textile, Automotive Technology: Continuous Wave, Pulsed, Hybrid, Femtosecond Application: Material Processing, Medical Surgery, Industrial Cutting, Scientific Research |
| Companies Covered | Amada Miyachi Co. Ltd., Trumpf, Coherent Inc., Blue Elephant CNC, Epilog Laser Inc., Rofin-Sinar Technologies Inc., IPG Photonics Corporation, Boss Laser, Kern Laser Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2 Laser Market Emerging Trajectories
Real-time process monitoring, regulatory documentation automation, and service-model unbundling are compressing equipment procurement cycles while elevating software and optics to primary vendor differentiation.
Ultrafast-pulse CO2 sources with nanosecond-scale peak power modulation are rendering obsolete traditional continuous-wave systems for heat-affected-zone-sensitive medical applications. Stuttgart surgical device manufacturers now specify pulsed platforms for stent and catheter cutting. This technology is rendering obsolete the thermal-damage trade-offs that previously constrained CO2 penetration in micro-machining segments.
REACH substance restrictions and F-Gas Regulation phase-down schedules in Europe are forcing resonator gas mixture reformulation away from helium-heavy compositions. Industrial laser OEMs are accelerating closed-loop gas recycling system development to maintain beam stability under constrained supply. Germany's precision manufacturing base faces the steepest compliance timeline, with 2027 certification deadlines already triggering pre-buy activity.
Hospital procurement departments now unbundle equipment purchase from maintenance contracts and consumable supply, treating laser systems as capital assets with separately negotiated service-level agreements. This purchasing pattern shift elevates vendor software competency and remote diagnostics capability above raw wattage specifications in competitive evaluations. The transformation is most advanced in United States ambulatory surgical centers, where group purchasing organizations consolidate negotiating leverage across multi-facility networks.
CO2 Laser Market Segmentation
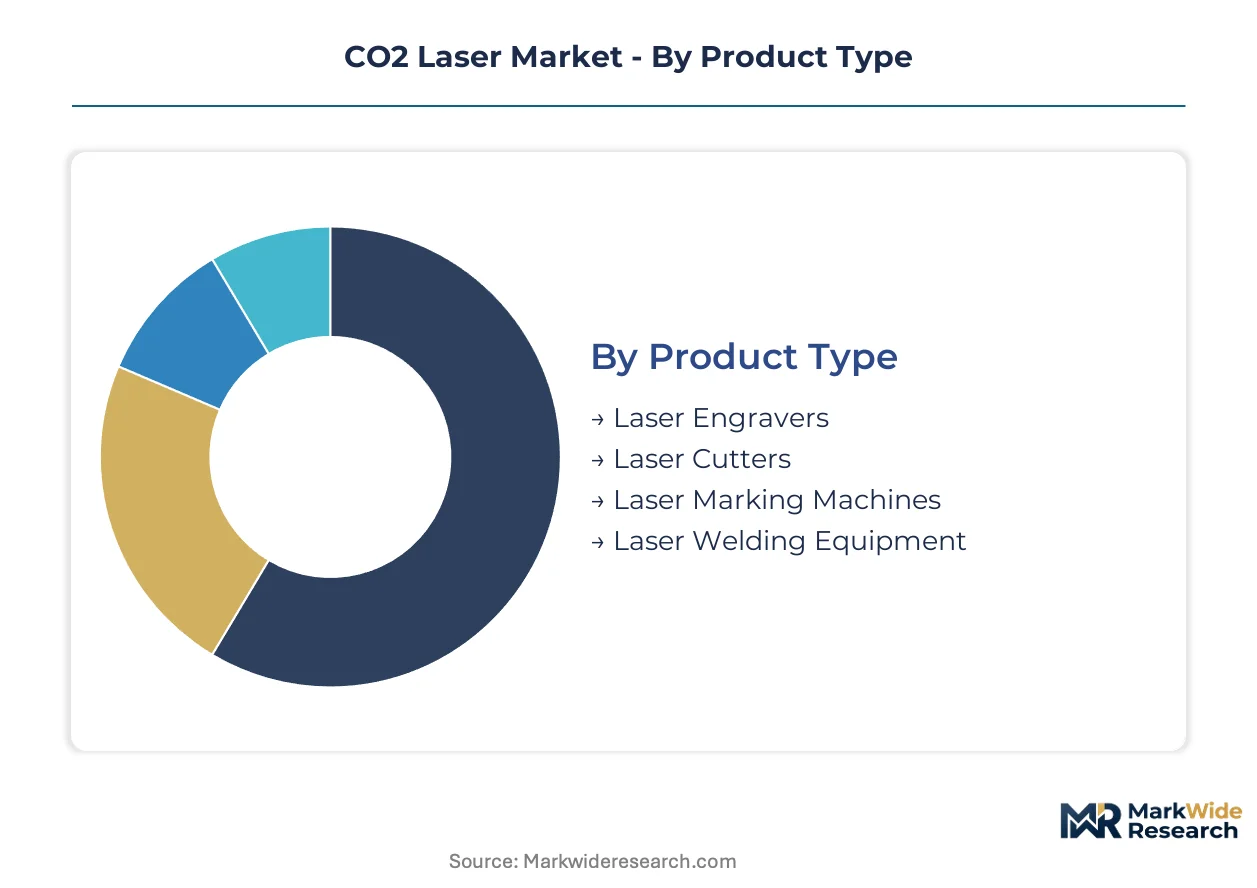
CO2 laser procurement patterns diverge sharply across industrial, medical, and scientific end-uses, with wavelength specificity and beam modulation characteristics determining system selection. Equipment vendors configure resonator architectures, gas mixtures, and delivery optics to match distinct thermal budgets and precision tolerances demanded by each segment cluster.
Product Type:
Use-case spectrum spans subtractive material removal, surface marking, and fusion joining, with each application imposing distinct optical power density and beam quality requirements on hardware design.
- Laser Cutters:These systems generate continuous-wave output at kilowatt-scale power levels to vaporize metal, ceramic, and polymer substrates along programmed vector paths. German automotive stamping plants and Stuttgart precision manufacturing clusters drive replacement demand as fiber-laser competition forces efficiency upgrades in high-wattage installations.
- Laser Welding Equipment:Beam-delivery robotics integrated with seam-tracking software characterizes next-generation configurations for aluminum and high-strength steel joint formation. Electric vehicle platform lightweighting specifications in Germany and France are accelerating capital allocation toward fully automated welding cells.
- Laser Engravers:Lower-power continuous-wave or pulsed sources ablate surface material for permanent marking and decorative texturing. Jewelry manufacturers and small-batch job shops in Italy favor these systems for non-metallic substrate processing.
- Laser Marking Machines:Galvanometer-steered beam systems apply barcodes, serial numbers, and traceability identifiers at production-line speeds. Medical device manufacturers seeking FDA 21 CFR 1040.10 compliance and EU MDR documentation capabilities specify these platforms for surgical instrument tracking.
Established volume favors Laser Cutters; emerging adoption favors Laser Welding Equipment.
End User:
Customer type concentration reflects divergent capital expenditure cycles, with industrial manufacturers prioritizing throughput metrics against healthcare procurement departments emphasizing regulatory documentation and service unbundling.
- Manufacturing:Sheet-metal fabricators, precision component suppliers, and industrial OEMs deploy high-wattage systems for volume production of automotive, aerospace, and machinery parts. German industrial corridors maintain the densest installed base of continuous-wave cutting systems.
- Healthcare:Hospitals, ambulatory surgical centers, and medical device manufacturers utilize pulsed configurations for tissue ablation, stent cutting, and ophthalmic procedures. EU MDR framework compliance and ISO 13485 certification requirements shape procurement specifications across France, Italy, and Germany.
- Automotive:Tier-1 suppliers and OEM assembly plants specify laser welding equipment for battery enclosure sealing and body-in-white joining. Joint-quality specifications for aluminum-intensive electric vehicle architectures are expanding equipment demand faster than traditional cutting applications.
- Textile:Apparel and technical fabric producers employ low-power engravers for surface patterning and synthetic material cutting. Italian fashion manufacturing clusters represent the primary demand concentration within this segment.
Procurement scale concentrates in Manufacturing; regulatory complexity peaks in Healthcare.
Technology:
Beam modulation architecture determines heat-affected zone dimensions, process speed, and capital cost, with continuous-wave dominance in industrial throughput applications yielding to pulsed precision in medical micro-machining.
- Continuous Wave:Uninterrupted resonator output maintains stable power delivery for high-speed cutting and deep-penetration welding of thick-section materials. This technology commands the largest installed base among industrial manufacturers, though helium supply volatility in Qatar and Russia squeezes operating margins.
- Pulsed:Nanosecond-to-microsecond peak power modulation enables precise energy deposition with minimal thermal diffusion. Stuttgart surgical device manufacturers now specify these platforms for stent and catheter cutting where heat-affected zone control determines clinical outcomes.
- Hybrid:Dual-mode architectures switch between continuous and pulsed operation to accommodate mixed-material processing workflows. Job shops serving diverse industrial clients favor these systems for operational flexibility.
- Femtosecond:Ultrafast pulse durations achieve cold ablation with negligible thermal damage for ophthalmic surgery and micro-electronics applications. Research laboratories and specialized medical centers in Japan and South Korea represent early adoption concentration.
Industrial throughput anchors Continuous Wave; precision medical applications are climbing the fastest.
Application:
Functional outcome requirements range from bulk material removal to sub-micron surgical precision, with regulatory classification and facility compliance costs varying substantially across the application matrix.
- Material Processing:Encompasses cutting, engraving, marking, and surface treatment of metals, polymers, ceramics, and composites. German precision manufacturing clusters and Italian industrial districts sustain the highest equipment utilization rates.
- Industrial Cutting:Dedicated high-power systems sever thick-section steel and aluminum plate for heavy machinery and structural fabrication. OSHA enclosure interlock mandates and protective eyewear protocols add facility retrofit costs for legacy system operators in the United States.
- Medical Surgery:Tissue ablation, incision, and coagulation applications in dermatology, gynecology, and otolaryngology require FDA 21 CFR 1040.10 compliance in the United States and EU MDR documentation in Europe. Hospital surgical suite upgrades across Germany, France, and Italy are accelerating system replacement cycles.
- Scientific Research:Spectroscopy, laser-induced breakdown spectroscopy, and fundamental physics experiments utilize specialized resonator configurations. National laboratories and university research centers in Germany and France maintain specialized procurement channels.
Equipment density peaks in Material Processing; regulatory upgrade intensity concentrates in Medical Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for CO2 laser systems favor manufacturing economies with dense precision engineering clusters. Germany and Japan maintain substantial trade surpluses in high-wattage industrial equipment. The United States and China balance significant domestic production against specialized component imports.
Germany
Stuttgart and Munich industrial corridors drive replacement demand for high-wattage continuous-wave systems. EU MDR documentation mandates accelerate hospital surgical suite upgrades across Bavaria and Baden-Württemberg. The F-Gas Regulation phase-down timeline triggers pre-buy activity for closed-loop gas recycling systems ahead of 2027 certification deadlines.
United States
Ambulatory surgical centers consolidate negotiating leverage through group purchasing organizations across multi-facility networks. FDA 21 CFR 1040.10 laser performance standards govern medical device market access. OSHA enclosure interlock mandates add facility retrofit costs for legacy system operators in Midwest industrial states.
Japan
Pulsed CO2 configurations for stent cutting and ophthalmic applications remain underpenetrated despite aging demographics. METI industrial policy supports precision manufacturing technology adoption. Nagoya and Osaka medical device clusters specify ultrafast-pulse platforms where heat-affected zone control determines clinical outcomes.
China
Domestic resonator manufacturing expands to reduce import dependency for industrial cutting systems. MIIT equipment upgrade programs target sheet-metal fabrication capacity expansion. Yangtze River Delta manufacturing bases absorb fiber-laser competition pressure through efficiency-focused CO2 system modernization.
South Korea
Femtosecond CO2 research applications concentrate at national laboratories and specialized medical centers. MFDS medical device regulations align with international standards for surgical laser approval. Seoul Capital Area electronics manufacturers drive demand for micro-machining beam delivery systems.
CO2 Laser Market Vendor Landscape
On the supply side, the industry is consolidating around resonator technology specialists and beam-delivery system integrators. German and Japanese engineering heritage dominates premium industrial equipment, while North American vendors capture medical and marking segments. Three strategic archetypes define competitive positioning: in-house resonator manufacturers controlling core component supply, optics specialists backward integrating into beam delivery, and automation integrators fusing robotics with machine vision. Dominant competitive moves include captive supply chain construction for helium-heavy gas mixtures and strategic partnerships between source OEMs and articulated-arm robotics suppliers.
Among German-based engineering conglomerates, Trumpf anchors the premium industrial tier through captive resonator production. Coherent Inc. occupies a position bridging industrial and medical applications with optics-centric positioning. IPG Photonics Corporation exemplifies fiber-laser crossover specialists informing CO2 efficiency improvements. These three represent distinct supply-side strategies: vertical manufacturing control, optical subsystem depth, and adjacent technology translation.
| Leading Market Players |
|---|
| Amada Miyachi Co. Ltd. |
| Trumpf |
| Coherent Inc. |
| Blue Elephant CNC |
| Epilog Laser Inc. |
| Rofin-Sinar Technologies Inc. |
| IPG Photonics Corporation |
| Boss Laser |
| Kern Laser Systems |
| Others |
Supply Flow & Price Mechanics
Stuttgart precision manufacturing clusters anchor CO2 laser resonator production capacity, and their helium-heavy gas mixture reformulation timelines directly shape downstream pricing power for continuous-wave system vendors facing EU F-Gas Regulation deadlines.
Pricing Analysis
Current-generation continuous-wave CO2 systems command substantial premiums over prior-generation pulsed platforms, while next-generation femtosecond architectures remain priced at research-lab accessibility tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified surgical configurations from industrial cutting systems and entry-level engraving platforms. Cost compression in standard-tier industrial equipment is intensifying because fiber-laser substitution at 1.06 micrometers erodes CO2's thin-gauge steel dominance. Sheet-metal job shops exhibit the highest price sensitivity, whereas hospital procurement departments prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for beam-delivery optics and articulated-arm robotics integration. Resonator manufacturing concentrates in Germany, Japan, and the United States, with mirror coatings and gas handling subsystems drawing from specialized Austrian and Swiss suppliers. Helium feedstock rests on Qatar and Russian extraction concentration, creating single-source vulnerability for continuous-wave gas mixtures. Distribution runs through Trumpf and Coherent captive service networks for high-wattage industrial systems, while medical device OEMs procure through ISO 13485-certified channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CO2 laser incumbents face a substitution defense against solid-state fiber sources, requiring strategic repositioning toward precision applications where wavelength specificity and heat-affected zone control sustain differentiation.
For Market Incumbents: Harden resonator gas recycling capabilities ahead of EU F-Gas Regulation certification deadlines, securing captive supply of helium-lean gas mixtures. Deepen backward integration into beam-delivery robotics through partnerships with Stuttgart automation specialists, countering fiber-laser speed advantages with seam-tracking software integration. Prioritize ISO 13485 certification maintenance to defend medical segment margins against emerging optics competitors.
For New Entrants and Emerging Players: Build out pulsed CO2 configurations for Japan and South Korea stent-cutting applications, where aging demographics and underpenetrated ophthalmic segments offer white-space expansion. Target medical micro-machining procurement channels through METI-supported precision manufacturing technology adoption programs. Differentiate via ultrafast-pulse platforms that render continuous-wave thermal damage trade-offs obsolete.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors beam-delivery system integrators with machine-vision software stacks over standalone source manufacturers. Long-term viability across the projection horizon hinges on automated cell deployment rates in German automotive lightweighting. Acquisition target archetype: articulated-arm robotics suppliers with existing OEM relationships. Signal to watch: pre-buy activity for closed-loop gas recycling systems as 2027 compliance deadlines approach.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Manufacturing | Trumpf's captive gas discharge cavity production insulates against helium supply volatility from Qatar and Russia. |
| ISO 13485 Certification Investment | Quality management accreditation unlocks European hospital procurement networks governed by EU MDR documentation mandates. |
| Beam-Delivery Robotics Partnership | Integration with Stuttgart automation specialists creates premium positioning against standalone CO2 source commoditization. |
| Closed-Loop Gas Recycling Development | REACH substance restrictions and F-Gas Regulation phase-down schedules force reformulation of helium-heavy resonator mixtures. |
| Ultrafast-Pulse Platform Launch | Nanosecond-scale peak power modulation captures stent-cutting margins where heat-affected zone control determines clinical outcomes. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with resonator manufacturing engineers, hospital biomedical equipment managers, automotive Tier 1 procurement leads, and precision manufacturing plant directors; and secondary validation against SEC 10-K filings, EU MDR submission databases, German trade association equipment statistics, and customs import records. Bottom-up triangulation across equipment unit economics and top-down reconciliation against end-use industry capital expenditure patterns ensured cross-verification.
Forecast inputs incorporated resonator technology substitution curves, helium supply concentration risk weighting, and regulatory compliance deadline clustering across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, beam modulation architecture, and application function. CAGRs were derived from equipment replacement cycle analysis and hospital surgical suite upgrade intensity. Industry-specific forecast inputs encompass EU F-Gas Regulation phase-down schedules and OSHA enclosure retrofit compliance cost assumptions.
Stress conditions across helium price volatility bands, fiber-laser speed parity thresholds, and EU MDR documentation enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding resonator efficiency improvement trajectories and automotive lightweighting joint-quality specification evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Fusion Splicer Market