
 300 Mm Front Opening Unified Pods (Foups) Market | 2026-2036
300 Mm Front Opening Unified Pods (Foups) Market Size, Share, and Industry Trends Forecast 2026-2036
300 Mm Front Opening Unified Pods (Foups) Market Insights
Advanced node semiconductor fabrication is repositioning demand toward FOUPs engineered for extreme cleanliness and longer wafer residence times. Entegris leverages its materials science portfolio to anchor supply relationships with leading logic foundries. Gudeng Precision Industrial Co., LTD dominates Taiwan's captive FOUP demand through proximity to the island's concentrated fab cluster. 3S KOREA competes on cost-optimized standard designs while extending its footprint among memory manufacturers in South Korea.
300 mm Front Opening Unified Pods are precision-molded polymer containers, typically constructed from polycarbonate or PBT blends, designed to transport and store silicon wafers in controlled mini-environments with particle counts below Class 1 standards. Their primary purpose is to protect wafers from contamination during automated material handling systems in semiconductor fabrication facilities. FOUPs with Sensors command attention as fabs pursue real-time environmental monitoring inside pods, while Standard FOUPs remain the volume backbone across mature node production. Wafer Foundries represent the dominant end user segment, with IC Manufacturers driving specification escalation for sub-7 nm processes.
ISO 14644 cleanroom standards, REACH chemical restrictions on polymer additives, and FDA-adjacent semiconductor equipment quality protocols collectively elevate barrier-to-entry for new FOUP suppliers. Taiwan's Industrial Development Bureau and South Korea's Ministry of Trade, Industry and Energy channel domestic content incentives that favor local pod manufacturers. Stakeholders must monitor how EU chip sovereignty programs and US CHIPS Act domestic sourcing requirements reshape regional supply qualifications and testing regimes.
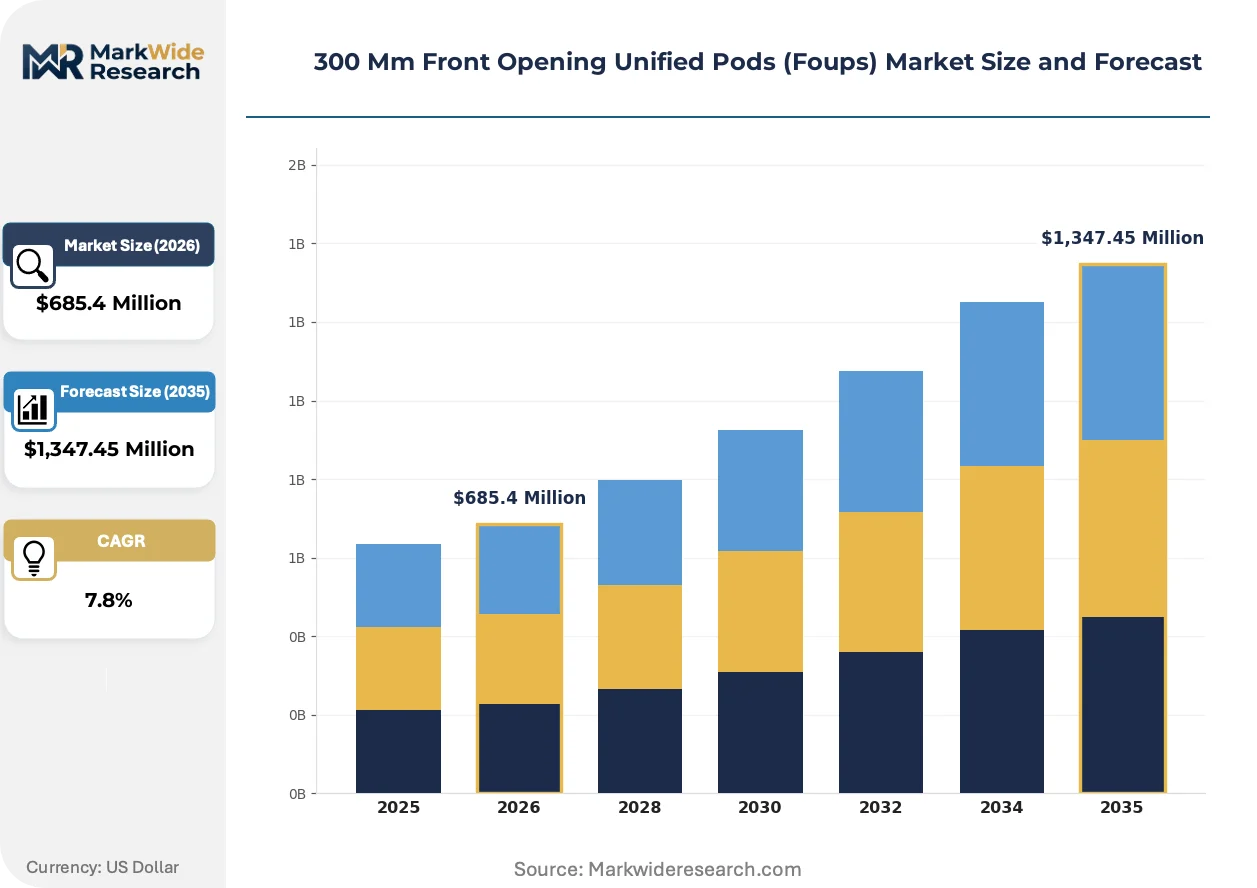
Market Dynamics
Advanced logic node migration below 7 nm is compressing wafer residence times inside FOUPs while simultaneously demanding stricter particle control, forcing pod architectures toward active environmental sensing and predictive contamination management.
Growth Catalysts
- Sub-7 nm process ramp:Leading wafer foundries in Taiwan and South Korea now require FOUPs rated for 72+ hour wafer storage without Class 1 particle degradation, pulling specification upgrades across supplier bases.
- EU chip sovereignty programs:European subsidies under the EU Chips Act are qualifying new local FOUP suppliers for fab construction in Germany and France, expanding addressable manufacturing capacity.
- Integrated sensor modules:Real-time humidity and particle monitoring inside pods is becoming standard for advanced logic production, creating attach-rate expansion for sensor-enabled variants.
Market Restraints
- Polycarbonate feedstock volatility:Bisphenol A supply disruptions and energy cost spikes in Asian petrochemical corridors transmit directly to FOUP bill-of-materials pressure.
- Taiwan supply concentration:Over 60% of high-specification FOUP fabrication capacity sits within earthquake-exposed zones on the island, creating single-point-of-failure exposure for logic foundry supply chains.
- REACH additive restrictions:ECHA scrutiny of flame retardants and plasticizers in polymer formulations is forcing reformulation cycles that extend qualification timelines by 12-18 months.
Strategic Opportunities
- India semiconductor manufacturing:Tata Electronics and ISMC Digital fabs under construction in Gujarat and Karnataka will require qualified local FOUP supply chains, opening greenfield vendor relationships.
- Memory sector sensor adoption:NAND and DRAM manufacturers in South Korea are piloting FOUPs with embedded RFID tracking for automated material handling integration.
- US CHIPS Act domestic content:Sourcing requirements for federally subsidized fabs in Arizona and Texas are creating preference windows for North American-molded pod suppliers.
Industry Challenges
- Cleanroom polymer engineering talent:The intersection of high-purity materials science and semiconductor contamination control requires specialists that fabs and suppliers compete to retain.
- ISO 14644-1 recertification cycles:Pod manufacturers must maintain Class 1 cleanroom production environments through annual third-party audits that disrupt output scheduling.
- Legacy AMHS compatibility:New FOUP form factors with sensor protrusions often require retooling of existing automated material handling tracks at mature fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 300 Mm Front Opening Unified Pods (Foups) Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard FOUPs, FOUPs with Sensors, High Capacity FOUPs, Customized FOUPs Application: Semiconductor Fabrication, Flat Panel Display, MEMS Manufacturing, Photovoltaic Cell Production End User: Wafer Foundries, IC Manufacturers, Equipment Suppliers, Research Laboratories Deployment: Cleanroom, Automation Line, Manual Handling, Robotic Integration |
| Companies Covered | Gudeng Precision Industrial Co., LTD, 3S KOREA, Chung King Enterprise Co., Ltd., Entegris, Miraial Co.,Ltd., Pozzetta, Shin-Etsu Polymer Co., Ltd., Dainichi Shoji K.K., Brooks Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
300 Mm Front Opening Unified Pods (Foups) Market Trends and Innovations
Active environmental management inside FOUPs is displacing passive contamination control, while regulatory chemistry restrictions and buyer consolidation are compressing supplier margins and accelerating qualification timelines.
Embedded sensor arrays measuring temperature, humidity, and particle counts in real-time are unifying environmental monitoring with wafer transport logistics. Taiwan's leading logic foundries now mandate sensor-equipped pods for all sub-5 nm production lots. This convergence is compressing the addressable market for standard FOUP variants while elevating technical barriers for sensor integration.
REACH authorization requirements for polycarbonate additives are forcing reformulation of base polymers used in FOUP construction. European fabs in Dresden and Leuven now require full material disclosure documentation upstream to supplier tiers. High-specification logic production lines are responding by pre-qualifying additive-free PBT blends ahead of regulatory deadlines.
Consolidated procurement by multi-fab operators is compressing supplier bases and unbundling aftermarket service contracts. Samsung and TSMC now negotiate enterprise-level FOUP agreements covering multiple sites rather than fab-specific purchases. This concentration is most visible in Taiwan and South Korea, where captive supplier relationships dominate volume allocation.
300 Mm Front Opening Unified Pods (Foups) Market Segmentation
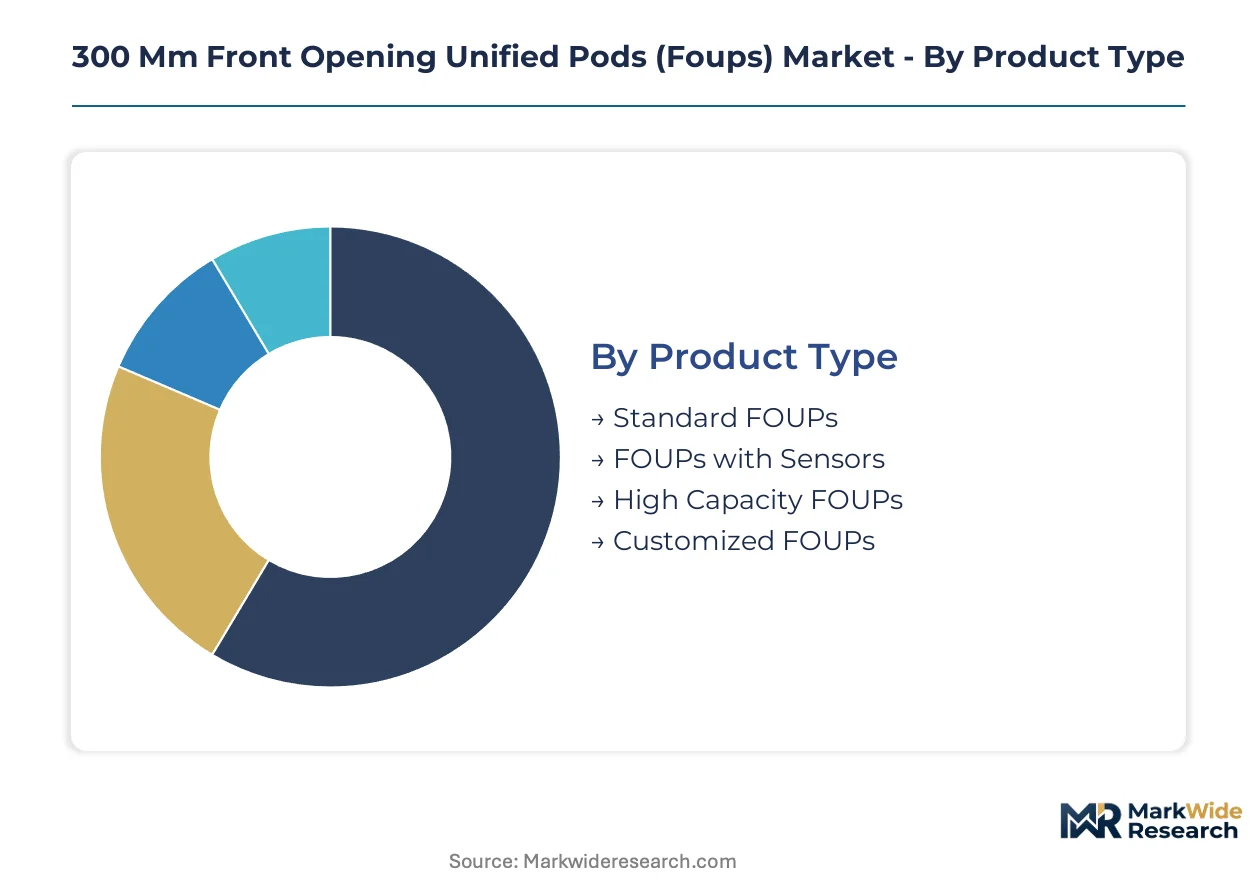
FOUP segmentation reveals how wafer protection requirements diverge across process nodes and automation levels. Specification tiers separate mature-node volume procurement from advanced logic sensor integration. Each category maps distinct technical barriers to supplier qualification pathways.
Product Type:
Customization intensity varies sharply across this category, from commodity-standard designs to fab-specific engineered variants with embedded electronics.
- Standard FOUPs:Polycarbonate or PBT blend construction without active monitoring components. Mature-node wafer foundries in Taiwan and South Korea procure these in highest volumes for processes above 14 nm where passive contamination control suffices.
- FOUPs with Sensors:Integrated humidity, temperature, and particle detection modules transmit real-time environmental data to fab AMHS networks. Taiwan's sub-7 nm logic foundries now mandate these for all production lots, pulling specification escalation across supplier bases.
- High Capacity FOUPs:Extended wafer slot configurations for specialty memory and power semiconductor batches.
- Customized FOUPs:Fab-specific dimensional modifications for non-standard automated material handling tracks.
Most installed capacity flows through Standard FOUPs. Expansion is steepest in FOUPs with Sensors.
Application:
Process contamination sensitivity determines specification grade, with semiconductor fabrication commanding the tightest particle thresholds.
- Semiconductor Fabrication:Class 1 cleanroom compliance with sub-0.1 micron particle control for silicon wafer transport and storage. Leading logic foundries in Taiwan and South Korea drive qualification timelines for advanced node compatibility.
- Flat Panel Display:Larger-format substrate handling with relaxed particle specifications versus semiconductor tiers. Korean display manufacturers in Gumi and Paju concentrate procurement for Gen 8.5+ fab expansions.
- MEMS Manufacturing:Mechanical device wafer protection with specialized vibration damping requirements.
- Photovoltaic Cell Production:Cost-optimized polymer selection for silicon solar wafer logistics.
Volume concentration sits with Semiconductor Fabrication. Specification complexity is climbing fastest in Flat Panel Display.
End User:
Procurement scale and technical integration depth separate captive fab operators from third-party equipment and research demand.
- Wafer Foundries:Enterprise-level multi-site agreements covering TSMC, Samsung, and GlobalFoundries facilities. These operators negotiate sensor-enabled specifications and consolidated aftermarket service contracts across Taiwan, South Korea, and Arizona fabs.
- IC Manufacturers:IDM captive production with fab-specific customization for memory and analog process flows. Intel, Micron, and SK Hynix drive qualification of high-capacity variants for 300 mm wafer batches.
- Equipment Suppliers:AMHS integrators requiring FOUP compatibility certification for track and loadport installations.
- Research Laboratories:Low-volume procurement with extended qualification tolerance for experimental polymer formulations.
Procurement volume aggregates through Wafer Foundries. Technical specification escalation is most pronounced among IC Manufacturers.
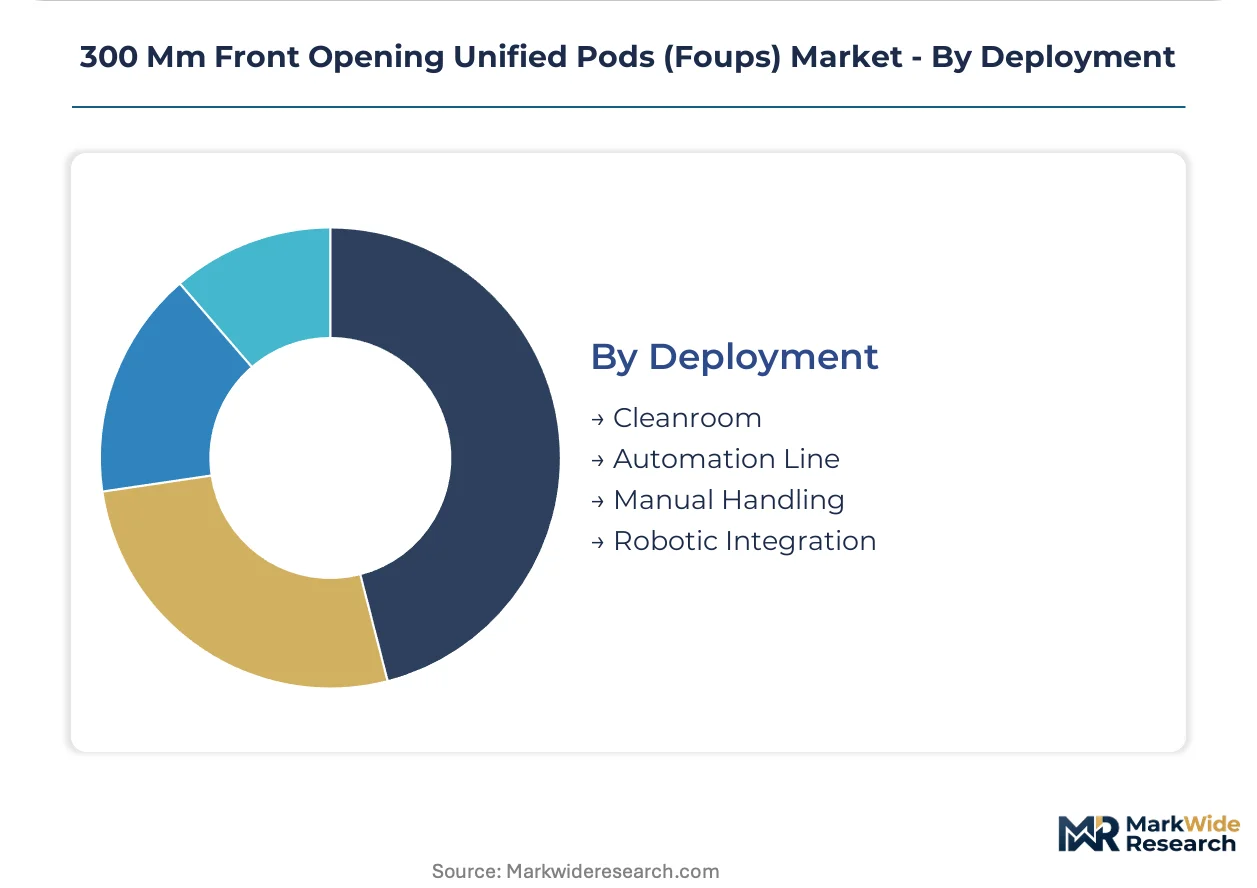
Deployment:
Automation integration level dictates dimensional tolerance and sensor interface requirements.
- Cleanroom:Static storage applications with minimal AMHS interface demands. Mature fabs in Japan and Europe maintain significant installed base of manually accessed FOUP racks.
- Automation Line:Full AMHS integration with RFID tracking and robotic loadport compatibility. Taiwan's newest logic fabs achieve near-total automation line deployment.
- Manual Handling:Operator-mediated transport for maintenance, engineering, and non-production wafer movement.
- Robotic Integration:Direct robot arm manipulation with force-feedback compatibility and precision alignment features.
Deployment share concentrates in Automation Line configurations. Growth trajectory is strongest in Robotic Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling FOUP production toward jurisdictions with REACH-aligned chemical frameworks but lower energy-input costs, while Taiwan's seismic exposure accelerates geographic diversification of high-specification molding capacity.
Taiwan
TSMC and United Microelectronics Corporation drive concentrated demand for sensor-integrated FOUPs across Hsinchu Science Park and Tainan facilities. The Industrial Development Bureau channels subsidies toward local content requirements that favor Gudeng Precision and domestic suppliers. Kaohsiung's emerging fab cluster is absorbing new FOUP qualification lines as earthquake-risk mitigation reshapes procurement geography.
South Korea
Samsung Electronics and SK Hynix memory operations in Giheung and Pyeongtaek mandate embedded RFID tracking for automated material handling integration. The Ministry of Trade, Industry and Energy administers domestic content incentives under K-Chips legislation. 3S KOREA anchors supply relationships across the Seoul Capital Area's concentrated fab corridor.
United States
Intel's Arizona and Ohio expansions plus TSMC's Phoenix fab are triggering CHIPS Act domestic sourcing requirements for FOUP qualification. The EPA oversees Bisphenol A emissions standards affecting polycarbonate feedstock selection. Greater Phoenix and Columbus metro areas are emerging as qualification hubs for North American-molded pod supply.
Japan
Shin-Etsu Polymer and Miraial serve captive demand from Tokyo Electron and SCREEN Holdings equipment integration requirements. METI's semiconductor revitalization strategy subsidizes advanced materials localization. Kyoto-Osaka corridor facilities maintain ISO 14644-1 Class 1 certification for high-purity polymer molding.
Germany
Bosch and Infineon IDM operations in Dresden and Regensburg are qualifying additive-free PBT blends ahead of ECHA flame-retardant authorization deadlines. The EU Chips Act is channeling subsidies toward FOUP supplier onboarding for new fab construction. Saxony's Silicon Saxony cluster is expanding environmental disclosure documentation requirements upstream to polymer tiers.
300 Mm Front Opening Unified Pods (Foups) Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers position molding lines near subsidized fab construction sites. The vendor base concentrates around three tiers: integrated materials-science conglomerates with captive polymer supply, regional specialists leveraging proximity to concentrated fab clusters, and cost-optimized fabricators serving memory-sector volume procurement. Strategic archetypes include sensor-integration specialists, REACH-compliant reformulators, and AMHS-certification aggregators. Geographic expansion and portfolio diversification toward sensor-enabled variants represent the dominant competitive vectors.
Among Taiwan-based precision molders, Gudeng Precision Industrial Co., LTD exemplifies the captive-supplier archetype through proximity to Hsinchu-Tainan fab concentration. Entegris occupies a position representing integrated materials-science capabilities spanning polymer formulation through contamination-control systems. 3S KOREA sits within the cost-optimized tier, anchoring supply relationships among South Korean memory manufacturers through standardized design platforms.
| Leading Market Players |
|---|
| Gudeng Precision Industrial Co., LTD |
| 3S KOREA |
| Chung King Enterprise Co., Ltd. |
| Entegris |
| Miraial Co.,Ltd. |
| Pozzetta |
| Shin-Etsu Polymer Co., Ltd. |
| Dainichi Shoji K.K. |
| Brooks Automation |
| Others |
Pricing and Supply Chain Analysis
Sensor-enabled premium variants and commodity-standard designs diverge sharply in both cost structures and procurement pathways. Taiwan's sub-7 nm logic foundries negotiate enterprise-level contracts for FOUPs with integrated environmental monitoring, while mature-node memory manufacturers in South Korea source cost-optimized polycarbonate pods through volume-driven spot arrangements.
Pricing Analysis
Direct-to-OEM channels handle hyperscale buyer demand from TSMC and Samsung, compressing distributor margins to single-digit percentages. Three-tier pricing structure across sensor-integrated, standard-certified, and economy-grade levels separates qualification-intensive logic foundry supply from memory-sector volume procurement. Price differentiation rests on ISO 14644-1 certification tier and REACH-compliant polymer formulation depth. Pricing pressure stems from polycarbonate feedstock volatility linked to Bisphenol A supply disruptions in Asian petrochemical corridors. Memory manufacturers exhibit highest price sensitivity, while advanced logic foundries prioritize contamination control over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through Taiwan, South Korea, and Japan-based molding facilities. Raw material dependencies center on polycarbonate and PBT blend feedstocks from petrochemical suppliers, plus sensor module electronics from semiconductor component distributors. Single-source vulnerability concentrates in Taiwan's Hsinchu-Tainan corridor, where earthquake exposure threatens over half of high-specification FOUP fabrication capacity. Distribution runs through captive supplier relationships for leading foundries, supplemented by third-party logistics for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node semiconductor fabrication represents a late-cycle quality story as wafer foundries mandate sensor-equipped pods for all sub-5 nm production lots, elevating technical barriers and compressing addressable supply bases.
For Market Incumbents: Anticipate REACH authorization deadlines for flame retardants by pre-qualifying additive-free PBT blends ahead of ECHA regulatory enforcement. Secure backward integration into polycarbonate compounding to buffer feedstock volatility from Bisphenol A supply disruptions. Expand molding capacity in Kaohsiung and Phoenix to mitigate Taiwan seismic concentration risk while capturing CHIPS Act domestic sourcing preferences. For New Entrants and Emerging Players: Capture greenfield qualification opportunities at Tata Electronics and ISMC Digital fabs under construction in Gujarat and Karnataka, where local FOUP supply chains remain unestablished. Target India's emerging semiconductor manufacturing cluster through partnerships with AMHS integrators seeking pod compatibility certification. Lead with cost-optimized standard designs for memory-sector procurement before advancing to sensor-integrated variants. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor integration capabilities and REACH-compliant polymer formulation expertise concentrate in limited supplier tiers. Long-term viability favors integrated materials-science conglomerates with captive cleanroom molding capacity and multi-site enterprise relationships. Watch for ECHA additive authorization decisions as inflection indicators for reformulation investment cycles and qualification timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Integration | Real-time environmental monitoring inside pods is becoming mandatory for Taiwan's sub-7 nm logic foundries. |
| REACH-Compliant Polymer Reformulation | Additive-free PBT blends secure qualification pathways ahead of ECHA flame-retardant authorization deadlines. |
| Geographic Capacity Diversification | Kaohsiung and Phoenix molding lines mitigate Taiwan seismic exposure while accessing CHIPS Act subsidies. |
| Enterprise-Level Procurement Consolidation | Multi-site agreements with TSMC and Samsung compress supplier bases and unbundle aftermarket service contracts. |
| AMHS Certification Aggregation | Compatibility validation with Tokyo Electron and Brooks Automation equipment expands addressable fab integration opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab procurement directors, polymer R&D leads, AMHS integration engineers, and cleanroom certification auditors with secondary validation from SEC filings, customs trade records, ECHA substance authorization databases, and ISO 14644-1 audit registries. Bottom-up demand modeling from individual fab expansion projects triangulated against top-down supply capacity assessments across Taiwan, South Korea, and North American molding facilities.
Segment-weighting approaches distributed value projections across product type tiers, application contamination sensitivity levels, end-user procurement scales, and deployment automation intensities. CAGRs were derived from fitted growth curves applied to wafer start forecasts and fab equipment capital expenditure trajectories. Industry-specific inputs included REACH regulatory timeline assumptions and CHIPS Act domestic sourcing implementation schedules.
Polycarbonate feedstock price volatility, Taiwan seismic event probability, and ECHA additive authorization delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding sensor attach-rate progression and regional fab construction timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market