
 PCB Punching Machine Market | 2026-2036
PCB Punching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
PCB Punching Machine Market Insights
East Asian machine-tool producers is broadening the supply base for precision PCB punching systems. LPKF Laser & Electronics AG leverages laser-based depaneling expertise to anchor premium positioning in medical and aerospace niches. ASYS Automatisierungssysteme GmbH sustains its European manufacturing footprint while competing aggressively in Asian electronics assembly lines. Mitsubishi Electric dominates servo-driven mechanical punching platforms across Japanese automotive supplier networks.
A PCB punching machine mechanically or thermally separates individual printed circuit boards from production panels using dies, lasers, or controlled force application, with positioning tolerances typically below 50 microns to preserve trace integrity. Automated punching machines lead unit shipments as electronics manufacturers replace manual equipment to reduce substrate damage and improve cycle consistency. CNC punching machines represent the fastest-expanding product category among high-mix, low-volume contract fabricators seeking programmable tooling paths. Laser punching technology commands the strongest margin pool where flexible substrates and ceramic-based boards prohibit mechanical contact.
Japan's METI enforces energy-efficiency benchmarks for industrial machinery that shape motor and drive-system specifications in new equipment designs. The EU's RoHS and REACH frameworks restrict cadmium and lead content in machine components, compelling redesigns of hydraulic fluid seals and electrical contacts. China's GB standards for electronic manufacturing equipment safety govern structural guarding and emergency-stop protocols for domestic and imported units. Stakeholders must monitor evolving dual carbon goals across East Asian manufacturing jurisdictions to anticipate retrofit obligations and electrification timelines for pneumatic-to-electric actuator transitions.
Market Dynamics
Automotive electronics densification is compressing board separation tolerances below 25 microns, forcing fabricators to retire mechanical punching systems before full depreciation cycles conclude. This premature replacement wave concentrates capital deployment in servo-electric and laser-based platforms.
Growth Catalysts
- China's MIIT Equipment Standards:Domestic certification mandates for electronic manufacturing machinery are accelerating replacement of imported legacy systems in Guangdong and Jiangsu production corridors.
- Automotive PCB Stack Density:Advanced driver-assistance systems require multi-layer boards with tighter component spacing, expanding demand for CNC punching with programmable tooling paths.
- EU RoHS Component Bans:Restrictions on lead and cadmium in electrical contacts and hydraulic seals are redirecting R&D investment toward all-electric actuator architectures.
Market Restraints
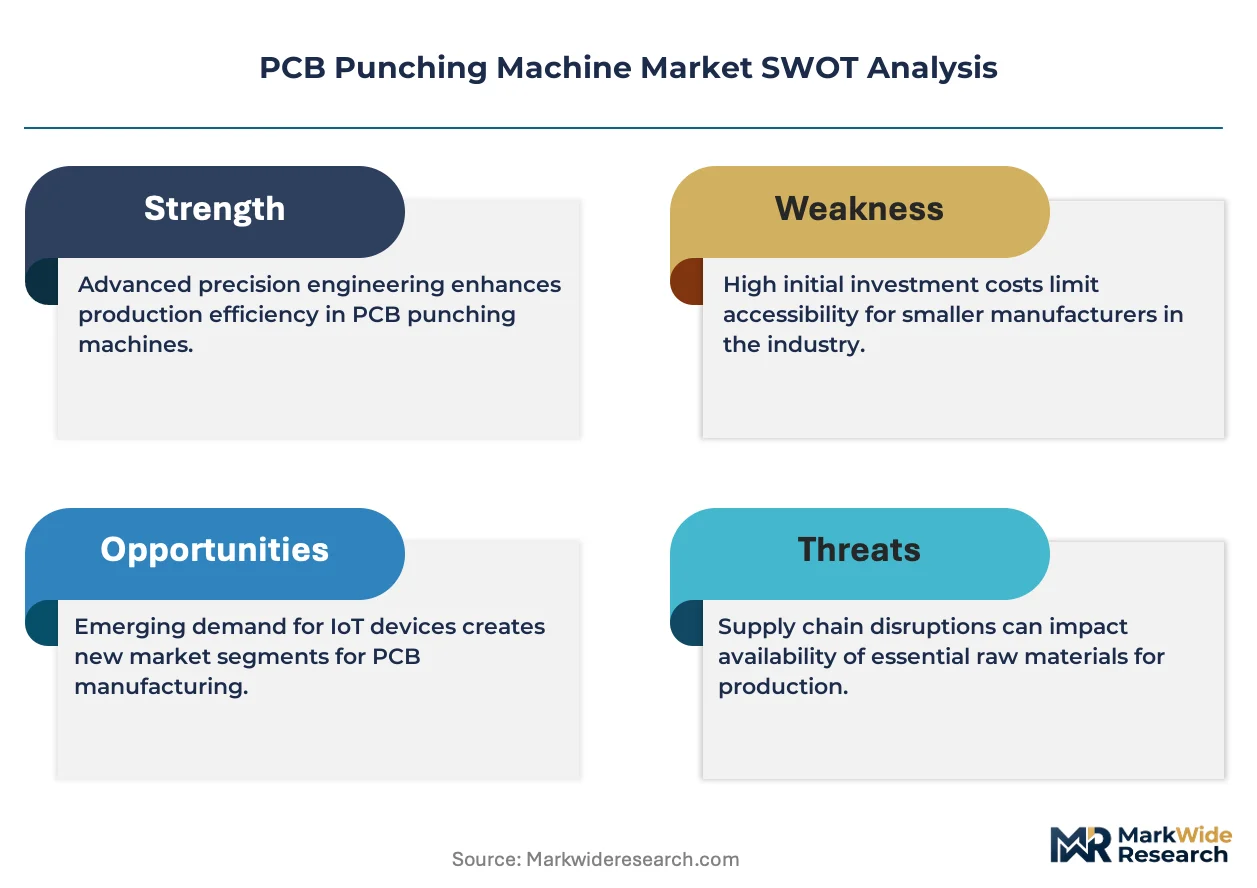
- Neodymium Magnet Supply Concentration:Servo motor production depends on rare earth processing concentrated in Chinese refining facilities, exposing equipment makers to input volatility.
- Technical Limitation on Ceramic Substrates:Mechanical punching generates micro-fractures in aluminum nitride boards above 1.6mm thickness, restricting addressable substrate range.
- Japan's METI Energy Benchmarks:Compliance with industrial machinery efficiency standards adds 12-18 months to product development cycles for Japanese manufacturers.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for semiconductor and component manufacturing are attracting punching equipment vendors to establish technical service presence in Gujarat and Tamil Nadu.
- Laser-Ultrasonic Convergence:Hybrid systems combining laser scoring with ultrasonic substrate stabilization are opening processing windows for polyimide flexible circuits.
- Medical Device Miniaturization:Implantable electronics requiring sub-10-micron trace preservation are creating premium niches for UV laser depaneling systems.
Industry Challenges
- Mechatronics Skill Scarcity:Servo calibration and laser optics alignment require technicians cross-trained in precision mechanics and software parameter tuning, a combination rare in contract fabrication workforces.
- ISO 14644 Cleanroom Integration:Medical and aerospace customers demand punching systems certified for Class 7 particulate environments, extending factory acceptance testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCB Punching Machine Market |
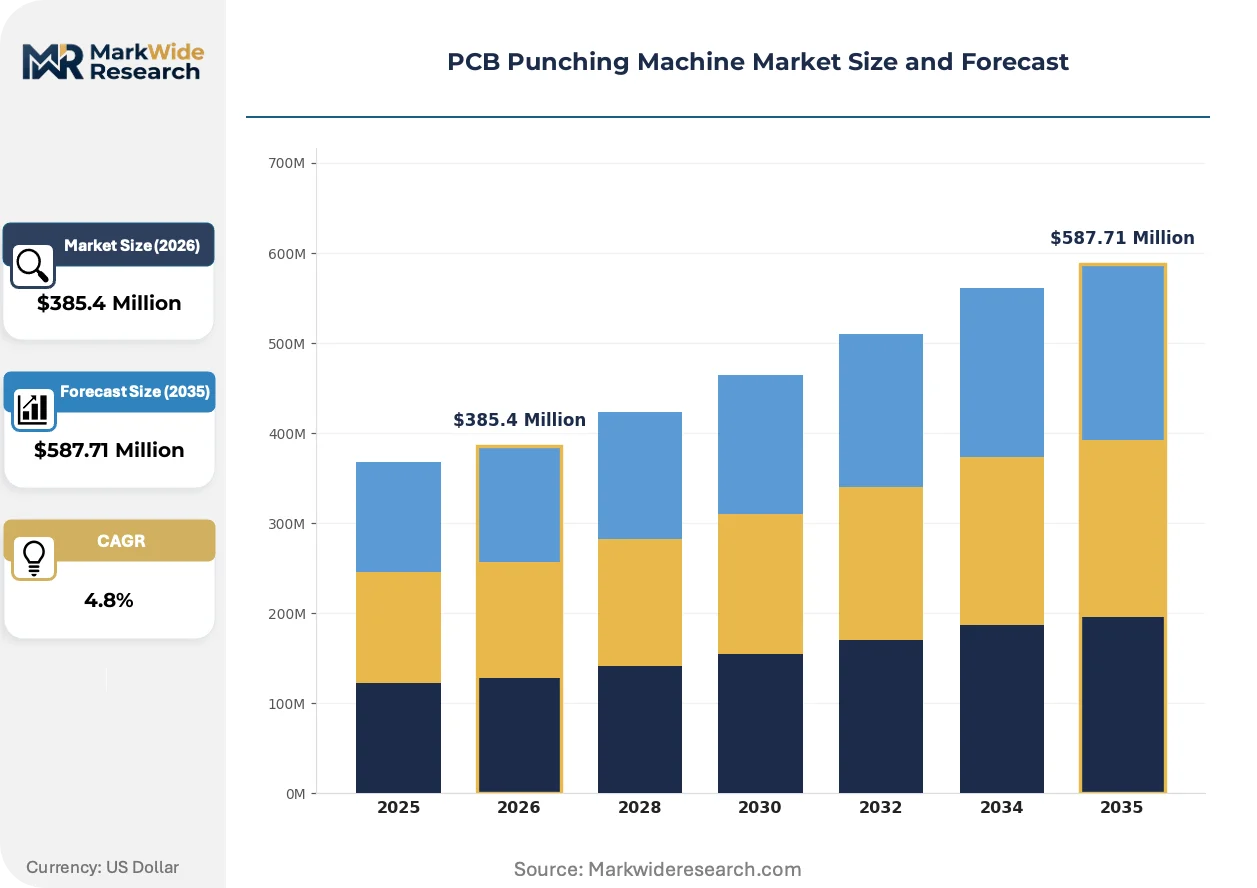
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Punching Machines, Automated Punching Machines, Semi-Automatic Punching Machines, CNC Punching Machines End User: Electronics Manufacturers, PCB Fabricators, Automotive Suppliers, Aerospace Components Material: Copper, Aluminum, Steel, Plastic Technology: Mechanical Punching, Laser Punching, Hydraulic Punching, Pneumatic Punching |
| Companies Covered | LPKF Laser & Electronics AG, ASYS Automatisierungssysteme GmbH, FKN Systek, CAB Technology, Cencorp Corporation, Schneider Electric, Mitsubishi Electric, Panasonic, Disco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCB Punching Machine Market Trends and Innovations
Laser-based depaneling architectures are fragmenting into application-specific configurations, while regulatory pressure on hazardous substances accelerates material science substitution. Equipment vendors are reconfiguring service models to capture recurring revenue from precision maintenance contracts.
UV picosecond laser systems are modularizing across medical device and aerospace supply chains. Manufacturers of implantable cardiac monitors and satellite payload electronics are specifying these platforms for ceramic and polyimide substrates where mechanical contact risks trace damage. The technology is modularizing equipment procurement decisions, allowing fabricators to add wavelength modules rather than replacing entire systems when substrate portfolios expand.
China's GB standards for electronic manufacturing equipment safety are mandating redundant emergency-stop circuits and structural guarding specifications that exceed ISO baseline requirements. Domestic inspectors are enforcing these protocols through factory audits of both local and imported equipment. Japanese and German vendors are responding by pre-certifying control cabinets to GB protocols before shipment, compressing installation timelines for customers in Shenzhen and Suzhou industrial parks.
Contract manufacturers are unbundling precision maintenance from capital equipment purchases, signing multi-year service agreements with independent technical providers rather than OEM service divisions. This disintermediation is most pronounced in Taiwan's Hsinchu Science Park, where dedicated laser optics cleaning and die refurbishment specialists have captured 40% of the installed base service volume. Vendors are countering with predictive diagnostics subscriptions to retain customer attachment.
PCB Punching Machine Market Segmentation
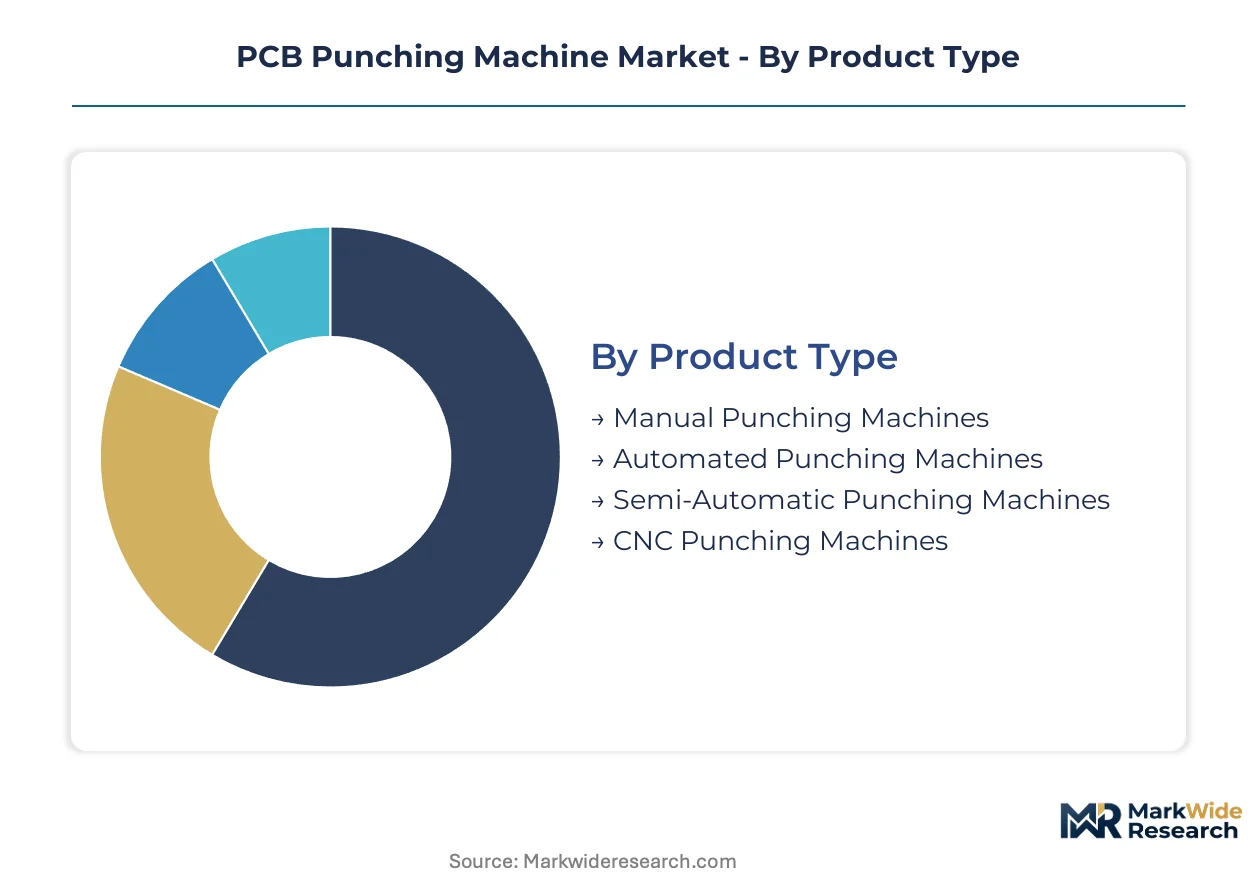
Equipment replacement cycles vary sharply across PCB punching modalities, with automation levels and substrate compatibility dictating capital deployment timing. Fabricators segment procurement decisions by volume predictability, substrate fragility, and cleanroom requirements.
Product Type:
Upgrade urgency separates equipment categories, as automotive densification forces premature retirement of mechanical systems before depreciation cycles conclude.
- Automated Punching Machines:Servo-electric actuators with programmable force curves dominate high-volume consumer electronics lines in Guangdong Province. Japanese automotive supplier networks specify these platforms for trace preservation below 25 microns in advanced driver-assistance system boards.
- CNC Punching Machines:Programmable tooling paths enable rapid changeover between board designs, attracting high-mix contract fabricators in Taiwan's Hsinchu Science Park. The category benefits from India's PLI scheme for electronics manufacturing, where technical service providers are establishing calibration capabilities.
- Manual Punching Machines:Legacy installations persist in low-volume repair operations and prototype shops with irregular batch sizes.
- Semi-Automatic Punching Machines:Transitional installations bridge manual workflows and full automation in mid-tier PCB fabricators upgrading from mechanical to servo platforms.
Automated punching machines sit at the top of the volume ranking, with CNC punching machines climbing the fastest.
End User:
Customer technical requirements stratify by trace density tolerance and cleanroom certification demands.
- Electronics Manufacturers:Consumer device assemblers in Shenzhen and Suzhou industrial parks drive standardized platform procurement with compressed installation timelines.
- PCB Fabricators:Multi-layer board specialists require sub-50-micron positioning accuracy for trace integrity preservation in smartphone and tablet substrates.
- Automotive Suppliers:Tier-1 electronics suppliers to Japanese and German OEMs specify servo-electric systems for multi-layer stack separation, with China's MIIT equipment standards accelerating replacement of imported legacy systems in domestic production corridors.
- Aerospace Components:Satellite payload manufacturers command premium UV picosecond laser configurations for ceramic and polyimide substrates where mechanical contact risks trace damage.
Electronics manufacturers capture the largest installed base, while aerospace components deliver the steepest margin expansion trajectory.
Material:
Substrate hardness and thermal sensitivity determine punching modality selection and tooling wear rates.
- Copper:Dominant conductive layer material in standard FR-4 boards, processed across all mechanical and thermal punching platforms.
- Aluminum:Lightweight substrate for LED lighting and thermal management applications, requiring modified die clearances to prevent burr formation.
- Steel:Rigid backing materials and certain RF shielding applications demand hardened tooling and elevated force specifications.
- Plastic:Polyimide flexible circuits and ceramic-filled substrates prohibit mechanical contact, routing demand toward laser punching systems with ultrasonic stabilization.
Copper substrates anchor volume deployment, with plastic substrates gaining share fastest on flexible circuit demand.
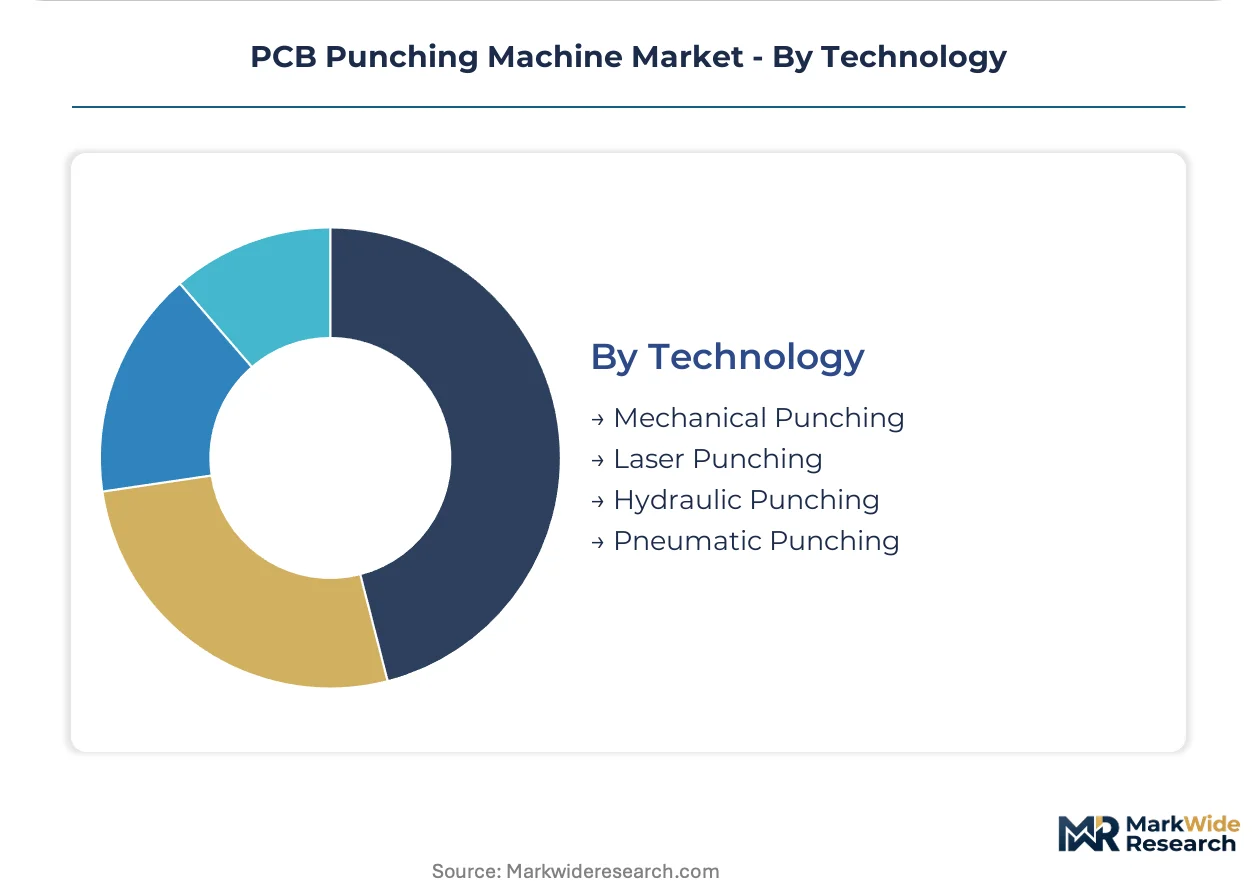
Technology:
Actuation architecture determines energy efficiency compliance, hazardous substance exposure, and substrate damage risk.
- Laser Punching:UV picosecond systems command the strongest margin pool where flexible substrates and ceramic-based boards prohibit mechanical contact. Medical device miniaturization for implantable cardiac monitors creates premium niches for trace preservation below 10 microns.
- Mechanical Punching:Conventional die-based systems face premature replacement as automotive electronics densification compresses tolerances below 25 microns, with micro-fracture limitations on aluminum nitride boards above 1.6mm thickness constraining addressable range.
- Hydraulic Punching:Legacy installations in heavy-gauge applications face EU RoHS and REACH restrictions on hydraulic fluid seals containing cadmium and lead.
- Pneumatic Punching:Compressed-air systems are transitioning to electric actuators under Japan's METI energy-efficiency benchmarks and China's dual carbon goals for manufacturing equipment.
Mechanical punching retains the largest installed base, with laser punching expanding most quickly on medical and aerospace specification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers exploit compliance-cost differentials across jurisdictions, relocating assembly and testing operations to jurisdictions with streamlined certification pathways. This arbitrage accelerates capacity buildup in East Asian manufacturing corridors while European producers absorb REACH and RoHS redesign costs.
China
Guangdong Province hosts the densest concentration of automated punching capacity, serving Shenzhen and Suzhou electronics assemblers with compressed installation timelines. MIIT equipment standards mandate redundant emergency-stop circuits and structural guarding that exceed ISO baselines, forcing pre-certification of imported control cabinets. Domestic inspectors enforce GB safety protocols through factory audits of both local and foreign equipment.
Japan
Automotive supplier networks in Nagoya and Osaka specify servo-electric systems for multi-layer stack separation below 25 microns. METI energy-efficiency benchmarks for industrial machinery add 12-18 months to product development cycles, shaping motor and drive-system specifications in new equipment designs. Kanto region fabricators dominate high-precision medical and aerospace substrate processing.
Germany
Baden-Württemberg and Bavaria anchor European precision machinery production, with Stuttgart-area specialists supplying laser-based depaneling systems. ECHA REACH restrictions on cadmium and lead in hydraulic fluid seals redirect R&D toward all-electric actuator architectures. German vendors compete aggressively in Asian electronics assembly lines while sustaining domestic manufacturing footprints.
India
Gujarat and Tamil Nadu attract punching equipment vendors establishing technical service presence under the PLI scheme for electronics manufacturing. High-mix contract fabricators in these corridors seek programmable CNC punching with rapid changeover capabilities. Technical calibration capabilities remain underdeveloped, creating openings for foreign specialists.
South Korea
Seoul Capital Area and Busan-Ulsan clusters process flexible substrates for consumer device exporters, driving demand for laser punching with ultrasonic stabilization. MFDS medical device regulations and corporate carbon neutrality commitments accelerate pneumatic-to-electric actuator transitions. Domestic equipment makers face input volatility from rare earth supply concentration.
PCB Punching Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue laser-ultrasonic hybrid configurations and predictive diagnostics subscriptions. The vendor base stratifies across three maturity levels: legacy mechanical-system specialists, servo-electric platform providers, and premium laser-depaneling architects. Competitive positioning hardens around three strategic archetypes: precision-mechanics heritage firms, electronics-automation conglomerates, and medical-aerospace niche specialists. Dominant competitive moves include geographic expansion into Indian PLI corridors and technology licensing for UV picosecond wavelength modules.
Among German precision-equipment architects, LPKF Laser & Electronics AG and ASYS Automatisierungssysteme GmbH exemplify the premium-tier positioning anchored in medical and aerospace niches. LPKF occupies a position representing laser-based depaneling expertise, while ASYS sits within the European manufacturing footprint competing across Asian assembly lines. Mitsubishi Electric exemplifies the servo-driven mechanical punching platform dominance in Japanese automotive supplier networks. These three entities represent distinct competitive archetypes: wavelength-specialized precision systems, transregional automation integrators, and servo-motor industrial conglomerates.
| Leading Market Players |
|---|
| LPKF Laser & Electronics AG |
| ASYS Automatisierungssysteme GmbH |
| FKN Systek |
| CAB Technology |
| Cencorp Corporation |
| Schneider Electric |
| Mitsubishi Electric |
| Panasonic |
| Disco Corporation |
| Others |
Pricing and Supply Chain Analysis
Automotive electronics densification below 25-micron tolerances is forcing fabricators to accept shorter depreciation cycles and premium equipment procurement, compelling supply chains to absorb higher component costs for servo-electric and laser-based platforms.
Pricing Analysis
Distributor margins on imported control cabinets compress under China's MIIT pre-certification requirements, which add compliance layers before Guangdong installation. Three-tier pricing structure across premium UV picosecond laser, standard servo-electric, and economy mechanical platforms separates aerospace medical niches from high-volume consumer lines. Cost compression in the mechanical tier is intensifying because automotive suppliers are retiring die-based systems prematurely. Contract fabricators in Taiwan's Hsinchu Science Park exhibit highest price sensitivity; Japanese automotive Tier-1 networks show lowest sensitivity due to trace-preservation mandates.
Supply Chain Analysis
Workforce scarcity for mechatronics technicians in Shenzhen, Nagoya, and Stuttgart constrains calibration and optics alignment capacity across precision equipment assembly. Rare earth processing for neodymium magnets concentrates in Chinese refining facilities, while servo motor production and laser source manufacturing anchor in Japan and Germany. Supply chain risk centers on single-source vulnerability for UV picosecond laser diodes. Distribution runs through OEM-direct channels for automotive accounts and specialized industrial distributors serving high-mix contract fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive PCB stack densification and medical device miniaturization are redirecting procurement toward premium laser and servo-electric specifications.
For Market Incumbents: Cement dominance in Japanese automotive supplier networks by pre-certifying control cabinets to China's GB safety protocols before shipment, compressing installation timelines for Shenzhen and Suzhou customers. Lock in multi-year predictive diagnostics subscriptions to counter disintermediation by independent laser optics specialists capturing service volume in Taiwan. For New Entrants and Emerging Players: Enter via technical service presence in Gujarat and Tamil Nadu under India's PLI scheme for electronics manufacturing, where calibration capabilities remain underdeveloped. Target high-mix CNC punching demand from contract fabricators seeking rapid changeover capabilities, leveraging programmable tooling paths as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with laser-ultrasonic hybrid specialists and UV wavelength module licensors serving medical-aerospace substrate niches. The five-to-ten-year viability window favors acquisition targets with captive servo motor supply or backward integration into rare earth magnet sourcing. Watch for pneumatic-to-electric actuator retrofit timelines under Japan's METI benchmarks and China's dual carbon goals as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Pre-Certification | Compresses installation timelines for imported equipment in Guangdong and Jiangsu corridors. |
| Predictive Diagnostics Subscription | Retains customer attachment against independent service specialists in Hsinchu Science Park. |
| Laser-Ultrasonic Hybrid Development | Opens processing windows for polyimide flexible circuits in Seoul Capital Area clusters. |
| Technical Service Presence in India | Captures PLI-driven demand from Gujarat and Tamil Nadu contract fabricators. |
| Backward Integration into Rare Earth Sourcing | Insulates servo motor production from Chinese refining facility volatility. |
Research Methodology
Multiple input streams — equipment procurement directors at Guangdong electronics assemblers, calibration technicians in Taiwan's Hsinchu Science Park, and aftermarket service heads at German precision machinery vendors — were reconciled against customs records for punching machine imports, MIIT equipment certification filings, and SEC disclosures from listed automation conglomerates. Primary interviews with plant engineers and OEM procurement teams across Japanese automotive supplier networks were cross-validated against bottom-up unit shipment estimates and top-down market value reconstructions.
Data-stream reconciliation across product type, end-user industry, substrate material, and actuation technology dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating automotive electronics densification curves, medical device miniaturization trajectories, and regulatory compliance cost absorption across East Asian manufacturing jurisdictions.
Inputs from equipment vendors and contract fabricators were available through the study window; gaps in real-time rare earth pricing transparency and PLI scheme implementation timelines introduce uncertainty bands around servo-electric platform cost forecasts. Material deviation in Japan's METI energy benchmark enforcement or China's dual carbon goal acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Seismic Data Acquisition Equipment Market