
 Die Bonder Equipment Market | 2026-2036
Die Bonder Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Die Bonder Equipment Market Analysis
Modular platform configurations is recalibrating how semiconductor packaging houses evaluate capital equipment procurement. Kulicke & Soffa Industries leverages its vertical integration in bonding tools to sustain pricing power across advanced packaging nodes. ASM Pacific Technology anchors its position through R&D intensity in hybrid bonding architectures. BE Semiconductor Industries differentiates via manufacturing scale that spans flip-chip and wafer-level packaging systems.
Die bonder equipment comprises precision assembly systems that place semiconductor dies onto substrates or packages with placement accuracy below five micrometers, using thermal compression, adhesive dispensing, or ultrasonic energy transfer to form electrical and mechanical interconnections. The primary commercial purpose centers on enabling advanced semiconductor packaging for higher I/O density and smaller form factors. Automated bonding machines dominate volume shipments as foundries scale heterogeneous integration capacity, while hybrid bonding machines represent the fastest-growing product category driven by 3D stacking requirements in memory and logic devices. Thermal bonding technology leads installed base share, though laser bonding is gaining traction for thermally sensitive compound semiconductors.
ISO 14644 cleanroom standards, SEMI safety guidelines, and EU REACH chemical restrictions shape equipment design requirements and market access conditions for die bonder suppliers serving European and Asian fabrication zones. China's GB standards and SAMR certification protocols add compliance layers for equipment imported into domestic packaging facilities. Stakeholders must monitor how dual-use export control expansions affect tool shipment timelines and service access across major semiconductor manufacturing clusters.
Market Dynamics
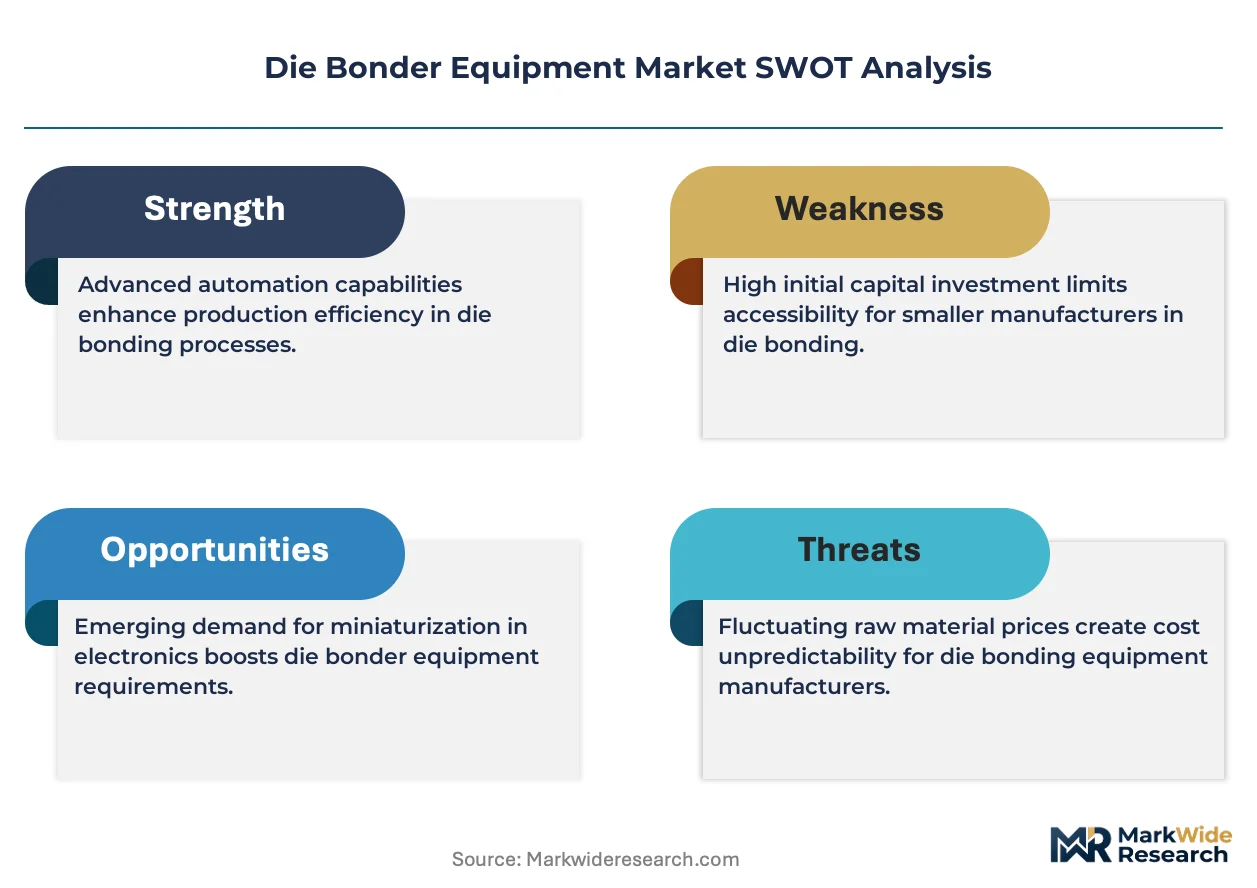
Heterogeneous integration roadmaps at leading foundries are compressing placement accuracy requirements below three micrometers, forcing packaging houses to retire thermal compression platforms faster than standard depreciation cycles permit.
Growth Catalysts
- EU Chips Act certification mandates:European fabrication facilities must upgrade to qualified advanced packaging equipment, accelerating replacement demand for legacy die bonders across Germany, France, and the Netherlands.
- Hybrid bonding architectures:Memory and logic manufacturers are scaling 3D stacking capacity, requiring precision placement systems capable of sub-micron alignment for copper-to-copper interconnects.
- Hsinchu Science Park cluster expansion:Taiwan's concentrated packaging capacity buildout is pulling disproportionate volumes of automated bonding machines for heterogeneous integration lines.
Market Restraints
- Precision motion control component scarcity:High-resolution encoders and linear motors face concentrated supply from Japanese and German specialists, creating input cost volatility and extended lead times.
- Cleanroom infrastructure requirements:ISO 14644 Class 1-3 compliance for hybrid bonding platforms demands facility investments that packaging houses in cost-sensitive geographies cannot absorb.
- Technical limitation in compound semiconductor handling:Thermally sensitive gallium nitride and silicon carbide dies restrict throughput speeds on thermal compression systems, capping productivity gains.
Strategic Opportunities
- India's semiconductor packaging incentives:PLI scheme disbursements and state-level infrastructure subsidies are attracting first-mover equipment deployments to Gujarat and Karnataka greenfield sites.
- Laser bonding technology convergence:Ultrafast laser systems combined with machine vision architectures enable non-thermal die placement for photonics and RF device packaging.
- Refurbished equipment channels:Secondary market platforms for certified pre-owned die bonders address mid-tier packaging houses excluded from new equipment procurement by capital constraints.
Industry Challenges
- Mechatronics engineering talent scarcity:Packaging equipment manufacturers compete with robotics and automotive sectors for specialists in precision motion control and thermal management system design.
- Dual-use export control compliance timelines:US Bureau of Industry and Security licensing reviews for advanced die bonders with sub-five-micron accuracy extend delivery schedules by six to twelve months.
- Legacy system integration friction:Hybrid bonding platforms must interface with existing wafer handling and inspection infrastructure, requiring custom software bridges that delay production ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Bonder Equipment Market |
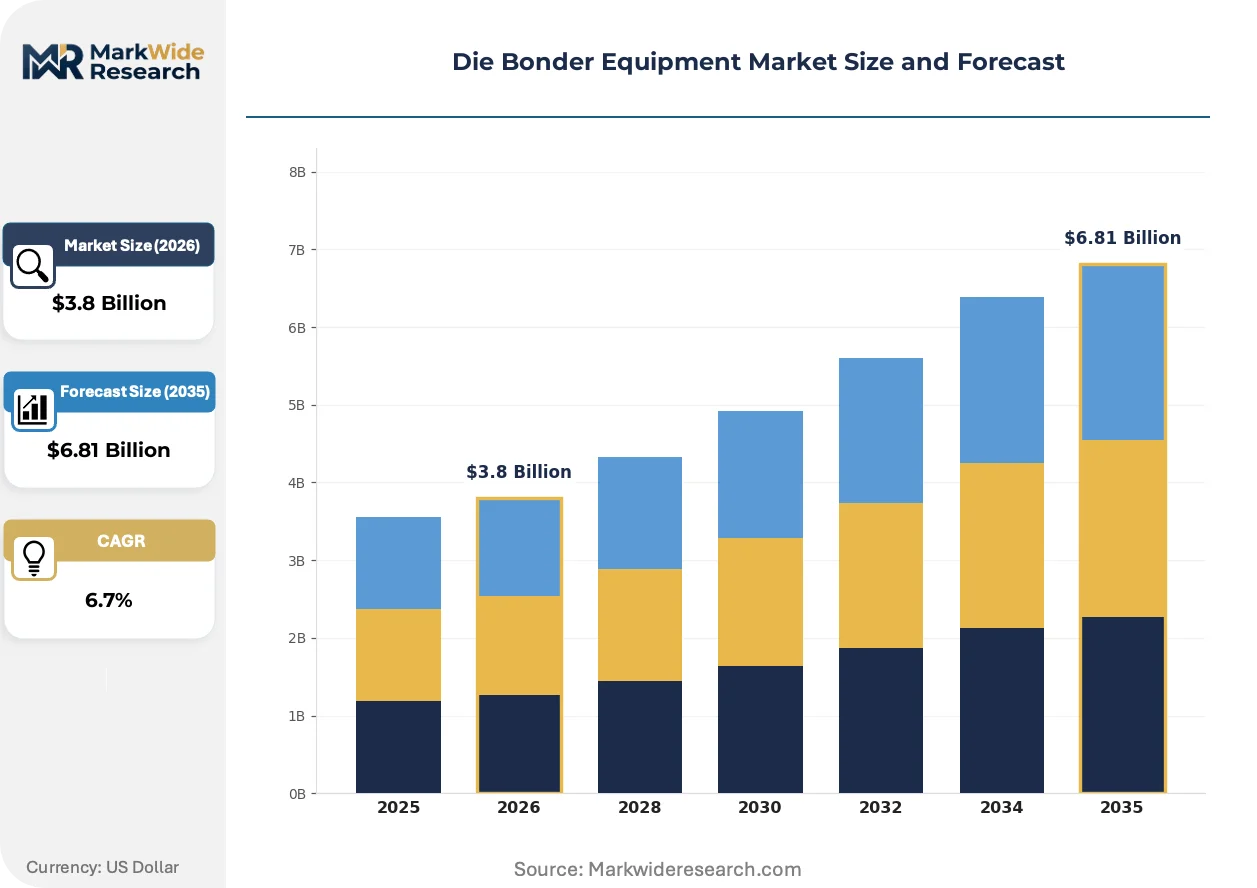
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Bonding Machines, Manual Bonding Machines, Semi-Automated Bonding Machines, Hybrid Bonding Machines Technology: Thermal Bonding, Adhesive Bonding, Ultrasonic Bonding, Laser Bonding End User: Semiconductor Manufacturers, Electronics Industries, Aerospace Providers, Automotive Suppliers Application: Microelectronics, Consumer Electronics, Industrial Applications, Medical Devices |
| Companies Covered | Palomar Technologies, Shibuya Corporation, Kulicke & Soffa Industries, West-Bond, Inc., Shinkawa Ltd., ASM Pacific Technology, TRESKY GmbH, MRSI Systems, BE Semiconductor Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Bonder Equipment Market Emerging Trajectories
Packaging equipment architectures are pivoting from discrete thermal processes to integrated precision assembly systems that combine placement, inspection, and bonding in unified vacuum environments.
Hybrid bonding technology is absorbing capital allocation from traditional thermal compression platforms as memory manufacturers scale 3D NAND and high-bandwidth memory stacks. Leading foundries in Taiwan and South Korea are deploying these systems at triple the pace of two years prior. The technology is absorbing market share from adhesive-based interconnects by enabling pitch scaling below ten micrometers without thermal stress degradation.
EU REACH chemical restrictions on lead-based solders and halogenated flame retardants are forcing equipment redesigns for compliant material handling and process chemistries. Die bonder manufacturers must validate alternative alloy systems and flux formulations that meet both placement accuracy and environmental compliance thresholds. European packaging facilities face the steepest adaptation costs, with German and Dutch fabs leading qualification timelines for REACH-compliant production lines.
Consolidated procurement consortia among OSATs are displacing individual equipment purchasing decisions, with three to five packaging houses collectively negotiating platform specifications and service terms. This buyer concentration is compressing vendor margins while accelerating standardization of machine interfaces and data formats. The shift is most visible in Taiwan's Hsinchu and Tainan corridors, where foundry-affiliated packaging subsidiaries coordinate capital expenditure cycles with parent wafer fabrication schedules.
Die Bonder Equipment Market Segmentation
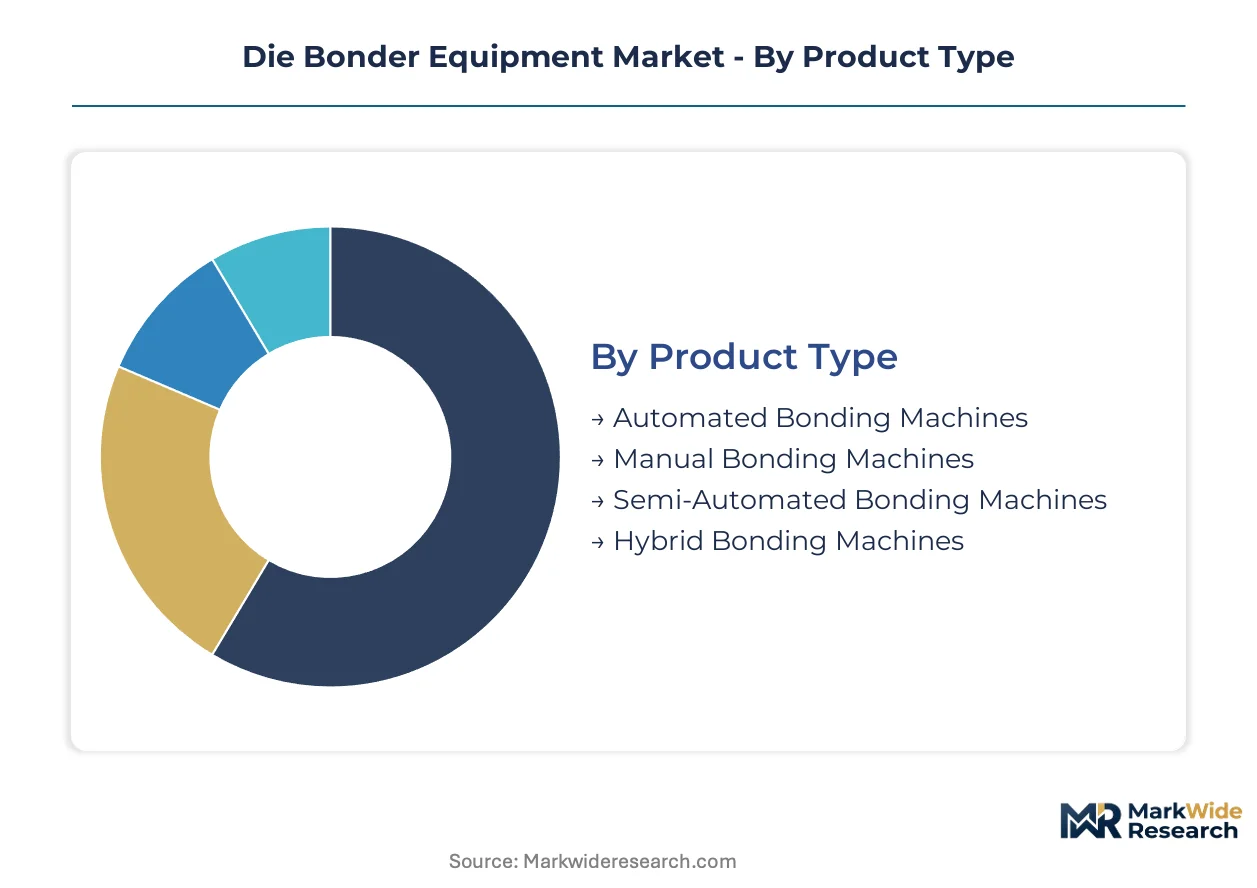
Die bonder equipment segmentation reveals how packaging houses prioritize capital allocation across automation levels, bonding physics, and end-use requirements. Equipment specifications diverge sharply between high-volume memory fabrication and precision medical device assembly.
Product Type:
Procurement decisions pivot on throughput requirements versus placement accuracy trade-offs, with foundries balancing depreciation schedules against node migration timelines.
- Automated Bonding Machines:Fully automated systems integrate die placement, inspection, and bonding sequences with throughput exceeding 10,000 units per hour. Taiwan's Hsinchu Science Park cluster absorbs the dominant share as foundries scale heterogeneous integration lines for advanced packaging nodes.
- Hybrid Bonding Machines:These systems enable copper-to-copper interconnects at sub-micron alignment precision for 3D NAND and high-bandwidth memory stacks. Memory manufacturers in South Korea and Taiwan are tripling deployment pace versus prior periods as 3D stacking architectures mature.
- Semi-Automated Bonding Machines:Mid-tier packaging houses in cost-sensitive geographies deploy these for product families with moderate I/O density requirements.
- Manual Bonding Machines:Laboratory environments and prototype lines retain limited volumes for process development and qualification work.
Volume sits with automated bonding machines; growth tilts toward hybrid bonding machines.
Technology:
Process thermal budgets dictate technology selection, with compound semiconductor sensitivity accelerating non-thermal alternatives.
- Thermal Bonding:Thermal compression platforms dominate installed base share, using controlled heat and pressure to form metallic interconnections. Legacy packaging houses in Germany and the Netherlands face accelerated replacement cycles as EU Chips Act certification mandates tighten.
- Laser Bonding:Ultrafast laser systems enable localized energy deposition without bulk substrate heating. Photonics device manufacturers and RF component suppliers are adopting these for gallium arsenide and indium phosphide die assembly.
- Adhesive Bonding:Polymer-based interconnects serve cost-optimized consumer electronics packaging where I/O density requirements remain moderate.
- Ultrasonic Bonding:Mechanical energy transfer suits wire bonding transitions and thermosonic applications in power module packaging.
Revenue concentrates in thermal bonding; technology transition favors laser bonding for thermally sensitive applications.
End User:
Capital intensity and cleanroom infrastructure requirements fragment demand across user categories with divergent scale economics.
- Semiconductor Manufacturers:Integrated device manufacturers and foundry-affiliated packaging subsidiaries drive equipment specifications through consolidated procurement consortia. These buyers negotiate platform standardization and service terms collectively, compressing vendor margins while accelerating interface harmonization.
- Automotive Suppliers:Tier-1 electronics suppliers are expanding die bonder deployments for power module and sensor packaging as electrification architectures multiply semiconductor content per vehicle.
- Electronics Industries:Contract manufacturers and subsystem integrators represent fragmented demand with high price sensitivity.
- Aerospace Providers:Defense and satellite applications require specialized qualification protocols and extended service lifecycles.
Equipment shipments concentrate with semiconductor manufacturers; automotive suppliers are expanding fastest.
Application:
Placement accuracy and throughput specifications diverge across application tiers, with medical and industrial segments demanding precision over speed.
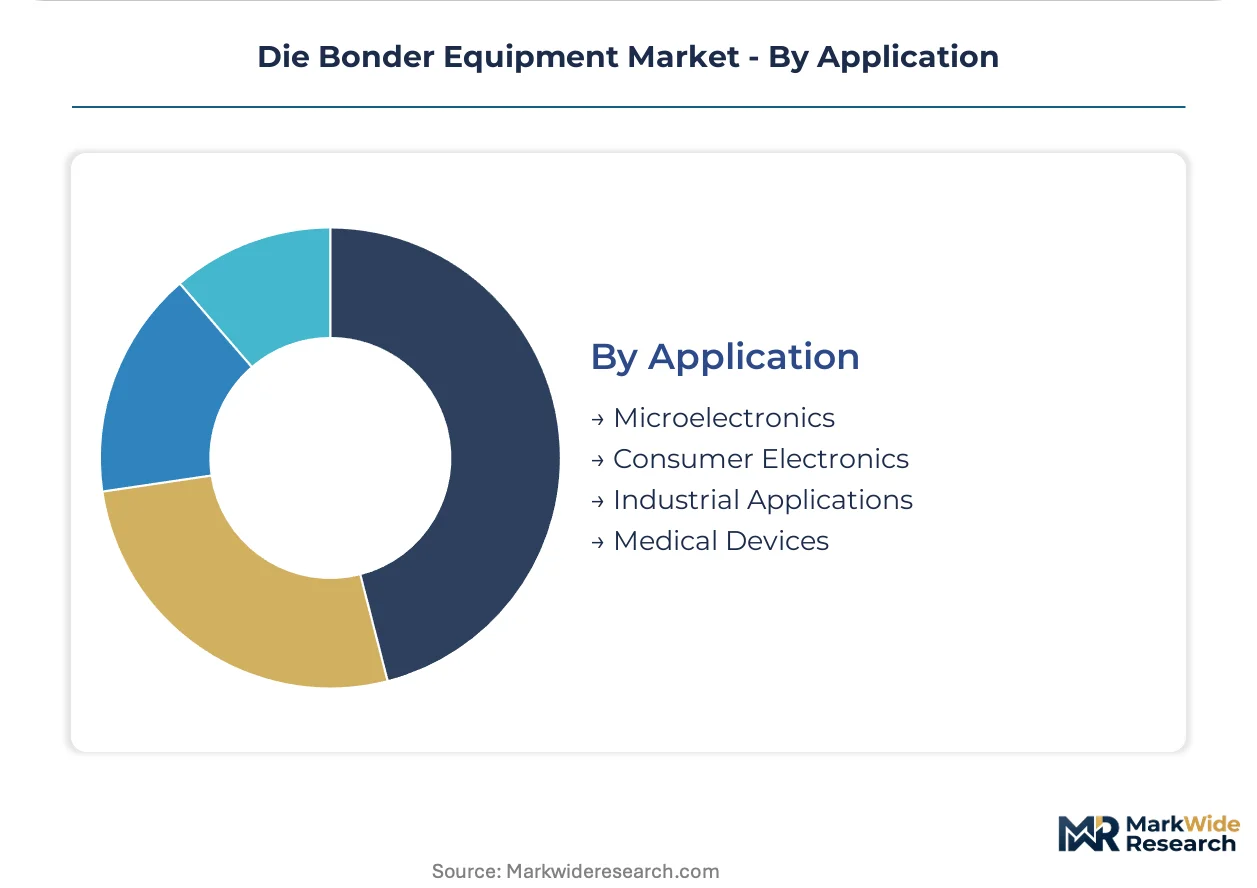
- Microelectronics:Advanced packaging for logic and memory devices requires sub-five-micrometer placement accuracy. Heterogeneous integration roadmaps at leading foundries are compressing requirements below three micrometers, forcing platform retirements ahead of standard depreciation cycles.
- Medical Devices:Implantable and diagnostic equipment packaging demands traceability, validation documentation, and process control exceeding consumer electronics standards. FDA and EMA device regulations shape equipment qualification protocols.
- Consumer Electronics:Smartphone and wearable packaging prioritizes form factor miniaturization and cost optimization.
- Industrial Applications:Power electronics and automation component assembly tolerate wider placement tolerances in exchange for reliability and thermal performance.
Microelectronics commands equipment value; medical devices are climbing fastest on precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors equipment concentration through Taiwan's advanced packaging cluster, while the EU Chips Act redirects investment flows toward German and Dutch fabrication zones. India's PLI scheme and China's domestic certification protocols are reshaping procurement geography across Asia.
Taiwan
Foundry-affiliated packaging subsidiaries drive automated bonding machine volumes through consolidated procurement consortia. Taiwan's Industrial Development Bureau coordinates capital expenditure cycles with parent wafer fabrication schedules. Hsinchu Science Park absorbs disproportionate equipment shipments as heterogeneous integration capacity scales.
South Korea
Memory manufacturers triple hybrid bonding machine deployment pace for 3D NAND and high-bandwidth memory stacks. Korea's Ministry of Trade, Industry and Energy channels subsidies toward advanced packaging R&D consortia. The Pyeongtaek and Yongin clusters concentrate copper-to-copper interconnect qualification activity.
Germany
Legacy packaging houses face accelerated thermal compression platform replacement cycles under EU Chips Act certification mandates. Germany's Federal Ministry for Economic Affairs and Climate Action administers equipment upgrade grants for REACH-compliant production lines. Dresden and Regensburg fabrication zones lead qualification timelines for environmentally compliant bonding chemistries.
China
Domestic packaging facilities navigate GB standards and SAMR certification protocols for imported equipment. China's Ministry of Industry and Information Technology enforces dual-use export control compliance timelines for sub-five-micron accuracy systems. The Yangtze River Delta and Pearl River Delta clusters scale heterogeneous integration capacity for local logic and memory device production.
United States
Integrated device manufacturers and defense contractors drive demand for specialized qualification protocols and extended service lifecycles. The US Bureau of Industry and Security extends licensing review timelines for advanced die bonders by six to twelve months. Arizona and Texas fabrication corridors attract first-mover deployments from CHIPS Act incentive recipients.
Die Bonder Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment tiers. The vendor base stratifies between precision motion control integrators and bonding process technology developers. Three archetypes dominate: diversified semiconductor equipment conglomerates with captive bonding divisions, pure-play die bonder specialists with vertical integration in precision mechanics, and regional fabricators serving cost-optimized packaging segments. Competitive moves concentrate on strategic partnerships for hybrid bonding architecture development and geographic expansion into India and Southeast Asia greenfield sites.
Within the diversified equipment tier, Kulicke & Soffa Industries and ASM Pacific Technology exemplify scale-driven positioning through backward integration into bonding tool production. Among European specialists, TRESKY GmbH and BE Semiconductor Industries occupy positions in precision assembly system development. These company structures reflect the market's bifurcation between conglomerate-backed platform standardization and specialist-driven technology differentiation.
| Leading Market Players |
|---|
| Palomar Technologies |
| Shibuya Corporation |
| Kulicke & Soffa Industries |
| West-Bond, Inc. |
| Shinkawa Ltd. |
| ASM Pacific Technology |
| TRESKY GmbH |
| MRSI Systems |
| BE Semiconductor Industries |
| Others |
Supply Flow & Price Mechanics
Mechatronics engineering talent scarcity in Germany and Japan creates labor-cost differentials that widen pricing spreads between premium hybrid bonding platforms and economy-tier thermal compression systems.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as packaging houses pay 15-25% markups to bypass six-to-twelve-month BIS licensing delays for sub-five-micron accuracy systems. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because refurbished equipment channels expand supply. Mid-tier OSATs in Southeast Asia exhibit highest price sensitivity; foundry-affiliated packaging subsidiaries in Taiwan show least.
Supply Chain Analysis
Workforce availability constraints in Japan and Germany limit precision motion control component output, forcing die bonder manufacturers to extend production schedules. Supply concentrates in Taiwan, South Korea, and Japan for high-resolution encoders, linear motors, and granite positioning stages. Raw material dependencies rest on rare-earth magnets, high-purity ceramics, and specialized alloys. Single-source vulnerability from Japanese encoder specialists creates supply chain risk. Distribution runs through direct OEM sales teams serving consolidated procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where precision motion control component scarcity props pricing power for vendors with captive component supply.
For Market Incumbents: Hedge against mechatronics talent poaching by robotics and automotive sectors through captive training academies in Hsinchu and Dresden. Lock in multi-year encoder supply agreements with Heidenhain and Renishaw before competitors exhaust allocation. Hybrid bonding architecture R&D is the priority lever to defend against Chinese equipment makers scaling sub-micron platforms. For New Entrants and Emerging Players: Digital aftermarket platforms for certified refurbished die bonders offer the lowest competitive friction entry path. Target India's Gujarat and Karnataka greenfield sites where PLI subsidies offset capital constraints and local vendor relationships remain unformed. Lead with service-heavy business models bundling installation, training, and spare parts to differentiate from established OEMs. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play hybrid bonding specialists given memory manufacturer 3D stacking capex acceleration. Five-to-ten-year viability favors vendors with backward integration into precision mechanics rather than software-only positioning. Watch BIS licensing queue length as the signal: shortening timelines indicate supply normalization and margin compression; extension indicates sustained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Architecture Development | Enables copper-to-copper interconnects below ten-micrometer pitch for 3D NAND stacking. |
| Precision Component Backward Integration | Captures encoder and linear motor supply chains against Japanese specialist allocation constraints. |
| India Greenfield Manufacturing Footprint | Positions for PLI scheme disbursements and state infrastructure subsidies in Gujarat. |
| REACH-Compliant Process Chemistry Validation | Unlocks EU Chips Act certification pathways for German and Dutch fabrication facilities. |
| Refurbished Equipment Certification Platform | Addresses mid-tier OSATs excluded from new equipment procurement by capital constraints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with packaging equipment procurement directors, precision motion control engineers, and OSAT operations executives combined with secondary validation from SEMI shipment statistics, BIS export license databases, and EU Chips Act implementation reports. Bottom-up equipment shipment tallies triangulated against top-down foundry capex disclosures.
Granularity-level modeling operated at product-type, technology, and end-user dimensions across the analysis window. CAGRs derived from weighted-average growth assumptions applied to base-year shipment volumes. Forecast inputs incorporated heterogeneous integration roadmaps at leading foundries, EU Chips Act certification timelines, and memory manufacturer 3D stacking capacity announcements.
The model holds under stable dual-use export control enforcement; deviation in BIS licensing velocity or EU REACH chemical restriction expansion would shift equipment availability and pricing trajectories. A small set of named triggers—encoder supply allocation, mechatronics graduate pipeline output, and India PLI disbursement pacing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market