
 Global Next Generation Surgical Robotics Market | 2026-2036
Global Next Generation Surgical Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Surgical Robotics Market Foresight
CE-marked platform certifications is reorganizing competitive tiers across the Global Next Generation Surgical Robotics Market. Intuitive Surgical dominates North American installed base expansion through its captive supply of instruments and accessories. Medtronic leverages its hospital channel relationships to accelerate international placement of its robotic surgery systems. Stryker Corporation anchors orthopedic robotics through its specialized MAKO platform for knee and hip procedures.
Next generation surgical robotics encompasses electromechanical systems with sub-millimeter positioning accuracy, force-feedback haptic interfaces, and real-time intraoperative imaging fusion for minimally invasive procedures. These platforms integrate multi-arm instrument manipulation with AI-driven tissue recognition to reduce surgeon fatigue and improve procedural consistency. Robotic arms and imaging systems command the largest installed base, while AI-assisted robotics and sensor fusion represent the fastest-expanding technology layers where R&D investment concentrates. Orthopedic surgeries and neurosurgeries attract premium platform configurations, whereas gynecological operations and urological treatments drive higher annual procedure volumes across academic medical centers and ambulatory surgery centers.
FDA premarket authorization requirements in the United States, CE marking under the EU MDR framework, and Japan's PMDA robotic surgery guidelines collectively determine product development roadmaps and market access timelines. Regulatory divergence between these jurisdictions forces manufacturers to maintain parallel validation studies, inflating compliance costs but also creating barriers for undercapitalized entrants. Stakeholders must monitor how autonomous suturing and tissue dissection features trigger reclassification under existing medical device frameworks.
Market Dynamics
CE-marked platform certifications is reorganizing competitive tiers across the Global Next Generation Surgical Robotics Market. FDA clearance pathways for autonomous surgical features are compressing development timelines while EU MDR compliance costs filter out undercapitalized entrants.
Growth Catalysts
- FDA 510(k) De Novo Pathway:Expedited premarket authorization for AI-assisted tissue recognition features accelerates commercialization timelines for electromechanical systems with sub-millimeter positioning accuracy.
- German Academic Medical Center Procurement:Integrated imaging-robotic platforms command priority capital allocation as hospitals expand minimally invasive procedure volumes.
- Force-Feedback Haptic Interfaces:Real-time tactile sensation transmission reduces surgeon fatigue and improves procedural consistency in multi-hour orthopedic interventions.
Market Restraints
- EU MDR Parallel Validation Burden:Regulatory divergence between FDA, PMDA, and CE marking frameworks forces manufacturers to maintain redundant clinical studies, inflating compliance expenditures.
- Specialized Servo Motor Supply:Precision electromechanical actuator production concentrates in Japanese and German component suppliers, creating input bottleneck vulnerability.
- Autonomous Suturing Reclassification Risk:Self-executing tissue manipulation features trigger potential device class elevation under existing medical device frameworks, extending approval horizons.
Strategic Opportunities
- Ambulatory Surgery Center Channel:Gynecological and urological procedure volume concentration in United States outpatient facilities creates placement opportunity for compact platform configurations.
- Japan PMDA Robotic Surgery Guidelines:Streamlined approval pathways for sensor fusion technologies enable faster market entry for AI-assisted navigation systems.
- Neurosurgery Application White Space:Premium platform configurations for cranial and spinal procedures remain underpenetrated relative to orthopedic installed base density.
Industry Challenges
- Surgeon Training Pipeline Constraints:Fellowship programs for robotic-assisted minimally invasive techniques produce insufficient certified operators to match installed base expansion rates.
- Legacy Hospital IT Integration:Real-time intraoperative imaging fusion requires interoperability with proprietary PACS and EMR architectures, complicating deployment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Surgical Robotics Market |
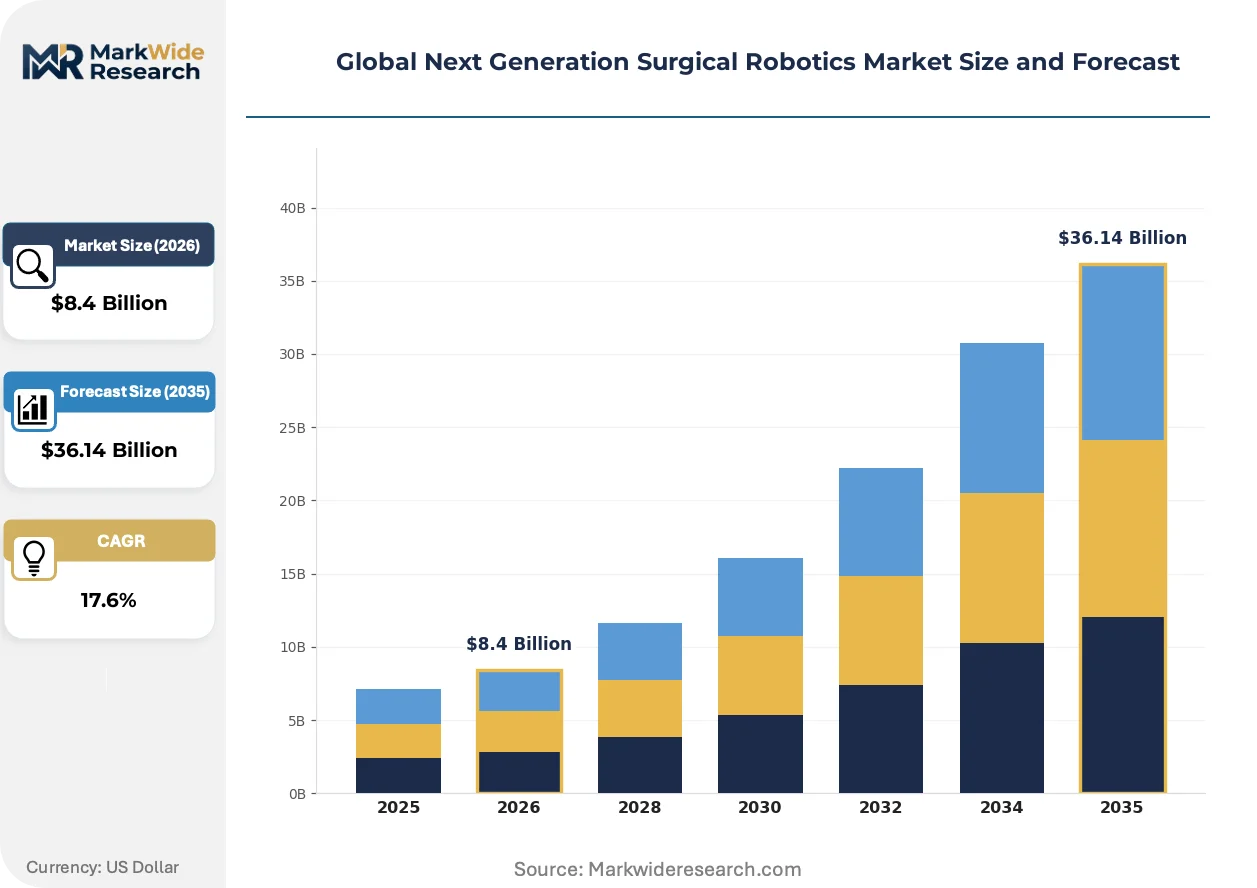
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Navigation Systems, Imaging Systems, Patient Positioners, Haptic Devices Technology: AI-Assisted Robotics, Telemanipulation, Machine Learning, Augmented Reality, Sensor Fusion Application: Orthopedic Surgeries, Neurosurgeries, Cardiothoracic Procedures, Gynecological Operations, Urological Treatments End User: Specialized Clinics, Academic Medical Centers, Ambulatory Surgery Centers, Research Institutes, Government Facilities |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker Corporation, Johnson & Johnson Services, Zimmer Biomet Holdings, Smith+Nephew, Siemens Healthineers AG, Asensus Surgical, CMR Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Surgical Robotics Market Shifts & Advancements
AI-driven tissue recognition is actively displacing conventional preoperative planning across next generation surgical robotics platforms. Three concurrent developments are compressing innovation cycles and restructuring competitive positioning.
Electromechanical systems with sub-millimeter positioning accuracy is bifurcating the installed base between premium academic medical centers and standard-tier community hospitals. Massachusetts General and Mayo Clinic anchor early adoption of multi-arm instrument manipulation with real-time haptic feedback. This capability compression is forcing mid-tier manufacturers to abandon standalone robotic arm offerings in favor of integrated imaging-robotic bundles.
EU MDR Article 10.4 clinical evidence requirements is elevating post-market surveillance obligations for electromechanical surgical platforms. Manufacturers must now maintain active implantable device-level documentation for systems previously classified as Class IIa. German notified bodies and Dutch regulators are processing certification renewals at reduced velocity, compressing European launch windows relative to FDA timelines.
Hospital procurement committees are consolidating vendor relationships around full-service platform ecosystems rather than capital equipment transactions. Academic medical centers in the United States now demand captive instrument supply contracts spanning 7-10 years as condition of system placement. This preference compression is visible most acutely in California and Texas health systems where robotic surgery program expansion coincides with value-based care contract proliferation.
Global Next Generation Surgical Robotics Market Segmentation
Segmentation in surgical robotics reveals how technology layers, clinical applications, and facility types create divergent purchasing criteria and pricing power. Manufacturers must align platform configurations with specific procedural workflows and capital allocation patterns across healthcare systems.
Product Type:
Robotic arms face substitution pressure from integrated imaging-robotic bundles as hospitals consolidate vendor relationships around full-service ecosystems.
- Robotic Arms:Multi-joint electromechanical manipulators with seven degrees of freedom enable sub-millimeter positioning accuracy in confined anatomical spaces. Massachusetts General and Mayo Clinic anchor early adoption of multi-arm configurations with real-time haptic feedback, though mid-tier manufacturers are abandoning standalone offerings.
- Imaging Systems:Intraoperative fluoroscopy, CT, and MRI fusion platforms provide real-time tissue visualization synchronized with instrument positioning. German academic medical centers prioritize these integrated configurations as they expand minimally invasive procedure volumes.
- Navigation Systems:Optical and electromagnetic tracking platforms guide instrument trajectories through preoperative planning overlays.
- Patient Positioners:Motorized tables with robotic joint articulation optimize surgical access angles.
- Haptic Devices:Force-feedback interfaces transmit tactile sensation to reduce surgeon fatigue during multi-hour interventions.
Robotic arms anchor the volume base while imaging systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium AI-integrated platforms from standard telemanipulation systems, with reimbursement codes favoring clinically validated automation layers.
- AI-Assisted Robotics:Deep learning models trained on surgical video libraries enable real-time tissue recognition and autonomous instrument positioning. FDA 510(k) De Novo pathway expedites premarket authorization for these features, compressing commercialization timelines relative to conventional submissions.
- Sensor Fusion:Multi-modal data integration from optical tracking, force sensors, and electromagnetic fields creates closed-loop control for instrument positioning. Japan PMDA streamlined approval pathways enable faster market entry for these navigation systems.
- Telemanipulation:Master-slave architectures transmit surgeon hand motions to remote instrument controllers.
- Machine Learning:Predictive algorithms optimize preoperative planning and postoperative outcome forecasting.
- Augmented Reality:Head-mounted displays overlay anatomical structures and instrument trajectories onto the surgical field.
Telemanipulation anchors the installed base while sensor fusion climbs the fastest.
Application:
Procedure volume concentration in outpatient settings creates divergent platform requirements between high-acuity interventions and high-throughput screenings.
- Gynecological Operations:Hysterectomy and myomectomy procedures drive the highest annual robotic case volumes across United States ambulatory surgery centers. Compact platform configurations with reduced footprint command priority placement in outpatient facilities where space constraints limit capital equipment density.
- Orthopedic Surgeries:Knee and hip arthroplasty platforms require specialized servo motors and force-feedback systems for bone resection accuracy. Stryker's MAKO platform anchors this segment through proprietary implant-station alignment workflows.
- Urological Treatments:Prostatectomy and nephrectomy procedures concentrate in academic medical centers with established robotic surgery fellowship programs.
- Neurosurgeries:Cranial and spinal interventions demand premium platform configurations with sub-millimeter accuracy for neural tissue avoidance.
- Cardiothoracic Procedures:Mitral valve repair and coronary bypass grafting require specialized instrument shafts and beating-heart stabilization.
Gynecological operations anchor procedure volume while neurosurgeries show the steepest expansion trajectory.
End User:
Customer type determines procurement committee composition, with academic medical centers demanding captive supply contracts and ambulatory centers prioritizing lease structures.
- Academic Medical Centers:Teaching hospitals with robotic surgery fellowship programs command premium platform configurations and captive instrument supply contracts spanning 7-10 years. California and Texas health systems consolidate vendor relationships around full-service ecosystems as value-based care contracts proliferate.
- Ambulatory Surgery Centers:Outpatient facilities concentrate gynecological and urological procedure volumes, creating placement opportunity for compact platform configurations with reduced footprint and simplified sterilization workflows.
- Specialized Clinics:Single-specialty orthopedic and ophthalmology practices deploy procedure-specific robotic platforms.
- Research Institutes:Preclinical validation centers test autonomous suturing and tissue dissection features under FDA investigational device exemptions.
- Government Facilities:Veterans Affairs hospitals and military medical centers prioritize interoperable platforms with standardized training protocols.
Academic medical centers anchor system placement volume while ambulatory surgery centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component suppliers for precision electromechanical actuators cluster in Japan and Germany, creating input dependencies that shape regional platform assembly strategies. Hospital procurement patterns diverge sharply between academic medical centers demanding integrated imaging bundles and ambulatory surgery centers prioritizing compact footprints.
United States
FDA 510(k) De Novo pathway approvals for AI-assisted tissue recognition compress commercialization timelines for electromechanical systems. Massachusetts General and Mayo Clinic anchor early adoption of multi-arm instrument manipulation with real-time haptic feedback in Boston and Rochester respectively. California and Texas health systems consolidate vendor relationships around full-service ecosystems as value-based care contracts proliferate.
Germany
Academic medical centers in Munich and Heidelberg prioritize integrated imaging-robotic platforms as they expand minimally invasive procedure volumes. EU MDR Article 10.4 clinical evidence requirements elevate post-market surveillance obligations, with German notified bodies processing certification renewals at reduced velocity. The Baden-Württemberg and Bavaria clusters concentrate precision manufacturing capabilities for surgical navigation components.
Japan
PMDA streamlined approval pathways for sensor fusion technologies enable faster market entry for AI-assisted navigation systems. Tokyo and Osaka academic hospitals drive demand for sub-millimeter positioning accuracy in multi-hour orthopedic interventions. METI industrial policy supports domestic production of specialized servo motors for robotic joint articulation.
United Kingdom
NHS procurement frameworks favor platforms with demonstrated interoperability against proprietary PACS and EMR architectures. London teaching hospitals and the Oxford-Cambridge corridor concentrate robotic surgery fellowship programs that produce certified operators. MHRA post-Brexit regulatory autonomy creates parallel validation requirements distinct from EU MDR timelines.
Switzerland
Swissmedic certification for autonomous suturing features triggers device class elevation discussions under evolving medical device frameworks. Basel and Zurich host research institutes testing tissue dissection automation under FDA investigational device exemptions. The country's precision engineering heritage supports development of force-feedback haptic interfaces for neural tissue avoidance.
Global Next Generation Surgical Robotics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Next Generation Surgical Robotics Market. Premium-tier manufacturers with captive instrument supply chains dominate academic medical center placements, while mid-tier competitors compete on compact platform configurations for ambulatory surgery centers. Three archetypes define competitive positioning: integrated ecosystem providers with full-service contracts, specialized orthopedic robotics developers with implant alignment workflows, and emerging AI-navigation specialists with sensor fusion capabilities. M&A activity concentrates on AI-assisted tissue recognition assets, while strategic partnerships between component suppliers and platform assemblers address servo motor supply bottlenecks.
Within the integrated ecosystem tier, Intuitive Surgical and Medtronic exemplify contrasting geographic anchoring strategies. Intuitive Surgical represents North American installed base expansion through instrument and accessory supply chain control. Medtronic occupies a position leveraging hospital channel relationships for international system placement acceleration. Stryker Corporation sits within the specialized orthopedic segment, with its corporate structure reflecting dedicated platform development for knee and hip procedure workflows.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson Services |
| Zimmer Biomet Holdings |
| Smith+Nephew |
| Siemens Healthineers AG |
| Asensus Surgical |
| CMR Surgical |
| Others |
Supply & Pricing Matrix
Component-scale economies in precision electromechanical actuator manufacturing concentrate production among Japanese and German suppliers, compressing margins for mid-tier platform assemblers while elevating price floors for systems requiring sub-millimeter positioning accuracy. This supply concentration forces hospital procurement committees toward captive instrument supply contracts spanning 7-10 years, locking in recurring revenue streams for integrated ecosystem providers.
Pricing Analysis
FDA 510(k) and EU MDR certification tiers dictate the pricing structure across the Global Next Generation Surgical Robotics Market. Three-tier pricing stratifies across premium AI-integrated platforms with autonomous tissue recognition, standard telemanipulation systems, and compact economy configurations for ambulatory surgery centers. Price differentiation rests on CE marking grade and after-sales service bundling. Cost compression in standard-tier systems is intensifying because mid-tier manufacturers abandon standalone robotic arm offerings. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize performance over unit cost.
Supply Chain Analysis
Specialized servo motor production concentrates in Osaka and Stuttgart manufacturing clusters, creating single-source vulnerability for multi-joint robotic arm assemblies. Component sourcing draws from Japanese precision electromechanical suppliers, German optical tracking specialists, and Taiwanese sensor fusion chipset fabricators. Raw material dependencies include rare-earth magnets for actuator torque density, high-purity aluminum alloys for robotic joint housings, and medical-grade optical glass for navigation systems. Tariff exposure on precision components from Asia-Pacific trade routes threatens margin stability. Distribution runs through hospital procurement committees and GPO contracts rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as procedure volume concentration shifts toward ambulatory surgery centers, creating niches for compact platform configurations that incumbent integrated ecosystems underserve.
For Market Incumbents: Fortify captive instrument supply chains through backward integration into specialized servo motor production, defending against emerging AI-navigation specialists with sensor fusion capabilities. Prioritize certification investment for autonomous suturing features before potential device class elevation extends approval horizons. Channel control through 7-10 year service contracts remains the critical lever for academic medical center retention. For New Entrants and Emerging Players: Lead with compact platform configurations targeting United States ambulatory surgery centers where gynecological and urological procedure volumes concentrate and space constraints limit capital equipment density. Neurosurgery applications for cranial and spinal interventions remain underpenetrated relative to orthopedic installed base density. Pursue hospital system partnership go-to-market models rather than capital equipment transactions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ecosystem providers with captive instrument supply chains and long-term service contracts. Long-term viability across the analysis window favors manufacturers with parallel FDA and EU MDR regulatory capabilities. Target acquisition archetypes include AI-assisted tissue recognition specialists and sensor fusion navigation developers. Monitor FDA premarket authorization velocity for autonomous surgical features as the inflection indicator for competitive tier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10.4 compliance elevates post-market surveillance obligations for German notified body processing. |
| Hospital System Partnership | California and Texas health systems consolidate vendor relationships around full-service ecosystems with value-based care alignment. |
| Software Companion Development | AI-driven tissue recognition modules enable real-time intraoperative imaging fusion with proprietary PACS architectures. |
| Reimbursement Strategy | CPT code validation for robotic-assisted procedures determines ambulatory surgery center capital allocation priority. |
| Sensor Fusion Acquisition | Japan PMDA streamlined pathways for navigation systems accelerate market entry for multi-modal data integration platforms. |
Research Methodology
Operator-level perspectives from robotic surgery fellowship directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this study. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare procedure data. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory approval velocity variations, component supply disruption scenarios, and reimbursement code expansion timelines. Segmentation dimensions modeled include product type configuration, technology layer integration, clinical application workflow, and end-user facility tier. CAGRs derived from procedure volume trajectory analysis and capital equipment replacement cycles. Forecast inputs incorporated AI-assisted feature adoption curves and academic medical center expansion pipelines.
The analysis sits within stated boundaries; outcomes outside parallel FDA-EU MDR regulatory convergence or sustained component supply from Japanese-German clusters would require recalibration. Forecasts reflect documented assumptions regarding procedure volume migration to outpatient settings and autonomous feature regulatory classification stability. Practitioners should keep alternative scenarios live as FDA De Novo pathway velocity and EU MDR renewal processing rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Near Vision Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Intubation Accessories Market