
 Global Bone Cement Delivery System Market | 2026-2036
Global Bone Cement Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Cement Delivery System Market Foresight
Modular unbundling of mixing and delivery components is rebalancing procurement patterns across hospital systems. Zimmer Biomet Holdings, Inc. leverages its integrated orthopedic platform to anchor premium positioning in joint arthroplasty workflows. Merit Medical Systems, Inc. specializes in minimally invasive delivery technologies that compete on procedural efficiency. Stryker Corporation dominates North American distribution through direct channel control and surgeon training infrastructure.
A bone cement delivery system comprises the mechanical or powered apparatus used to mix, transfer, and inject polymethyl methacrylate-based bone cement into skeletal defects during orthopedic and neurosurgical procedures, typically operating at controlled pressures between 20 and 60 psi to prevent cement leakage and ensure void filling. Gun-type delivery systems occupy the largest installed base due to familiarity and lower capital requirements, while power-assisted systems represent the fastest-expanding category as ambulatory surgical centers adopt electric and battery-operated technologies to reduce surgeon fatigue and improve cement viscosity control. Vacuum mixing systems command premium positioning because porosity reduction directly correlates with improved mechanical fixation outcomes.
The FDA enforces Class II medical device controls with 510(k) premarket notification requirements for cement delivery systems, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance through EUDAMED. Japan's PMDA imposes additional biocompatibility and sterilization validation standards that shape product development priorities for manufacturers seeking access. Stakeholders must monitor evolving battery-operated system standards and hydraulic technology safety guidelines as regulatory divergence between jurisdictions intensifies compliance complexity.
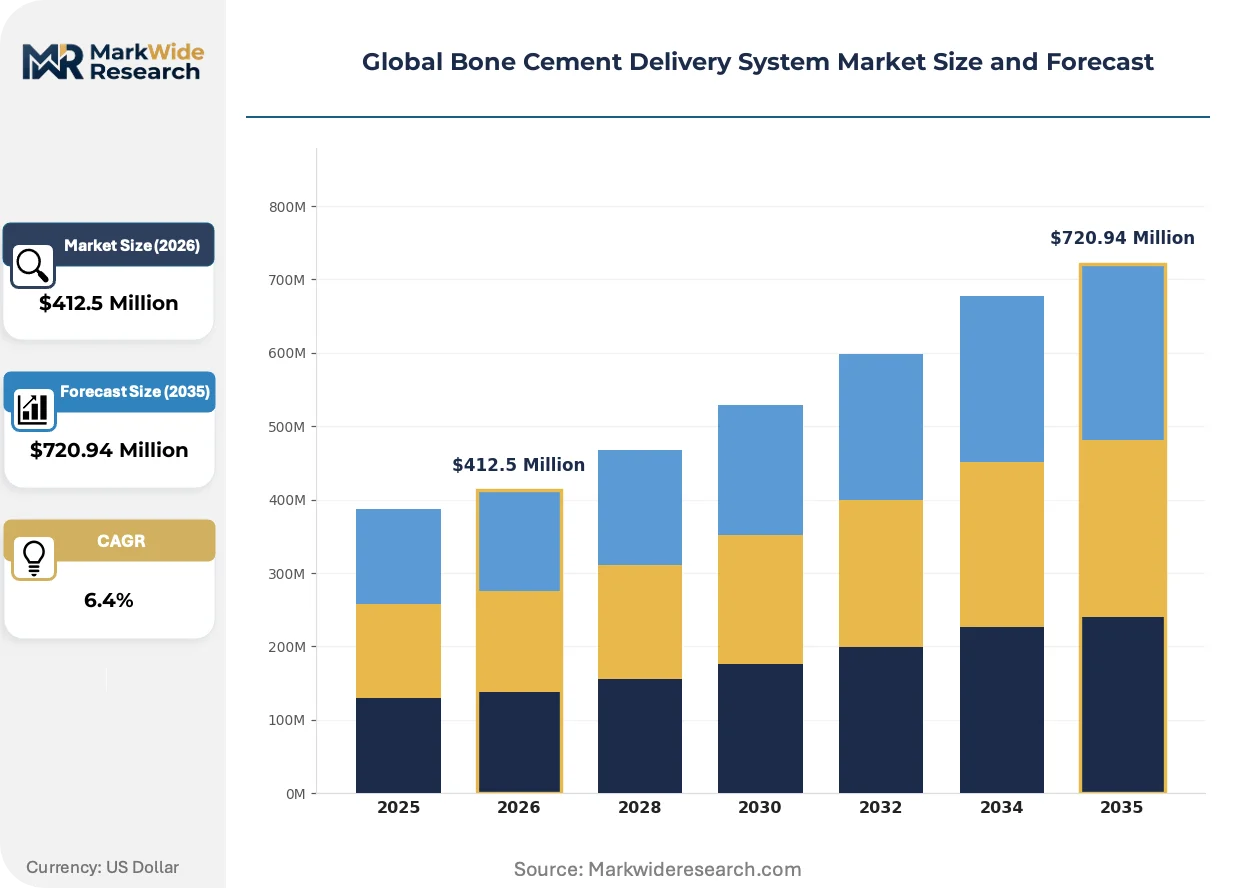
Market Dynamics
EU Medical Device Regulation premarket validation requirements are compressing product development timelines and forcing manufacturers to consolidate clinical evidence generation ahead of notified body submissions.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient joint arthroplasty programs in the United States are accelerating demand for battery-operated delivery platforms that reduce procedural time and surgeon fatigue.
- REACH-compliant material sourcing:European orthopedic manufacturers are securing competitive positioning through validated polymethyl methacrylate supply chains that satisfy ECHA substance restrictions.
- Vacuum mixing adoption:Porosity reduction protocols in German university hospitals are pulling premium cement preparation systems into standard-of-care workflows.
Market Restraints
- Raw material concentration:Methyl methacrylate monomer supply concentrates among petrochemical producers in the Middle East, exposing manufacturers to feedstock volatility and logistics disruption.
- Capital intensity barriers:Power-assisted system development requires sustained R&D investment in battery safety architectures and hydraulic pressure calibration, favoring established players with captive manufacturing.
- Regulatory divergence friction:PMDA biocompatibility validation standards in Japan impose additive testing requirements beyond FDA 510(k) pathways, fragmenting global product architectures.
Strategic Opportunities
- India orthopedic infrastructure buildout:Government hospital modernization programs under the Ayushman Bharat scheme are creating first-mover advantages for cement delivery system suppliers establishing training partnerships.
- Robotic-assisted surgery convergence:Integration of precision delivery mechanisms with navigation platforms is opening workflow capture opportunities in academic medical centers.
- Direct-to-hospital distribution:Bypassing traditional orthopedic distributor networks in Germany allows manufacturers to capture margin and control surgeon education.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in cement rheology and pressurized delivery mechanics concentrates among aging specialists in Warsaw and Bologna research clusters.
- Legacy system integration complexity:Retrofitting vacuum mixing protocols into existing operating room setups in French public hospitals demands custom adapter development and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Cement Delivery System Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Injection System, Power-Assisted System, Vacuum Mixing System, Gun-Type Delivery System Technology: Hydraulic, Pneumatic, Electric, Mechanical, Battery Operated Application: Spinal Surgery, Joint Arthroplasty, Cranial Surgery, Vertebroplasty, Maxillofacial Procedures End User: Orthopedic Clinics, Ambulatory Surgical Centers, Specialized Hospitals, Rehabilitation Centers |
| Companies Covered | Zimmer Biomet Holdings, Inc., Merit Medical Systems, Inc., Medtronic plc, B. Braun Melsungen AG, Heraeus Medical GmbH, Stryker Corporation, Globus Medical, Inc., Smith & Nephew, Johnson & Johnson (DePuy Synthes), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Cement Delivery System Market Shifts & Advancements
Active pressure modulation technologies are compressing the performance gap between manual gun-type systems and capital-intensive power platforms, redistributing competitive advantage across price tiers.
Battery-operated precision injectors is overtaking pneumatic alternatives in ambulatory settings. These devices maintain consistent 40-60 psi delivery curves regardless of cement viscosity changes. United States outpatient surgery centers are standardizing on rechargeable lithium-ion platforms that eliminate compressed gas cylinder logistics. The shift is overtaking traditional procurement patterns that separated capital equipment from consumable contracts.
EU Medical Device Regulation post-market surveillance mandates through EUDAMED are forcing manufacturers to restructure complaint handling and vigilance reporting. Device history record granularity requirements now extend to individual component batch tracking. German notified bodies are interpreting MDR Article 10 technical documentation standards most stringently, driving consolidation among smaller system suppliers unable to sustain quality management system upgrades.
Surgeon training unbundling from equipment procurement is disrupting traditional vendor-captive education models. Academic medical centers in Japan are establishing independent simulation centers for cement delivery technique certification. Device manufacturers must now compete for curriculum placement rather than securing automatic training inclusion through purchase contracts. This pattern is most visible in Tokyo and Osaka orthopedic residency programs.
Global Bone Cement Delivery System Market Segmentation
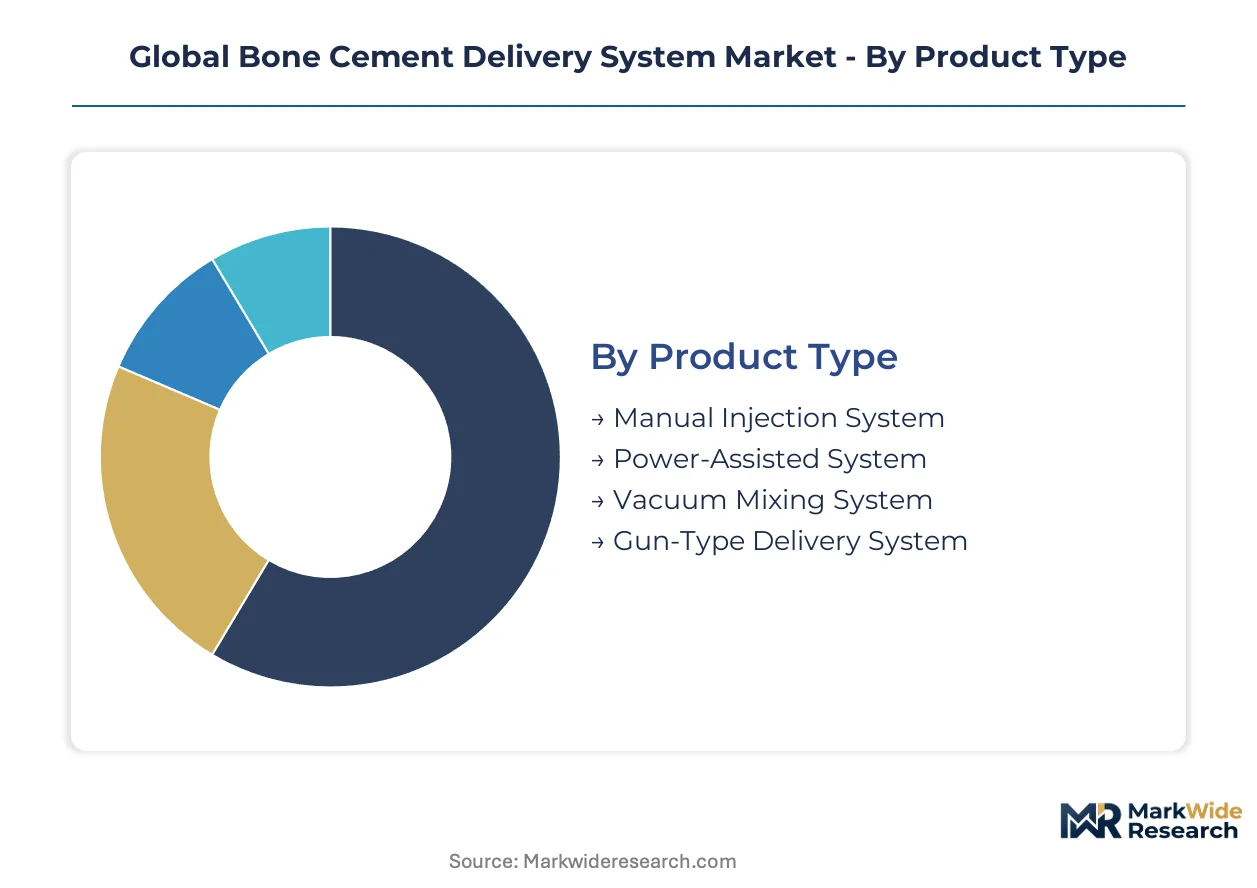
Supply concentration across polymethyl methacrylate feedstock channels dictates how delivery system architectures cluster by price-performance tier. Manufacturers calibrate product portfolios to match procurement patterns in high-volume arthroplasty programs versus specialized neurosurgical workflows.
Product Type:
Supply concentration in precision pressure calibration components favors integrated manufacturers with captive machining capabilities.
- Manual Injection System:Hand-operated syringe or pistol-grip devices deliver cement through direct mechanical force, typically employed in low-volume procedures where capital expenditure minimization outweighs speed requirements. Demand concentrates in Indian government hospital networks under Ayushman Bharat modernization, constrained by procurement budget cycles that prioritize device longevity over throughput.
- Power-Assisted System:Motorized platforms maintain consistent injection pressure through electric or battery-driven mechanisms, reducing surgeon fatigue during multi-level vertebroplasty. United States ambulatory surgical centers are standardizing these platforms as outpatient joint replacement volumes climb, though battery safety architecture validation under FDA 510(k) pathways extends development timelines.
- Vacuum Mixing System:Closed-chamber preparation units eliminate porosity through negative-pressure polymerization, commanding premium positioning in German university hospital procurement.
- Gun-Type Delivery System:Pistol-configured manual devices dominate installed base familiarity in Japanese orthopedic clinics.
Gun-type delivery systems absorb the bulk of installed capacity; power-assisted systems are expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive electric platforms from disposable mechanical alternatives in procurement evaluations.
- Hydraulic:Fluid-pressure mechanisms generate smooth delivery curves for high-viscosity cement formulations, prevalent in spinal fusion applications requiring controlled extravasation prevention. German trauma centers specify hydraulic systems for thoracolumbar procedures, though maintenance complexity elevates total cost of ownership.
- Pneumatic:Compressed gas-driven injectors offer rapid pressure modulation without electrical components, suiting operating room environments with strict ignition risk protocols. Japanese PMDA sterilization validation requirements for gas cylinder interfaces add regulatory friction to device clearance.
- Electric:Mains-powered motors deliver sustained torque for polymethyl methacrylate delivery at 40-60 psi setpoints.
- Mechanical:Ratchet or screw-driven mechanisms provide tactile feedback without external power dependencies.
- Battery Operated:Lithium-ion platforms eliminate compressed gas logistics in United States outpatient facilities.
Mechanical technology absorbs the bulk of installed capacity; battery operated platforms are climbing the fastest.
Application:
Volume concentration in joint replacement procedures shapes R&D allocation toward arthroplasty-optimized delivery geometries.
- Joint Arthroplasty:Hip and knee replacement workflows demand high-pressure cement delivery for intramedullary canal pressurization, with nozzle designs calibrated to acetabular and femoral component geometries. United States hospital systems are consolidating procurement around platforms compatible with robotic navigation systems, though integration validation cycles extend adoption timelines.
- Spinal Surgery:Pedicle screw augmentation and interbody fusion procedures require low-pressure, high-precision cement application to avoid neural compression. German spine centers specify vacuum-mixed cement delivery for thoracolumbar constructs, correlating porosity reduction with pullout strength outcomes.
- Cranial Surgery:Cranioplasty cement application prioritizes aesthetic contouring over structural load-bearing.
- Vertebroplasty:Percutaneous vertebral body augmentation uses small-gauge delivery for outpatient fracture stabilization.
- Maxillofacial Procedures:Orbital floor and mandibular reconstruction applications favor micro-delivery precision.
Joint arthroplasty absorbs the bulk of installed capacity; vertebroplasty is gaining share fastest.
End User:
Customer type fragmentation across integrated delivery networks versus independent surgical facilities fragments pricing architectures.
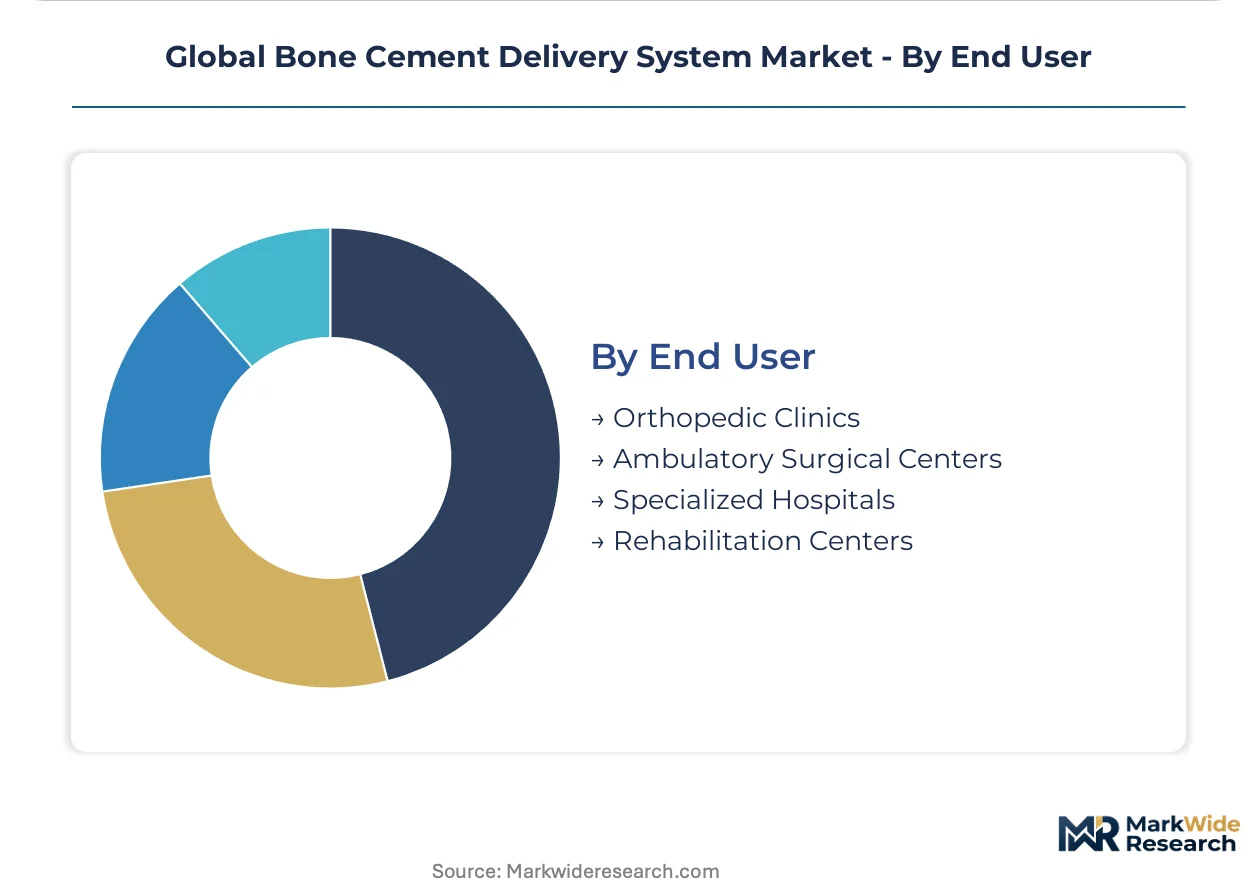
- Orthopedic Clinics:Dedicated musculoskeletal practices perform high-volume arthroplasty with standardized cement protocols, prioritizing device reliability over feature differentiation. United States clinic chains negotiate enterprise pricing through group purchasing organizations, compressing margins for manufacturers without direct sales infrastructure.
- Ambulatory Surgical Centers:Freestanding outpatient facilities optimize throughput with battery-operated platforms that eliminate setup complexity. German ASC licensing requirements under state hospital laws restrict cemented joint replacement to specific procedure codes, constraining addressable market expansion.
- Specialized Hospitals:Academic medical centers with residency programs specify training-compatible device platforms.
- Rehabilitation Centers:Post-acute facilities occasionally perform cemented hardware adjustments or salvage procedures.
Orthopedic clinics absorb the bulk of installed capacity; ambulatory surgical centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States while consumption spreads across aging populations in Japan and Western Europe. Supply chains route precision-machined components from Baden-Württemberg and Warsaw clusters toward assembly facilities serving hospital networks. Regulatory divergence between FDA, EMA, and PMDA pathways fragments product architectures and extends validation timelines.
United States
Ambulatory surgical centers in Florida and Texas are standardizing battery-operated delivery platforms for outpatient joint replacement. FDA 510(k) premarket notification requirements govern cement delivery system clearances with Class II medical device controls. Greater Boston hosts simulation centers where orthopedic residency programs certify cement delivery technique independently from vendor contracts.
Germany
University hospitals in Bavaria and North Rhine-Westphalia specify vacuum-mixing systems for porosity reduction in arthroplasty workflows. EU Medical Device Regulation mandates notified body conformity assessment through EUDAMED post-market surveillance. The Warsaw-Bologna research corridor supplies specialized biomechanical engineering talent for cement rheology development.
Japan
Tokyo and Osaka orthopedic clinics maintain installed bases of gun-type delivery systems familiar to aging surgical specialists. PMDA imposes additional biocompatibility and sterilization validation standards beyond FDA pathways. Academic medical centers in Kansai are establishing independent certification programs that decouple training from equipment procurement.
India
Government hospital modernization under Ayushman Bharat creates procurement opportunities for manual injection systems in Maharashtra and Gujarat. CDSCO regulates medical device imports and manufacturing licenses under the Medical Device Rules framework. Delhi-NCR and Bangalore clusters are emerging as training partnership hubs for cement delivery technique dissemination.
United Kingdom
NHS England procurement frameworks consolidate demand for power-assisted systems in high-volume arthroplasty centers. MHRA operates as the UK responsible authority for medical device regulation post-Brexit, maintaining alignment with EU MDR standards. London and the Southeast concentrate private orthopedic clinic chains negotiating enterprise pricing through group purchasing organizations.
Global Bone Cement Delivery System Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with captive distribution infrastructure. Three tiers separate integrated platform providers from specialized delivery technology firms and regional equipment suppliers. Consolidation pressures favor manufacturers with direct sales channels and surgeon training ecosystems. Strategic moves center on robotic navigation integration and ambulatory surgical center capture.
Among diversified orthopedic platform operators, Zimmer Biomet Holdings, Inc. and Stryker Corporation occupy positions anchoring premium-tier procurement in joint arthroplasty workflows. Merit Medical Systems, Inc. represents the specialized delivery technology archetype, competing on procedural efficiency in minimally invasive applications. These three entities exemplify the strategic divergence between integrated platform breadth and focused delivery precision.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Merit Medical Systems, Inc. |
| Medtronic plc |
| B. Braun Melsungen AG |
| Heraeus Medical GmbH |
| Stryker Corporation |
| Globus Medical, Inc. |
| Smith & Nephew |
| Johnson & Johnson (DePuy Synthes) |
| Others |
Supply & Pricing Matrix
Battery-operated precision injector adoption in United States ambulatory surgical centers is compressing capital equipment pricing while concentrating procurement leverage among integrated delivery networks. This technology shift simultaneously elevates lithium-ion battery safety certification costs and fragments component sourcing across multiple qualified suppliers.
Pricing Analysis
Margin tightening in power-assisted system tiers reflects FDA 510(k) battery architecture validation requirements and extended development timelines. Three-tier pricing structure across premium vacuum-mixing, standard electric, and economy manual gun-type levels separates German university hospital procurement from Indian government hospital budgets. Price differentiation hinges on CE marking tier under EU MDR Article 10 standards and after-sales training bundling. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with robotic navigation integration show lowest.
Supply Chain Analysis
ISO 13485 quality management certification and FDA establishment registration function as primary gating mechanisms for component suppliers entering orthopedic device supply chains. Precision-machined pressure calibration components concentrate in Baden-Württemberg machining clusters and Warsaw tool-and-die corridors. Polymethyl methacrylate monomer feeds from Middle Eastern petrochemical producers; lithium-ion cells source from South Korean and Japanese battery specialists. Single-source vulnerability concentrates in methyl methacrylate feedstock channels. Distribution runs through direct manufacturer-to-hospital contracts in Germany and orthopedic distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomechanical engineering talent scarcity in Warsaw and Bologna research clusters props pricing power for manufacturers with captive R&D capabilities. Vacuum mixing system capacity expansion lags demand acceleration from German porosity reduction protocols.
For Market Incumbents: Cement defensive positioning through backward integration into polymethyl methacrylate formulation capabilities and captive battery safety architecture development. Consolidate clinical evidence generation ahead of EU MDR notified body submissions to compress competitor clearance timelines. Threat: emerging battery-operated specialists with simplified 510(k) pathways.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian government hospital procurement under Ayushman Bharat creates white-space capture opportunity. Target manual injection system segments with REACH-compliant material sourcing and extended device longevity specifications. Go-to-market angle: training partnership hubs in Delhi-NCR and Bangalore clusters.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified orthopedic conglomerates seeking ambulatory surgical center channel control. Long-term viability favors manufacturers with integrated robotic navigation compatibility and direct-to-hospital distribution infrastructure. Signal to watch: EU MDR Article 10 technical documentation consolidation among German notified bodies.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body consolidation accelerates clearance differentiation for prepared manufacturers. |
| Hospital System Partnership | Direct channel control in German university hospitals captures margin from distributor bypass. |
| Software Companion Development | Pressure modulation algorithms for robotic navigation integration anchor academic medical center procurement. |
| Backward Integration | In-house polymethyl methacrylate formulation secures REACH-compliant supply against Middle Eastern feedstock volatility. |
| Reimbursement Strategy | Outpatient joint arthroplasty coding alignment in United States ASCs standardizes battery-operated platform adoption. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR EUDAMED vigilance records, and PMDA biocompatibility validation guidelines, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers specializing in cement rheology, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare utilization data, and customs import records for polymethyl methacrylate monomer. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue aggregation.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application procedure, end-user facility category, and regional regulatory cluster. CAGRs derived from logarithmic trend fitting of installed base expansion and replacement cycle dynamics. Industry-specific forecast inputs encompass ambulatory surgical center licensing trajectory and robotic navigation platform penetration rates.
Underlying measurement precision varies by segment; power-assisted system forecasts carry tighter precision than vacuum mixing category projections due to disclosed manufacturer shipment data. Forecasts reflect assumptions regarding EU MDR implementation pace and PMDA biocompatibility standard harmonization. A model refresh is warranted upon material change in FDA battery-operated device guidance or ambulatory surgical center joint replacement reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Biopsy Punch Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Global Pessary Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Global Bone Cement Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Needle Destroyer Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market