
 Pancreatic and Biliary Stents Market | 2026-2036
Pancreatic and Biliary Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic and Biliary Stents Market Analytics
Hospital procurement for pancreatic and biliary stents is decoupling from traditional group purchasing organizations toward direct manufacturer contracts with integrated delivery networks. Boston Scientific leverages its broad interventional endoscopy portfolio to sustain long-term supply agreements with major health systems. Olympus Corporation anchors its position through proprietary endoscope-stent compatibility that locks in recurring device sales. Cook Group differentiates via specialized biliary stent geometries designed for complex malignant strictures.
Pancreatic and biliary stents are tubular prostheses typically constructed from nitinol, stainless steel, or biocompatible polymers such as polyurethane or silicone, designed for endoscopic placement to relieve obstructions in the pancreatic duct or biliary tree. These devices maintain luminal patency in benign and malignant strictures, with diameters ranging from 5 Fr to 10 Fr and lengths from 4 cm to 12 cm depending on anatomical target. Self-expanding metallic stents dominate malignant biliary applications where longer patency duration reduces reintervention burden. Polymer stents retain significant share in benign conditions and preoperative drainage where removability matters. Ambulatory surgical centers represent the fastest-growing end-user channel as same-day ERCP procedures migrate from inpatient settings.
The FDA governs premarket notification requirements under 510(k) pathways, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class III implantable devices. Both frameworks are elevating biocompatibility and fatigue-testing requirements, which favors manufacturers with established regulatory infrastructure. Stakeholders must monitor evolving reimbursement thresholds for outpatient ERCP procedures, as payor policy shifts will determine whether ambulatory migration accelerates or stalls across key markets.
Market Dynamics
The migration of endoscopic retrograde cholangiopancreatography procedures from inpatient hospitals to ambulatory surgical centers is compressing procurement cycles and forcing manufacturers to reconfigure distribution networks around same-day discharge protocols.
Growth Catalysts
- Outpatient Reimbursement Expansion:CMS reimbursement codes for same-day ERCP procedures are accelerating facility investment in interventional gastroenterology suites across United States ambulatory centers.
- Biodegradable Polymer Innovation:Absorbable stent materials eliminate retrieval procedures in benign stricture cases, reducing total cost of care and expanding addressable patient populations.
- Integrated Delivery Network Consolidation:United States health system mergers are standardizing device formularies around preferred manufacturer contracts with multi-year supply commitments.
Market Restraints
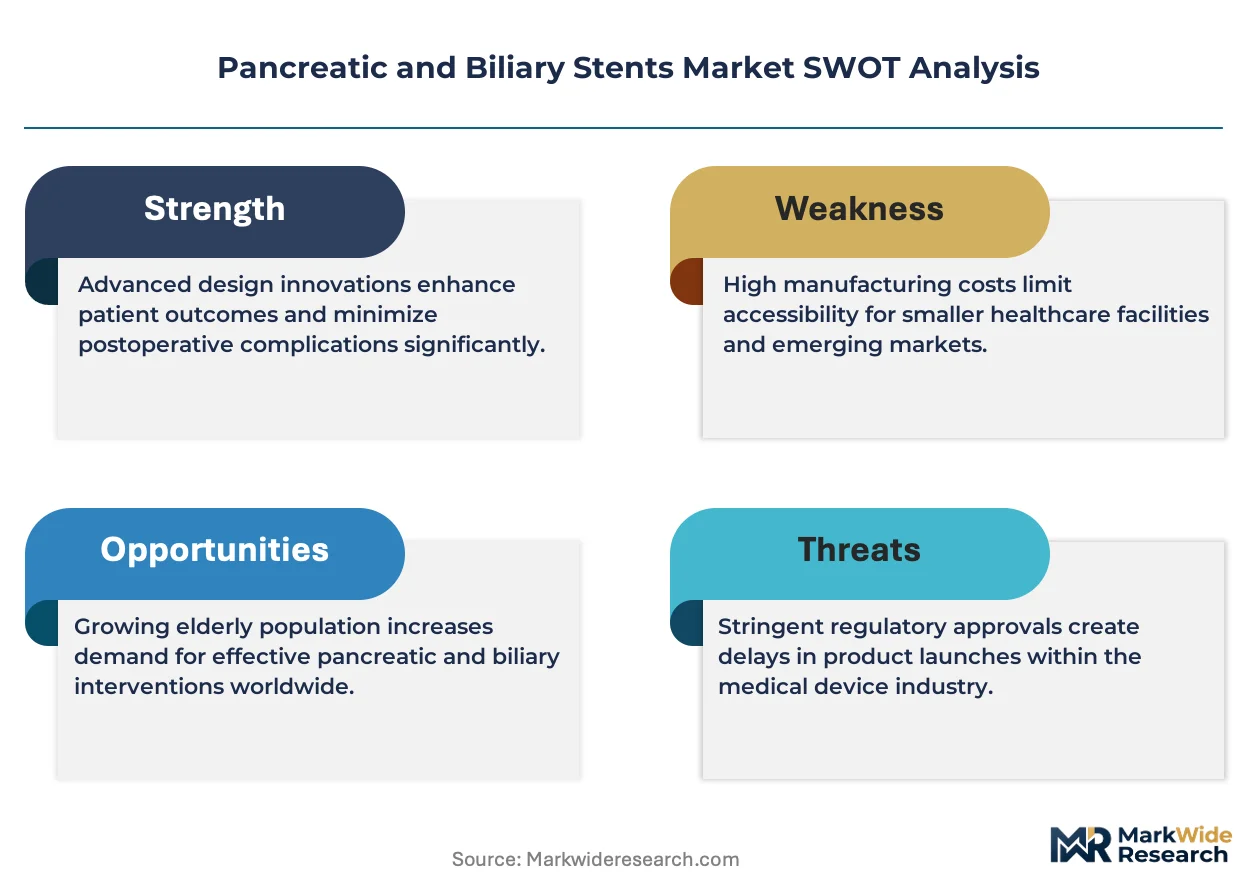
- Nitinol Price Volatility:Nickel-titanium alloy supply concentration in Chinese smelting operations exposes manufacturers to raw material cost swings and export quota uncertainties.
- EU MDR Clinical Evidence Burden:The European Union Medical Device Regulation's stricter biocompatibility testing requirements for Class III implantables are extending certification timelines and elevating compliance costs.
- Plastic Stent Patency Limitations:Polymer devices in malignant biliary obstruction require replacement every 3-4 months, creating procedure burden that metallic alternatives are gradually displacing.
Strategic Opportunities
- India Outpatient Infrastructure:Private hospital chains in Mumbai, Delhi, and Bangalore are building dedicated endoscopy centers to capture rising pancreaticobiliary disease prevalence among aging urban populations.
- Drug-Eluting Stent Convergence:Combination devices integrating chemotherapy agents with metallic scaffolds are expanding into locally advanced pancreatic cancer palliation protocols.
- Japan Preventive Screening Mandates:METI-backed health check programs for high-risk populations are expanding early biliary stricture detection and stent-eligible intervention volumes.
Industry Challenges
- Interventional Endoscopist Training Bottlenecks:ERCP procedure volume requirements for credentialing are limiting specialist pipeline growth relative to rising patient demand.
- 510(k) Predicate Device Drift:FDA's narrowing acceptance of historical stent designs as predicates is forcing novel submissions toward more expensive De Novo pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic and Biliary Stents Market |
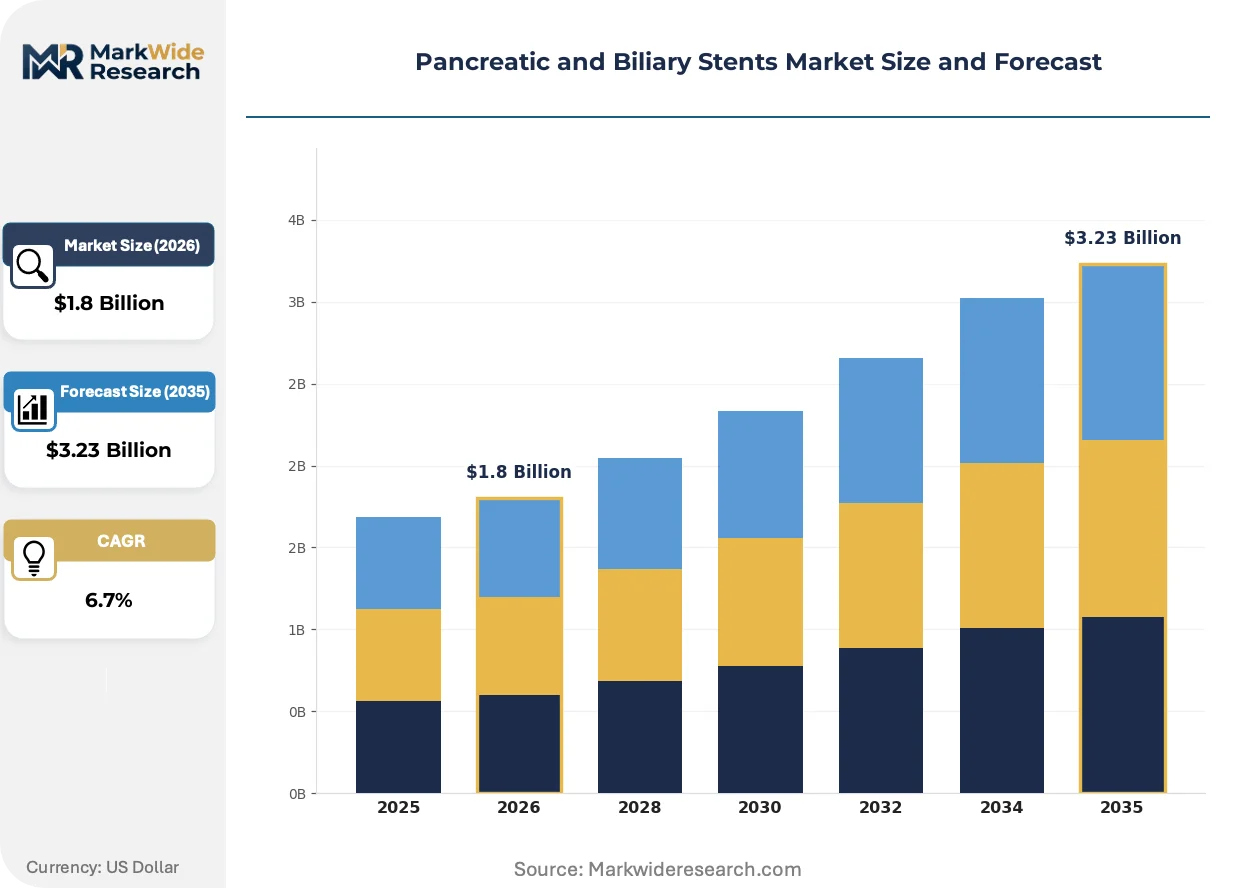
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pocket Stents, Expandable Stents, Self-Expanding Stents, Guided Stents End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Healthcare Material: Metallic Stents, Polymer Stents, Biodegradable Stents, Coated Stents Design: Covered Stents, Uncovered Stents, Flared Stents, Angled Stents |
| Companies Covered | Olympus Corporation, Becton, Dickinson and Company, Boston Scientific, Taewoong Medical, Abbott Laboratories, Medtronic, CONMED Corporation, ENDO-FLEX GmbH, Cook Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic and Biliary Stents Market Evolving Landscape
Device manufacturers are racing to differentiate through material science breakthroughs and procedural workflow integration, shifting competitive advantage from scale economics toward clinical outcome demonstration.
Biodegradable magnesium alloy stents are expanding into benign biliary stricture applications where temporary scaffolding eliminates retrieval colonoscopy requirements. Academic medical centers in Germany and South Korea are piloting these devices in preoperative drainage protocols. The technology is compressing total procedure counts per patient episode and reshaping cost-accounting models for payors.
The European Union Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to maintain active implant registries tracking real-world patency outcomes. This policy is elevating data infrastructure costs but creating competitive separation between firms with established clinical evidence platforms and smaller entrants. Metallic stent portfolios face the steepest compliance burden due to longer implant durations.
Direct manufacturer contracting with United States integrated delivery networks is displacing traditional group purchasing organization intermediaries in stent procurement. Health systems in Texas, Florida, and Ohio are consolidating spend across multiple facilities to extract volume-based pricing guarantees. This concentration is visible most acutely in malignant biliary applications where metallic stent standardization yields measurable supply chain savings.
Pancreatic and Biliary Stents Market Segmentation
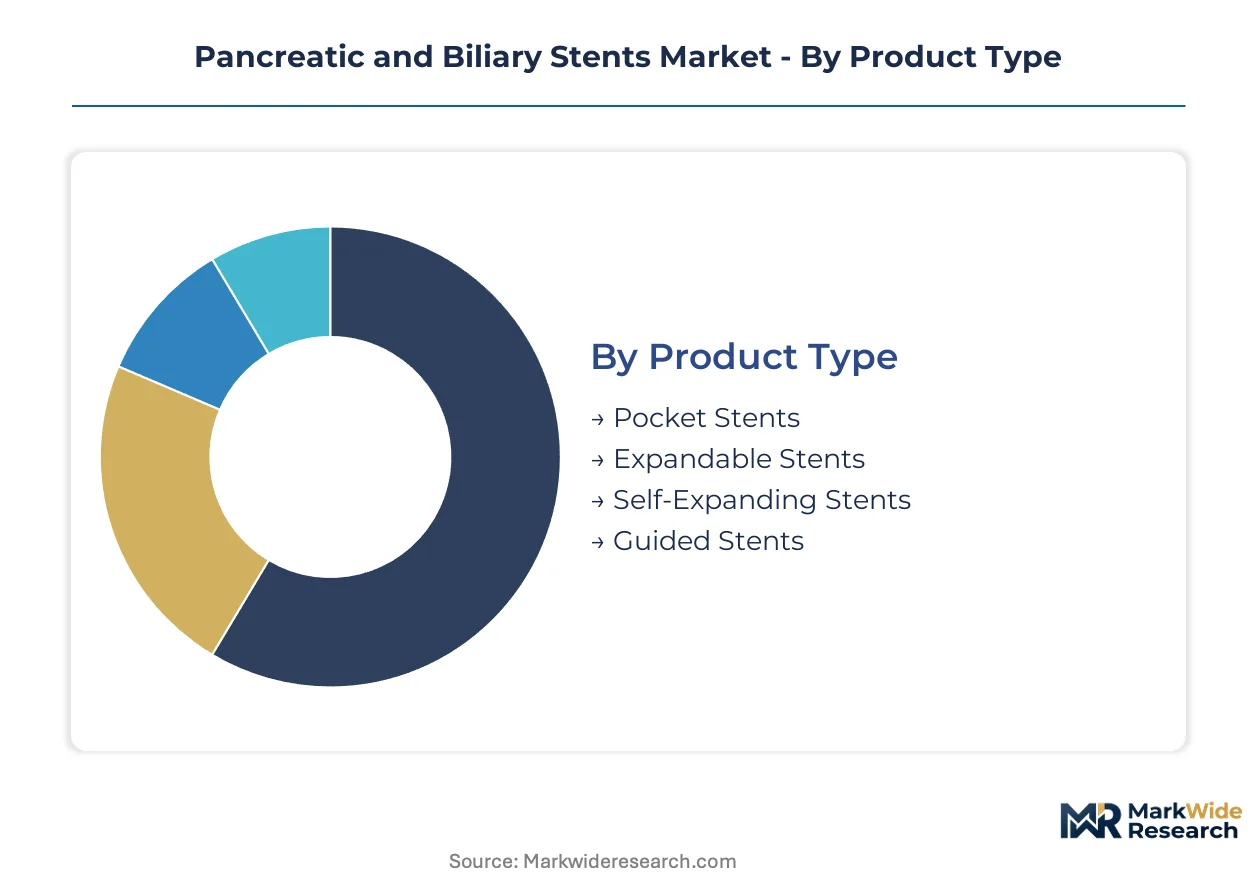
Stent segmentation in pancreatic and biliary applications determines reimbursement pathways, procurement contract structures, and clinical training requirements across endoscopy suites. Manufacturers configure product portfolios around material durability versus removability trade-offs that align with malignant versus benign disease presentations.
Product Type:
Procedure complexity and anatomical access challenges differentiate buyer preferences across stent deployment mechanisms.
- Self-Expanding Stents:Nitinol or stainless steel scaffolds deploy via catheter release without balloon inflation, enabling placement in tortuous biliary strictures. United States interventional gastroenterology suites favor these devices for malignant obstructions where long-term patency reduces reintervention frequency.
- Expandable Stents:Balloon-expandable platforms deliver precise diameter control in proximal biliary strictures with fibrotic resistance. Academic medical centers in Germany and Japan deploy these configurations for hilar cholangiocarcinoma where radial force customization matters.
- Pocket Stents:Specialized retrieval-loop designs facilitate endoscopic removal in benign stricture management.
- Guided Stents:Radiopaque marker integration enables fluoroscopic placement confirmation in altered anatomy cases.
Self-expanding platforms lead volumes today; biodegradable iterations are gaining share fastest.
End User:
Capital equipment requirements and reimbursement coding determine facility participation in stent-eligible procedures.
- Ambulatory Surgical Centers:Same-day ERCP capabilities require fluoroscopy suites and anesthesia support that smaller clinics cannot sustain. CMS outpatient reimbursement expansion across Texas and Florida is accelerating capital deployment for biliary stent placement in these settings.
- Hospitals:Inpatient admission infrastructure handles complex malignant cases requiring multidisciplinary tumor board coordination. Integrated delivery networks in Ohio and California are consolidating stent procurement across hospital campuses to extract volume pricing.
- Clinics:Office-based endoscopy limits stent placement to diagnostic procedures with referral pathways.
- Home Healthcare:Post-procedure monitoring and drainage tube management extend care continuity outside facilities.
Hospitals retain the largest procedure share; ambulatory surgical centers are expanding most quickly.
Material:
Biocompatibility profiles and retrieval requirements segment material selection by disease chronicity.
- Metallic Stents:Nitinol and Elgiloy alloys provide radial force durability for malignant biliary strictures where tissue ingrowth extends functional patency. FDA 510(k) pathways for these devices emphasize fatigue testing under cyclic loading conditions that polymer alternatives do not face.
- Biodegradable Stents:Magnesium alloy and polylactic acid compositions eliminate retrieval colonoscopy in benign stricture protocols. South Korean academic centers are piloting these materials in preoperative drainage to compress total procedure counts per patient episode.
- Polymer Stents:Polyurethane and silicone formulations dominate temporary drainage applications.
- Coated Stents:Drug-eluting and anti-migratory surface treatments address stent occlusion mechanisms.
Metallic stents command the revenue base; biodegradable platforms are climbing the fastest.
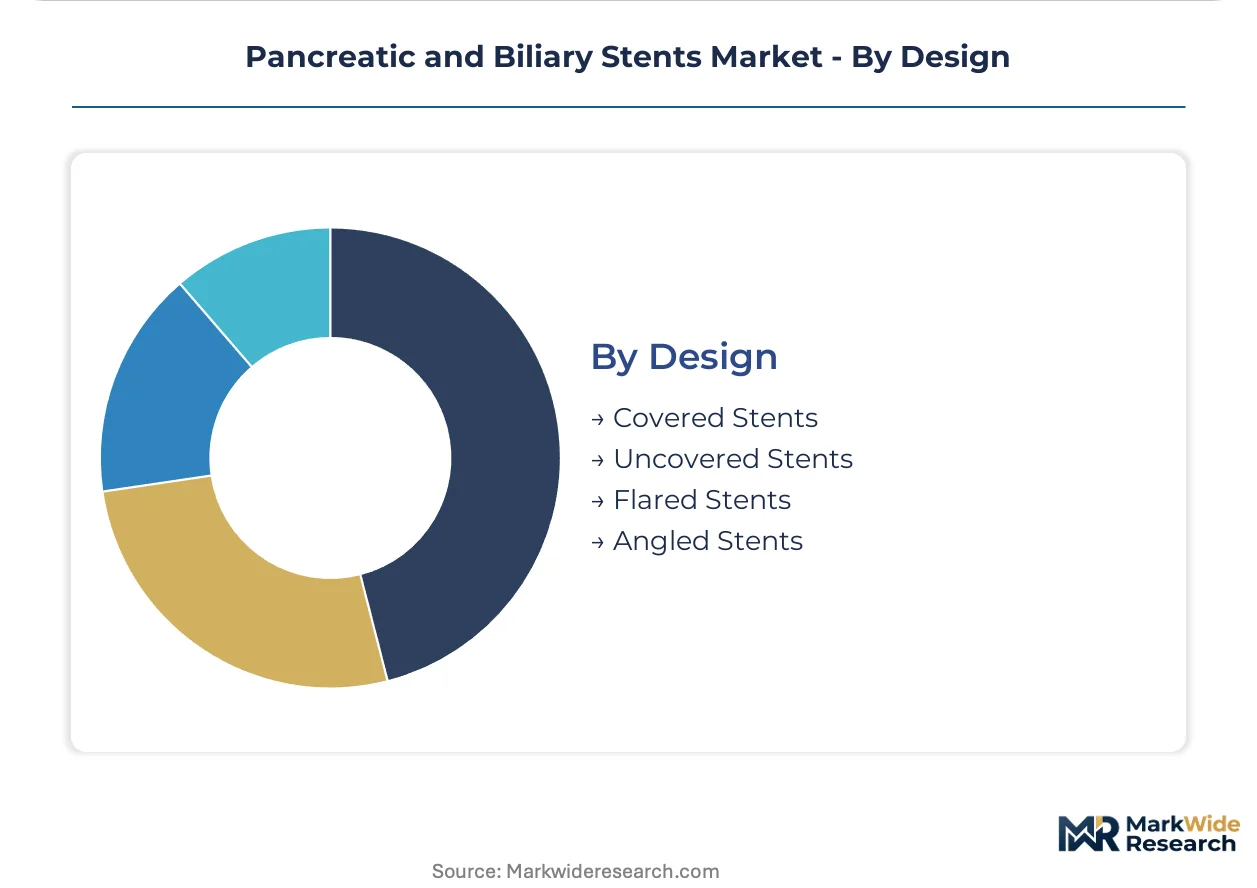
Design:
Anatomical fixation and migration resistance requirements differentiate stent architecture by stricture location.
- Covered Stents:Polymer membrane barriers prevent tumor ingrowth in distal malignant biliary obstructions, extending patency duration versus uncovered alternatives. EU MDR post-market surveillance requirements are forcing manufacturers to maintain active registries tracking real-world outcomes for these implants.
- Flared Stents:Proximal and distal diameter differentials anchor devices at stricture margins to resist axial migration. Japanese PMDA approvals for these designs emphasize radial force consistency across the flared transition zone.
- Uncovered Stents:Open mesh architectures permit side branch patency in hilar strictures.
- Angled Stents:Pre-curved configurations align with anatomical variants in pancreatic duct anatomy.
Uncovered stents retain the highest placement volumes; covered platforms are expanding most rapidly in malignant applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procedural volumes outpace German throughput by a factor of three, yet South Korean centers now lead biodegradable stent pilot adoption rates. Japan maintains the highest metallic stent penetration per capita among aging populations.
United States
Ambulatory surgical centers in Texas and Florida are expanding ERCP suites to capture CMS outpatient reimbursement codes for same-day biliary procedures. FDA 510(k) clearance pathways for nitinol self-expanding designs continue streamlining market entry for novel stent geometries. Integrated delivery networks across Ohio and California are consolidating procurement across hospital campuses to extract volume-based pricing guarantees from manufacturers.
Germany
Academic medical centers in Munich and Heidelberg are piloting magnesium alloy biodegradable stents for preoperative biliary drainage protocols. EU MDR post-market surveillance requirements mandate active implant registries tracking real-world patency outcomes, elevating compliance costs for metallic portfolios. The country's interventional gastroenterology training programs are expanding ERCP credentialing capacity to address specialist pipeline constraints.
Japan
METI-backed health check programs for high-risk populations are expanding early biliary stricture detection and stent-eligible intervention volumes. PMDA approvals for flared stent designs emphasize radial force consistency across diameter transition zones. Tokyo and Osaka medical centers are standardizing covered stent protocols for malignant hilar obstructions.
South Korea
Seoul-based academic hospitals are conducting the largest clinical pilots of polylactic acid biodegradable stents in benign stricture management. The country's national health insurance system is evaluating procedure bundling codes that would compress total episode costs by eliminating retrieval colonoscopies. Device manufacturers are establishing dedicated training centers for interventional endoscopists in the capital region.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are building dedicated endoscopy centers to capture rising pancreaticobiliary disease prevalence among aging urban populations. CDSCO import licensing requirements for Class III implantables are channeling procurement toward established multinational suppliers with regulatory infrastructure. Metropolitan tertiary centers are expanding fellowship programs to address the gap between ERCP demand and qualified specialist supply.
Pancreatic and Biliary Stents Market Competitive Landscape
United States producers anchor one tier; Japanese and German specialists hold differentiated positions in endoscope-stent compatibility and complex stricture geometries. The vendor base clusters around three strategic archetypes: diversified medtech conglomerates with broad interventional portfolios, pure-play endoscopy device specialists, and regional champions with localized regulatory expertise. Dominant competitive moves include direct contracting with integrated delivery networks to displace group purchasing organization intermediaries, and material science partnerships targeting biodegradable scaffold platforms.
Within the diversified conglomerate tier, Boston Scientific and Olympus Corporation exemplify scale-driven positions through long-term supply agreements and proprietary ecosystem lock-in. Cook Group occupies a specialist position in complex malignant stricture applications. ENDO-FLEX GmbH represents the mid-cap European fabrication archetype with concentrated regulatory expertise in EU MDR compliance pathways.
| Leading Market Players |
|---|
| Olympus Corporation |
| Becton, Dickinson and Company |
| Boston Scientific |
| Taewoong Medical |
| Abbott Laboratories |
| Medtronic |
| CONMED Corporation |
| ENDO-FLEX GmbH |
| Cook Group |
| Others |
Value Network & Pricing Analysis
Nitinol price indices on the London Metal Exchange cascade through pancreatic and biliary stent manufacturing tiers, compressing margins on metallic scaffolds while polymer alternatives capture cost-sensitive ambulatory volume. Chinese nickel-titanium smelting concentration amplifies this transmission mechanism into United States and European procurement contracts.
Pricing Analysis
Capacity additions in South Korean magnesium alloy production are reshaping price floors for biodegradable stent platforms. Three-tier pricing structure across premium, standard, and economy levels separates drug-eluting metallic designs from bare nitinol scaffolds and commodity polymer alternatives. Pricing pressure stems from integrated delivery network consolidation extracting volume guarantees. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers tolerate premium tiers for complex malignant applications.
Supply Chain Analysis
Nitinol feedstock rests on Chinese smelting operations, German precision wire drawing, and United States shape-setting fabrication. Polymer resin supplies draw from South Korean petrochemical complexes and Japanese specialty polymer producers. Single-source vulnerability concentrates in nickel-titanium alloy supply. Distribution runs through manufacturer-direct contracts with integrated delivery networks, displacing traditional group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pancreatic and biliary stents function as a stable compounder anchored by aging demographics and irreversible procedure migration toward outpatient settings. Reimbursement code expansion for same-day ERCP sustains predictable volume growth across ambulatory channels.
For Market Incumbents: Anticipate biodegradable stent platforms eroding metallic stent share in benign stricture protocols. Defend position by deepening backward integration into nitinol wire production and securing multi-year supply agreements with Texas and Florida ambulatory networks. Lock in proprietary endoscope compatibility to sustain recurring revenue attachment. For New Entrants and Emerging Players: Enter via biodegradable magnesium alloy platforms targeting preoperative biliary drainage in German and South Korean academic centers. White-space exists in drug-eluting stent convergence for locally advanced pancreatic cancer palliation. Pursue regulatory sandbox pathways in South Korea's national health insurance evaluation framework. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed mid-cap balance sheet capacity. Five-to-ten year viability favors manufacturers with established clinical evidence platforms and active implant registries. Target acquisition archetype: European fabrication specialists with concentrated EU MDR expertise and biodegradable scaffold partnerships. Watch biodegradable stent reimbursement bundling decisions as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Scaffold Development | Magnesium alloy platforms eliminate retrieval procedures, compressing total episode costs for payors. |
| Integrated Delivery Network Partnership | Direct manufacturer contracts with Ohio and California health systems displace group purchasing organization intermediaries. |
| EU MDR Compliance Infrastructure | Post-market surveillance registries for metallic stents create competitive separation against undercapitalized entrants. |
| Drug-Eluting Stent Convergence | Chemotherapy-agent integration expands addressable market into locally advanced pancreatic cancer palliation. |
| Ambulatory Surgical Center Training | Dedicated Seoul and Mumbai endoscopist education centers address specialist pipeline constraints limiting procedure growth. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional gastroenterologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, EU MDR technical documentation, and hospital procurement contract records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Segment-weighting approaches distributed value across self-expanding versus balloon-expandable platforms, metallic versus biodegradable materials, and ambulatory surgical center versus hospital end-user channels. CAGRs derived from procedure volume trajectories, reimbursement code expansion schedules, and material substitution curves. Forecast inputs incorporated nitinol price volatility indices, EU MDR certification timeline data, and ambulatory migration penetration rates by United States state.
Inputs from CMS outpatient reimbursement databases and EU MDR notified body technical files were available through the study window; gaps in real-time ambulatory surgical center procedure counts introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions on biodegradable stent adoption velocity and specialist training pipeline expansion. Regulatory reimbursement bundling decisions, nickel-titanium export quota announcements, and 510(k) predicate acceptance criteria shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electronic Skin Patch Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Neuromodulation Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
PET Injectors Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market