
 Thin Wafer Market | 2026-2036
Thin Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wafer Market Analysis
The widening gap between sub-50-micron premium wafers and standard 100-micron commodity supply is repositioning procurement strategies across the semiconductor value chain. Shin-Etsu Chemical leverages its polysilicon-to-wafer integration to sustain margin capture in ultra-thin silicon segments. SUMCO anchors its position through advanced crystal-pulling capabilities that differentiate thickness uniformity at scale.
Thin wafers are semiconductor substrates ground or etched to thicknesses below 200 micrometers, enabling 3D stacking, through-silicon vias, and reduced thermal resistance in high-density packages. Their primary purpose is to maximize die-per-wafer yields while enabling form-factor miniaturization in mobile processors and power devices. Silicon wafers dominate volume shipments but SOI wafers command premium positioning where substrate isolation improves radio-frequency and power efficiency. MEMS applications represent the fastest-growing application segment as automotive pressure sensors and inertial measurement units adopt thinner device layers.
REACH substance restrictions and RoHS hazardous material limits in Europe constrain dopant chemistries and surface treatments available to wafer manufacturers. The EPA and OSHA in the United States impose particulate and ergonomic standards that elevate cleanroom capital intensity for sub-100-micron handling. Stakeholders must track how the EU AI Act and emerging chip export controls reshape end-user qualification pathways before committing capacity to advanced thickness nodes.
Market Dynamics
Chiplet architectures are compressing substrate thickness requirements across advanced packaging lines, forcing foundries to qualify sub-75-micron wafers at volume while managing warpage and breakage rates that spike below 100 micrometers.
Growth Catalysts
- EU AI Act compliance pathways:Semiconductor manufacturers are pre-qualifying thinner wafers for AI accelerator modules to meet emerging European traceability and energy-efficiency mandates before enforcement deadlines.
- MEMS sensor miniaturization:Automotive pressure sensors and inertial measurement units are migrating to sub-50-micron device layers, pulling specialized SOI wafer volumes from South Korean foundry expansions.
- Plasma dicing adoption:Dry etch separation processes are enabling thinner exit wafers without mechanical damage, expanding yield economics for 3D stacked memory producers.
Market Restraints
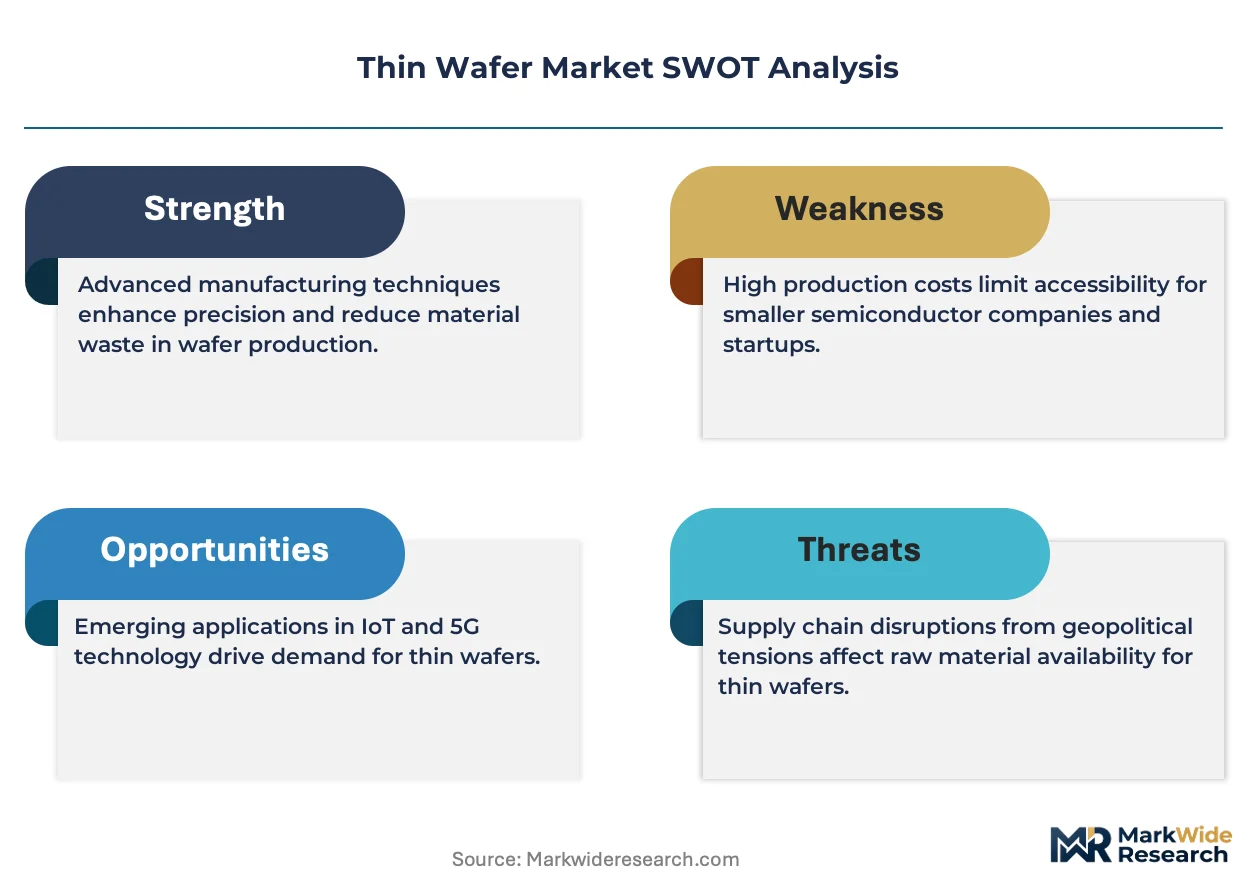
- Polysilicon supply concentration:Five integrated producers control over 80% of semiconductor-grade feedstock, exposing wafer manufacturers to price volatility and allocation rationing during capacity crunches.
- Sub-50-micron handling physics:Wafer warpage and breakage rates escalate non-linearly below 75 micrometers, constraining automated transport and temporarily capping practical thickness floors.
- REACH substance restrictions:ECHA limitations on boron and phosphorus dopant chemistries are forcing reformulation of surface treatments, extending qualification timelines for European-bound shipments.
Strategic Opportunities
- Power device substrate conversion:Silicon carbide epitaxy lines are experimenting with ultra-thin silicon carrier wafers as temporary substrates, opening a captive demand channel distinct from mainstream logic applications.
- India PLI scheme localization:Domestic packaging incentives are attracting thin-wafer grinding and dicing investments to Gujarat and Tamil Nadu, creating new regional supply nodes outside East Asian concentration.
- Glass interposer convergence:Through-glass via technologies are merging with thin-wafer temporary bonding workflows, enabling hybrid substrate architectures for next-generation RF modules.
Industry Challenges
- Cleanroom ergonomics compliance:OSHA particulate and lifting standards for sub-100-micron wafer handling are elevating capital intensity per square foot, compressing returns on legacy facility retrofits.
- Cross-node qualification bottlenecks:Each thickness reduction requires recertification across TSMC, Samsung, and Intel process flows, fragmenting engineering resources and extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wafer Market |
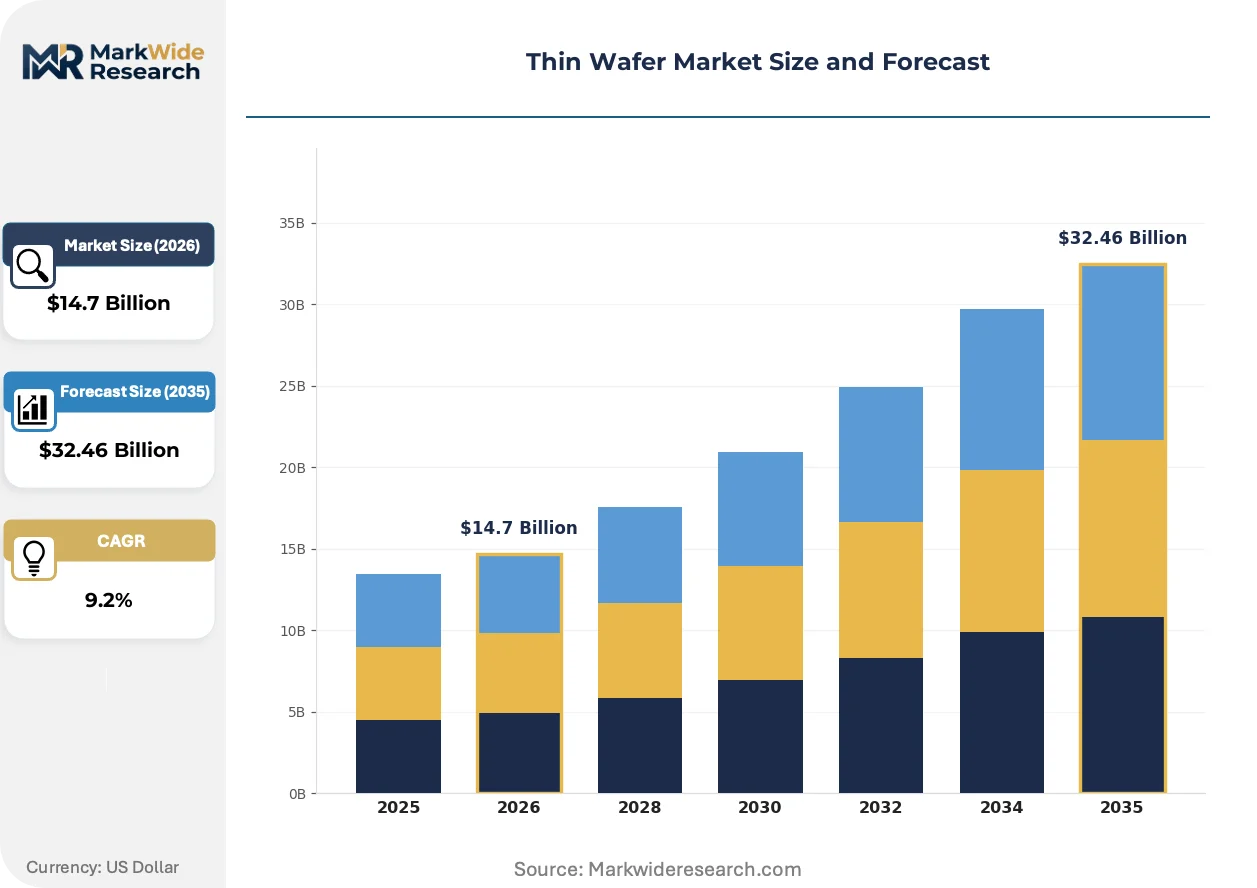
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $32.46 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Wafers, III-V Wafers, Compound Wafers, SOI Wafers Application: Semiconductors, Photovoltaics, MEMS, Sensors End User: Electronics, Renewable Energy, Automotive, Aerospace Technology: Etching, Dicing, Bonding, Grinding |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., SUMCO Corporation, Siltronic AG, GlobalWafers Co., Ltd., SK Siltron, Süss MicroTec AG, DISCO Corporation, LG Siltron Inc., Sunedison Semiconductor Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wafer Market Emerging Trajectories
Laser-assisted debonding and plasma activation processes are converging to redefine temporary carrier workflows, compressing the cost gap between mechanical grinding and chemical etch thinning.
Plasma-activated direct bonding is rewriting the economics of wafer-to-wafer stacking by eliminating adhesive layers that previously consumed 5-10 micrometers of vertical budget. Memory manufacturers at Samsung and Micron are transitioning pilot lines to this approach for HBM4 architectures. The elimination of intermediate polymers is compressing thermal resistance paths and enabling thicker die stacks within existing package height constraints.
REACH Annex XIV substance restrictions are tightening the allowable concentration windows for boron and phosphorus surface dopants used in wafer resistivity tuning. European-bound wafer lots now require dedicated process lines with segregated chemistries and enhanced metrology documentation. Suppliers are responding by qualifying alternative gallium and indium doping schemes that trade off cost against compliance certainty.
Consolidation among OSATs is compressing the qualified vendor lists for thin-wafer grinding and dicing services, shifting negotiation leverage toward packaging houses. Tier-one foundries are now mandating captive or semi-captive grinding capacity as a condition of advanced node access. This concentration is most visible in South Korea, where Samsung's packaging affiliate has absorbed multiple independent grinding specialists since 2023.
Thin Wafer Market Segmentation
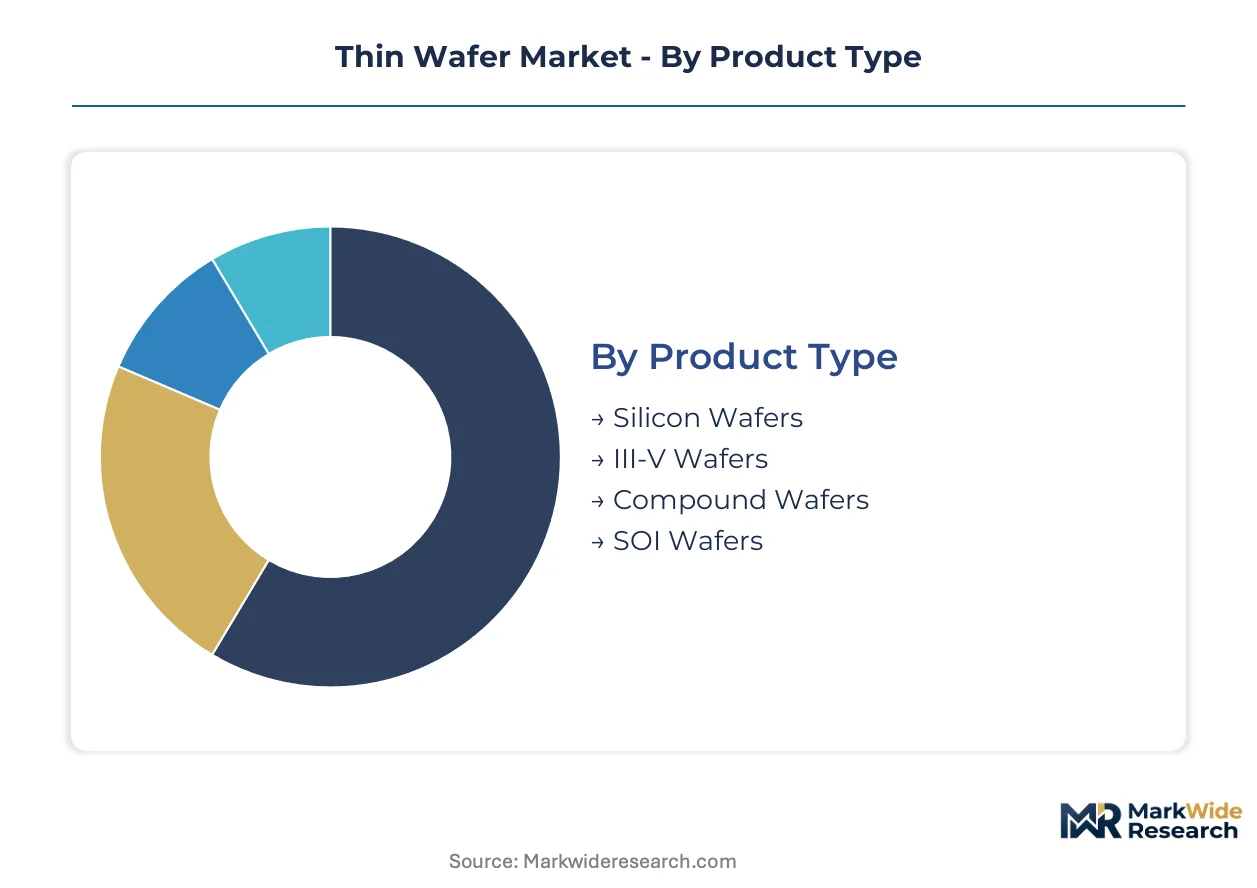
Thin wafer procurement strategies diverge sharply across substrate compositions and downstream applications. Specification requirements for chiplet packaging, MEMS miniaturization, and power device integration create distinct demand clusters that reshape supplier qualification priorities.
Product Type:
Thickness tolerance and crystal orientation specifications define competitive positioning across substrate categories.
- Silicon Wafers:Standard crystalline silicon substrates ground to sub-200-micron thicknesses dominate volume shipments for logic and memory packaging. Demand concentrates in South Korean foundry expansions where Samsung and SK Hynix are qualifying sub-75-micron wafers for HBM stacking.
- SOI Wafers:Silicon-on-insulator architectures embed a buried oxide layer that eliminates latch-up in RF and power-efficient designs. Automotive radar modules and 5G baseband processors in European OEM supply chains are absorbing premium-priced SOI volumes for substrate isolation.
- III-V Wafers:Gallium arsenide and gallium nitride substrates enable high-electron-mobility transistors for millimeter-wave applications.
- Compound Wafers:Silicon carbide and gallium nitride-on-silicon alternatives serve power electronics where thermal conductivity exceeds silicon limits.
Mature deployment sits with Silicon Wafers. Newer deployment is concentrated in SOI Wafers.
Application:
End-use performance thresholds determine acceptable wafer thickness floors and breakage risk tolerance.
- Semiconductors:Logic and memory packaging applications drive the steepest thickness reduction trajectories. Through-silicon via integration at TSMC and Intel process nodes is pulling sub-50-micron wafers into pilot production despite warpage handling challenges.
- MEMS:Microelectromechanical systems require device layers thin enough for resonant frequency tuning yet robust enough for wafer-level packaging. Automotive pressure sensors for tire pressure monitoring and inertial measurement units for electronic stability control are climbing the fastest in wafer consumption.
- Sensors:Image sensors and biometric detectors employ thinned wafers for optical path minimization.
- Photovoltaics:Solar cell manufacturers balance silicon savings against mechanical fragility in cell handling.
Established volume leadership rests with Semiconductors. Accelerating qualification activity centers on MEMS.
End User:
Industry-specific reliability standards and supply security requirements fragment procurement patterns.
- Electronics:Consumer device manufacturers prioritize die-per-wafer economics and form-factor constraints. Smartphone processor packaging at Apple and Qualcomm suppliers is compressing substrate thickness targets below 100 microns for vertical space savings.
- Automotive:Functional safety requirements under ISO 26262 impose stricter defect density thresholds than consumer applications. ADAS sensor modules and power inverter substrates are absorbing specialized thin-wafer volumes with enhanced traceability documentation.
- Renewable Energy:Solar inverter and energy storage system manufacturers seek cost-optimized wafer solutions.
- Aerospace:Radiation-hardened device requirements sustain demand for specialized substrate qualification.
Volume concentration aligns with Electronics. Specification tightening is most pronounced in Automotive.
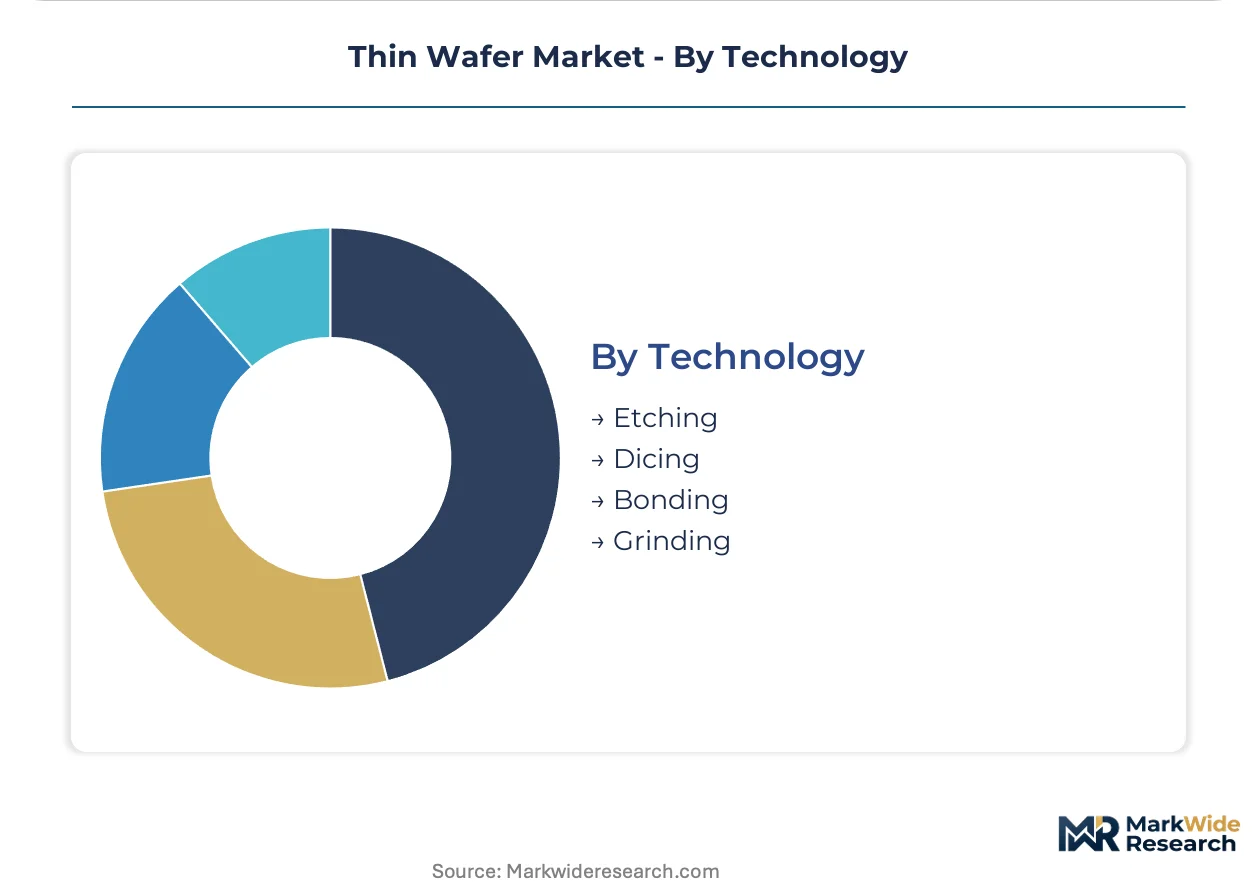
Technology:
Thinning and separation process selection directly constrains achievable thickness floors and edge quality.
- Grinding:Mechanical backside grinding with diamond wheels remains the baseline thinning method for cost-sensitive applications. South Korean OSATs are expanding captive grinding capacity to secure advanced packaging node access.
- Etching:Wet chemical and plasma etch processes remove subsurface damage left by mechanical grinding. Memory manufacturers at Micron and Samsung are transitioning HBM pilot lines to plasma-assisted thinning for improved die strength.
- Dicing:Blade dicing and stealth laser dicing separate thinned wafers into individual dies.
- Bonding:Temporary adhesive and direct bonding workflows enable wafer-to-wafer stacking architectures.
Process maturity favors Grinding. Capability investment is redirecting toward Etching.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors thin wafer demand concentration through Samsung and SK Hynix foundry expansions pulling sub-75-micron volumes for HBM stacking. European REACH compliance pathways and South Korean capacity buildouts are fragmenting procurement geography across three distinct supply basins.
South Korea
Samsung and SK Hynix are qualifying sub-50-micron wafers for HBM4 architectures at Pyeongtaek and Icheon complexes. MFDS chemical safety notifications align with REACH substance tracking for European-bound shipments. The Seoul Capital Area concentrates grinding and dicing captive capacity as packaging affiliates absorb independent specialists.
United States
Intel's Arizona and Oregon fabs are piloting through-silicon via integration at sub-50-micron nodes for AI accelerator modules. OSHA particulate and ergonomic standards elevate cleanroom capital intensity for sub-100-micron handling. The Pacific Northwest cluster houses specialized SOI wafer qualification for RF applications in 5G baseband processors.
Germany
Automotive radar module manufacturers in Bavaria and Baden-Württemberg absorb premium SOI volumes for substrate isolation under ISO 26262 functional safety mandates. ECHA REACH Annex XIV restrictions on boron and phosphorus dopants force segregated process lines for European-bound lots. The Dresden semiconductor corridor anchors silicon carbide epitaxy experiments with ultra-thin carrier wafers.
Japan
MEMS pressure sensor producers for tire pressure monitoring systems source sub-50-micron device layers from Nagoya-area foundries. METI technology roadmaps prioritize plasma dicing adoption to enable thinner exit wafers without mechanical damage. The Kyushu silicon cluster maintains advanced crystal-pulling capabilities for thickness uniformity at scale.
India
Domestic packaging incentives under the PLI scheme attract thin-wafer grinding investments to Gujarat and Tamil Nadu. BIS certification requirements for semiconductor materials are aligning with international thickness tolerance standards. The Delhi-NCR corridor hosts emerging OSAT capacity targeting captive demand from smartphone processor packaging.
Thin Wafer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thickness uniformity and crystal orientation capabilities. The market structure consolidates around polysilicon-to-wafer integrated producers controlling feedstock access, with grinding and dicing services fragmenting into captive and independent tiers. Three archetypes dominate: integrated chemical conglomerates with upstream polysilicon control, specialized wafer manufacturers with advanced crystal-pulling differentiation, and equipment specialists enabling thinning and separation workflows. Competitive moves center on captive grinding capacity mandates by tier-one foundries and plasma dicing technology licensing for yield economics in 3D stacked memory.
Within the integrated chemical tier, Shin-Etsu Chemical Co., Ltd. and SUMCO Corporation exemplify polysilicon-to-wafer backward integration strategies that sustain margin capture in ultra-thin segments. Siltronic AG occupies a position representing European-based specialization under REACH compliance constraints. These three entities anchor distinct geographic supply basins while facing common pressure from foundry captive capacity absorption in South Korea and the United States.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| SUMCO Corporation |
| Siltronic AG |
| GlobalWafers Co., Ltd. |
| SK Siltron |
| Süss MicroTec AG |
| DISCO Corporation |
| LG Siltron Inc. |
| Sunedison Semiconductor Ltd. |
| Others |
Supply Flow & Price Mechanics
Polysilicon price benchmarks cascade through semiconductor-grade feedstock tiers into wafer pricing stratification, compressing margins at grinding and dicing stages while integrated producers capture upstream premiums. REACH compliance costs and captive capacity mandates at South Korean foundries reshape procurement economics across thickness specifications.
Pricing Analysis
Yield-per-wafer throughput anchors value-based pricing for sub-75-micron substrates, with breakage risk premiums separating premium uniformity grades from standard tolerance lots. Three-tier pricing structure across premium, standard, and economy levels reflects thickness uniformity certification, crystal orientation precision, and volume scale commitments. Cost compression in commodity grinding services is intensifying because OSAT consolidation shifts negotiation leverage toward packaging houses. Fabless semiconductor designers exhibit highest price sensitivity, while automotive ADAS module manufacturers absorb premiums for enhanced traceability documentation.
Supply Chain Analysis
Semiconductor-grade polysilicon supply rests on five integrated producers controlling over 80% of feedstock, tethering wafer manufacturers to allocation rationing during capacity crunches. Raw material dependencies span high-purity polysilicon, quartz crucibles for crystal pulling, and specialty doping chemistries. Geographic concentration in South Korea, Japan, and Germany creates tariff exposure from chip export control fragmentation. Distribution runs through qualified vendor lists maintained by tier-one foundries, with captive grinding capacity increasingly mandatory for advanced node access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin wafer competition has become a vertical-integration race, with polysilicon-to-wafer backward integration and captive grinding capacity serving as the primary levers for margin defense.
For Market Incumbents: Anchor market position through captive grinding capacity absorption in South Korea and advanced crystal-pulling investments for thickness uniformity at scale. Defend against plasma dicing technology displacement by licensing yield-enhancing separation workflows to HBM memory producers. Prioritize REACH-compliant process line segregation to maintain European qualification pathways amid ECHA dopant restrictions. For New Entrants and Emerging Players: Launch via India PLI scheme localization in Gujarat and Tamil Nadu packaging corridors, targeting domestic smartphone processor grinding demand. White-space opportunities concentrate in MEMS pressure sensor sub-50-micron device layers for automotive tire pressure monitoring, where specialized SOI wafer qualification requirements deter commodity competitors. Pursue joint development agreements with emerging OSATs seeking non-captive grinding alternatives. For Investors and Strategic Acquirers: The window for entry favors equipment specialists with plasma dicing and laser-assisted debonding patent portfolios. Long-term viability hinges on temporary bonding workflow convergence with glass interposer architectures for RF module applications. Watch for captive capacity absorption announcements by tier-one foundries as inflection indicators for independent grinding service valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Grinding Capacity Buildout | Samsung's packaging affiliate absorption of independent specialists since 2023 reshapes vendor leverage. |
| Plasma Dicing Technology Licensing | Yield economics for HBM4 architectures at Micron and Samsung pilot lines accelerate adoption timelines. |
| REACH-Compliant Process Segregation | ECHA Annex XIV dopant restrictions force dedicated European-bound wafer lines with enhanced documentation. |
| India PLI Scheme Localization | Domestic packaging incentives attract grinding investments to Gujarat and Tamil Nadu outside East Asian concentration. |
| Glass Interposer Convergence | Through-glass via integration with temporary bonding workflows enables hybrid RF substrate architectures. |
Methodological Framework
Multi-period observation of thickness reduction trajectories, captive capacity absorption patterns, and REACH compliance cost structures anchored the trend analysis, supplemented by interviews with semiconductor manufacturing executives, wafer procurement leads at foundries, grinding service operations managers, and ECHA regulatory affairs specialists. Secondary validation drew from SEC 10-K filings by integrated chemical conglomerates, customs trade data for polysilicon and wafer shipments, MFDS chemical safety notifications, and BIS certification records. Bottom-up segment sizing triangulated against top-down semiconductor capital expenditure forecasts.
Input-output matrices mapped polysilicon feedstock volumes through crystal pulling, grinding, and dicing stages to wafer output by thickness tier across the analysis window. Segmentation dimensions modeled included substrate composition, application category, end-use industry, thinning technology, and regional production cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating chiplet architecture penetration rates and MEMS miniaturization curves. Industry-specific forecast inputs encompassed HBM stacking layer counts and automotive pressure sensor wafer consumption per vehicle.
Chip export control expansion, polysilicon supply rationing events, and sub-50-micron handling physics breakthroughs are the dominant revision risks to thickness reduction timelines and regional demand concentration. Forecasts reflect documented assumptions about foundry qualification pacing and regulatory enforcement calendars. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Zener Diode Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Field Effect Transistor Market