
 Varactor Diode Market | 2026-2036
Varactor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Varactor Diode Market Analysis
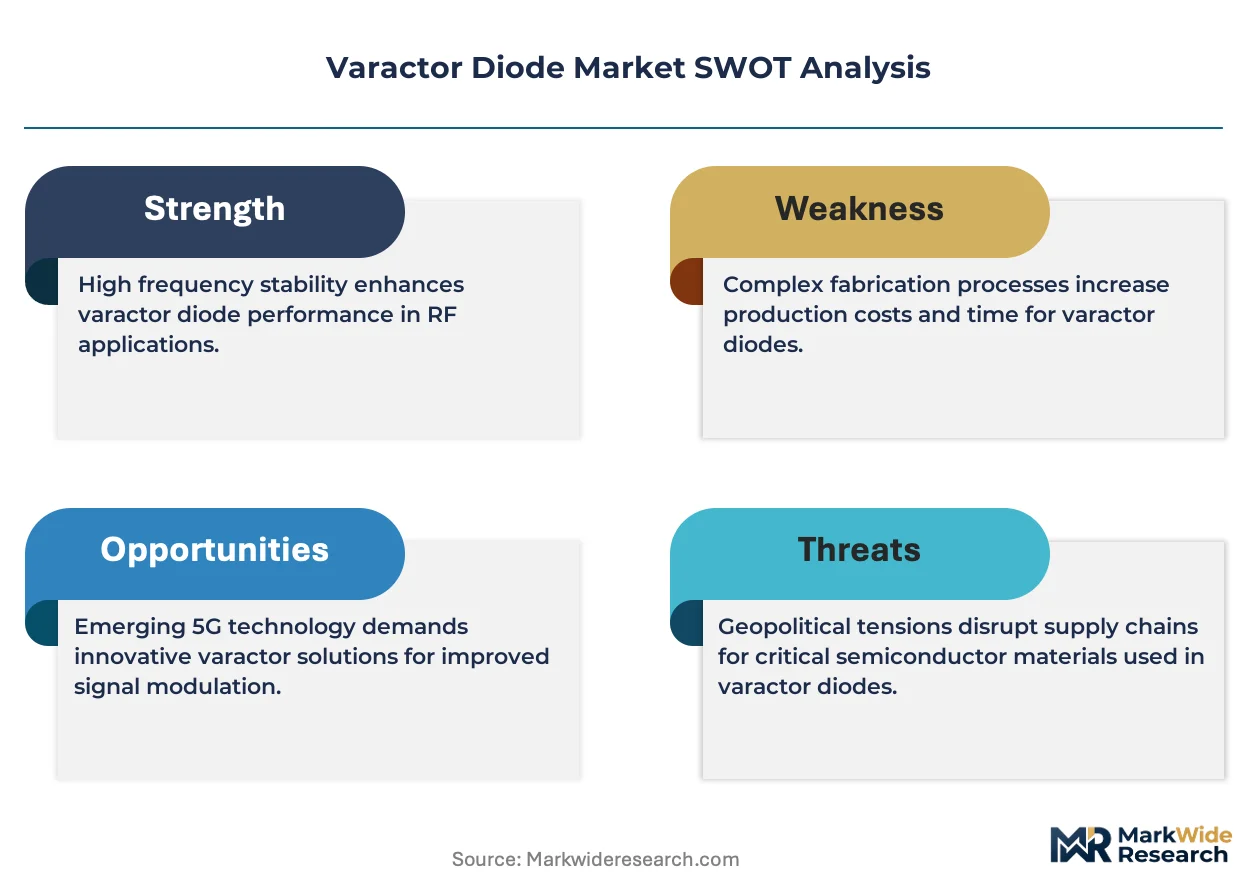
Silicon-to-GaN migration in RF front-ends is tilting procurement specifications toward wide-bandgap varactor variants. NXP Semiconductors leverages its automotive-qualified portfolio to anchor supply contracts with tier-one module makers. STMicroelectronics sustains R&D intensity across European fabrication sites for aerospace-grade tuning diodes. Infineon Technologies dominates industrial frequency-control applications through backward integration into epitaxial wafer supply.
A varactor diode functions as a voltage-controlled variable capacitor, exploiting the depletion-region width modulation in a reverse-biased p-n junction to achieve capacitance ranges typically spanning picofarads to hundreds of picofarads with tuning ratios of 2:1 to 20:1 depending on doping profile. Gallium arsenide diodes command premium positioning in millimeter-wave and satellite communications where electron mobility requirements exceed silicon physical limits. Tuning diodes retain volume leadership across consumer electronics and legacy broadcast equipment, while microwave diodes capture the fastest expansion as phased-array radar and 5G massive MIMO architectures proliferate.
FCC Part 15 emissions standards and EU RoHS substance restrictions constrain material selection and packaging formats for varactors entering North American and European equipment supply chains. ETSI harmonized spectrum regulations in the European Union mandate tighter phase-noise specifications, directly elevating demand for high-Q tuning devices. China's GB standards for telecommunications equipment impose additional domestic testing protocols that shape market access conditions for non-Chinese suppliers. Stakeholders must monitor evolving spectrum allocation decisions and corresponding diode specification cascades across major regulatory jurisdictions to align product roadmaps with compliance windows.
Market Dynamics
Silicon-to-GaN migration in RF front-ends is compressing procurement specifications across telecommunications infrastructure, forcing incumbent silicon suppliers to reposition or exit millimeter-wave segments entirely.
Growth Catalysts
- 5G Massive MIMO Deployment:Base station architects require voltage-controlled capacitors with wider tuning ranges, pulling GaN varactors into macro-cell designs previously served by silicon.
- EU RoHS Substance Mandates:Lead-free packaging requirements are accelerating qualification of new metallization processes for automotive-qualified tuning diodes.
- Phased-Array Radar Proliferation:Defense and satellite communication programs in South Korea and Germany are specifying high-Q microwave varactors for electronically steerable antennas.
Market Restraints
- Epitaxial Wafer Supply Concentration:China and Japan control over seventy percent of GaN-on-SiC substrate capacity, creating chokepoint vulnerability for non-integrated diode manufacturers.
- Electron Beam Lithography Cost Structure:Sub-micron junction patterning for millimeter-wave devices requires capital-intensive equipment with depreciation cycles exceeding five years.
- Silicon Carbide Defect Density:Micropipe and dislocation rates in 150mm substrates limit yield for high-voltage varactor arrays in industrial frequency synthesizers.
Strategic Opportunities
- India Telecom Infrastructure Buildout:TRAI spectrum auctions and domestic PLI scheme incentives are creating first-mover openings for GaN diode suppliers establishing local packaging operations.
- Automotive Radar Frequency Extension:79GHz band allocation for short-range radar in European and Chinese vehicle platforms is expanding addressable market for GaAs tuning devices.
- AI-Driven Impedance Matching:Machine learning algorithms optimizing bias voltage in real-time are converging with varactor control circuits to enable adaptive antenna systems.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:GaN and GaAs device physics expertise concentrates in legacy defense contractors and IDMs, constraining fabless startup scaling.
- Aerospace Qualification Timelines:MIL-PRF-19500 and ESA SCC specifications require eighteen-to-thirty-six month test cycles before flight heritage approval.
- Legacy Broadcast Equipment Support:End-of-life silicon varactor lines must be maintained for AM/FM tuner replacement markets with shrinking volume economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Varactor Diode Market |
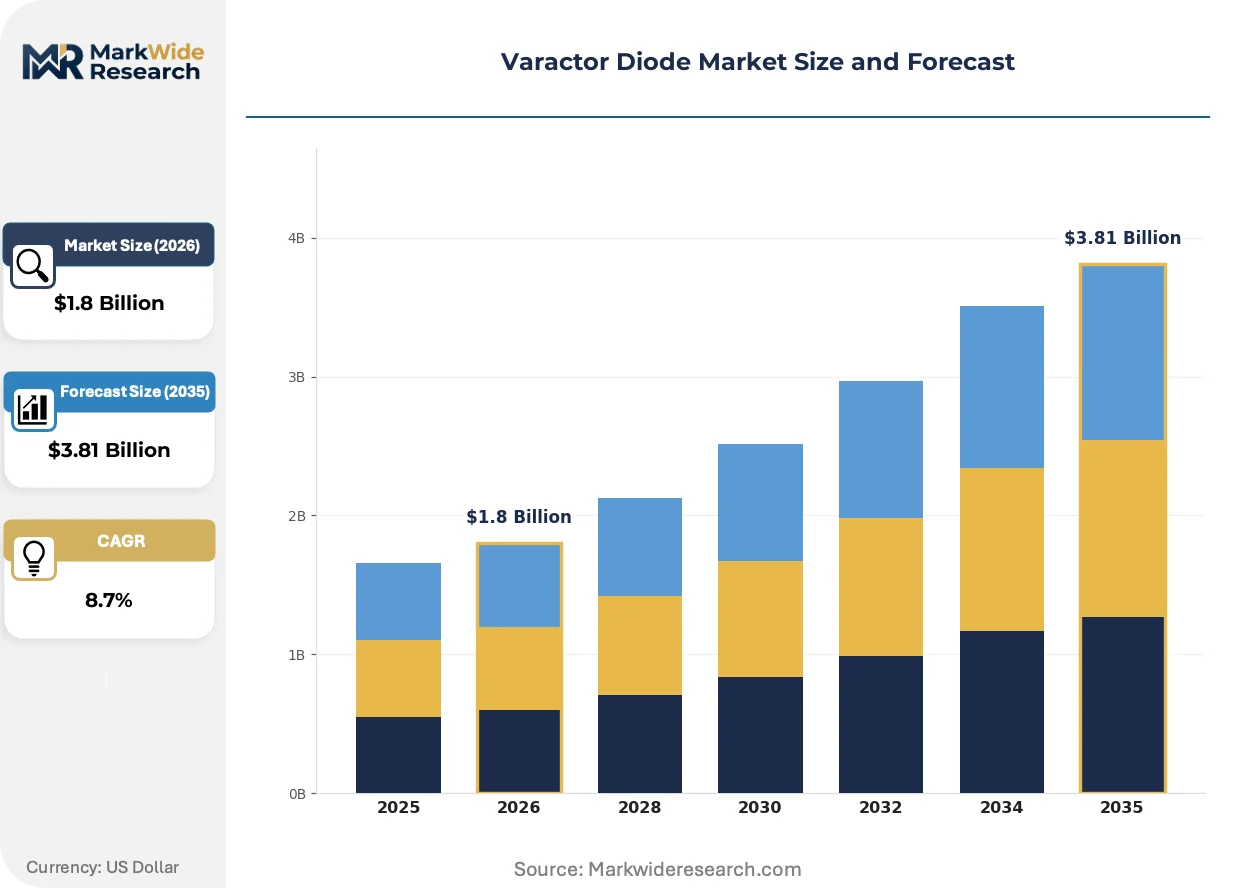
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuning Diodes, Voltage-Controlled Capacitors, RF Diodes, Microwave Diodes End User: Telecommunications, Consumer Electronics, Aerospace, Automotive Technology: Silicon Diodes, Gallium Arsenide Diodes, Schottky Diodes, Integrated Diodes Application: Frequency Modulation, Phase-Locked Loops, Signal Processing, Electronic Tuning |
| Companies Covered | NXP Semiconductors, STMicroelectronics, MACOM, Vishay Intertechnology, ON Semiconductor, Infineon Technologies, Skyworks Solutions, Analog Devices, Toshiba Electronic Devices & Storage Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Varactor Diode Market Emerging Trajectories
Process node migration and packaging innovation are redefining performance boundaries for voltage-variable capacitors, with material science advances outpacing traditional junction engineering approaches.
Gallium nitride epitaxy on silicon substrates is collapsing the cost barrier between consumer-grade silicon varactors and premium GaN-on-SiC devices. Smartphone antenna tuner suppliers in China are now sampling GaN-on-Si diodes for sub-6GHz 5G bands, compressing the price premium from ten-to-one to roughly three-to-one against legacy silicon solutions. This substrate shift is collapsing the historical segmentation between industrial and consumer RF component supply chains.
ETSI harmonized spectrum regulations mandating tighter phase-noise specifications for base station equipment are elevating demand for high-Q tuning devices. European equipment manufacturers must now demonstrate compliance with EN 301 908 series standards for UMTS and LTE infrastructure, forcing diode suppliers to redesign doping profiles for reduced series resistance. The aerospace and satellite communication segment is most affected, with prime contractors now requiring Q-factors above 3000 at 1GHz for space-qualified varactors.
Module makers are consolidating supplier relationships around vertically integrated diode-wafer vendors capable of delivering epitaxial material, device fabrication, and packaged components under single-source contracts. This buyer concentration is displacing traditional merchant semiconductor distributors in millimeter-wave procurement channels. The shift is most visible in South Korea, where Samsung and LG base station divisions have reduced qualified varactor suppliers from twelve to four vendors over the past qualification cycle.
Varactor Diode Market Segmentation
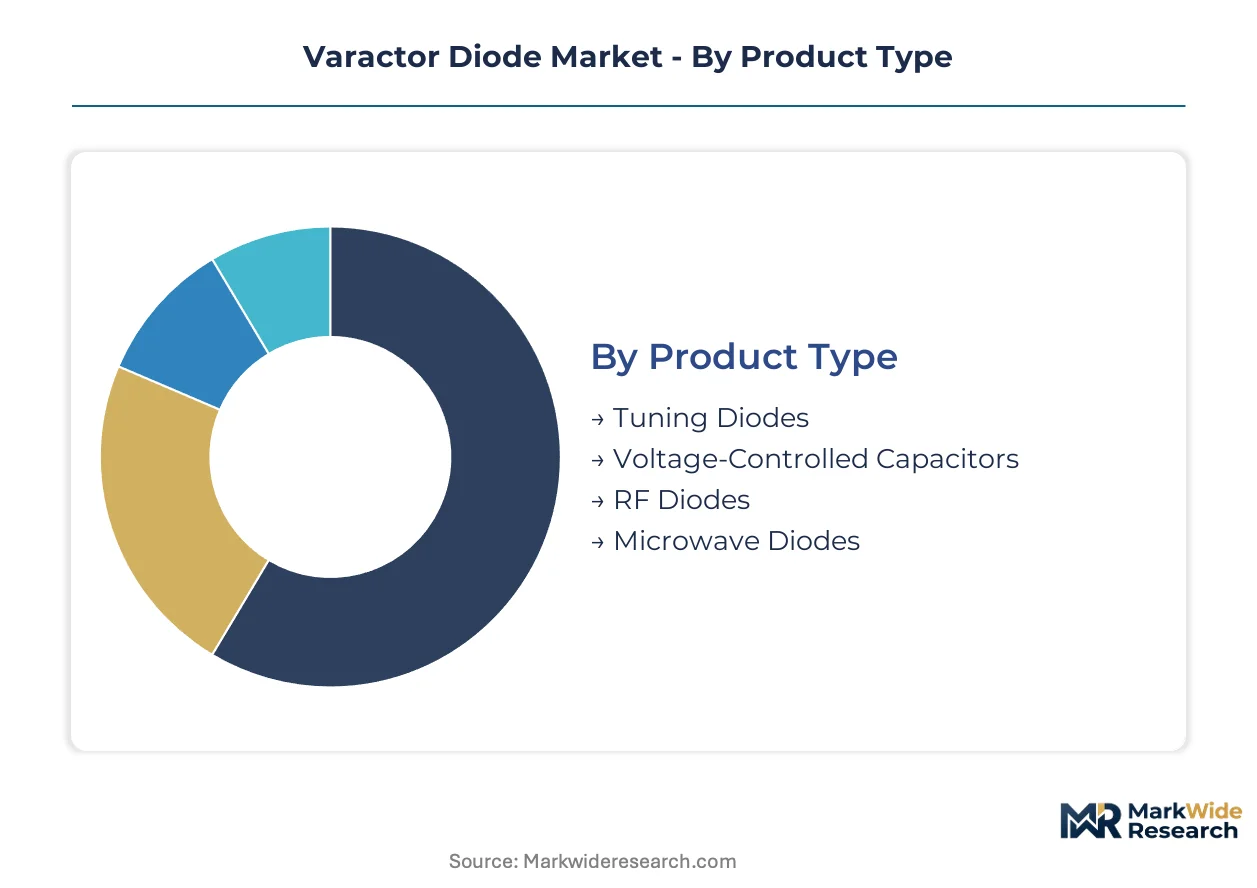
Varactor diode procurement patterns diverge sharply across product architectures and end-use environments. Component specifications cascade differently through telecommunications infrastructure versus automotive radar modules. Technology selection and application requirements further stratify supplier relationships and qualification protocols.
Product Type:
Cost tier separation between legacy silicon-based products and wide-bandgap alternatives defines competitive positioning across this dimension.
- Tuning Diodes:These devices leverage abrupt or hyperabrupt junction profiles to achieve capacitance variation ratios from 2:1 to 20:1 across reverse bias ranges. Broadcast receiver and AM/FM tuner replacement markets in Germany and Japan sustain volume demand despite terminal decline in new design wins.
- Voltage-Controlled Capacitors:Functionally equivalent to tuning diodes but packaged for surface-mount assembly with integrated bias networks. 5G massive MIMO base stations in South Korea specify these for automated impedance matching in phased-array front-ends.
- RF Diodes:Optimized for sub-6GHz operation with emphasis on low series resistance and minimal parasitic inductance.
- Microwave Diodes:Engineered for millimeter-wave frequencies through sub-micron junction geometries and GaAs or GaN material platforms.
Tuning diodes command the established base. The steepest expansion runs through microwave diodes.
End User:
Application maturity and qualification intensity create divergent margin structures across customer categories.
- Telecommunications:Base station OEMs in China and South Korea dominate procurement volumes for sub-6GHz and millimeter-wave infrastructure. FCC Part 15 emissions standards and ETSI EN 301 908 phase-noise specifications constrain supplier eligibility for North American and European network equipment.
- Consumer Electronics:Smartphone antenna tuner integration drives demand for ultra-miniature surface-mount packages with automated bias calibration.
- Aerospace:Satellite communication payloads and electronically steerable arrays require MIL-PRF-19500 or ESA SCC qualification with eighteen-to-thirty-six month test cycles.
- Automotive:79GHz short-range radar modules for European and Chinese vehicle platforms specify GaAs tuning devices with AEC-Q101 automotive qualification.
Telecommunications anchors volume procurement. Aerospace captures premium pricing through qualification barriers.
Technology:
Material platform selection determines frequency ceiling, power handling, and integration compatibility with surrounding RF circuitry.
- Silicon Diodes:Dominant in cost-sensitive applications below 3GHz through mature CMOS-compatible fabrication. Consumer electronics and legacy broadcast equipment sustain residual demand despite performance limitations at higher frequencies.
- Gallium Arsenide Diodes:Electron mobility advantages enable operation through millimeter-wave bands with superior noise performance. Satellite communication and defense radar programs in Germany and South Korea specify these for Q-factors exceeding 3000 at 1GHz.
- Schottky Diodes:Metal-semiconductor junction architecture delivers faster switching and lower forward voltage drop than p-n alternatives.
- Integrated Diodes:Monolithic integration with bias control circuitry and temperature compensation networks simplifies system-level design.
Silicon diodes retain the volume foundation. Gallium arsenide variants are climbing the fastest through 5G and satellite deployment.
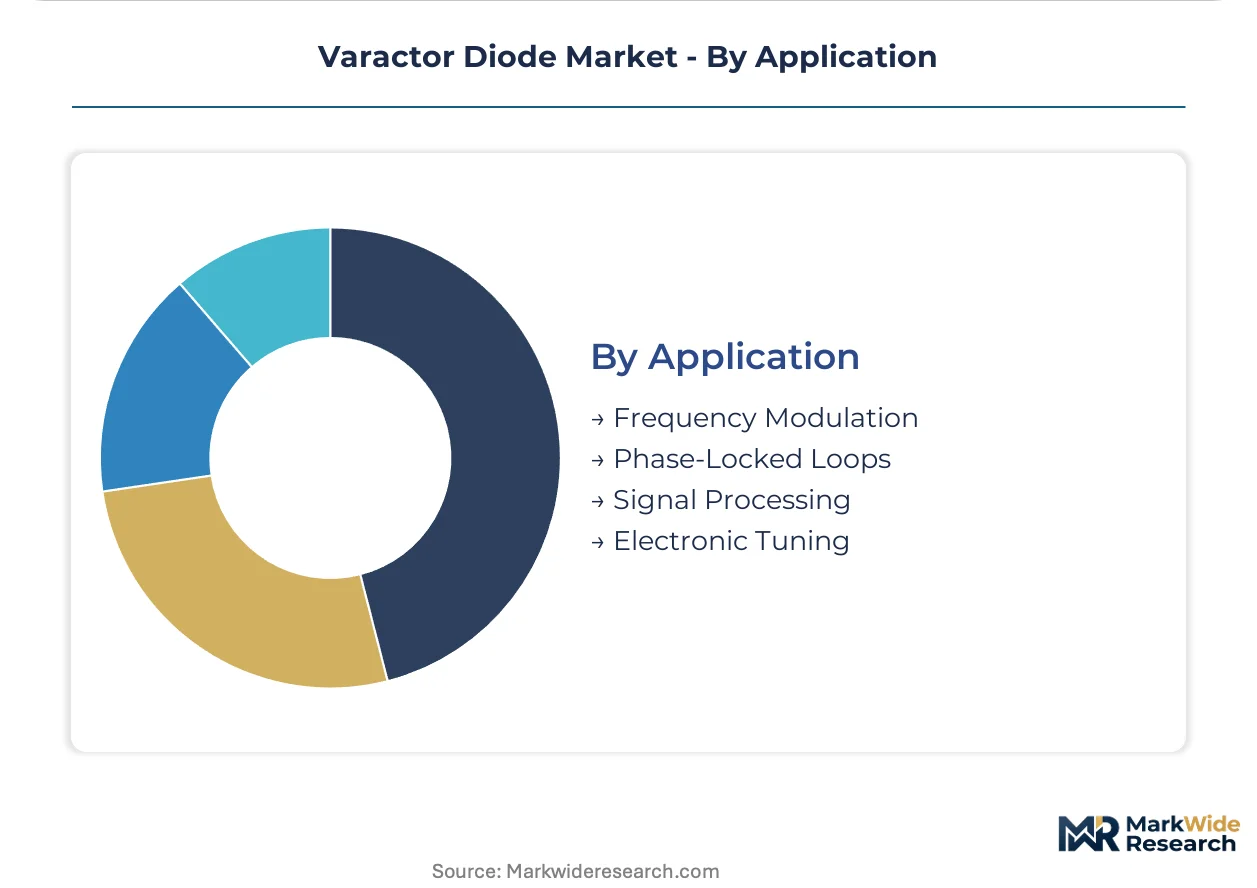
Application:
Functional use case dictates specification priorities ranging from tuning linearity to phase-noise contribution and thermal stability.
- Frequency Modulation:Voltage-controlled oscillators in FM broadcast transmitters and two-way radio equipment depend on tuning linearity and low distortion. Regulatory constraints from FCC and ETSI on adjacent-channel interference elevate specification thresholds for new designs.
- Phase-Locked Loops:Synthesizer applications require minimal tuning hysteresis and stable capacitance-voltage characteristics across temperature extremes. China's GB standards for telecommunications equipment impose domestic testing protocols affecting non-Chinese supplier market access.
- Signal Processing:Variable filter and equalizer implementations exploit capacitance range for adaptive bandwidth control.
- Electronic Tuning:Antenna matching networks and resonant circuit adjustment leverage real-time bias control for impedance optimization.
Frequency modulation holds the installed base. Phase-locked loops are gaining share fastest through 5G infrastructure timing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in wide-bandgap substrates are redrawing procurement geography for varactor diode manufacturers. China and Japan control over seventy percent of GaN-on-SiC substrate capacity, forcing European and North American module makers to secure long-term supply agreements or accelerate domestic epitaxial growth investments.
China
MIIT's 5G base station deployment targets and domestic semiconductor self-sufficiency mandates under the dual carbon goals are pulling GaN varactors into macro-cell infrastructure. GB standards for telecommunications equipment impose additional testing protocols that shape market access for non-Chinese suppliers. Shanghai and Shenzhen clusters host integrated diode-wafer vendors delivering epitaxial material through packaged components under single-source contracts.
South Korea
Samsung and LG base station divisions have consolidated qualified varactor suppliers from twelve to four vendors, concentrating procurement around vertically integrated partners. MFDS spectrum allocation decisions for 28GHz and 39GHz bands are cascading into tighter phase-noise specifications for 5G massive MIMO architectures. The Busan-Ulsan industrial corridor anchors defense and satellite communication programs specifying high-Q microwave varactors for electronically steerable antennas.
Germany
Automotive radar frequency extension to 79GHz for short-range sensing is expanding addressable market for GaAs tuning devices with AEC-Q101 qualification. EU RoHS substance mandates and ETSI EN 301 908 phase-noise specifications constrain supplier eligibility for European network equipment. Bavaria's aerospace and satellite communication prime contractors now require Q-factors above 3000 at 1GHz for space-qualified varactors under ESA SCC protocols.
United States
FCC Part 15 emissions standards constrain material selection and packaging formats for varactors entering North American equipment supply chains. Defense phased-array radar programs are specifying high-Q microwave varactors for millimeter-wave operation. The Greater Boston and Pacific Northwest clusters host fabless startups constrained by compound semiconductor process engineering talent concentration in legacy defense contractors.
India
TRAI spectrum auctions and domestic PLI scheme incentives are creating first-mover openings for GaN diode suppliers establishing local packaging operations. BIS certification requirements for telecommunications equipment are shaping import substitution strategies for base station components. The Delhi-NCR and Karnataka clusters are emerging as assembly and test locations for voltage-controlled capacitors targeting sub-6GHz 5G infrastructure buildout.
Varactor Diode Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated diode-wafer vendors capable of delivering epitaxial material, device fabrication, and packaged components under single-source contracts. Merchant semiconductor distributors are losing position in millimeter-wave procurement channels as module makers reduce qualified supplier lists. Three archetypes dominate: IDMs with captive substrate supply, fabless specialists licensing process technology, and foundry-integrated packaging houses. Competitive moves center on backward integration into epitaxial wafer supply and geographic expansion through local packaging operations in India and Southeast Asia.
Among European IDMs, NXP Semiconductors, STMicroelectronics, and Infineon Technologies occupy positions across automotive-qualified and aerospace-grade tuning diode segments. These Netherlands-based, Swiss-Italian, and German entities exemplify the vertically integrated archetype through in-house production of epitaxial material. Their geographic concentration in European fabrication sites aligns with ETSI harmonized spectrum regulations and EU RoHS compliance requirements for regional equipment manufacturers.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| MACOM |
| Vishay Intertechnology |
| ON Semiconductor |
| Infineon Technologies |
| Skyworks Solutions |
| Analog Devices |
| Toshiba Electronic Devices & Storage Corporation |
| Others |
Supply Flow & Price Mechanics
GaN-on-SiC substrate chokepoint exposure in China and Japan determines both tiered pricing spreads between silicon and wide-bandgap varactors and the geographic shape of supplier qualification protocols. FCC Part 15 and ETSI EN 301 908 compliance costs cascade into premium positioning for automotive-qualified and aerospace-grade devices.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium GaN microwave diodes command spreads against silicon based on Q-factor performance and MIL-PRF-19500 qualification status. Cost compression in consumer-grade silicon varactors intensifies as GaN-on-Si substrates collapse historical material premiums. Smartphone antenna tuner suppliers exhibit highest price sensitivity; defense prime contractors show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
TSMC, GlobalFoundries, and domestic Chinese foundries hold compound semiconductor capacity for varactor fabrication. Epitaxial wafer supply draws from China, Japan, and Germany for substrate preparation and doping services. Raw material dependencies center on high-purity gallium, silicon carbide boules, and specialized metallization precursors. Single-source vulnerability concentrates in 150mm SiC substrate supply. Distribution runs through vertically integrated diode-wafer vendors delivering single-source contracts to base station OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Varactor diode procurement is shifting toward service-attach models where calibration, temperature compensation firmware, and field-replacement programs expand faster than discrete component sales. Recurring revenue from bias-network integration and automated impedance matching software outpaces hardware growth trajectories.
For Market Incumbents: Build captive epitaxial supply moats through backward integration into GaN-on-SiC substrate production. Infineon Technologies exemplifies this through in-house wafer supply for industrial frequency-control applications. Defend against fabless startup encroachment by accelerating AEC-Q101 and ESA SCC qualification pipelines. Channel control through direct OEM contracts displaces merchant distributors in millimeter-wave segments. For New Entrants and Emerging Players: Establish a beachhead in India's sub-6GHz 5G infrastructure buildout where TRAI spectrum auctions and PLI scheme incentives reduce incumbent lock-in. Target voltage-controlled capacitor packaging operations in Delhi-NCR and Karnataka clusters. GaN-on-Si substrate sourcing from Chinese vendors enables cost-competitive positioning against legacy silicon solutions. Go-to-market through local EMS partnerships bypasses established single-source contract barriers. For Investors and Strategic Acquirers: EU RoHS substance mandates and ETSI harmonized spectrum regulations reshape the acquisition landscape toward lead-free packaging and high-Q device capabilities. Long-term viability centers on compound semiconductor process engineering talent pools concentrated in legacy defense contractors and European IDMs. Acquisition targets include fabless specialists with GaN epitaxy licenses and Indian packaging operations. Monitor BIS certification requirements and domestic content thresholds as inflection signals for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Captive GaN-on-SiC substrate production secures qualification pipelines for aerospace-grade varactors. |
| India Local Packaging Operations | TRAI spectrum allocations and PLI incentives create first-mover positioning in sub-6GHz infrastructure. |
| AEC-Q101 Automotive Qualification | 79GHz radar frequency extension in European and Chinese vehicles expands addressable market for GaAs devices. |
| High-Q Microwave Diode R&D Investment | ETSI EN 301 908 phase-noise specifications elevate demand for Q-factors exceeding 3000 at 1GHz. |
| AI-Driven Impedance Matching Integration | Machine learning bias optimization enables adaptive antenna systems with recurring firmware revenue. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, and telecommunications equipment certification databases. Base station OEM procurement directors, compound semiconductor process engineers, and automotive radar module architects contributed structured interviews. Secondary validation drew from FCC Part 15 emissions filings, ETSI EN 301 908 compliance records, and MIIT 5G deployment disclosures. Bottom-up varactor shipment analysis triangulates against top-down infrastructure capex tracking.
Forecast inputs span product type segmentation across tuning diodes and microwave variants, technology platforms from silicon through GaN, and end-use categories including telecommunications infrastructure and automotive radar. Deployment intensity across China's MIIT targets, South Korea's MFDS spectrum allocations, and India's TRAI auctions anchors volume projections. CAGRs derive from equipment installation curves and content-per-unit assumptions across phased-array architectures.
Stress conditions across GaN-on-SiC substrate availability, electron beam lithography capacity constraints, and aerospace qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding 5G massive MIMO deployment cadence and defense radar program continuity. Quarterly review of BIS certification progress, PLI scheme disbursement rates, and ESA SCC qualification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Automotive Grade Emmc Market