
 Finfet Technology Market | 2026-2036
Finfet Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Finfet Technology Market Intelligence
Access to proprietary Process Design Kits (PDKs) for advanced nodes is hardening the relationship between foundries and fabless design houses. TSMC Limited leverages its massive manufacturing scale and ecosystem to maintain leadership in 7nm and 5nm process technologies. Samsung Electronics competes aggressively on both process technology and advanced packaging solutions. Intel Corporation is re-entering the foundry market with significant capital investment to attract external chip design clients.
FinFET, or Fin Field-Effect Transistor, is a non-planar, multi-gate transistor architecture built on a silicon substrate. Its three-dimensional 'fin' structure provides superior channel control, which significantly reduces short-channel effects and leakage current. The 7nm and 5nm process technology nodes currently represent the most advanced, high-volume manufacturing segments. Demand from fabless companies for mobile processors and high-performance computing applications drives volume in these leading-edge nodes.
National industrial policies, including the US CHIPS Act and the European Chips Act, are reshaping capital investment flows and foundry construction. Export control regimes administered by entities like the US Department of Commerce's Bureau of Industry and Security restrict technology transfer and equipment sales. Navigating these geopolitical influences to secure access to leading-edge foundry capacity is now a primary strategic concern for all semiconductor firms.
Market Dynamics
The FinFET technology landscape is defined by the strategic tension between national industrial policies aiming to onshore production and the deeply concentrated nature of leading-edge foundry capacity. This dynamic forces fabless companies to navigate geopolitical risks to secure manufacturing access.
Growth Catalysts
- High-Performance Computing Demand:The proliferation of artificial intelligence accelerators and data center processors requires the superior performance and power efficiency delivered by advanced FinFET nodes, driving volume production at the 7nm and 5nm levels.
- Process Node Advancement:Continuous innovation in lithography and materials science enables the transition to smaller, more powerful process nodes, sustaining the economic and performance incentives for fabless firms to migrate their designs.
- National Industrial Policy:Government initiatives, including the US CHIPS Act and the European Chips Act, provide substantial subsidies and incentives for the construction of new, geographically diverse semiconductor foundries, expanding future capacity.
Market Restraints
- Extreme Capital Expenditure:The cost of building and equipping a leading-edge foundry exceeds tens of billions of dollars, creating an exceptionally high barrier to entry and reinforcing the market concentration among a few dominant players.
- Physical Scaling Limits:As transistors approach atomic scales, short-channel effects and quantum tunneling present fundamental physics-based barriers, increasing the research and development costs required to advance to sub-3nm architectures like Gate-All-Around.
- Geopolitical Supply Risk:Heavy concentration of advanced node manufacturing in Taiwan and South Korea exposes the global semiconductor supply chain to significant disruption from regional political instability and trade disputes.
Strategic Opportunities
- Advanced Packaging Integration:The convergence of FinFET logic with 2.5D and 3D advanced packaging technologies creates opportunities to build powerful, heterogeneous systems-in-package, bypassing the challenges of monolithic die scaling for certain applications.
- New End-Market Penetration:Growth in automotive electronics for autonomous driving and the expansion of edge AI in consumer and industrial devices opens new volume markets for mature and specialized FinFET process technologies.
- Foundry Diversification:Capital investments spurred by national security concerns are creating opportunities for new foundry players and geographic locations, particularly in the United States and Europe, to capture market share from incumbents.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of engineers with expertise in semiconductor process technology, extreme ultraviolet (EUV) lithography, and advanced materials science constrains the pace of both research and manufacturing expansion.
- PDK Access and IP Control:Increasingly restrictive access to proprietary Process Design Kits (PDKs) from leading foundries creates a challenge for smaller fabless companies and startups, hardening relationships and limiting design flexibility.
- Export Control Complexity:Navigating complex and evolving export control regimes, such as those administered by the US Department of Commerce, requires significant legal and compliance resources, creating operational friction for all firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finfet Technology Market |
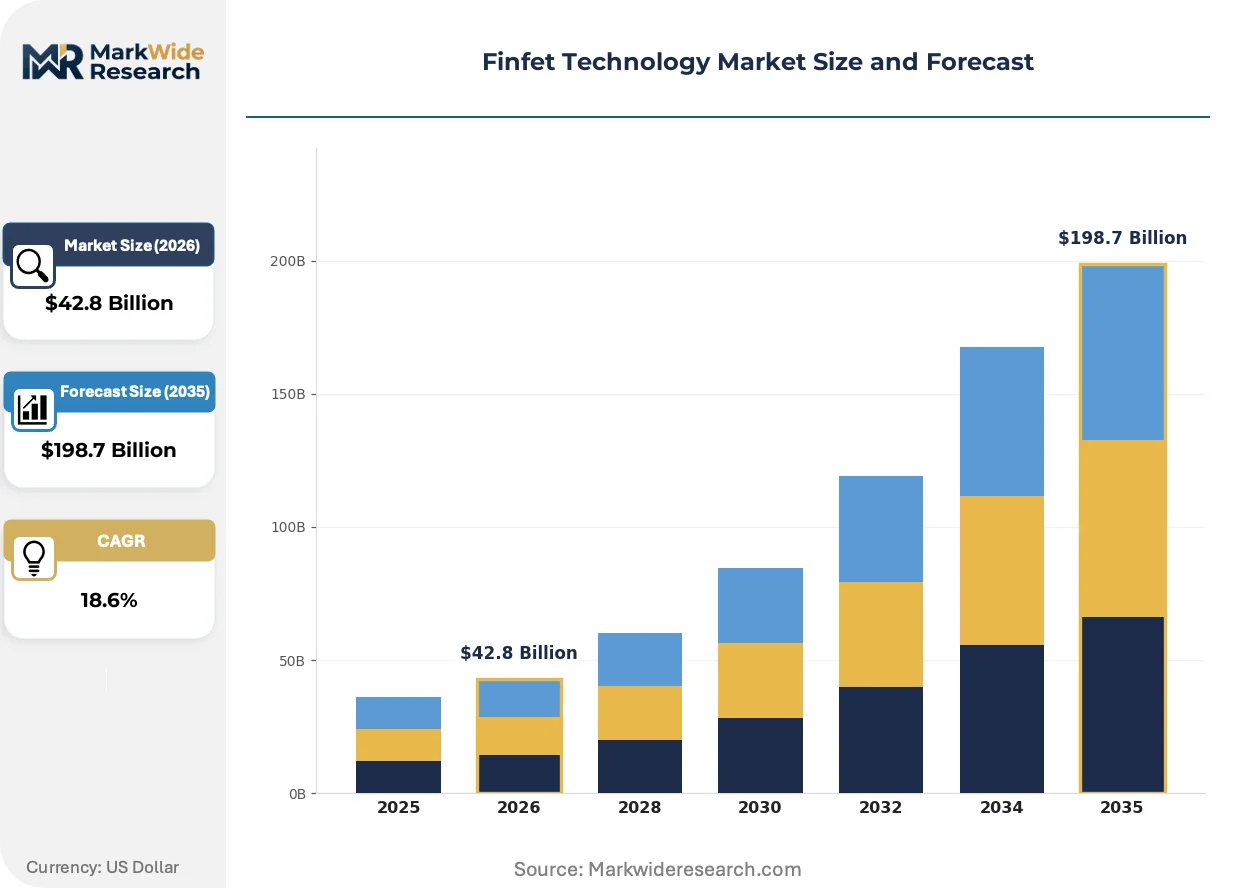
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $198.7 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Mobile Processors, High-Performance Computing, Embedded Systems, Automotive Electronics, IoT Devices Process Technology: 5nm, 7nm, 10nm, 14nm, 22nm Application: Consumer Electronics, Telecommunication Infrastructure, Aerospace Systems, Industrial Automation, Wearable Technology End User: Semiconductor Manufacturers, Fabless Companies, Foundries, Electronic Design Houses |
| Companies Covered | TSMC Limited, Samsung Electronics, Intel Corporation, GlobalFoundries Inc., Semiconductor Manufacturing International Corporation, Infineon Technologies AG, NXP Semiconductors, Renesas Electronics Corporation, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finfet Technology Market Strategic Shifts & Innovations
The market is pivoting from pure transistor scaling to architectural and packaging innovations to sustain performance improvements. This shift emphasizes co-design between fabless companies and foundries, redefining the value chain beyond simple wafer manufacturing services.
Chiplet-based design is a key architectural evolution. These small, modular dies perform specific functions and are integrated within a single package. High-performance computing and server CPU designers are the primary adopters of this approach. This trend is modularizing system-on-chip design, enabling the flexible combination of IP blocks manufactured on different process nodes to optimize cost and performance.
National security-driven regulations are directly influencing technology access and supply chain strategy. The US Department of Commerce's Bureau of Industry and Security (BIS) administers export controls that restrict the sale of advanced semiconductor manufacturing equipment and related technologies. This action creates a bifurcated technology ecosystem, forcing affected entities in China to invest heavily in domestic alternatives. The high-performance computing segment is most impacted by these controls.
A fundamental shift in engagement models is underway between foundries and their largest customers. Fabless companies are increasingly pursuing deep co-design partnerships that extend beyond standard wafer procurement. This model displaces the traditional arms-length transactional relationship with collaborative development on process technology customization and advanced packaging integration. This is most evident in the AI accelerator and flagship smartphone processor markets, where tight hardware-software optimization is critical.
Finfet Technology Market Segmentation
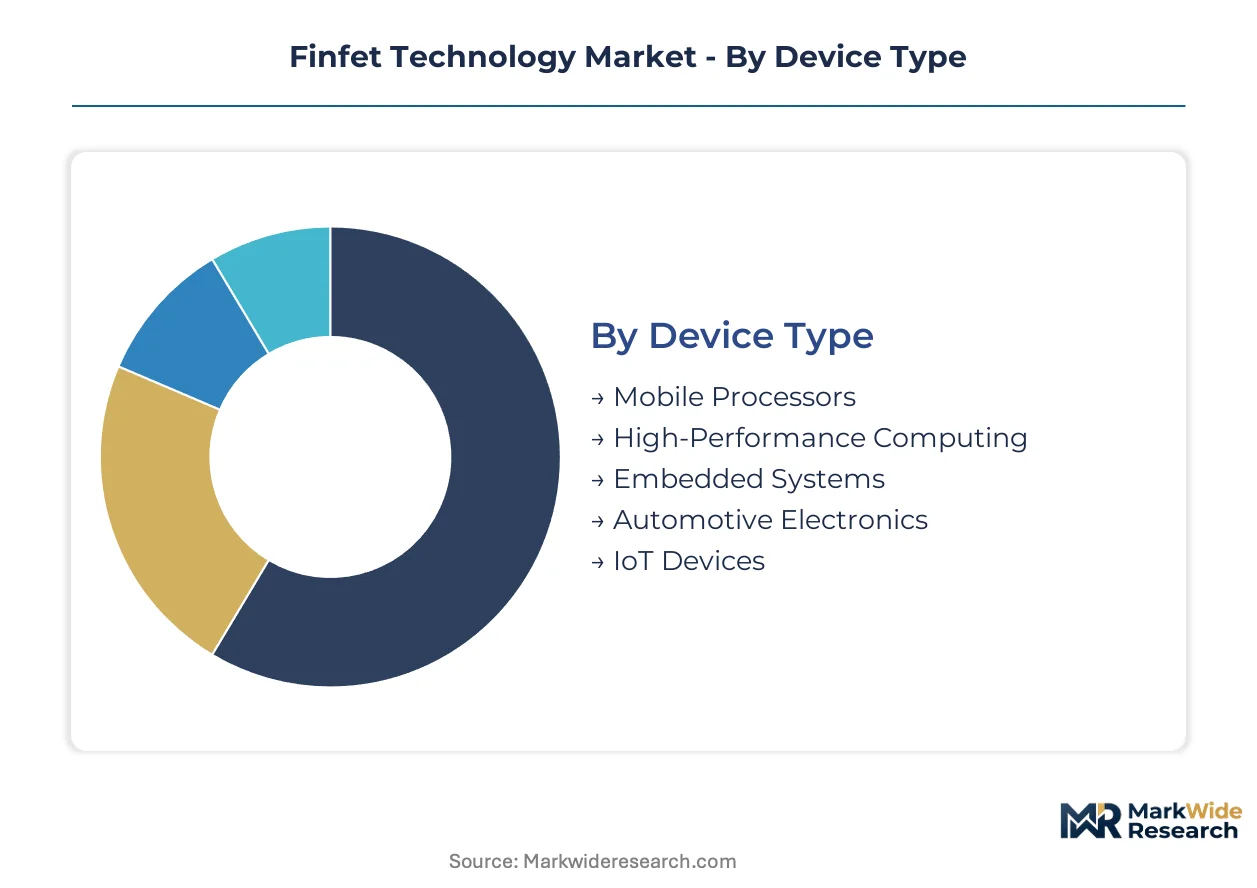
Understanding the FinFET technology market through segmentation reveals the nuanced interplay of innovation cycles and diverse application demands. This granular analysis highlights where advanced transistor architectures deliver critical performance advantages. It also pinpoints the specific end-user requirements driving investment in next-generation process nodes.
Device Type:
The upgrade cycle for device types significantly influences FinFET demand, as new product generations consistently require enhanced processing capabilities.
- High-Performance Computing:These devices integrate complex FinFET-based processors for parallel data processing and large-scale computations. Demand concentrates in data centers and scientific research facilities, driven by the need for faster AI model training and complex simulations.
- Mobile Processors:These integrated circuits power smartphones and tablets, leveraging FinFET's efficiency for extended battery life and compact design. Volume demand stems from flagship smartphone releases and the continuous consumer upgrade cycle in major Asian markets.
- Embedded Systems:These specialized controllers utilize FinFETs for reliable, low-power operation in industrial and consumer devices.
- Automotive Electronics:Advanced driver-assistance systems (ADAS) and infotainment units increasingly adopt FinFET designs for processing power and safety-critical functions.
- IoT Devices:FinFET technology supports low-power, high-integration requirements for smart sensors and connected devices across various industries.
Volume placements concentrate in Mobile Processors; the faster expansion belongs to High-Performance Computing.
Process Technology:
The maturity of FinFET process technologies dictates their applicability and cost-effectiveness across various product generations.
- 5nm:This represents the current leading-edge FinFET process node, offering maximum transistor density and performance. Demand comes from premium smartphone processors and advanced AI accelerators requiring ultimate power efficiency.
- 7nm:A highly mature and high-volume FinFET node, providing an optimal balance of cost, performance, and power consumption. Major applications include high-end CPUs, GPUs, and networking chips for data centers.
- 10nm:This node serves as a cost-effective option for a range of mid-tier and specialized computing applications.
- 14nm:A well-established process technology, widely adopted for mainstream processors, FPGAs, and certain automotive components.
- 22nm:This older FinFET node finds continued use in power-sensitive and cost-optimized embedded applications.
While 7nm maintains significant volume, the 5nm process technology is climbing the fastest in terms of advanced design wins.
Application:
FinFET technology finds diverse applications across various industries, each presenting unique performance and power requirements.
- Consumer Electronics:This segment includes smartphones, laptops, and gaming consoles, where FinFET enables powerful, energy-efficient processors. Demand is global, driven by continuous innovation in personal devices and multimedia capabilities.
- Telecommunication Infrastructure:FinFETs power base stations, network routers, and 5G equipment, requiring high-speed data processing and reliability. Investment in this area is driven by global 5G rollout and increasing data traffic demands.
- Aerospace Systems:FinFETs are integrated into mission-critical avionics and satellite communication systems for robust performance.
- Industrial Automation:FinFET-based microcontrollers and sensors enhance precision and efficiency in smart factories and robotic systems.
- Wearable Technology:FinFET's low power consumption is crucial for compact, long-lasting smartwatches and health monitoring devices.
Consumer Electronics represents the largest application segment, while Telecommunication Infrastructure shows the steepest expansion trajectory.
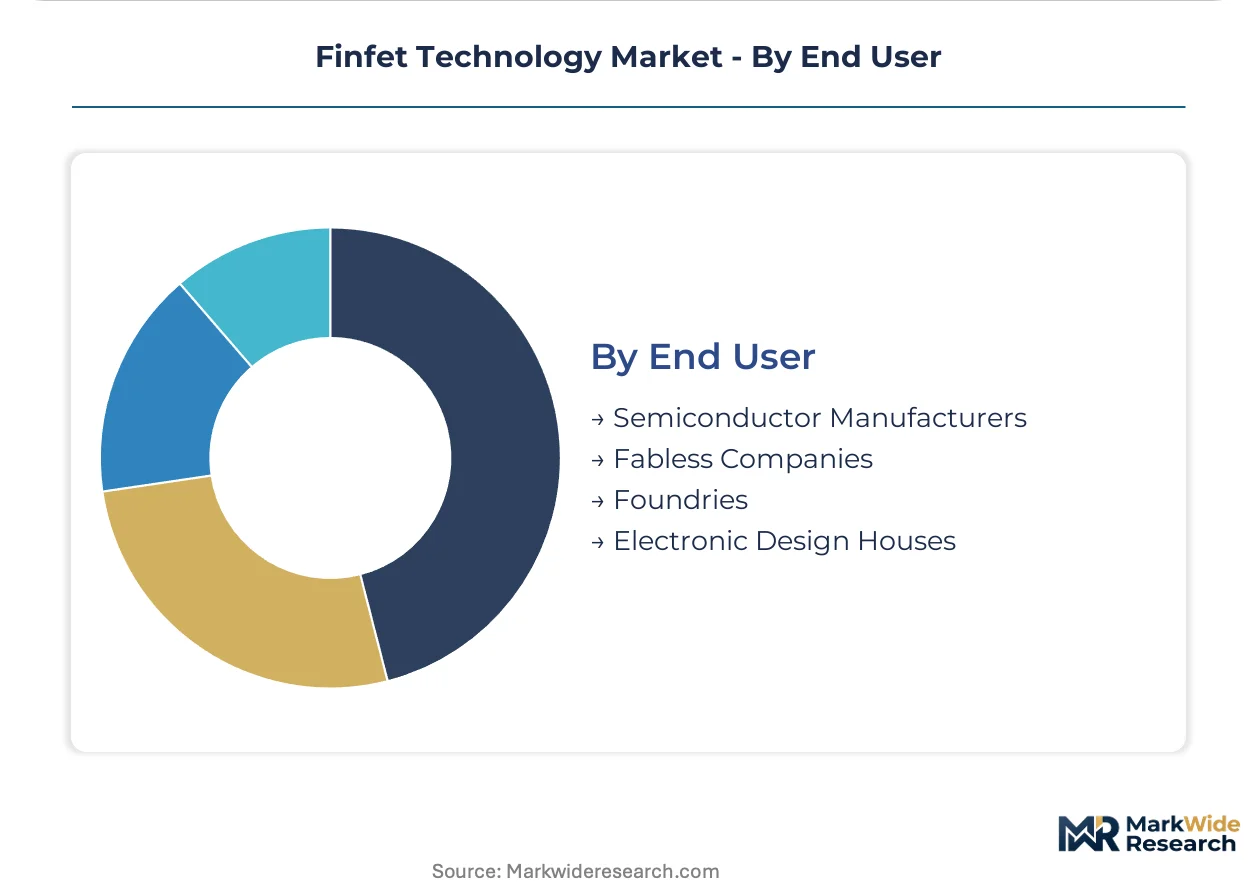
End User:
The concentration of leading-edge FinFET manufacturing among specific end-user types shapes the industry's supply dynamics and strategic alliances.
- Foundries:These are specialized manufacturers that produce chips for other companies, leveraging massive capital investments in FinFET process technology. Their demand is driven by the need to provide leading-edge manufacturing services to a global client base.
- Fabless Companies:These firms design chips but outsource manufacturing to foundries, relying on FinFET advancements for competitive product differentiation. Their focus is on intellectual property development and market penetration, particularly in high-growth segments.
- Semiconductor Manufacturers:These integrated device manufacturers (IDMs) design and produce their own FinFET-based chips for various markets.
- Electronic Design Houses:These companies provide specialized design services and IP blocks, supporting the integration of FinFET technology into complex systems.
While Foundries control the manufacturing capacity, Fabless Companies are gaining share fastest in terms of design innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan concentrates significant FinFET research and manufacturing. This region drives global innovation in advanced process nodes for high-performance computing. Foundry capacity for leading-edge FinFET technology remains heavily centralized, creating strategic dependencies worldwide.
Taiwan
Taiwan's FinFET market thrives on demand from global mobile processor and AI accelerator designers. Government initiatives actively support advanced semiconductor manufacturing capabilities. Hsinchu Science Park remains a critical hub for leading-edge foundry production and process technology development.
South Korea
South Korea sees strong FinFET demand for high-performance computing and advanced memory integration. The government implements policies to bolster domestic semiconductor competitiveness and R&D. Gyeonggi Province hosts major foundries pushing the boundaries of 5nm and sub-3nm process technologies.
United States
The United States drives FinFET demand for data center processors and artificial intelligence accelerators. The US CHIPS Act provides significant incentives for domestic foundry construction and technology development. Arizona is emerging as a new center for advanced semiconductor manufacturing investments.
Germany
Germany's FinFET market is propelled by robust automotive electronics and industrial automation sectors. The European Chips Act aims to expand regional semiconductor production and supply chain resilience. Dresden's Silicon Saxony cluster continues to attract investments in advanced manufacturing facilities.
China
China's FinFET demand focuses on developing domestic alternatives for high-performance computing and consumer electronics. National industrial policies prioritize self-sufficiency in advanced semiconductor manufacturing capabilities. The Yangtze River Delta region is investing heavily in local process technology innovation.
Finfet Technology Market Key Industry Players
Capital-heavy foundries compete with asset-light fabless design houses for FinFET market dominance. The industry exhibits a highly concentrated structure at the leading-edge manufacturing tier, driven by immense capital expenditure requirements. Strategic archetypes include integrated device manufacturers, pure-play foundries, and specialized intellectual property providers. Capacity expansion and strategic partnerships define the primary competitive moves across this complex ecosystem, alongside technology licensing efforts.
On the pure-play foundry vector, TSMC Limited exemplifies the leading-edge manufacturing capacity and extensive ecosystem for advanced FinFET nodes. Samsung Electronics represents a vertically integrated model, combining advanced foundry services with proprietary product lines and memory solutions. Intel Corporation, a US-based entity, is actively re-entering the foundry market with significant capital investment, aiming to attract external chip design clients. These entities collectively anchor the high-volume production and technological advancement within the FinFET ecosystem, driving innovation in process nodes and advanced packaging solutions.
| Leading Market Players |
|---|
| TSMC Limited |
| Samsung Electronics |
| Intel Corporation |
| GlobalFoundries Inc. |
| Semiconductor Manufacturing International Corporation |
| Infineon Technologies AG |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Extreme capital expenditure for advanced foundry construction directly influences pricing power for leading-edge process nodes. This cost component flows through the value chain, shaping the negotiation leverage of foundries over fabless design houses for access to critical manufacturing capacity.
Pricing Analysis
Value-based pricing for FinFET technology anchors on performance per watt and transistor density. Foundry services operate on a contract-based long-term offtake model, securing committed volumes. Price differentiation stems from process node performance, such as 5nm versus 7nm, and the level of design customization offered through proprietary Process Design Kits. Pricing pressure stems from intense competition among leading foundries for high-volume customer contracts. Embedded systems and IoT device makers represent the most price-sensitive segments, while high-performance computing clients exhibit less sensitivity.
Supply Chain Analysis
EUV lithography equipment supply rests heavily on a single European vendor, creating a critical dependency for advanced FinFET manufacturing. Geographic supply concentration for leading-edge nodes is centered in Taiwan and South Korea, with emerging investments in the United States. Key raw material dependencies include silicon wafers and specialty gases. Geopolitical supply risk from regional instability or trade disputes represents a structural vulnerability. Downstream distribution runs through direct foundry services to fabless companies and integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a supply-constrained story, with leading-edge foundry capacity representing a significant bottleneck propping pricing for advanced FinFET manufacturing. Access to sub-7nm nodes remains a strategic imperative for technology firms globally.
For Market Incumbents: Acquire specialized IP design houses focused on Gate-All-Around architectures to accelerate the transition beyond FinFET. Expand manufacturing capacity in geopolitically stable regions, such as the United States or Europe, to mitigate supply chain risks. Deepen co-design partnerships with major fabless clients for AI accelerators and flagship mobile processors. This strategy defends market leadership against emerging subsidized foundry entrants and geopolitical shifts.
For New Entrants and Emerging Players: Capture niche markets requiring specialized FinFET process technologies, such as automotive electronics or industrial automation. The most penetrable segment lies in mature FinFET nodes (e.g., 14nm, 22nm) where volume demand is stable and capital intensity is lower. Focus on regional supply chain resilience as a key go-to-market angle, appealing to national industrial policies seeking diversified manufacturing. Leverage government subsidies from initiatives like the US CHIPS Act to establish initial fabrication capabilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor established foundry players or specialized equipment manufacturers in regions with strong government backing, such as the United States. Long-term viability hinges on sustained demand from artificial intelligence and high-performance computing, driving continuous innovation. Target advanced packaging specialists or materials science firms crucial for heterogeneous integration. A key signal to watch is the successful ramp-up and utilization rates of new foundry construction projects outside of traditional hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Western Geographies | Increases supply chain resilience and attracts fabless clients seeking diversified manufacturing options. |
| Advanced Packaging Technology Development | Enables powerful heterogeneous systems, bypassing physical scaling limits for performance gains. |
| Gate-All-Around (GAA) Architecture R&D | Positions firms for the next generation of sub-3nm process nodes, sustaining transistor scaling. |
| Co-Design Partnerships with Major Fabless Firms | Secures long-term revenue streams and ensures optimal hardware-software integration for critical applications. |
| Specialized Talent Recruitment and Training | Addresses the global scarcity of semiconductor engineers, maintaining innovation and manufacturing efficiency. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with foundry executives, fabless design engineers, semiconductor equipment suppliers, and government policy advisors. This approach combined bottom-up market sizing with top-down validation, integrating diverse data points for comprehensive insights.
Market segmentation by device type, process technology, application, end user, and regional manufacturing capacity formed the core of the quantitative model. Compound annual growth rates were derived from historical data trends and projected demand across the analysis window. Industry-specific forecast inputs included AI accelerator deployment rates and mobile processor unit shipments, informing future volume projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability and technological breakthroughs. Forecasts reflect assumptions regarding capital investment trends and export control regimes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Gan on Diamond Technology Market