
 Global Gan Semiconductor Device Market | 2026-2036
Global Gan Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gan Semiconductor Device Market Analysis
The shift from single-source silicon carbide substrate reliance toward multi-source GaN epitaxy partnerships is recalibrating supply security for RF and power device makers. Wolfspeed, Inc. leverages its captive SiC substrate production to anchor high-performance GaN-on-SiC roadmaps for defense and telecom base stations. Infineon Technologies AG competes through integrated module design that bundles GaN switches with gate drivers and protection logic. Qorvo, Inc. specializes in GaN RF front-ends for 5G massive MIMO arrays, occupying a narrow but defensible frequency band above 3 GHz.
Gallium nitride semiconductor devices are wide-bandgap electronic components fabricated on silicon, silicon carbide, or sapphire substrates, typically operating at breakdown fields above 3 MV/cm and switching frequencies exceeding 100 kHz. They serve primarily as high-efficiency power converters and RF power amplifiers where silicon devices face thermal and frequency limitations. Power Devices lead volume shipments due to penetration across server power supplies and onboard chargers, though RF Devices capture superior margins from aerospace and 5G infrastructure programs. GaN-on-Si technology dominates unit economics for consumer adapters below 100W, while GaN-on-SiC commands performance-critical applications above 600V where thermal conductivity determines reliability.
The U.S. Environmental Protection Agency and Department of Energy efficiency mandates are tightening minimum performance standards for external power supplies and data center infrastructure, directly expanding addressable volume for GaN replacements. The European Union's F-Gas Regulation and Ecodesign requirements are accelerating refrigerant compressor electrification, creating parallel demand for GaN motor drives. China's MIIT domestic substitution directives and GB standards for wide-bandgap semiconductors are reshaping procurement criteria for state-backed infrastructure projects. Stakeholders must monitor substrate cost trajectories and foundry qualification timelines to time capacity commitments before demand inflections lock in supplier relationships.
Market Dynamics
The transition from silicon-based power electronics to wide-bandgap alternatives is compressing design cycles across automotive and data center supply chains. Wolfspeed's captive silicon carbide substrate production and Infineon's integrated GaN module roadmaps are forcing tier-one suppliers to accelerate qualification timelines or risk exclusion from next-generation platform awards.
Growth Catalysts
- Electric Vehicle Powertrain Electrification:Automotive OEMs in Germany, Japan, and the United States are integrating GaN-based onboard chargers and DC-DC converters to reduce weight and extend range. The U.S. Inflation Reduction Act's clean energy manufacturing tax credits are accelerating domestic foundry investments.
- Data Center Efficiency Mandates:The U.S. Environmental Protection Agency and Department of Energy are tightening minimum performance standards for server power supplies, directly expanding replacement demand for GaN rectifiers and PFC circuits.
- 5G Infrastructure Deployment:Massive MIMO antenna arrays operating above 3 GHz require GaN RF power amplifiers for thermal efficiency and linearity, with China's MIIT domestic substitution directives reshaping procurement for state-backed telecom builds.
Market Restraints
- Substrate Cost Volatility:High-purity silicon carbide substrates remain concentrated among Japanese and U.S. suppliers, creating input cost pressure for GaN-on-SiC device manufacturers serving aerospace and defense programs.
- Epitaxy Equipment Bottlenecks:Metal-organic chemical vapor deposition systems for GaN epitaxial growth face 12-18 month lead times from German and Japanese equipment vendors, constraining foundry capacity expansion.
- Silicon Superjunction Competition:Mature silicon superjunction MOSFETs below 600V continue improving cost-performance ratios, delaying GaN penetration in price-sensitive industrial motor drive applications.
Strategic Opportunities
- India Power Infrastructure Modernization:The country's Bureau of Indian Standards is drafting wide-bandgap semiconductor specifications for grid-tied solar inverters, creating first-mover advantage for GaN suppliers qualifying under CEA technical standards.
- Residential Heat Pump Electrification:The European Union's F-Gas Regulation is accelerating refrigerant compressor electrification, opening parallel demand for GaN motor drives in variable-speed HVAC systems.
- GaN-Silicon Carbide Hybrid Integration:Converging GaN switching with SiC diodes in multi-chip power modules is enabling 800V automotive architectures that neither material achieves optimally alone.
Industry Challenges
- Reliability Qualification Timelines:Automotive AEC-Q101 certification for GaN devices requires 1,000-hour high-temperature reverse bias testing, extending time-to-revenue for new product introductions by 18-24 months.
- Packaging Thermal Management:High-frequency switching in GaN devices demands novel copper-clip and embedded-die packaging approaches that legacy silicon assembly lines cannot accommodate without capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gan Semiconductor Device Market |
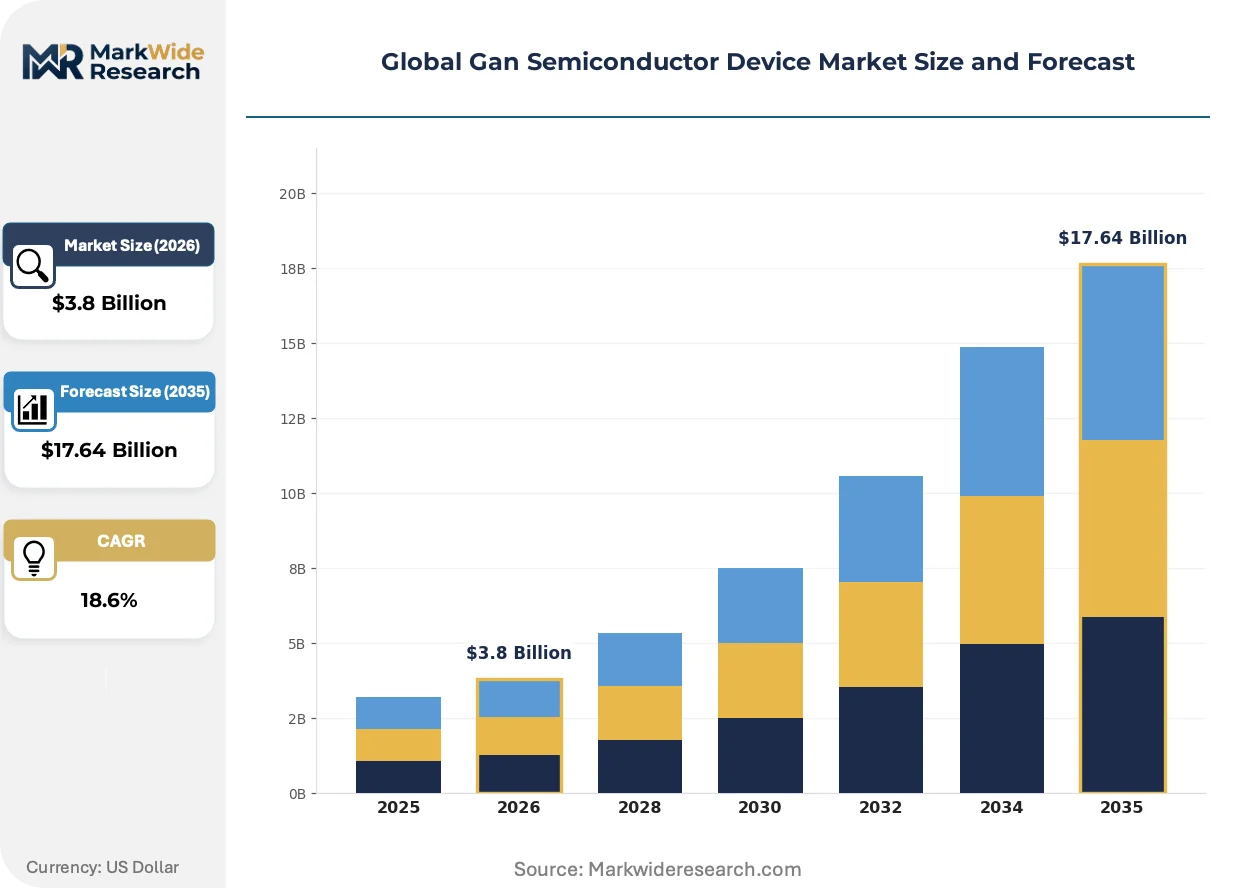
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Devices, RF Devices, Optoelectronics, Diodes Application: Telecommunications, Energy, Automotive, Consumer Electronics End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers Technology: GaN-on-Si, GaN-on-SiC, Hybrid Technology, Others |
| Companies Covered | Wolfspeed, Inc., Qorvo, Inc., Infineon Technologies AG, MACOM Technology Solutions Holdings, Inc., Texas Instruments Incorporated, Sumitomo Electric Industries, Ltd., Mitsubishi Electric Corporation, ROHM Co., Ltd., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gan Semiconductor Device Market Emerging Trajectories
GaN device architecture is bifurcating between cost-optimized silicon substrates and performance-driven silicon carbide platforms. This divergence is reshaping foundry specialization, equipment vendor roadmaps, and end-user procurement criteria across power and RF applications.
GaN-on-silicon technology is consolidating the sub-100W consumer adapter segment through 650V lateral device structures that leverage existing 8-inch silicon foundry infrastructure. Smartphone and laptop OEMs in Taiwan and South Korea are adopting integrated GaN power ICs that combine controller, driver, and switch functions. This consolidation is compressing bill-of-materials counts by 30-40% while enabling form factors incompatible with discrete silicon solutions.
The European Union's Ecodesign requirements for external power supplies are mandating minimum active-mode efficiency and no-load power consumption thresholds that silicon-based designs struggle to meet cost-effectively. Industrial equipment manufacturers exporting to Europe must redesign power architectures around GaN primary-side regulation or risk market exclusion. This regulatory pressure is accelerating qualification programs among Chinese adapter suppliers seeking CE marking compliance.
Buyer concentration among hyperscale cloud providers is restructuring component procurement from discrete device purchasing toward system-level power architecture partnerships. Amazon Web Services, Microsoft Azure, and Google Cloud are engaging directly with GaN foundries to co-design custom power stages for server racks, bypassing traditional distributor channels. This disintermediation is most visible in the United States, where data center construction permits and IRA clean energy credits are concentrating demand in Virginia, Texas, and Arizona clusters.
Global Gan Semiconductor Device Market Segmentation
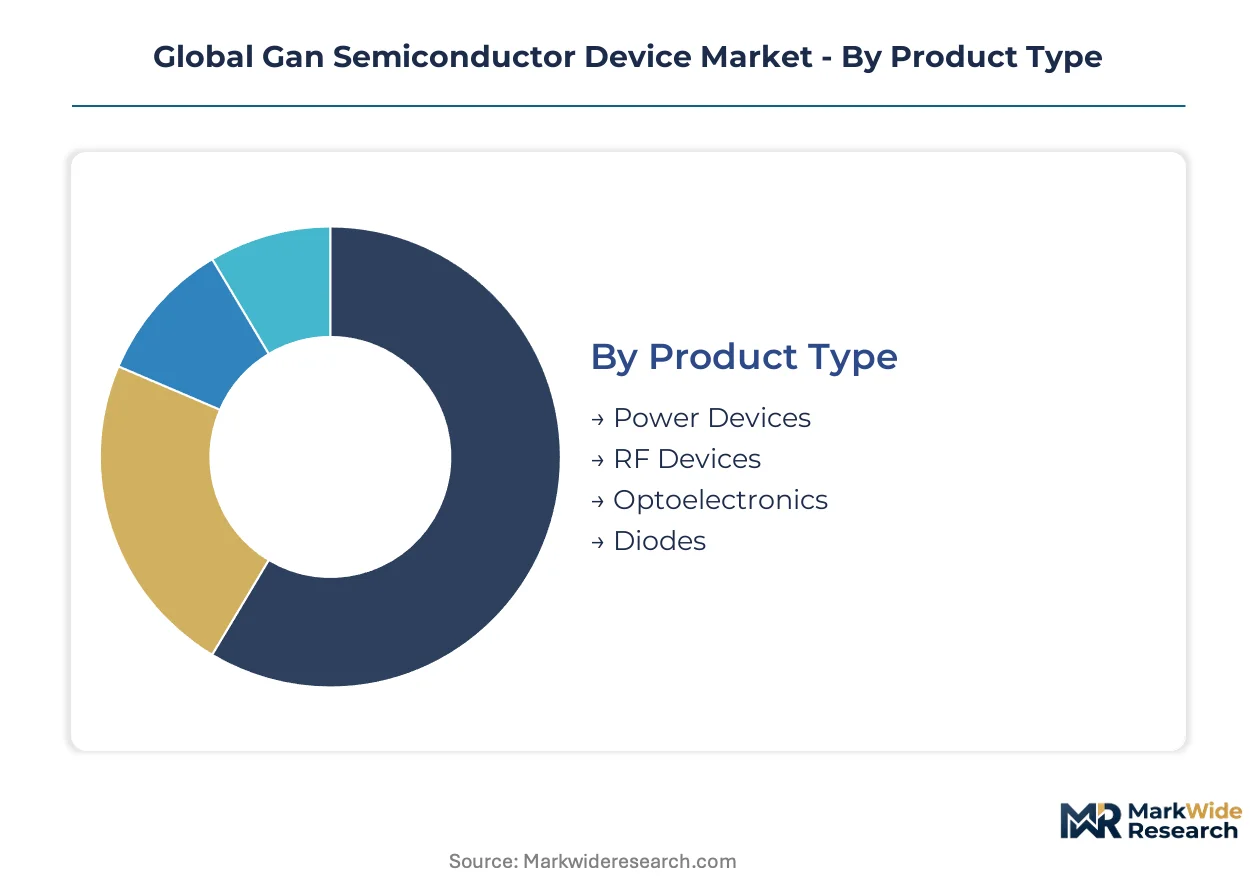
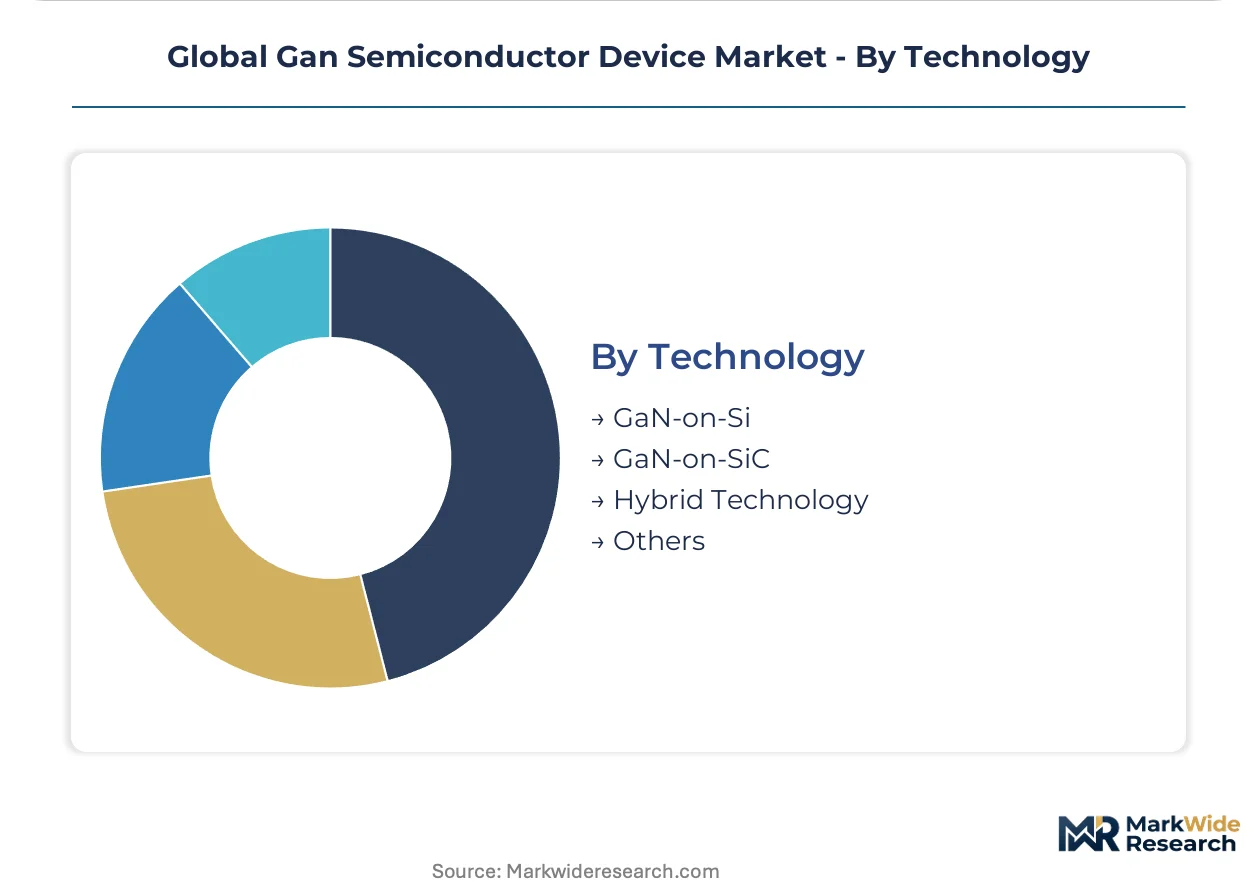
GaN semiconductor segmentation reveals divergent economics across substrate platforms and end-use requirements. Power density specifications, thermal constraints, and regulatory efficiency mandates reshape procurement patterns differently across each category.
Product Type:
Volume leadership sits with mass-market power conversion, while premium margins concentrate in specialized RF amplification.
- Power Devices:High-frequency switching components fabricated on silicon or silicon carbide substrates for DC-DC converters and AC-DC rectifiers. Server power supplies in Virginia and Texas data center clusters drive procurement volume under EPA efficiency mandates.
- RF Devices:Gallium nitride power amplifiers and low-noise amplifiers operating above 3 GHz for radar and telecommunications. China's MIIT-directed 5G massive MIMO deployments in Beijing and Shenzhen absorb high-margin production from domestic foundry expansions.
- Optoelectronics:Blue and ultraviolet LEDs plus laser diodes leveraging wide-bandgap emission properties.
- Diodes:Schottky barrier and PIN structures for high-speed rectification in automotive onboard chargers.
Mature deployment sits with Power Devices. Newer deployment is concentrated in RF Devices.
Application:
End-use concentration tracks regulatory pressure intensity and electrification investment cycles.
- Telecommunications:Base station power amplifiers and RF front-ends for 5G infrastructure. South Korea's SK Telecom and KT Corporation massive MIMO rollouts in Seoul metropolitan area prioritize GaN-on-SiC thermal performance for 28 GHz millimeter-wave spectrum.
- Automotive:Onboard chargers, DC-DC converters, and traction inverters for battery electric vehicles. Germany's BMW and Volkswagen integrate 800V architectures using GaN-SiC hybrid modules to reduce charging time and extend driving range.
- Energy:Solar inverters, wind turbine converters, and grid-tied storage systems.
- Consumer Electronics:Smartphone and laptop adapters below 100W using GaN-on-Si cost advantages.
Procurement scale concentrates in Telecommunications. Fastest qualification timelines appear in Automotive.
End User:
Channel structure reflects design-in complexity and certification burden distribution.
- OEMs:Original equipment manufacturers with captive power electronics design teams. Taiwan's Delta Electronics and Lite-On Technology specify custom GaN controller ICs for notebook adapter platforms serving Dell and HP procurement.
- Tier-1 Suppliers:Automotive and industrial subsystem integrators managing AEC-Q101 qualification programs.
- Distributors:Arrow Electronics and Avnet channel inventory for mid-volume industrial customers.
- Aftermarket Providers:Replacement power supply vendors for legacy infrastructure upgrades.
Design authority rests with OEMs. Volume aggregation flows through Tier-1 Suppliers.
Technology:
Substrate selection determines performance ceiling and unit economics tradeoffs.
- GaN-on-Si:Lateral heterostructure devices on 8-inch silicon wafers leveraging existing CMOS foundry infrastructure. South Korea's Samsung and Taiwan's TSMC dominate wafer processing for sub-100W consumer adapters where cost minimization overrides thermal performance.
- GaN-on-SiC:Epitaxial growth on high-purity silicon carbide substrates for breakdown voltages above 600V. Wolfspeed's captive SiC substrate production in North Carolina anchors defense and aerospace supply chains requiring maximum thermal conductivity.
- Hybrid Technology:Multi-chip modules combining GaN switches with SiC diodes or silicon gate drivers.
- Others:GaN-on-sapphire and GaN-on-diamond experimental platforms for specialized optoelectronics.
Unit cost leadership belongs to GaN-on-Si. Performance boundaries expand through GaN-on-SiC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride semiconductor demand concentrates where substrate fabrication, automotive electrification, and data center construction intersect. The United States, China, Germany, Japan, and South Korea anchor capacity expansion and consumption growth.
United States
Data center clusters in Virginia and Texas drive procurement volume for server power supplies under EPA efficiency mandates. The Inflation Reduction Act's clean energy manufacturing tax credits redirect capital toward domestic GaN foundry investments. Wolfspeed's captive silicon carbide substrate production in North Carolina anchors defense and aerospace supply chains.
China
State-backed 5G massive MIMO deployments in Beijing and Shenzhen absorb high-margin RF device production from domestic foundry expansions. MIIT domestic substitution directives and GB standards for wide-bandgap semiconductors reshape procurement criteria for state-backed infrastructure projects. Yangtze River Delta fabrication complexes scale gallium nitride epitaxy capacity.
Germany
BMW and Volkswagen integrate 800V architectures using GaN-SiC hybrid modules to reduce charging time and extend driving range. The EU F-Gas Regulation and Ecodesign requirements accelerate refrigerant compressor electrification, creating demand for GaN motor drives. Bavaria's automotive electronics corridor concentrates tier-one supplier qualification programs.
Japan
Sumitomo Electric and Mitsubishi Electric anchor high-purity silicon carbide substrate supply for GaN-on-SiC devices serving aerospace programs. METI technology roadmaps prioritize wide-bandgap semiconductor commercialization for grid-tied renewable systems. Kyushu-based material suppliers face 12-18 month lead times for metal-organic chemical vapor deposition equipment.
South Korea
SK Telecom and KT Corporation massive MIMO rollouts in Seoul prioritize GaN-on-SiC thermal performance for 28 GHz millimeter-wave spectrum. Samsung dominates 8-inch silicon wafer processing for sub-100W consumer adapters where cost minimization overrides thermal performance. Government semiconductor self-sufficiency programs accelerate domestic epitaxy partnerships.
Global Gan Semiconductor Device Market Vendor Landscape
Capacity expansion dominates the current landscape as foundries race to qualify automotive and data center programs before design cycles lock. The vendor base stratifies between integrated device manufacturers with captive substrate supply, fabless specialists leveraging foundry partnerships, and diversified semiconductor conglomerates bundling GaN with adjacent power technologies. Three archetypes define positioning: substrate-integrated pure-plays, module-integrated diversified players, and RF-specialized fabless designers. M&A activity and strategic foundry partnerships represent the dominant competitive moves.
Among substrate-integrated fabricators, Wolfspeed, Inc. exemplifies vertical control over silicon carbide supply chains, while Infineon Technologies AG represents the diversified module-integrated tier bundling GaN switches with gate drivers and protection logic. Qorvo, Inc. occupies the RF-specialized fabless position, anchoring high-frequency amplification above 3 GHz. These three patterns—captive material control, system-level integration, and frequency-band specialization—structure competitive differentiation across power and RF applications.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Qorvo, Inc. |
| Infineon Technologies AG |
| MACOM Technology Solutions Holdings, Inc. |
| Texas Instruments Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Mitsubishi Electric Corporation |
| ROHM Co., Ltd. |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed foundry expansions in China and South Korea are consolidating pricing power among state-supported producers, compressing margins for private-capital-dependent specialists while redirecting procurement toward vertically integrated domestic supply chains.
Pricing Analysis
Warranty and reliability-guarantee bundling separates automotive-grade GaN devices from unbundled consumer adapter components. Three-tier pricing structure across AEC-Q101 certified, industrial-grade, and consumer-grade tiers reflects qualification burden and thermal performance specifications. Cost compression in sub-100W GaN-on-Si adapters is intensifying because 8-inch silicon foundry overcapacity in Taiwan enables aggressive wafer pricing. Hyperscale data center operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations favoring efficiency gains over upfront component costs.
Supply Chain Analysis
Freight costs for high-purity silicon carbide substrates from Japan and the United States to European automotive assembly plants add significant landed cost premiums for GaN-on-SiC devices. Epitaxial growth equipment concentrates in Germany and Japan, while 8-inch silicon wafer processing anchors in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for metal-organic chemical vapor deposition systems with extended equipment lead times. Distribution runs through tier-one automotive subsystem integrators and direct foundry partnerships with hyperscale cloud providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GaN semiconductor market is becoming a vertical-integration race where captive substrate supply and in-house epitaxy capacity determine qualification access for automotive and defense programs.
For Market Incumbents: Anticipate silicon superjunction MOSFET price-performance improvements below 600V by accelerating GaN-SiC hybrid module roadmaps for 800V automotive architectures. Secure AEC-Q101 certification timelines through captive reliability testing facilities before design cycles lock for next-generation EV platforms. Prioritize backward integration into silicon carbide substrate production to reduce dependency on Japanese and U.S. material suppliers. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer lower barrier entry for fabless GaN controller IC specialists targeting India's grid-tied solar inverter specifications under CEA technical standards. Focus qualification resources on residential heat pump motor drives for European HVAC OEMs facing F-Gas Regulation compliance deadlines. Pursue co-development partnerships with Chinese adapter suppliers seeking CE marking for Ecodesign-compliant external power supplies. For Investors and Strategic Acquirers: Foundry qualification announcements for automotive AEC-Q101 programs are the leading indicator that revenue inflection is 18-24 months forward. Target mid-cap epitaxy specialists with established MOCVD equipment access and pending tier-one supplier engagements. Monitor EPA efficiency mandate enforcement intensity for data center server power supplies as demand signal confirmation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Production | Wolfspeed's North Carolina fabrication complex secures defense supply chain priority for GaN-on-SiC RF devices. |
| AEC-Q101 Certification Investment | Automotive tier-one suppliers require 1,000-hour high-temperature reverse bias testing for EV onboard charger integration. |
| Hybrid Module Integration | GaN-SiC multi-chip architectures enable 800V traction inverters that BMW and Volkswagen are qualifying for next-generation platforms. |
| Direct Hyperscale Partnerships | Amazon Web Services and Microsoft Azure are bypassing distributors to co-design custom power stages with GaN foundries. |
| Domestic Foundry Expansion | China's MIIT-directed Yangtze River Delta complexes are scaling gallium nitride epitaxy capacity for state-backed 5G infrastructure. |
Methodological Framework
Multi-period observation of foundry capacity announcements, automotive platform qualification timelines, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with GaN device engineering directors, automotive tier-one supplier procurement managers, epitaxy equipment vendor sales leads, and data center power architecture specialists. Primary fieldwork drew from SEC 10-K filings, MIIT domestic substitution directives, EPA efficiency mandate dockets, and customs data for wide-bandgap semiconductor trade flows. Bottom-up wafer shipment estimates and top-down OEM procurement budget analysis provided triangulation validation.
Input-output matrices mapped substrate supply constraints against end-use demand segments across the analysis window, modeling volume and value trajectories by product type, application, substrate technology, and geographic production cluster. CAGRs were derived from regression analysis of historical foundry utilization rates and forward-looking OEM platform introduction schedules. Forecast inputs incorporated silicon carbide substrate price trajectories, MOCVD equipment delivery backlogs, and automotive electrification investment cycles.
The model holds under sustained IRA clean energy credit enforcement and MIIT domestic procurement directives; deviation in EPA efficiency mandate timing or silicon superjunction cost-performance improvements would shift GaN penetration curves. Stakeholders should weight assumptions against their own operating context and qualification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
SLD Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market