
 Transparent Digital Signage Market | 2026-2036
Transparent Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Digital Signage Market Outlook
Modular screen bundling with content management software is restructuring buyer procurement patterns in the Transparent Digital Signage Market. LG Electronics leverages vertical integration across OLED panel fabrication and display controller production to sustain pricing power in premium installations. Samsung Electronics anchors global supply through its dominance in semiconductor-grade substrate manufacturing for transparent microLED arrays. Planar Systems specializes in fine-pitch LED architectures for corporate lobby deployments, differentiating through extended warranty programs and direct channel control.
Transparent digital signage denotes display systems that maintain partial light transmission while projecting visual content, typically achieving transparency ratios between 40% and 85% depending on pixel pitch and backlighting architecture. These installations employ thin-film transistor backplanes bonded to transparent conductive oxide layers, serving commercial environments where spatial continuity and information overlay must coexist. OLED product configurations currently occupy the highest margin pools due to manufacturing complexity and limited supplier base, while LED segments compete on scale across transportation hub deployments. Interactive touch technology within the technology dimension is recording the fastest adoption velocity as retailers seek to convert passive window shoppers into engaged prospects.
The Federal Communications Commission governs electromagnetic emissions from networked signage hardware in the United States, while the EU RoHS directive restricts hazardous substance thresholds in display component manufacturing across European markets. South Korea's Ministry of Trade, Industry and Energy enforces energy efficiency grading that shapes import eligibility for foreign panel suppliers. Stakeholders must monitor evolving e-waste recovery mandates and carbon disclosure requirements that will reshape supplier qualification criteria and total cost of ownership calculations.
Market Dynamics
MicroLED pixel density advances are compressing manufacturing yields while simultaneously expanding addressable application spaces, forcing display fabricators to recalibrate capacity allocation between premium transparent OLED and emerging microLED product lines.
Growth Catalysts
- EU RoHS hazardous substance restrictions:These directives accelerate substitution of legacy LCD backlighting with self-emissive transparent OLED architectures in European retail deployments.
- Transportation hub modernization:Airports and rail terminals in Germany, France, and the Netherlands are replacing static wayfinding with transparent LED installations that preserve sightlines while delivering dynamic passenger information.
- Self-emissive transparency layers:Advances in thin-film encapsulation are eliminating diffuser requirements, reducing panel thickness and enabling curved glass integration in automotive showroom applications.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductive oxide feedstock relies heavily on Chinese rare earth processing, exposing panel fabricators to input cost volatility and export restriction risk.
- Pixel pitch limitations in LED segments:Current microLED transfer yields struggle below 0.7mm pitch for large-format transparent installations, capping resolution in premium retail window applications.
- South Korean energy efficiency grading:Ministry of Trade, Industry and Energy import eligibility rules disadvantage foreign panel suppliers lacking local certification infrastructure.
Strategic Opportunities
- Underpenetrated Indian retail modernization:BIS certification pathways for display electronics remain underutilized by transparent signage specialists, creating first-mover positioning in shopping mall and flagship store segments.
- EU CSRD carbon disclosure mandates:Corporate sustainability reporting requirements are elevating procurement preference for displays with verified lifecycle carbon footprints and modular repair architectures.
- Interactive touch convergence with transparent OLED:Capacitive sensing integration is opening museum and exhibition verticals where gesture-driven content exploration commands premium installation budgets.
Industry Challenges
- Semiconductor-grade substrate fabrication expertise:Cleanroom operations for microLED epitaxy require talent pools concentrated in South Korea and Taiwan, constraining geographic diversification of supply.
- Legacy building management system integration:Transparent signage networks must interface with proprietary lighting and climate control protocols in commercial real estate, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Digital Signage Market |
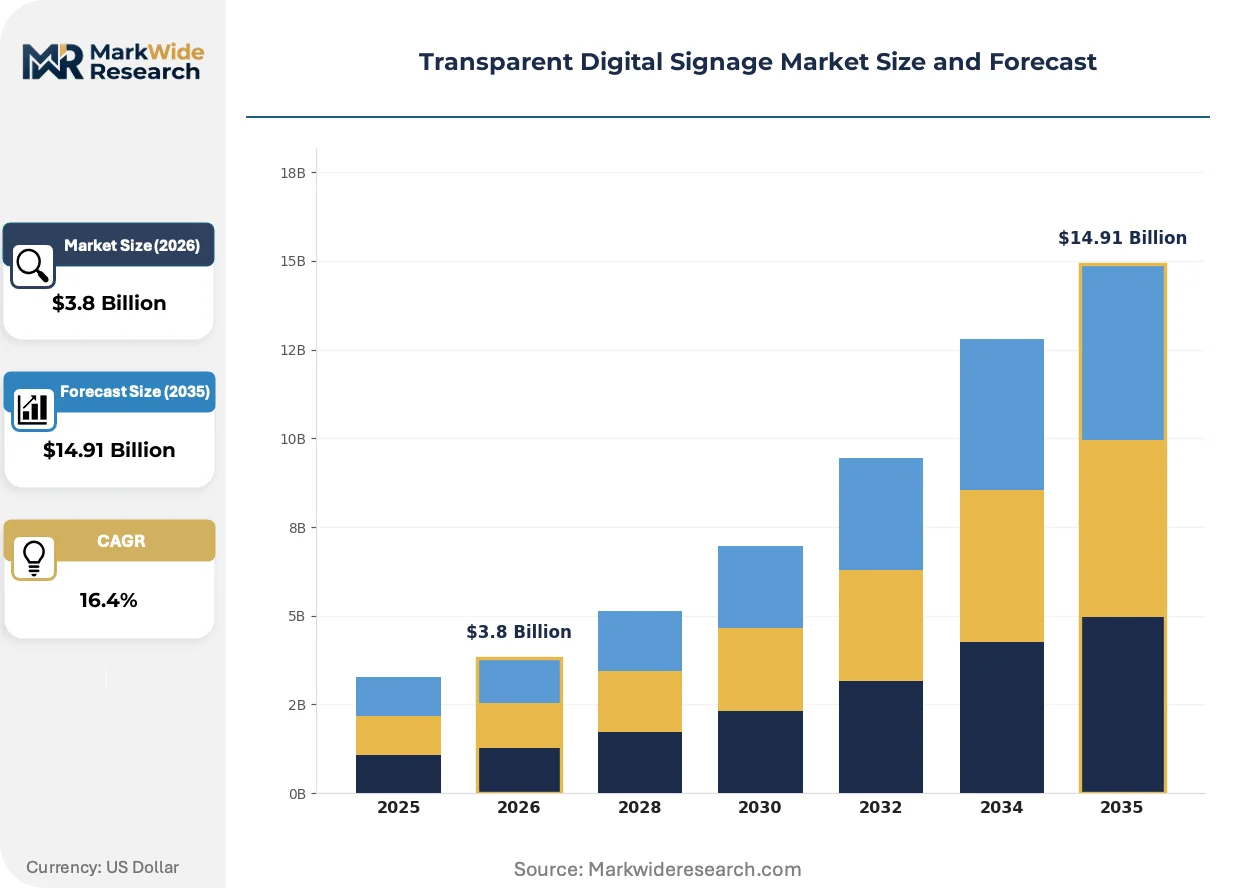
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, Transparent LCD Application: Retail Displays, Transportation Hubs, Museums, Corporate Environments Technology: Content Management Systems, Interactive Displays, Touch Technology, Sensor Integration End User: Retailers, Transportation Agencies, Hospitality, Corporations |
| Companies Covered | LG Electronics, Planar Systems, BenQ, Shenzhen NEXNOVO Technology, Leyard Group, Samsung Electronics, AUO Corp., Panasonic Holdings Corp., Barco NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Digital Signage Market Strategic Shifts
Transparent display architectures are bifurcating between ultra-high-margin OLED configurations for flagship retail and cost-optimized LED alternatives for transportation infrastructure, with interactive capabilities emerging as the decisive competitive differentiator across both tiers.
MicroLED chiplet transfer technology is rewriting yield economics for large-format transparent installations. Samsung Electronics and domestic competitors in South Korea are scaling mass transfer equipment for sub-millimeter pixel pitches. This compression of defect rates is enabling transparent video walls in automotive showrooms that were previously exclusive to projection-mapped glass.
REACH substance authorization procedures are tightening restrictions on cadmium-based quantum dot phosphors in European display manufacturing. Panel suppliers are accelerating indium phosphide alternative development to maintain CE marking eligibility. Automotive and luxury retail segments face the steepest compliance recertification timelines as existing inventory phases out.
Retailers are unbundling hardware procurement from content management subscriptions, reversing the bundled screen-plus-software contracts that dominated early transparent signage adoption. Specialist software vendors in Germany and the United Kingdom are capturing recurring revenue streams previously retained by display manufacturers. This disintermediation is most pronounced among mid-size European fashion chains operating 50-200 store networks.
Transparent Digital Signage Market Segmentation
Transparent digital signage procurement decisions hinge on certification requirements, application environment constraints, and integration complexity with legacy infrastructure. Each segmentation dimension carries distinct regulatory burdens and technical specifications that reshape vendor qualification and deployment economics.
Product Type:
CE marking requirements under EU RoHS apply differentially across display architectures, with self-emissive technologies facing stricter substance thresholds than backlit alternatives.
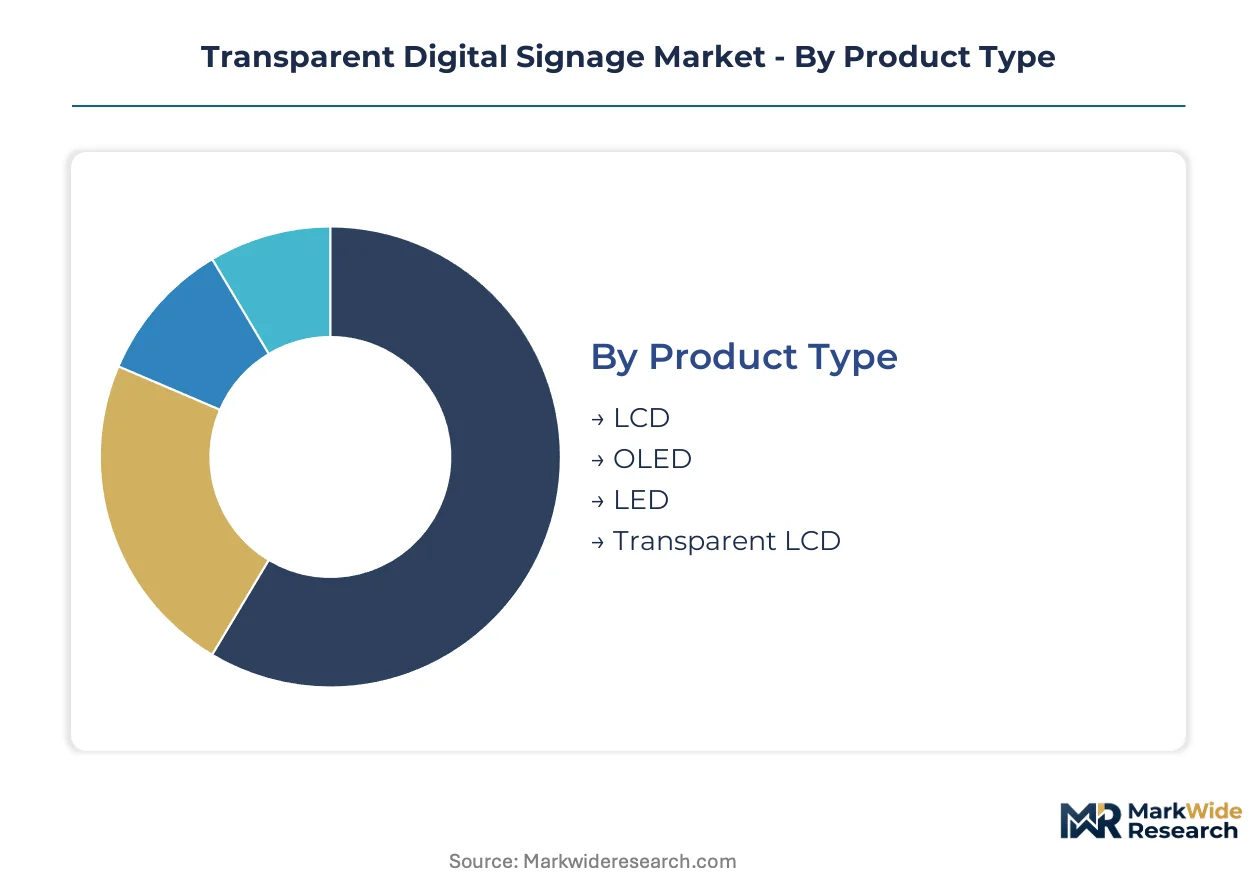
- OLED:Self-emissive pixels eliminate backlighting layers, achieving transparency ratios above 70% through thin-film encapsulation. Luxury automotive showrooms in Germany and flagship retail chains in France concentrate procurement here, driven by REACH compliance deadlines for cadmium-free quantum dot alternatives.
- LED:MicroLED chiplet architectures enable large-format transparent video walls through mass transfer bonding. Transportation agencies in the Netherlands and rail operators in Germany deploy these for passenger information systems where sightline preservation matters.
- LCD:Backlit configurations with transparent diffusers occupy budget-tier positioning in corporate lobby installations where full transparency is secondary to content visibility.
- Transparent LCD:Specialized backlight-stripped variants serve museum exhibition cases requiring artifact visibility alongside interpretive overlays.
LED sits at the top of the volume ranking, with OLED climbing the fastest.
Application:
Deployment environments dictate durability specifications, with outdoor transportation installations requiring IP65 enclosures absent from climate-controlled retail settings.
- Retail Displays:Window-facing installations merge physical merchandising with dynamic content, demanding high-brightness panels that combat ambient glare. Department store chains across South Korea and specialty fashion retailers in Italy drive specification toward interactive touch integration.
- Transportation Hubs:Airports in Germany and rail terminals in France prioritize wayfinding clarity and real-time schedule integration. These deployments emphasize 24/7 operational reliability and centralized content management federation.
- Museums:Curatorial requirements for artifact preservation impose strict thermal emission limits, favoring low-heat OLED configurations over LED alternatives.
- Corporate Environments:Lobby and meeting room installations balance aesthetic minimalism with video conferencing compatibility, often requiring integration with building management systems.
Transportation Hubs command the largest installed base, though Retail Displays are expanding most quickly.
Technology:
Software and sensing layers determine recurring revenue potential and customer lock-in, with cloud-native architectures displacing on-premise legacy systems.
- Interactive Displays:Capacitive touch grids embedded in transparent substrates convert passive viewers into engaged users. Museum curators in the United Kingdom and experiential retail designers in the United States specify these for gesture-driven content exploration.
- Content Management Systems:Cloud-based orchestration platforms enable real-time playlist updates across distributed estate networks. Mid-size European fashion chains with 50-200 locations increasingly procure these separately from hardware.
- Touch Technology:Projected capacitive and infrared frame alternatives compete on cost and precision in high-traffic retail windows.
- Sensor Integration:Occupancy detection and environmental responsiveness automate brightness adjustment and content triggering.
Content Management Systems anchor current procurement volumes, while Interactive Displays show the steepest expansion trajectory.
End User:
Budget cycles and decision authority structures vary sharply across buyer categories, with transportation agencies requiring public procurement compliance absent from corporate direct purchasing.
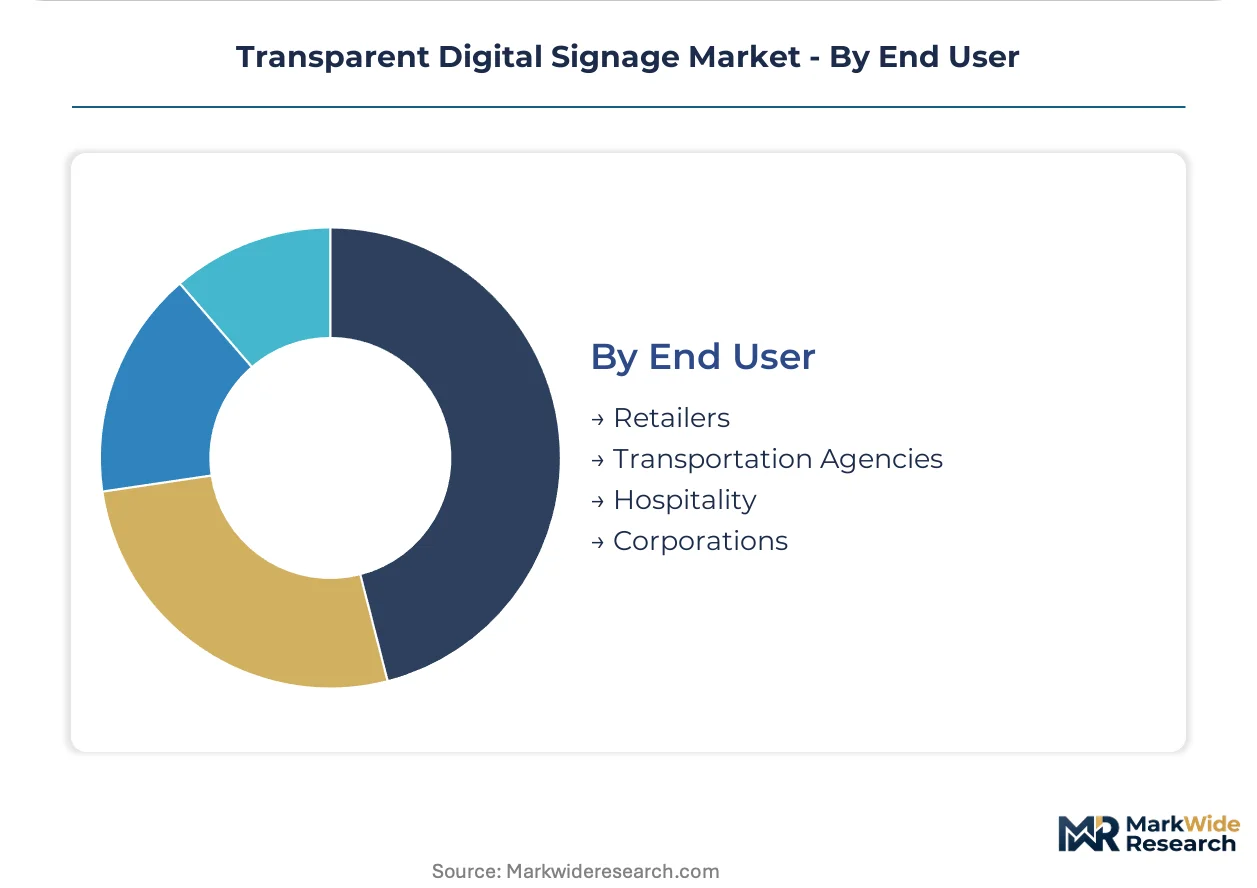
- Retailers:Visual merchandising teams control specification, prioritizing brand alignment and window conversion metrics. Flagship store budgets accommodate premium OLED, while chain rollouts favor LED economics.
- Corporations:Facilities and IT departments share ownership, driving standardization across global office portfolios and API integration with unified communications platforms.
- Transportation Agencies:Public tenders emphasize total cost of ownership, modular repair architectures, and multi-year service level agreements.
- Hospitality:Hotels and entertainment venues prioritize ambient design integration and concierge information delivery in lobby and elevator applications.
Retailers maintain the dominant share of current installations, with Corporations gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea pioneered transparent OLED commercialization through Samsung Electronics and LG Electronics, establishing the foundational manufacturing base that now feeds retail and transportation deployments worldwide.
South Korea
Seoul anchors global panel supply through vertically integrated fabrication complexes serving luxury automotive showrooms and flagship retail chains. The Ministry of Trade, Industry and Energy enforces energy efficiency grading that shapes import eligibility and domestic procurement preferences. Gyeonggi Province hosts concentrated cleanroom operations for microLED epitaxy, constraining geographic diversification of semiconductor-grade substrate expertise.
Germany
Transportation agencies in Frankfurt, Munich, and Berlin drive transparent LED installations for rail terminal wayfinding and airport passenger information systems. REACH substance authorization procedures tighten restrictions on cadmium-based quantum dot phosphors, accelerating indium phosphide alternative development. Baden-Württemberg's automotive showrooms concentrate premium OLED procurement as existing inventory phases out under compliance deadlines.
United States
Federal Communications Commission electromagnetic emission regulations govern networked signage hardware deployment across corporate lobby and retail window applications. Experiential designers in New York and Los Angeles specify interactive touch-integrated transparent displays for museum and exhibition verticals. The Federal Trade Commission monitors advertising disclosure requirements for digital content overlaying physical merchandise.
China
Shenzhen and Guangzhou fabricators scale microLED chiplet architectures for cost-optimized transportation infrastructure exports. Indium tin oxide supply concentration in Chinese rare earth processing exposes panel fabricators to input cost volatility and export restriction risk. MIIT standard-setting for display electronics shapes domestic certification pathways and import substitution dynamics.
Netherlands
Rail operators in Amsterdam and Rotterdam prioritize transparent LED installations preserving sightlines while delivering real-time schedule integration. EU RoHS hazardous substance restrictions accelerate substitution of legacy LCD backlighting with self-emissive architectures in European retail deployments. Eindhoven's technology corridor hosts specialist software vendors capturing recurring content management revenue streams.
Transparent Digital Signage Market Competitive Environment
Premium-margin players sit above commodity-margin players across transparency ratio and pixel density specifications, with OLED configurations commanding the highest margin pools due to manufacturing complexity and limited supplier base. The vendor base stratifies into three tiers: South Korean conglomerates with captive substrate fabrication, Chinese scale specialists in microLED assembly, and European software vendors disintermediating bundled procurement. Dominant competitive moves include backward integration into semiconductor-grade substrate manufacturing and geographic expansion through BIS certification pathways in underpenetrated Indian retail markets.
Within the South Korean conglomerate tier, Samsung Electronics and LG Electronics exemplify vertically integrated positioning spanning OLED panel fabrication through display controller production. Planar Systems occupies a specialist position in fine-pitch LED architectures, differentiating through extended warranty programs and direct channel control in corporate lobby deployments. These three companies collectively represent the archetype spectrum from captive supply chain control to application-specific service differentiation.
| Leading Market Players |
|---|
| LG Electronics |
| Planar Systems |
| BenQ |
| Shenzhen NEXNOVO Technology |
| Leyard Group |
| Samsung Electronics |
| AUO Corp. |
| Panasonic Holdings Corp. |
| Barco NV |
| Others |
Value Chain & Pricing Dynamics
OLED-LED bifurcation creates distinct margin architectures across the Transparent Digital Signage Market, with premium self-emissive panels commanding pricing power through South Korean supply concentration while LED alternatives compete on scale through Chinese microLED assembly. This tier divergence feeds directly into procurement patterns: luxury automotive showrooms in Baden-Württemberg absorb 40-70% transparency premiums for OLED, whereas transportation agencies in the Netherlands optimize for total cost of ownership in LED tenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes buyer segmentation, with transparency ratio and pixel density as primary differentiation drivers. CE marking tier and REACH compliance status separate premium OLED from standard LED configurations, while economy LCD variants serve budget-constrained corporate lobbies. Cost compression in LED segments intensifies as Chinese fabricators scale microLED transfer equipment, squeezing margins for mid-tier suppliers. Transportation agencies exhibit highest price sensitivity through public tender mechanisms, whereas museum curators prioritize thermal emission specifications over unit cost.
Supply Chain Analysis
Cleanroom talent scarcity in Gyeonggi Province and Hsinchu County constrains semiconductor-grade substrate expansion for microLED epitaxy. Panel fabrication draws from South Korea, China, and Taiwan, with indium tin oxide feedstock resting on Chinese rare earth processing and transparent conductive oxide layers hinging on Taiwanese thin-film deposition expertise. Single-source vulnerability in indium supply exposes fabricators to export restriction risk. Distribution runs through direct channel partnerships for premium OLED installations and systems integrator networks for transportation infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transparent Digital Signage Market functions as a regulatory compounder, with EU RoHS hazardous substance restrictions and REACH authorization timelines accelerating technology substitution cycles that drive replacement demand across European retail and transportation infrastructure.
For Market Incumbents: Cement captive supply of semiconductor-grade substrates through backward integration into microLED epitaxy capacity in South Korea or Taiwan. Defend OLED margin pools by accelerating indium phosphide quantum dot certification ahead of REACH cadmium phase-out deadlines. Channel control through direct service relationships with luxury automotive showrooms insulates against software vendor disintermediation.
For New Entrants and Emerging Players: Enter via BIS certification pathways for display electronics in Indian retail modernization, where shopping mall and flagship store segments remain underpenetrated by transparent signage specialists. Target mid-size European fashion chains with 50-200 store networks through unbundled content management SaaS, capturing recurring revenue streams that incumbent display manufacturers currently retain. Lead with cloud-native orchestration platforms that displace legacy on-premise systems.
For Investors and Strategic Acquirers: Consolidation pressure builds where cleanroom fabrication expertise concentrates in South Korea and Taiwan, constraining geographic diversification of microLED supply. Long-term viability favors acquisition targets with modular repair architectures and verified lifecycle carbon footprints aligned to EU CSRD disclosure mandates. Watch interactive touch integration velocity in museum and experiential retail verticals as inflection indicator for premium installation budget allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MicroLED Epitaxy | Captive substrate supply in Gyeonggi Province secures yield control for sub-millimeter pixel pitch production. |
| REACH-Compliant Quantum Dot Certification | Indium phosphide alternatives maintain CE marking eligibility as cadmium-based phosphors phase out in European manufacturing. |
| Cloud-Native Content Management Platform | Unbundled SaaS procurement captures recurring revenue from mid-size European fashion chains disintermediating bundled contracts. |
| BIS Certification Pathway Expansion | First-mover positioning in Indian retail modernization unlocks shopping mall and flagship store segments before incumbent entry. |
| Interactive Touch Convergence Development | Capacitive sensing integration commands premium installation budgets in museum and experiential exhibition verticals. |
Study Parameters
Coverage spans South Korea, Germany, the United States, China, and the Netherlands, with primary inputs from each market cluster. The research combines interviews with display panel procurement managers, transportation agency tender officers, museum curators, automotive showroom visual merchandising directors, and software vendor product strategists with secondary validation from SEC filings, EU regulatory databases, Korean Ministry of Trade energy efficiency disclosures, and customs trade records. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation dimensions modeled include display architecture type, application environment, interactive technology layer, and end-user procurement structure. CAGRs derive from logistic diffusion curves fitted to adoption velocity in flagship retail and transportation infrastructure verticals. Forecast inputs incorporate microLED transfer yield improvement timelines and REACH substance authorization phase-out schedules.
The model holds under stable regulatory enforcement timelines and continued indium supply accessibility; deviation in export restriction severity or cleanroom labor mobility would shift capacity allocation assumptions. Forecasts reflect documented base conditions with explicit trigger monitoring. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America Head-Up Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
3D Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Foldable Screens Market
Display Technologies
Industrial Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
Microdisplay Market
Display Technologies
Touch Screen Display Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Electrochromic Window Market
Display Technologies
Portable Projector Market
Display Technologies
Rental Outdoor LED Display Market