
 Tank Ammunition Market | 2026-2036
Tank Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Tank Ammunition Market Insights
Platform upgrade revenue is rewriting profitability expectations across the value chain. Rheinmetall leverages its integrated propellant-to-projectile manufacturing footprint to capture margins on 120mm DM-series rounds. BAE Systems anchors Atlantic supply security through its US-UK production network for armor-piercing fin-stabilized discarding sabot rounds. KNDS Group competes on Franco-German industrial consolidation, sustaining cross-border R&D coordination for next-generation 140mm systems.
Tank ammunition encompasses kinetic and chemical energy projectiles engineered from tungsten or depleted uranium penetrators, composite propellant charges, and electronically fused warheads designed to defeat reactive armor at engagement ranges exceeding three kilometers. Armor-piercing rounds command the highest unit economics due to tungsten supply constraints and precision machining requirements, while high-explosive variants retain volume dominance across armored forces procurement. The 120mm caliber segment leads NATO-aligned demand, though 125mm production concentrates on Soviet-legacy platform operators and export markets.
US Army acquisition directives through NHTSA-equivalent defense channels and NATO standardization agreements shape permissible propellant formulations and insensitive munition compliance thresholds. The EU Green Deal's REACH chemical restrictions and emerging PFAS regulations are forcing reformulation of base bleed and tracer compositions. Stakeholders must monitor how dual-use export control tightening between the US State Department and EU member licensing authorities reshapes cross-border supply availability.
Market Dynamics
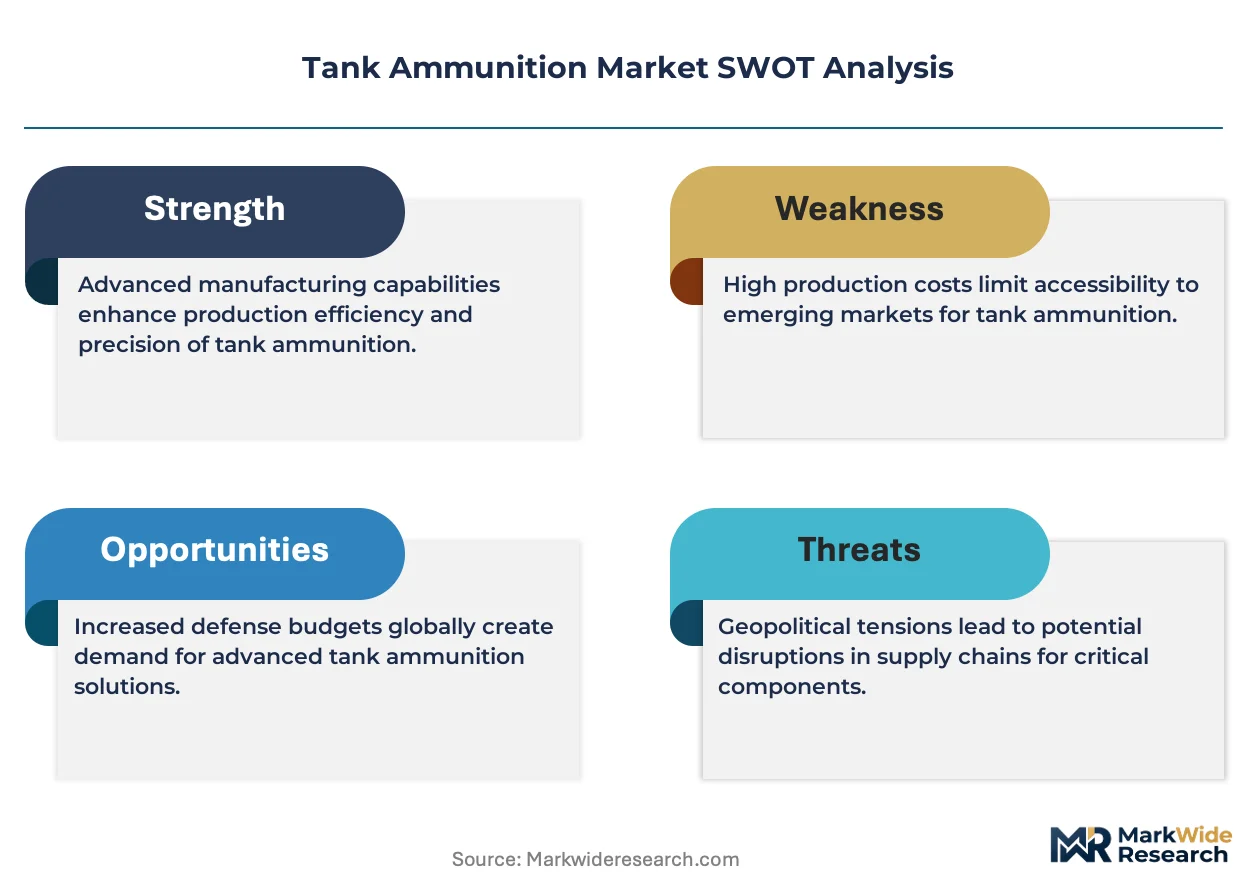
NATO capability targets and US Army modernization directives are concentrating procurement authority in government arsenals, compressing commercial sales cycles and forcing contractors toward multi-year framework agreements with embedded R&D co-funding clauses.
Growth Catalysts
- US Army Next Generation Combat Vehicle program:The initiative mandates 120mm ammunition stockpile expansion with performance thresholds exceeding current M829-series capabilities, directing multi-billion-dollar procurement through Army Contracting Command channels.
- REACH chemical reformulation mandates:EU Green Deal restrictions on base bleed and tracer compositions are accelerating insensitive munition development, creating compliant product lines eligible for transatlantic NATO standardization.
- Tungsten supply diversification:Kazakhstan and Vietnam mining expansion is reducing single-source dependency for armor-piercing penetrator feedstock, enabling volume scaling for DM-series and comparable kinetic energy rounds.
Market Restraints
- Depleted uranium processing concentration:US and UK facilities control 80% of weapons-grade DU machining capacity, constraining non-allied producers from matching unit economics on long-rod penetrators.
- Propellant nitrocellulose supply fragility:European chemical producers face feedstock volatility from cotton linter and wood pulp markets, inflating lot acceptance testing costs for composite charge formulations.
- Dual-use export licensing friction:US State Department ITAR and EU member state licensing divergence creates 90-180 day approval delays for 120mm and 125mm round transfers to non-NATO operators.
Strategic Opportunities
- Poland and Baltic states:These NATO frontline members are establishing domestic 120mm assembly lines through technology transfer agreements, creating captive demand for propellant and fuze subsystem suppliers.
- 140mm next-generation caliber convergence:Franco-German KNDS coordination on telescoped ammunition and autoloader integration opens supplier slots for advanced composite case manufacturers.
- US Infrastructure Investment and Jobs Act defense provisions:Congressional funding for ammunition industrial base resilience includes specific set-asides for insensitive munition production line modernization at government-owned facilities.
Industry Challenges
- Ballistician workforce scarcity:US Army Benét Laboratories and comparable European facilities face 15-year retirement cliffs among propellant combustion specialists with no accredited pipeline replacement.
- Lot acceptance testing timeline compression:NATO AQAP-2110 and US MIL-STD-810H environmental qualification protocols require 18-24 month validation cycles that misalign with urgent operational requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tank Ammunition Market |
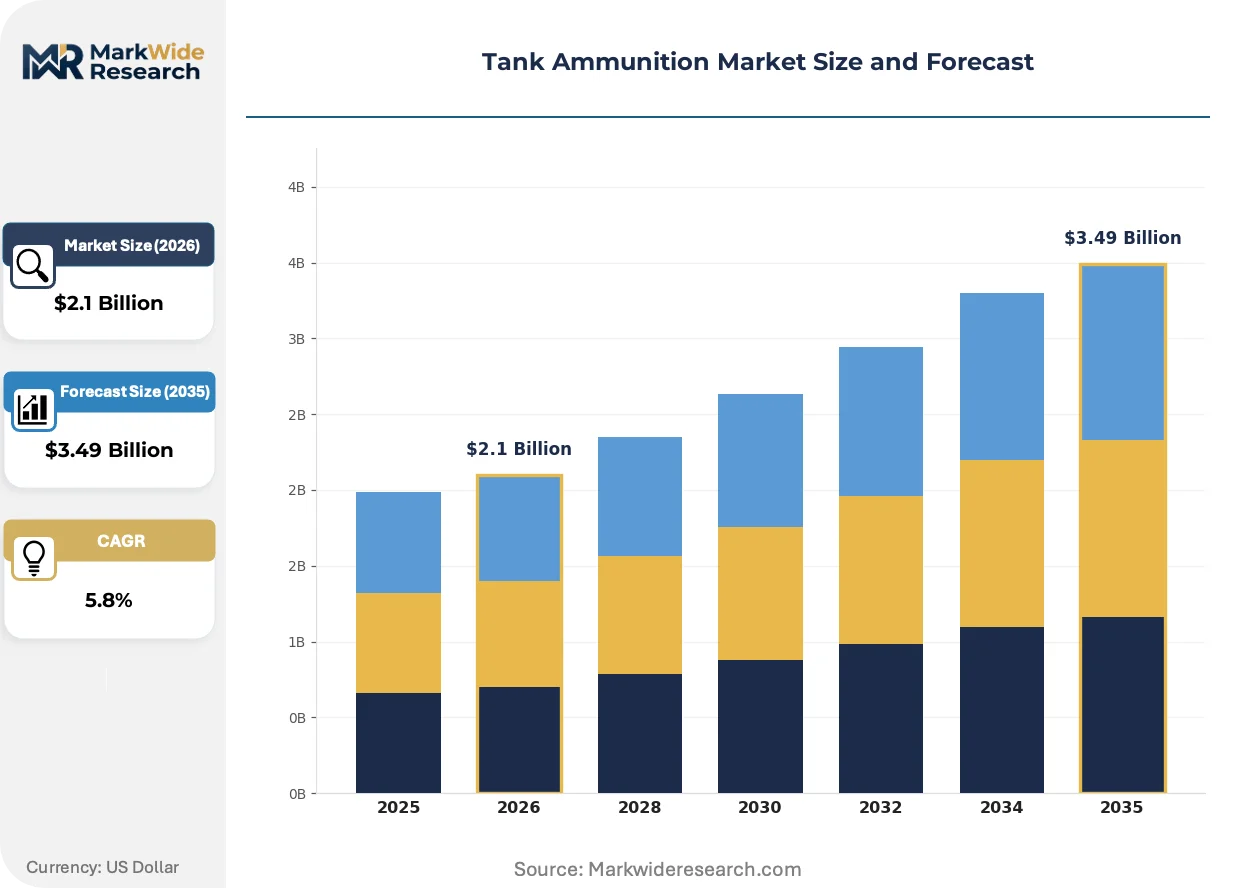
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armor-Piercing, High-Explosive, Incendiary, Practice, Target, Tracer Caliber: 105mm, 120mm, 125mm, 140mm, 152mm Delivery Mode: Cannon Shell, Guided Missile, Canister, Sabot, Sub-Caliber, High-Velocity End User: Armored Forces, Defense Contractors, Military Training Units, Security Agencies |
| Companies Covered | Rheinmetall, KNDS Group, General Dynamics Ordnance and Tactical Systems, FN Herstal, Nammo, BAE Systems, Hanwha Aerospace, Arsenal JSCo., Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tank Ammunition Market Trends and Innovations
Electronics integration into conventional munitions is redefining kill-chain architecture, while chemical compliance pressures and procurement centralization are restructuring supplier-competitor relationships across the value chain.
Programmable air-burst fuzes with millimeter-wave proximity sensors are collapsing the traditional separation between kinetic and chemical energy mission profiles. US Army Stryker and Abrams platform operators are fielding these rounds at brigade scale, enabling single ammunition types to address personnel, materiel, and aerial target sets without turret reload.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of base bleed compositions and tracer illuminants. German and French national regulators are coordinating transitional approval pathways, though ammunition lots manufactured before 2026 grandfathering deadlines face stranded inventory risk in Eastern European stockpiles.
Multi-year framework agreements with embedded spiral development clauses are displacing transactional spot procurement for armor-piercing rounds. US Army Contracting Command and UK Defence Equipment and Support are consolidating 120mm purchases under single-source IDIQ vehicles, compressing mid-tier suppliers into subsystem roles while prime contractors absorb integration risk.
Tank Ammunition Market Segmentation
Tank ammunition procurement patterns diverge sharply across technical specifications, with caliber selection and projectile type determining supply chain complexity and lifecycle service requirements. NATO standardization agreements and national stockpile mandates create distinct demand profiles that reshape supplier priorities across each segment category.
Product Type:
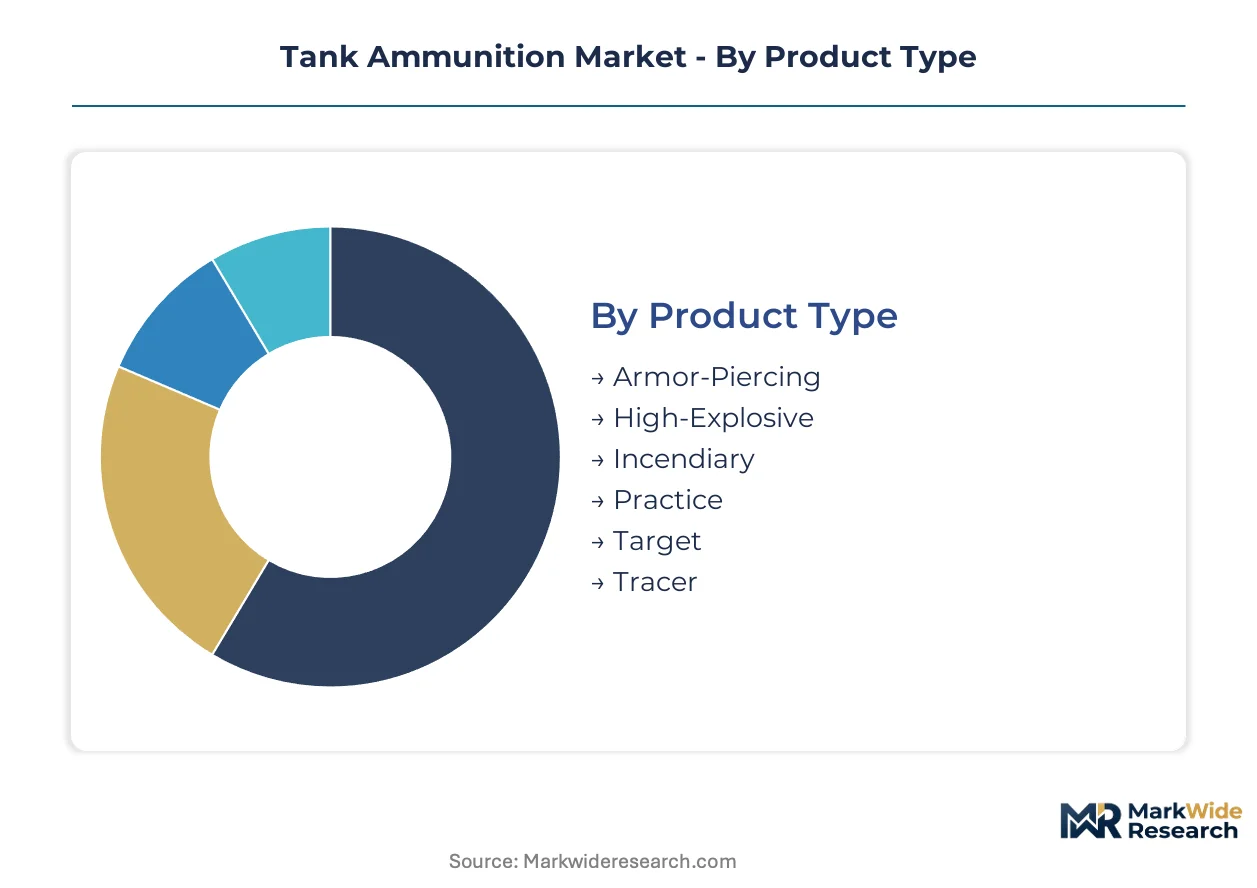
After-sales service intensity varies dramatically by product type, with armor-piercing rounds requiring penetrator integrity inspections and propellant stability monitoring across decades-long storage cycles.
- Armor-Piercing:Kinetic energy projectiles incorporate tungsten or depleted uranium penetrators engineered for reactive armor defeat at extended ranges. Demand concentrates in US Army and German Bundeswehr modernization programs where M829-series and DM-series upgrades mandate precision machining capabilities and lot traceability systems.
- High-Explosive:Fragmentation and blast-effect rounds retain volume dominance across armored forces procurement due to multi-target flexibility. Polish and Baltic states' stockpile expansion programs are driving framework agreements for insensitive munition variants compliant with evolving chemical regulations.
- Incendiary:Thermobaric and white phosphorus variants serve specialized anti-personnel and materiel destruction roles with restricted procurement channels.
- Practice:Reduced-cost training rounds with inert warheads and marker charges support live-fire qualification requirements without penetrator expense.
- Target:Instrumented projectiles with telemetry packages enable ballistic coefficient validation and fire control system calibration.
- Tracer:Illuminant-equipped rounds for trajectory observation face REACH-mandated composition reformulation affecting Eastern European inventory compatibility.
Armor-piercing holds the largest share; momentum sits with high-explosive insensitive munition variants.
Caliber:
Cost tier stratification across calibers reflects penetrator material intensity and chamber pressure engineering requirements, with 140mm systems commanding premium development funding despite limited fielded platforms.
- 120mm:NATO standard ammunition dominating transatlantic procurement through US Army and European land forces modernization. Rheinmetall and BAE Systems production networks anchor supply security with established propellant-to-projectile integration.
- 125mm:Soviet-legacy platform ammunition sustaining demand from former Warsaw Pact operators and export markets with distinct autoloader compatibility requirements.
- 105mm:Light armor and reconnaissance vehicle ammunition with declining procurement volume except in specific national upgrade programs.
- 140mm:Next-generation telescoped ammunition under Franco-German KNDS development for future main battle tank autoloader integration.
- 152mm:Limited production for specialized heavy armor applications with restricted NATO standardization progress.
120mm dominates procurement volume; 140mm claims the steepest expansion trajectory through development-phase investment.
Delivery Mode:
Application-specific delivery configurations determine integration complexity with platform fire control and autoloader systems, creating captive supplier relationships for specialized subcaliber and guided variants.
- Cannon Shell:Conventional full-caliber projectiles with rotating band obturation serving baseline armored engagement missions across all operator categories.
- Guided Missile:Precision munitions with millimeter-wave or laser seeker integration enabling beyond-line-of-sight engagement; US Army brigade-scale fielding is reshaping combined arms tactics.
- Canister:Multi-projectile anti-personnel rounds with flechette or spherical dispersion patterns for close-range defense.
- Sabot:Discarding petal assemblies enabling subcaliber penetrator launch at hypervelocity; tungsten supply diversification is reducing feedstock constraints for long-rod production.
- Sub-Caliber:Reduced-diameter projectiles optimized for specific armor defeat mechanisms with specialized fin stabilization.
- High-Velocity:Extended propellant charge configurations maximizing muzzle energy for next-generation gun systems.
Cannon shell retains foundational procurement status; guided missile variants are climbing the fastest through electronics integration priorities.
End User:
Customer type segmentation reveals divergent procurement authority structures, with government arsenals consolidating multi-year framework agreements while defense contractors absorb integration risk for subsystem suppliers.
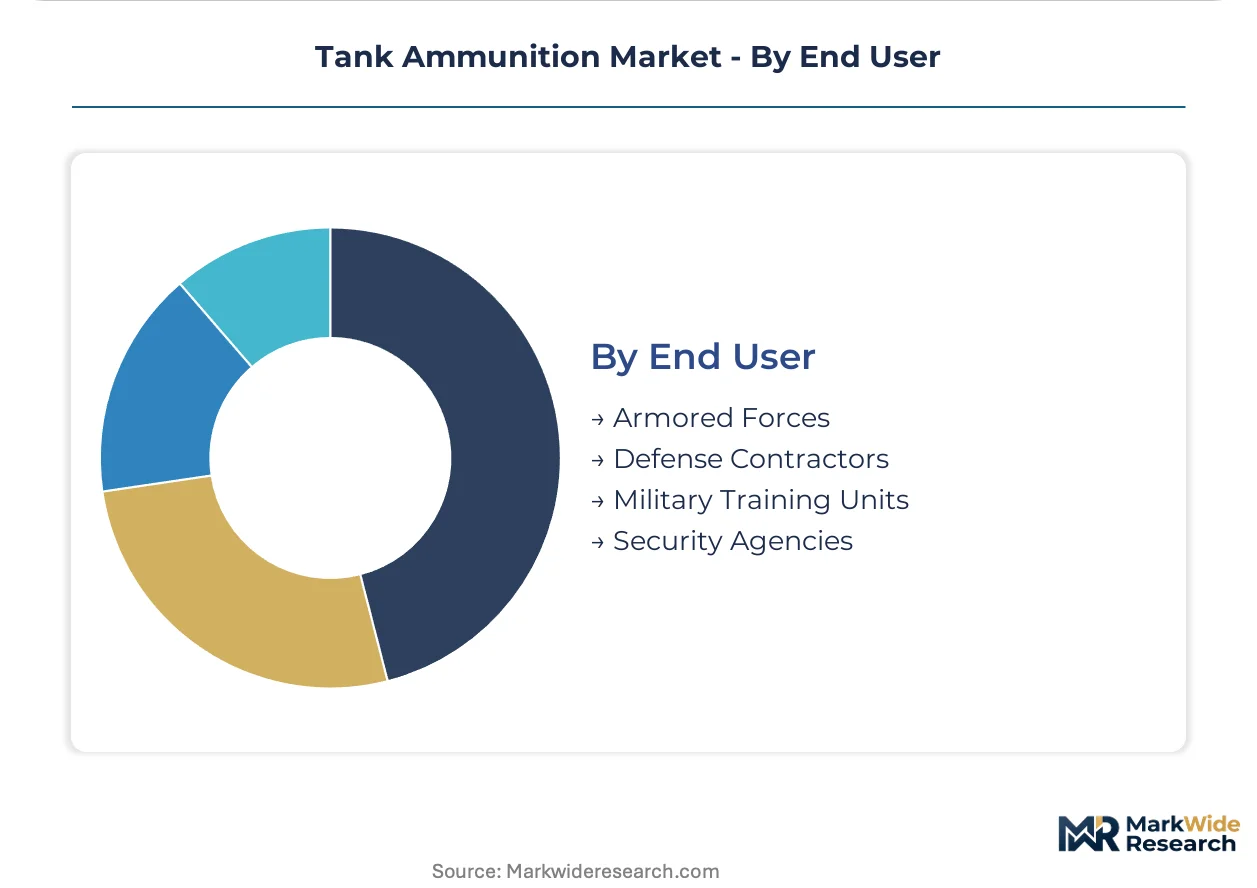
- Armored Forces:National military establishments with centralized ammunition stockpile management; NATO capability targets and US Army NGCV directives concentrate demand authority in government contracting channels.
- Defense Contractors:Prime and mid-tier suppliers procuring components for integration into complete round assemblies; multi-year IDIQ vehicles are compressing commercial sales cycles toward embedded R&D co-funding structures.
- Military Training Units:Specialized consumers of practice and reduced-range ammunition with distinct logistics and safety certification requirements.
- Security Agencies:Limited-volume procurement for armored vehicle-equipped border and critical infrastructure protection units with restricted access to armor-piercing variants.
Armored forces command procurement volume leadership; defense contractors are gaining share fastest through industrial base consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for tank ammunition diverges sharply across procurement channels. Government arsenals in NATO member states prioritize performance thresholds over unit cost, while export-dependent operators in former Warsaw Pact territories face hard budget constraints on 125mm replenishment.
United States
US Army Next Generation Combat Vehicle directives concentrate 120mm demand through Army Contracting Command multi-year IDIQ vehicles. ITAR licensing through the US State Department governs all cross-border transfers. Government-owned ammunition plants in Iowa and Tennessee anchor domestic propellant-to-projectile integration.
Germany
Bundeswehr modernization programs sustain premium procurement for DM-series armor-piercing rounds with tungsten penetrator requirements. EU REACH Annex XVII chemical restrictions on base bleed compositions force reformulation of legacy tracer stocks. Rheinmetall's integrated manufacturing footprint in Unterlüß consolidates NATO-standard 120mm supply security.
Poland
Frontline NATO positioning drives accelerated stockpile expansion through domestic 120mm assembly line construction. Polish national procurement channels prioritize insensitive munition variants compliant with emerging EU Green Deal chemical mandates. Technology transfer agreements with German industrial partners concentrate new capacity near the Baltic corridor.
United Kingdom
UK Defence Equipment and Support consolidates armor-piercing purchases under framework agreements with embedded spiral development clauses. Depleted uranium machining capacity at Aldermaston facilities constrains non-allied access to long-rod penetrator economics. BAE Systems' production network spans US-UK cross-border integration for fin-stabilized discarding sabot rounds.
South Korea
Hanwha Aerospace anchors Asia-Pacific 120mm demand through indigenous K2 Black Panther platform requirements. Korean Agency for Technology and Standards certification protocols shape permissible propellant formulations for export eligibility. Domestic nitrocellulose supply chains reduce feedstock volatility affecting European chemical producers.
Tank Ammunition Market Competitive Landscape
Capability concentration sits with integrated propellant-to-projectile manufacturers; scale advantage sits with government-contracting primes absorbing multi-year framework risk. The supplier base stratifies across three tiers: national champions with captive arsenals, mid-tier subsystem specialists, and emerging entrants securing technology transfer slots. Consolidation pressures favor prime contractors with embedded R&D co-funding structures. Cross-border licensing and joint venture formations represent the dominant competitive moves.
Within the integrated manufacturing tier, Rheinmetall and BAE Systems occupy positions defined by transatlantic production networks and NATO standardization alignment. KNDS Group represents Franco-German industrial consolidation archetypes coordinating cross-border R&D for next-generation 140mm systems. General Dynamics Ordnance and Tactical Systems anchors US government-contracting channels with Army-owned facility operation expertise.
| Leading Market Players |
|---|
| Rheinmetall |
| KNDS Group |
| General Dynamics Ordnance and Tactical Systems |
| FN Herstal |
| Nammo |
| BAE Systems |
| Hanwha Aerospace |
| Arsenal JSCo. |
| Northrop Grumman |
| Others |
Pricing and Supply Chain Analysis
The Baltic Sea corridor's freight cost volatility amplifies tungsten penetrator pricing premiums while compressing margins on high-explosive variants stocked in Eastern European arsenals. Armor-piercing round manufacturers exploit feedstock concentration to enforce volume-tiered contracts, whereas propellant suppliers absorb nitrocellulose volatility through indexed pricing clauses.
Pricing Analysis
After-sales service contracts spanning penetrator integrity inspections and propellant stability monitoring generate lifetime value multiples exceeding initial round sales. Three-tier pricing structure across armor-piercing, high-explosive, and practice ammunition separates NATO-standard certified lots from grandfathered REACH-noncompliant inventory and export-grade variants. Price differentiation hinges on insensitive munition certification status and tungsten supply chain traceability. Cost compression in high-explosive production is intensifying because Polish and Baltic assembly lines are absorbing volume previously sourced from Rheinmetall's premium-tier output. Export-dependent former Warsaw Pact operators exhibit highest price sensitivity; US Army Contracting Command channels demonstrate lowest elasticity due to performance-threshold mandates.
Supply Chain Analysis
Contract-manufacturing concentration for propellant charges sits with government-owned facilities in Iowa and Tennessee, plus Rheinmetall's Unterlüß integration campus. Geographic supply concentration centers on Germany for DM-series assembly, the United States for M829-series production, and Kazakhstan plus Vietnam for tungsten feedstock. Raw material dependencies encompass nitrocellulose from cotton linter markets, depleted uranium machining capacity concentrated at Aldermaston and US facilities, and electronic fuze components from South Korean semiconductor suppliers. Single-source vulnerability in depleted uranium long-rod penetrator machining constrains non-allied producers from matching unit economics. Distribution runs through NATO standardization agreements and Army Contracting Command IDIQ vehicles with embedded spiral development clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across NATO frontline states establishing domestic 120mm assembly capacity. Poland's technology transfer agreements with German industrial partners create subsystem supplier niches for propellant and fuze specialists previously locked out of prime contractor frameworks.
For Market Incumbents:Harden supply security through captive tungsten offtake agreements with Kazakhstan and Vietnamese mining expansion projects. Secure insensitive munition certification pipelines ahead of REACH Annex XVII grandfathering deadlines to strand competitor inventory. Absorb ballistician workforce scarcity risk through embedded R&D co-funding clauses in multi-year framework agreements with Army Contracting Command.
For New Entrants and Emerging Players:Poland and Baltic states' domestic assembly line construction represents the most penetrable geography for subsystem suppliers. Target propellant charge and electronic fuze integration slots opened by technology transfer agreements rather than competing on complete round assembly. Pursue joint venture formations with established German or US primes to bypass ITAR and EU licensing divergence barriers.
For Investors and Strategic Acquirers:REACH Annex XVII enforcement reshapes the acquisition landscape toward compliant product line owners with grandfathered inventory exposure. Five-to-ten-year viability favors subsystem specialists with insensitive munition formulation capabilities and NATO AQAP-2110 qualification track records. Watch for stranded inventory write-downs among Eastern European stockpile holders as 2026 chemical deadlines approach.
| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munition Certification | REACH Annex XVII compliance unlocks NATO standardization eligibility and transatlantic procurement access. |
| Tungsten Supply Agreement | Kazakhstan and Vietnamese mining partnerships reduce feedstock concentration risk for armor-piercing production. |
| Technology Transfer Partnership | Polish domestic assembly line construction creates captive demand for propellant and fuze subsystem suppliers. |
| Multi-Year Framework Contract | Army Contracting Command IDIQ vehicles compress commercial sales cycles and absorb integration risk. |
| Ballistician Workforce Pipeline | Embedded R&D co-funding with Benét Laboratories addresses 15-year retirement cliff in propellant combustion expertise. |
Research Methodology
Initial hypotheses were tested against primary input from Army Contracting Command procurement officers, propellant combustion specialists at Benét Laboratories, Bundeswehr modernization program managers, and Polish Ministry of Defence industrial policy directors and refined through secondary validation against NATO AQAP-2110 qualification records, EU REACH Annex XVII regulatory filings, US State Department ITAR licensing databases, and customs trade data for tungsten concentrate flows. Bottom-up round-level procurement tracking was triangulated with top-down national stockpile mandate aggregation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling caliber selection, projectile type, delivery mode configuration, and end-user procurement authority structure. CAGRs were derived from segmented volume build-ups reconciled against government arsenal budget authorization trajectories. Forecast inputs incorporated nitrocellulose feedstock price indices and dual-use export licensing approval timeline distributions.
Practitioners should monitor REACH enforcement acceleration, ITAR-EU licensing divergence resolution, and tungsten supply contract renegotiation patterns for early signals of forecast revision. Quarterly review of stranded inventory disclosures among Eastern European operators and insensitive munition certification approval velocities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Global Rockets and Missiles Market