
 Laminated Door Market | 2026-2036
Laminated Door Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Door Market Intelligence
The time-to-competency for skilled door installers and custom finishers is collapsing the traditional apprenticeship model, pushing manufacturers toward pre-finished systems. JELD-WEN leverages its extensive distribution network to serve large-scale construction, while Masonite differentiates through its focus on interior door design and material innovation. Hörmann sustains a strong position in the European commercial and industrial door sector through engineering and quality.
A laminated door consists of a core material, like MDF or wood, bonded with a decorative laminate sheet under high pressure. The laminate surface provides a durable, scratch-resistant, and aesthetically versatile finish for interior and exterior applications. Residential constructions represent the largest volume segment, but commercial complexes offer higher-margin opportunities. Material choice is application-specific, with wooden cores common in homes and PVC or aluminium variants used in high-traffic commercial facilities.
Product standards are shaped by frameworks like ISO 9001 for quality management and the EU's CE marking for market access. In the United States, EPA regulations on formaldehyde emissions from composite wood products influence material sourcing. Future competitive advantage will hinge on developing circular economy models for door lifecycle management and material reclamation.
Market Dynamics
The laminated door market's trajectory is defined by the intersection of aesthetic demand from the commercial building sector and tightening environmental regulations. This dynamic forces manufacturers to innovate with materials that offer design versatility while complying with standards for indoor air quality.
Growth Catalysts
- Urbanization in India:Rapid construction of residential and commercial complexes across India's metropolitan areas creates sustained volume demand for durable, cost-effective, and aesthetically flexible door solutions suitable for modern architectural designs.
- HPL Advancements:Continuous improvements in high-pressure laminate (HPL) manufacturing are yielding surfaces with superior scratch resistance, UV stability, and a wider array of textures and finishes, expanding applications in high-traffic environments.
- Hospitality Sector Expansion:The global build-out of hotels, resorts, and restaurants necessitates doors that meet stringent fire safety codes, offer high acoustic performance, and align with specific interior design themes, a combination well-served by laminated products.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of core inputs, including medium-density fiberboard (MDF), particleboard, and specialty adhesives, can compress manufacturer margins and create pricing instability for end-users.
- Substitution from Alternatives:In the premium residential segment, laminated doors face competition from solid wood, wood-veneer, and advanced composite doors, which are often perceived as offering superior longevity and a more traditional aesthetic.
- Regulatory Compliance Burden:Adhering to disparate international regulations, such as the EPA's formaldehyde emissions standards in the United States and the EU's CE marking requirements, increases testing costs and supply chain complexity.
Strategic Opportunities
- Circular Economy Integration:Developing verifiable circular models for door reclamation, core material recycling, and laminate separation presents a significant opportunity to appeal to green building projects and comply with emerging sustainability mandates.
- Smart Technology Embedding:Incorporating smart features like biometric scanners, electronic locks, and occupancy sensors directly into the door structure during manufacturing can create high-margin products for the smart home and commercial security markets.
- African Market Penetration:Expanding into burgeoning urban centers in countries like Nigeria and Kenya offers a new growth frontier, driven by infrastructure investment and a rising middle class demanding modern housing and commercial spaces.
Industry Challenges
- Installer Skill Deficiencies:The industry confronts a persistent shortage of properly trained installers capable of handling pre-finished systems and complex hardware integrations, leading to performance issues and reputational risk for manufacturers.
- Logistical Complexity:Managing global supply chains for diverse raw materials exposes manufacturers to geopolitical risks, shipping delays, and tariff impacts, which can disrupt production schedules and inflate inventory costs.
- Certification Delays:Achieving specific performance certifications, such as fire ratings or acoustic insulation standards like STC ratings, is a time-consuming and expensive process that can delay market entry for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Door Market |
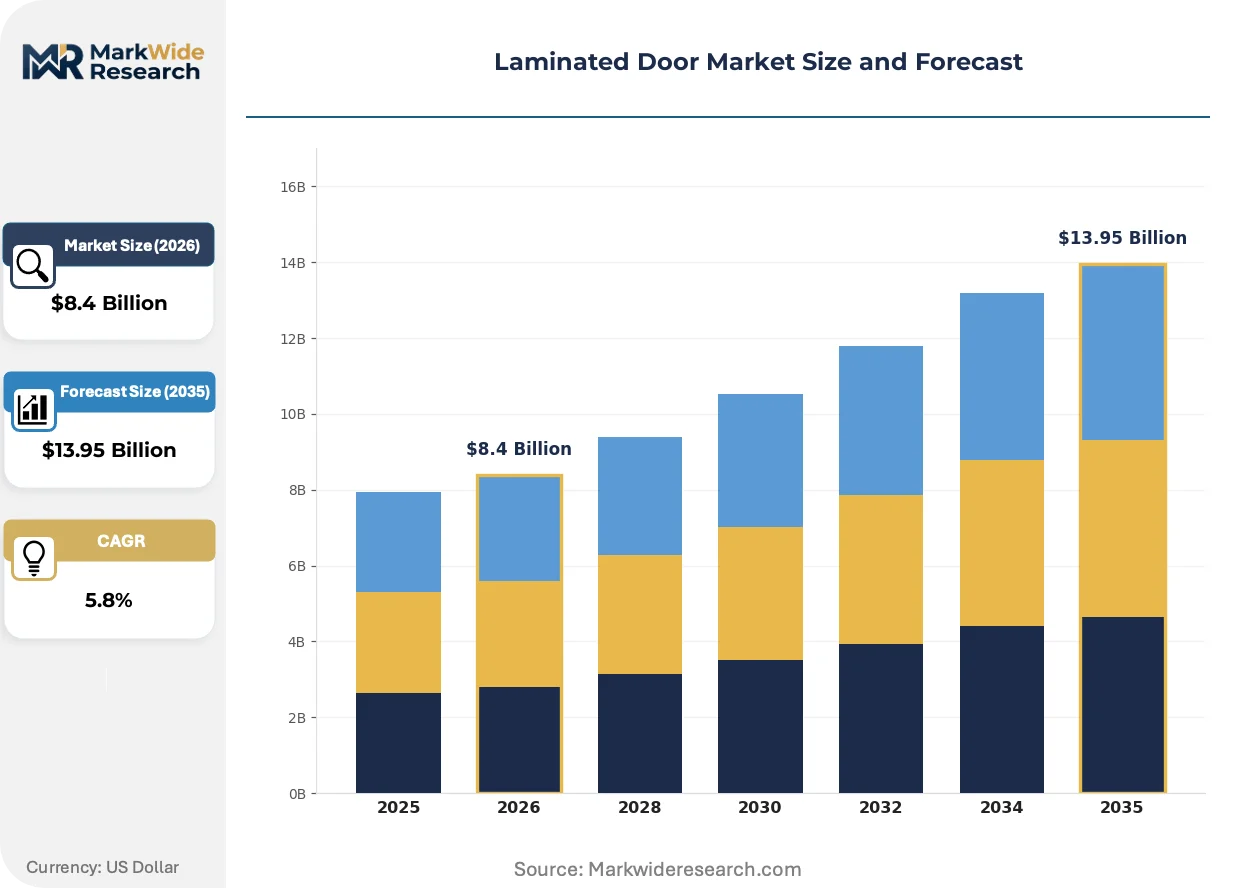
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flush Doors, Panel Doors, French Doors, Sliding Doors, Folding Doors Material: Wooden, MDF, PVC, Stainless Steel, Aluminium Application: Residential Constructions, Commercial Complexes, Educational Institutions, Hospitality Facilities, Religious Buildings End User: Contractors, Interior Designers, Retailers, Real Estate Developers, Facility Managers |
| Companies Covered | Pella Corporation, Therma-Tru, Masonite, Hörmann, ProVia, JELD-WEN, Marvin, Schüco International KG, Andersen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Door Market Strategic Shifts & Innovations
Material science advancements are converging with digital integration, fundamentally altering product capabilities and value propositions. Sustainability mandates are simultaneously compelling manufacturers to re-evaluate their entire value chain, from raw material sourcing to end-of-life product management.
Micro-sensor technology, including impact and humidity sensors, is being integrated within the core layers of laminated doors. Commercial facilities management and high-end residential developers adopt these features for predictive maintenance and security monitoring. This integration is miniaturizing the external hardware footprint, creating sleeker designs and embedding smart functionality directly into the door structure itself.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is forcing manufacturers to disclose detailed lifecycle environmental impacts. This mandate requires greater transparency in sourcing composite wood, adhesives, and laminates, pushing for materials with lower embodied carbon. Producers targeting the European commercial construction market are most affected, now investing in Environmental Product Declarations (EPDs) to maintain access.
A significant behavioral shift is occurring among large-scale builders, who now prioritize pre-finished door systems over unfinished components to accelerate project completion. This disrupts the traditional model of on-site finishing, reducing dependency on skilled trade labor at the construction site. The change is most pronounced in large, multi-family residential projects in North America and Western Europe, where compressed timelines are standard.
Laminated Door Market Segmentation
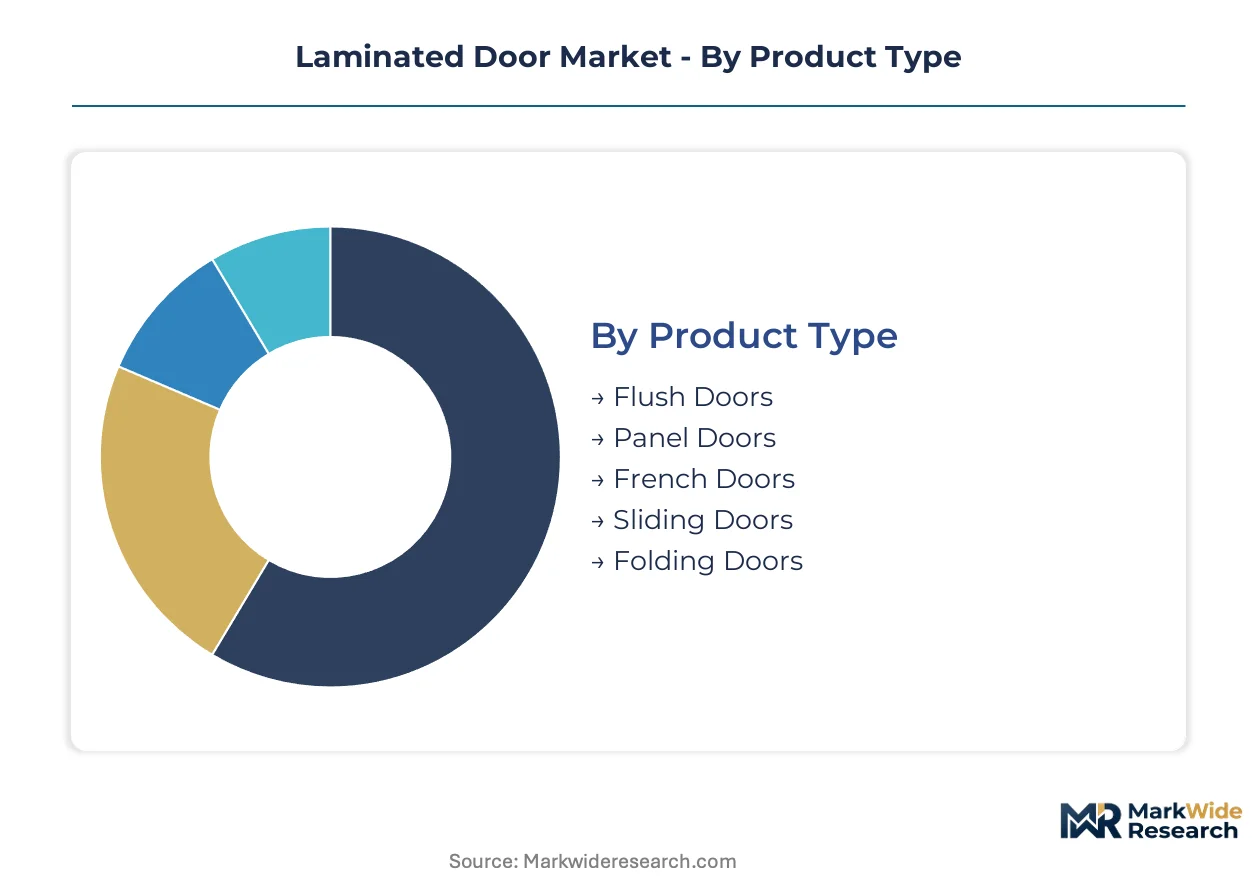
The segmentation of the laminated door market reveals distinct product characteristics, material compositions, and end-use applications. Understanding these divisions allows manufacturers to tailor offerings for specific customer needs and market dynamics. This granular view highlights areas of concentrated demand and evolving consumer preferences.
Product Type:
The geographic spread of product types varies, with some designs dominating local markets while others see broader international adoption.
- Flush Doors:These doors feature a simple, flat surface, often constructed with a solid or hollow core and laminated finish. Demand for flush doors is concentrating in high-volume residential projects in India due to their cost-effectiveness and ease of installation.
- Sliding Doors:Designed to slide horizontally along a track, these doors maximize space utilization in compact urban dwellings and commercial offices. Their adoption is accelerating across Western Europe and North America, driven by modern architectural trends and space-saving requirements.
- Panel Doors:Characterized by their classic framed construction with recessed or raised panels, panel doors offer a traditional aesthetic.
- French Doors:Featuring multiple glass panes set into a frame, French doors provide aesthetic appeal and allow light transmission, popular in residential extensions.
- Folding Doors:These doors consist of several panels that fold against each other, suitable for dividing large spaces or creating wide openings.
Flush Doors commands the established base. The steepest expansion runs through Sliding Doors.
Material:
Material choices are heavily influenced by application-specific performance requirements and cost considerations across different construction tiers.
- Wooden:Derived from various timber species, wooden cores offer natural strength and thermal insulation properties. They remain a preferred choice for premium residential applications in countries like the United States and Germany, valued for their perceived quality and longevity.
- MDF:Medium-density fiberboard cores provide a smooth, stable substrate for lamination, offering excellent design flexibility and cost efficiency. Builders in China and Brazil frequently specify MDF laminated doors for large-scale commercial and residential developments.
- PVC:Polyvinyl chloride materials offer high moisture resistance and durability, making them suitable for bathrooms and exterior applications in humid climates.
- Stainless Steel:Used primarily for specialized applications requiring high security or hygiene, such as industrial facilities and healthcare settings.
- Aluminium:Lightweight and corrosion-resistant, aluminium frames are often integrated into laminated doors for commercial entrances and partition systems.
Wooden materials retain significant market share. MDF variants demonstrate robust volume growth.
Application:
The profitability margins for laminated doors vary significantly depending on the end-use application and project scale.
- Residential Constructions:This segment encompasses doors for single-family homes, multi-family apartments, and housing developments. The large volume demand in India and Southeast Asia for new residential units fuels this market, prioritizing cost-effective and durable solutions.
- Hospitality Facilities:Hotels, resorts, and restaurants require doors that combine aesthetic appeal with stringent performance criteria, including fire ratings and acoustic insulation. High-end projects in the UAE and Singapore often specify custom laminated doors for their design versatility and compliance.
- Commercial Complexes:Office buildings, retail spaces, and corporate campuses utilize laminated doors for their durability and consistent appearance.
- Educational Institutions:Schools and universities require resilient doors capable of withstanding high traffic and providing sound attenuation.
- Religious Buildings:Temples, mosques, and churches often demand custom-designed laminated doors that align with specific architectural and aesthetic traditions.
Residential Constructions drives volume demand. Hospitality Facilities delivers higher average revenue per unit.
End User:
The procurement patterns for laminated doors are shaped by the purchasing power and project influence of various end-user types.
- Contractors:General contractors and construction firms directly procure laminated doors for their projects, often in large quantities for commercial and residential developments. Their purchasing decisions prioritize bulk pricing, delivery timelines, and product certifications in the United States and Canada.
- Real Estate Developers:These entities specify door types and materials during the planning and design phases of large-scale residential and commercial properties. Developers in China and the UK seek doors that enhance property value and meet modern design standards.
- Interior Designers:Influencing aesthetic and functional choices, interior designers recommend specific laminated door styles and finishes to clients.
- Retailers:Building material retailers and home improvement stores supply individual customers and small-scale builders with a range of laminated door options.
- Facility Managers:Responsible for maintaining existing buildings, facility managers purchase laminated doors for replacements, renovations, and upgrades.
Contractors represent the largest direct procurement channel. Real Estate Developers increasingly dictate product specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for laminated doors varies significantly across geographies, with some regions prioritizing cost-effectiveness for high-volume residential builds while others focus on aesthetic and performance features for commercial projects. India's rapid urbanization drives demand for durable, affordable door solutions. Western Europe and North America increasingly adopt space-saving sliding door systems.
India
Rapid construction of residential and commercial complexes across India's metropolitan areas creates sustained volume demand for durable, cost-effective door solutions. The PLI scheme for manufacturing supports local production capabilities. New Delhi and Mumbai witness extensive housing projects requiring efficient and modern door installations.
United States
Modern architectural trends and compressed timelines in multi-family residential projects accelerate the adoption of pre-finished door systems. EPA regulations on formaldehyde emissions influence material sourcing and product development. Construction hubs like Dallas and Atlanta prioritize factory-finished door solutions for rapid project completion.
Germany
Germany's focus on engineering and quality sustains a strong position in the commercial and industrial door sector. CE marking requirements ensure product compliance for market access throughout the European Union. The Rhine-Ruhr region sees consistent demand for high-performance laminated doors in new commercial facilities.
China
Builders frequently specify MDF laminated doors for large-scale commercial and residential developments due to cost efficiency and design flexibility. China's national GB standards ensure product quality and safety for consumers. The Yangtze River Delta region experiences substantial demand from new urban developments and infrastructure projects.
United Arab Emirates
High-end hospitality projects necessitate doors that meet stringent fire safety codes and align with specific interior design themes. The country's national building codes enforce fire-rated door standards for public and commercial spaces. Dubai and Abu Dhabi's luxury hotel developments feature custom laminated door specifications for their design versatility.
Laminated Door Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the laminated door market. This market exhibits a tiered consolidation, with major manufacturers leveraging extensive distribution networks. Companies pursue strategic partnerships to expand product portfolios and engage in capacity expansion to meet regional demand. Portfolio diversification remains a key competitive move for players targeting diverse end-use applications.
At the scale-driven end, JELD-WEN leverages its extensive distribution network to serve large-scale construction projects across North America. Masonite differentiates through its focus on interior door design and material innovation, exemplifying a specialist approach to specific aesthetic segments. Hörmann sustains a strong position in the European commercial and industrial door sector, anchoring the high-quality engineering archetype with its robust product offerings.
| Leading Market Players |
|---|
| Pella Corporation |
| Therma-Tru |
| Masonite |
| Hörmann |
| ProVia |
| JELD-WEN |
| Marvin |
| Schüco International KG |
| Andersen Corporation |
| Others |
Cost & Logistics Intelligence
Manufacturing scale underwrites competitive pricing for laminated doors, shaping both supply concentration and price floors across high-volume segments. This scale allows large players to optimize material sourcing and production efficiency, influencing market entry barriers for smaller manufacturers.
Pricing Analysis
Project-based contracts dominate pricing for commercial and large-scale residential laminated door installations. Price differentiation stems from the product's fire rating and acoustic insulation certifications, alongside the customization level required. Pricing pressure stems from raw material price volatility, particularly for MDF and specialty adhesives. Residential construction buyers exhibit the highest price sensitivity, prioritizing cost-effective flush door solutions.
Supply Chain Analysis
Global shipping delays and port congestion represent a persistent chokepoint for raw material delivery and finished product distribution. Supply concentration draws heavily from manufacturing hubs in China and India, which produce core materials like MDF and HPL. The supply chain relies on consistent access to composite wood products, decorative laminates, and specialized adhesives. Commodity price volatility for these inputs poses a significant structural risk. Distribution runs through a mix of direct sales to contractors and real estate developers, alongside specialist building material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated door market presents a capability-scarcity story, particularly concerning skilled installation and sustainable material science expertise.
For Market Incumbents: Secure long-term supply agreements for core materials like MDF and HPL to mitigate raw material price volatility. Invest in automated pre-finishing systems to reduce dependency on skilled on-site labor, addressing installer skill deficiencies. Focus R&D on developing circular economy models for material reclamation, countering emerging sustainability mandates. Expand distribution networks in high-growth urban centers across India to capitalize on residential construction volume.
For New Entrants and Emerging Players: Lead with smart technology integration, embedding biometric scanners and occupancy sensors into door structures for high-margin commercial security applications. Target burgeoning urban centers in Africa, specifically Nigeria and Kenya, offering modern, durable, and aesthetically versatile door solutions. Differentiate through rapid certification attainment for fire ratings and acoustic performance, appealing to hospitality and commercial projects. Emphasize innovative HPL designs with enhanced scratch resistance and UV stability.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with strong material science capabilities. Focus on acquiring companies demonstrating verifiable circular economy models and advanced smart door technology. Long-term viability hinges on companies that can navigate tightening environmental regulations and secure sustainable raw material sourcing. The signal to watch is the adoption rate of EPDs and circularity certifications among European commercial construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Automated Pre-finishing | Accelerates project completion for large-scale builders and reduces reliance on scarce skilled labor. |
| Develop Circular Economy Models | Aligns with global sustainability mandates and appeals to green building project specifications. |
| Integrate Smart Technology | Creates high-margin products for smart home and commercial security markets, expanding value proposition. |
| Expand African Market Presence | Captures new growth from infrastructure investment and rising middle-class demand in untapped regions. |
| Secure Long-term Raw Material Contracts | Mitigates price volatility for core inputs like MDF and HPL, stabilizing production costs. |
Research Approach
A standing panel of architects, general contractors, manufacturing executives, and facility managers provided ongoing calibration for market assumptions and validation of emerging trends. This study combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Secondary sources included government construction databases, company financial filings, industry association reports, and academic research on material science.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, application, end-user, and regional consumption patterns. Compound annual growth rates were derived from historical data and projected market drivers. Urbanization rates in India and commercial construction spending in the UAE served as key forecast inputs.
Underlying assumptions cover stable geopolitical conditions and consistent raw material availability, with deviation risk concentrated in unforeseen regulatory shifts or sustained logistical disruptions. Practitioners should keep alternative scenarios live as global economic conditions and trade policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Kids Table and Chair Market
Furniture
China Home Furniture Market
Furniture
US Contract Furniture and Furnishing Market
Furniture
Pedicure Chair Market
Furniture
Bounding Table Market
Furniture
North America RTA Furniture Market
Furniture
Bar Stools Market
Furniture
GCC Home Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
HORECA Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Canada Home Furniture Market