
 Saudi Arabia Home Furniture Market | 2026-2036
Saudi Arabia Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Home Furniture Market Analytics
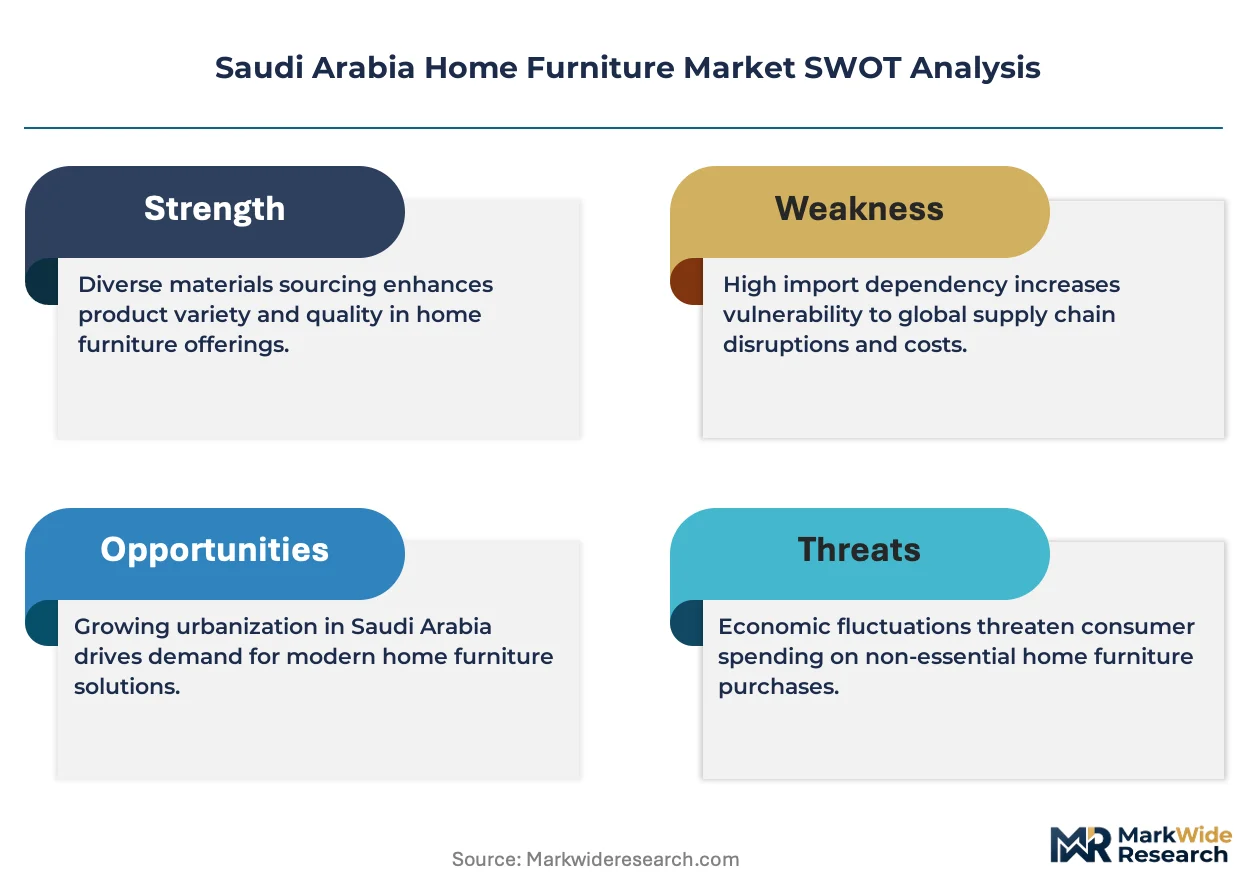
SFDA furniture material safety certification is unwinding competitive access for imported brands entering the Kingdom. Danube Home leverages its vertically integrated supply chain across GCC manufacturing hubs to sustain price competitiveness in mid-market segments. Royal Furniture anchors its position through deep showroom penetration in secondary cities where mall-based retail still dominates consumer purchase behavior.
Saudi Arabia home furniture encompasses movable residential fixtures engineered from engineered wood substrates, solid timber, metal framing, and synthetic textiles, typically dimensioned to standard room modules and finished for interior climate conditions. The category serves primary dwelling outfitting across villa, apartment, and compound housing typologies prevalent in the Kingdom. Wood material segments command margin pools given local joinery heritage and consumer preference for solid-wood statement pieces in formal reception areas. Modern style collections represent the fastest-growing orientation as younger households in Riyadh and Jeddah shift from ornate traditional profiles toward minimalist Nordic and Italian-influenced lines. Online retail distribution is displacing showroom dependency for repeat purchases and accessory categories, though big-ticket item conversion still requires tactile verification.
The Saudi Building Code mandates fire-retardant upholstery standards and structural stability testing that filter which overseas manufacturers qualify for commercial import. SFDA chemical emission protocols for lacquers, adhesives, and fabric treatments further constrain supplier eligibility and extend product registration timelines. MOHAP building permit data and municipal housing delivery schedules signal where demand clusters will form, enabling inventory pre-positioning ahead of handover waves. Stakeholders must monitor Riyadh Region municipality zoning changes that reclassify residential districts and redirect furniture demand geographically.
Market Dynamics
SFDA furniture material safety certification and Saudi Building Code fire-retardant mandates are compressing import eligibility timelines, forcing overseas manufacturers to restructure pre-market testing protocols or surrender shelf space to GCC-based producers with vertically controlled supply chains.
Growth Catalysts
- Riyadh megaproject pipeline:Municipal housing delivery schedules in Diriyah Gate and Qiddiya are generating concentrated demand waves for modular kitchen systems and fitted wardrobes.
- SFDA streamlined registration:Digital submission portals for chemical emission testing are reducing product clearance cycles for compliant manufacturers.
- Engineered wood substrate adoption:Moisture-resistant particleboard technologies are displacing solid timber in humidity-exposed secondary bedrooms and service quarters.
Market Restraints
- Import freight cost volatility:Red Sea shipping lane disruptions are inflating landed costs for European upholstery suppliers serving Jeddah and Yanbu distribution hubs.
- Saudi Building Code testing bottlenecks:Limited in-Kingdom fire-resistance certification laboratories are extending product launch timelines by four to eight weeks.
- Domestic joinery labor scarcity:Filipino and Indian skilled carpenter visa restrictions are constraining Riyadh-based custom furniture workshop capacity.
Strategic Opportunities
- Eastern Province housing stock:Dammam and Khobar villa completions are outpacing furniture retail penetration, creating white space for showroom expansion beyond mall corridors.
- MOHAP green building incentives:Energy-efficient fixture mandates in new residential permits are pulling demand toward LED-integrated cabinetry and low-VOC finishes.
- Direct-to-developer contracting:Bulk procurement agreements with Saudi Real Estate Refinance Company-financed projects are bypassing traditional retail markups.
Industry Challenges
- SFDA chemical retesting requirements:Reformulation of adhesives or lacquers triggers full re-certification cycles, freezing inventory turnover for six-month periods.
- Showroom-to-warehouse coordination:Big-ticket item tactile verification demands are forcing redundant inventory positioning across Riyadh, Jeddah, and Dammam nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Home Furniture Market |
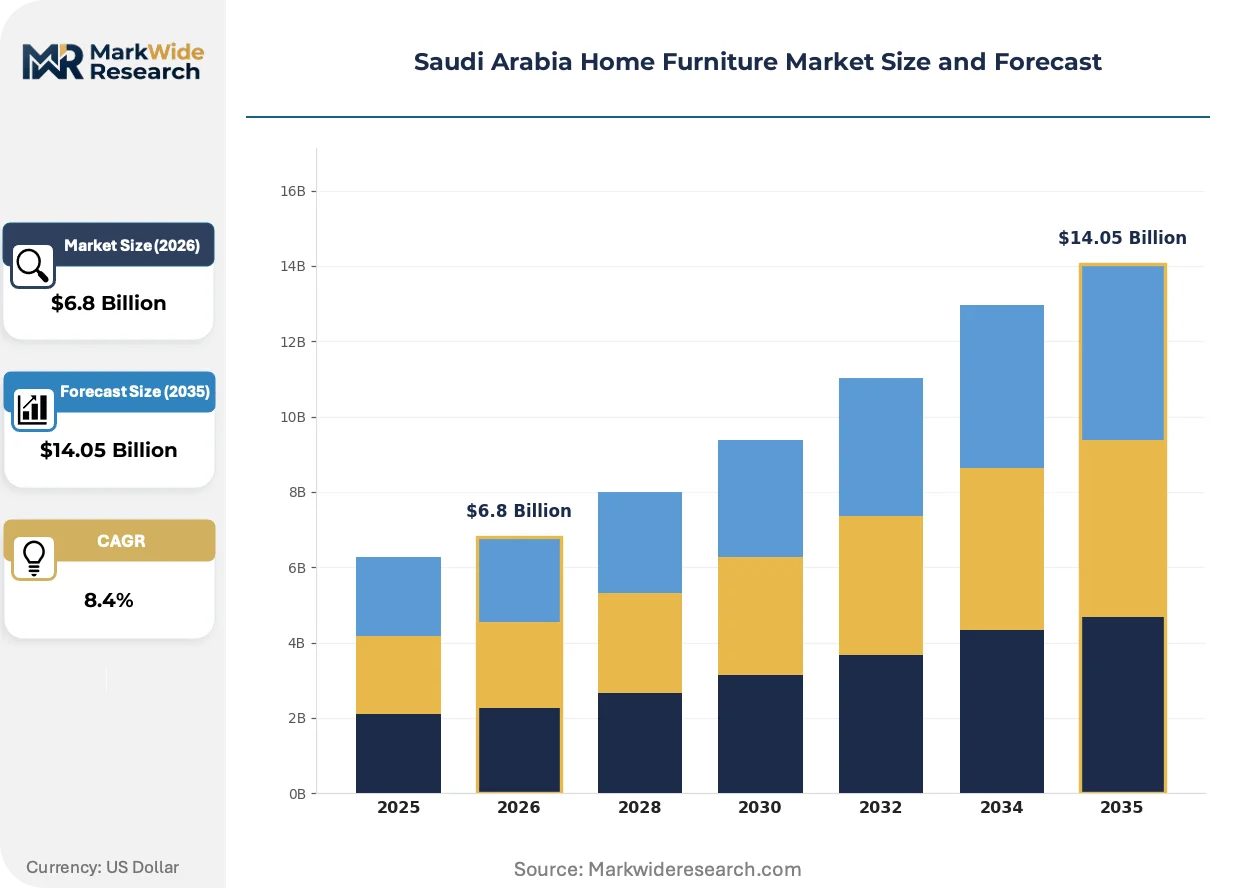
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Plastic, Fabric Style: Traditional, Modern, Contemporary, Vintage Distribution Channel: Online Retail, Showrooms, Wholesale, Specialty Stores |
| Companies Covered | Danube Home, Royal Furniture, IKEA, Pottery Barn, Al-Abdulkader Furniture Co. Ltd, Home Centre, Marina Home, IDdesign, PAN Emirates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Home Furniture Market Evolving Landscape
Digital configuration tools and climate-adaptive materials are compressing traditional design-to-delivery cycles while SFDA emission protocols and Saudi Building Code amendments are rewiring supplier qualification criteria.
Smart furniture with embedded wireless charging and ambient lighting control is bifurcating the premium segment. Younger households in Riyadh's northern districts are specifying these units for home office conversions. This technology is compressing margins for conventional case goods while creating service revenue streams through firmware updates.
SFDA chemical emission protocols for lacquers and fabric treatments are tightening supplier eligibility. Manufacturers reformulating adhesives to meet reduced formaldehyde thresholds are securing priority clearance at Saudi Customs. Upholstery producers in Jeddah's industrial zone are absorbing the highest compliance costs due to fabric treatment complexity.
Millennial buyers are bypassing mall showrooms for Instagram-curated direct purchases. Secondary city consumers in Tabuk and Hail still demand tactile verification for dining sets and sofas. Riyadh's online furniture penetration is deepest in accessory and lighting categories where return logistics are manageable.
Saudi Arabia Home Furniture Market Segmentation
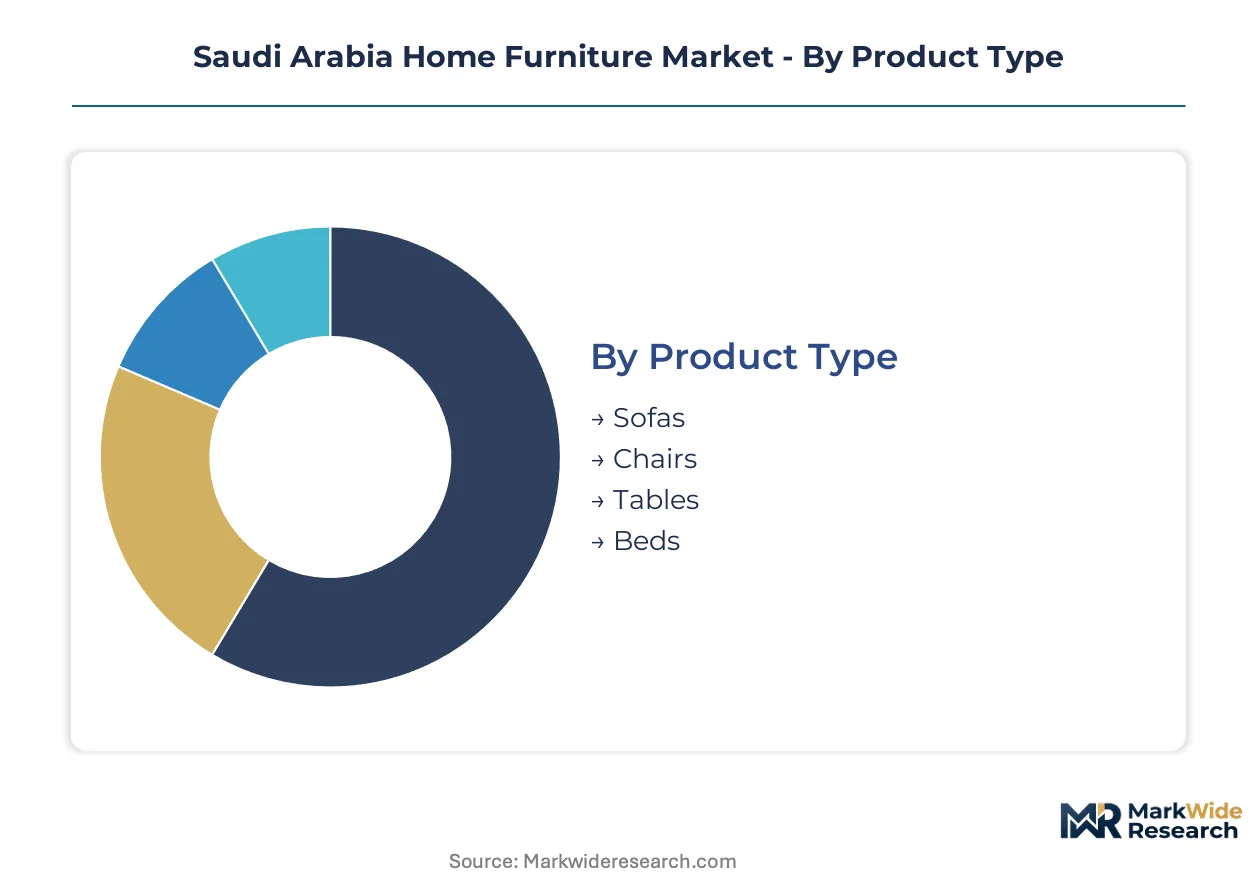
Saudi Arabia's home furniture market fragments across four intersecting dimensions that determine channel economics and margin capture. Product type and material composition dictate fulfillment complexity, while style orientation and distribution channel selection shape customer acquisition costs across Riyadh, Jeddah, and Dammam clusters.
Product Type:
Channel-mix varies sharply by product category, with big-ticket items demanding tactile verification while accessories migrate online.
- Sofas:Upholstered seating systems with fire-retardant foam cores and hardwood frames, typically commanding the highest per-unit margins in villa reception areas. Riyadh's northern districts and Jeddah's corniche developments are absorbing premium sectional configurations as primary residence handovers accelerate.
- Beds:Platform and storage-integrated frames with moisture-resistant substrates for coastal humidity exposure. Dammam and Khobar villa completions are driving demand for king-size upholstered headboards with integrated USB charging.
- Chairs:Dining and accent seating spanning solid timber to metal-tube construction. Secondary cities Tabuk and Hail still route the majority of purchases through mall-based specialty stores.
- Tables:Dining, coffee, and console variants in engineered wood and marble-composite surfaces. Online penetration is deepest in this category where dimensional standardization reduces return rates.
Sofas dominate installed base. Beds is where expansion concentrates.
Material:
Cost tier stratification separates premium solid-wood positioning from volume-engineered alternatives.
- Wood:Solid timber and engineered substrates including moisture-resistant particleboard for secondary bedrooms. Local joinery heritage in Riyadh sustains preference for oak and walnut statement pieces in formal majlis spaces.
- Metal:Powder-coated steel and aluminum framing for outdoor and service quarter applications. Jeddah's humidity-exposed coastal housing stock is accelerating corrosion-resistant specification.
- Fabric:Natural and synthetic textiles for upholstery with SFDA chemical emission certification requirements. Reformulation costs are compressing margins for Jeddah-based upholstery producers.
- Plastic:Polypropylene and polycarbonate for outdoor and children's furniture segments. Lowest compliance burden under Saudi Building Code structural standards.
Wood dominates installed base. Fabric is climbing the fastest.
Style:
Customer type bifurcation separates generational preferences between ornate traditional and minimalist contemporary lines.
- Modern:Clean-lined Nordic and Italian-influenced profiles with concealed hardware and neutral palettes. Younger households in Riyadh's King Abdullah Financial District and Jeddah's Al Andalus corridor are specifying these for primary residence outfitting.
- Traditional:Ornate carved wood and rich textile treatments reflecting regional heritage aesthetics. Still commands majority share in Qassim and Asir regions where extended family housing patterns persist.
- Contemporary:Transitional profiles blending traditional scale with modern materiality. Gaining traction in compound housing typologies across Dhahran and Jubail.
- Vintage:Reclaimed and reproduction pieces targeting expatriate and design-professional segments. Concentrated in Jeddah's Al Balad restoration-adjacent districts.
Traditional dominates installed base. Modern is gaining share fastest.
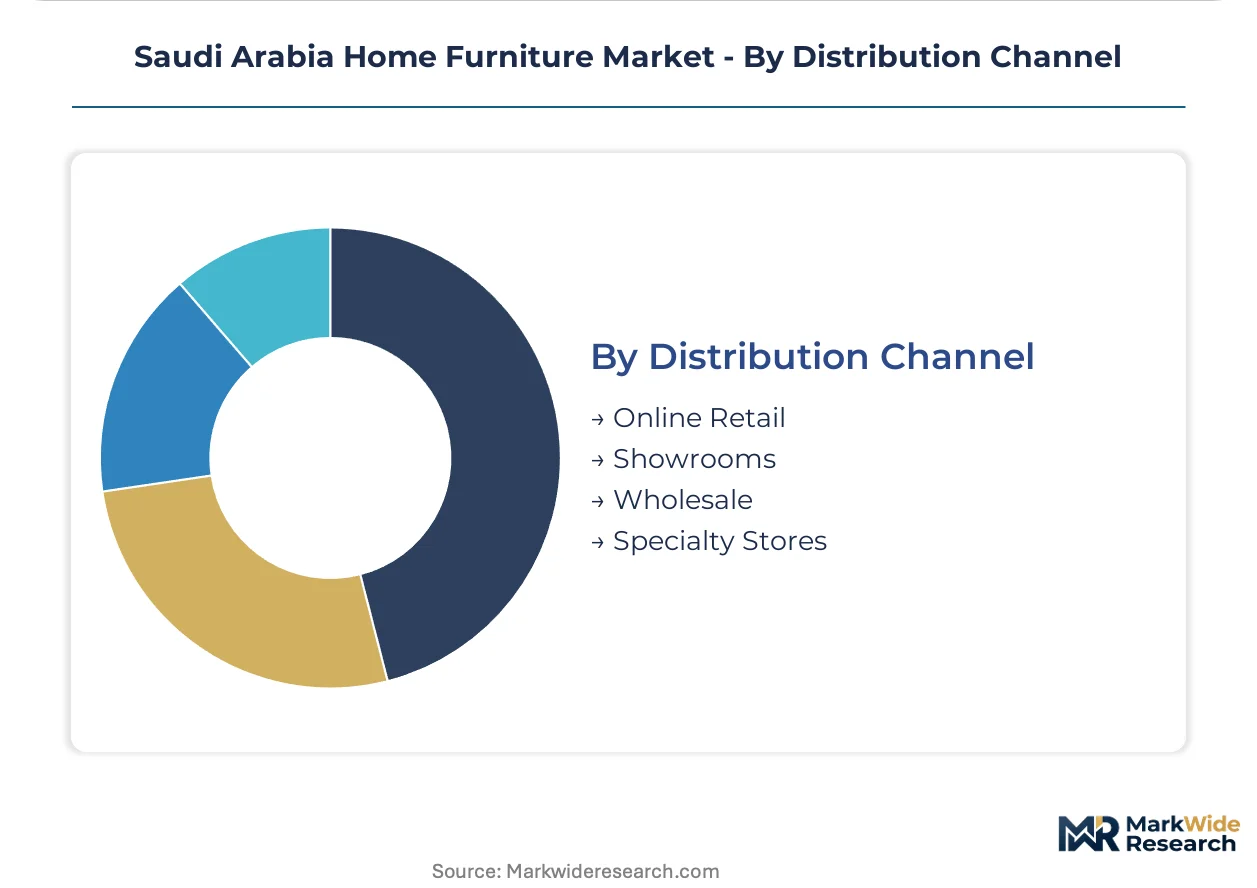
Distribution Channel:
Volume concentration and margin capture separate high-touch showroom models from scaled online fulfillment.
- Showrooms:Mall-based and flagship retail with tactile verification for big-ticket conversion. Royal Furniture and Danube Home anchor this channel with deep penetration in Riyadh's Riyadh Park and Jeddah's Red Sea Mall.
- Online Retail:Digital-native and omnichannel platforms capturing accessory and repeat purchase volume. Riyadh's online penetration leads the Kingdom for lighting and soft furnishing categories.
- Specialty Stores:Category-focused retailers for kitchen systems and fitted wardrobes. Diriyah Gate and Qiddiya megaproject procurement is routing through this channel for bulk specification.
- Wholesale:Developer-direct and contractor supply for multi-unit residential fit-out. Saudi Real Estate Refinance Company-financed projects are bypassing retail markups through this channel.
Showrooms dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals and newly formed households in Riyadh's northern districts and Jeddah's corniche zones constitute the dominant buyer archetype, driving specification for modular systems and contemporary profiles across the Kingdom's primary demand clusters.
Riyadh
Diriyah Gate and Qiddiya megaproject handovers are generating concentrated demand waves for fitted kitchens and built-in wardrobes. SFDA streamlined digital submission portals are reducing product clearance cycles for compliant manufacturers supplying these developments. The King Abdullah Financial District anchors premium furniture specification as young professionals outfit primary residences.
Eastern Province
Dammam and Khobar villa completions are outpacing furniture retail penetration, creating white space for showroom expansion beyond traditional mall corridors. MOHAP green building incentives in new residential permits are pulling demand toward LED-integrated cabinetry and low-VOC finishes. The Dhahran-Jubail corridor concentrates compound housing procurement through direct-to-developer contracting channels.
Western Region
Jeddah's humidity-exposed coastal housing stock is accelerating corrosion-resistant metal framing specification for outdoor and service quarter applications. Red Sea shipping lane disruptions are inflating landed costs for European upholstery suppliers serving Yanbu distribution hubs. Al Balad restoration-adjacent districts concentrate vintage and reproduction piece demand from expatriate segments.
Central Region Secondary Cities
Extended family housing patterns in Qassim and Asir sustain majority share for ornate traditional carved wood and rich textile treatments. Mall-based specialty stores still dominate consumer purchase behavior in Tabuk and Hail where tactile verification remains non-negotiable for dining sets and sofas. Royal Furniture anchors position through deep showroom penetration in these catchments.
NEOM Northwest
The linear city development is mandating energy-efficient fixture specifications that favor suppliers with established low-VOC certification portfolios. Bulk procurement agreements with Saudi Real Estate Refinance Company-financed projects are bypassing traditional retail markups in this zone. Modular kitchen systems and smart furniture with embedded wireless charging are gaining early traction among tech-sector relocations.
Saudi Arabia Home Furniture Market Competitive Landscape
Player mix skews toward vertically integrated regional specialists with GCC manufacturing footprints and showroom-heavy domestic incumbents with mall-based penetration. Market structure reflects a bifurcated tiering between premium international brands and mid-market regional players. Three archetypes dominate: GCC-integrated supply chain operators, mall-anchored domestic retailers, and digital-native direct-to-consumer platforms. Competitive moves concentrate on showroom network expansion in secondary cities and backward integration into captive manufacturing capacity.
Among GCC-integrated specialists, Danube Home leverages vertically controlled supply chains across regional manufacturing hubs to sustain price competitiveness in mid-market segments. Royal Furniture occupies a position exemplifying the mall-anchored domestic archetype through deep showroom penetration in secondary cities. IKEA represents the international scale-driven entrant navigating SFDA compliance through standardized global product platforms.
| Leading Market Players |
|---|
| Danube Home |
| Royal Furniture |
| IKEA |
| Pottery Barn |
| Al-Abdulkader Furniture Co. Ltd |
| Home Centre |
| Marina Home |
| IDdesign |
| PAN Emirates |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day ocean freight cycles from Southeast Asian manufacturing hubs to Jeddah Islamic Port concentrate pricing power among GCC-integrated distributors with captive inventory buffers. This lead-time structure rewards vertically controlled supply chains while penalizing spot-market importers facing Red Sea routing volatility.
Pricing Analysis
Cost-plus contracts with quarterly plywood and steel indexation dominate procurement between Riyadh-based retailers and Malaysian particleboard suppliers. Pricing stratifies across premium solid-wood majlis pieces, mid-market engineered-wood bedroom systems, and economy-grade metal-framed service quarter furniture. Cost compression in the mid-market tier is intensifying because Danube Home's captive UAE manufacturing feeds aggressive square-meter pricing. Developer-direct buyers exhibit highest price sensitivity; luxury villa owner-occupiers show least.
Supply Chain Analysis
Strait of Hormuz transit underwrites the bulk of Southeast Asian particleboard and Chinese hardware imports serving the Kingdom's furniture assembly plants. Malaysian engineered-wood substrates, Turkish upholstery textiles, and Italian design-licensed hardware constitute core input dependencies. Single-source vulnerability concentrates in fire-retardant chemical treatments where SFDA-certified suppliers number fewer than twelve. Distribution runs through Riyadh-Jeddah-Dammam warehouse nodes with final-mile showroom stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generational housing preference fragmentation creates niche formation opportunities as millennial buyers in Riyadh's northern districts diverge from traditional extended-family procurement patterns in Qassim and Asir.
For Market Incumbents: Secure SFDA pre-certification portfolios for low-VOC lacquer systems before chemical emission thresholds tighten further. Anchor showroom network expansion in Dammam and Khobar corridors where villa completions outpace retail penetration. Backward integration into captive UAE or Oman manufacturing hedges Red Sea freight volatility. For New Entrants and Emerging Players: Post-purchase installation and white-glove assembly services represent an under-served layer where Royal Furniture and Danube Home maintain minimal coverage. Target NEOM linear city bulk procurement channels for modular kitchen systems and smart furniture specifications. Pursue direct-to-developer contracting bypassing traditional retail markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital-native furniture platforms with dropship fulfillment models versus asset-heavy showroom operators. Long-term viability favors acquirers of vertically integrated mid-market specialists with GCC manufacturing footprints and established SFDA compliance histories. Monitor Saudi Real Estate Refinance Company project financing volumes as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Low-VOC Certification Investment | Pre-positions suppliers ahead of tightened chemical emission mandates from Saudi regulators. |
| Direct-to-Developer Contracting | Bypasses retail markups in NEOM and Diriyah Gate megaproject procurement channels. |
| Showroom Network Expansion | Captures unmet demand in Eastern Province villa corridors beyond traditional mall locations. |
| Captive GCC Manufacturing Footprint | Insulates margin structure from Red Sea shipping lane disruptions and freight volatility. |
| Smart Furniture Technology Integration | Addresses millennial buyer specification for wireless charging and ambient lighting control. |
Research Methodology
Desk research of customs import records, MOHAP building permit databases, and SFDA product registration filings preceded structured interviews with furniture retail procurement directors, GCC manufacturing plant managers, and Saudi developer fit-out contractors. Primary fieldwork with Riyadh and Jeddah showroom operators cross-validated inventory turnover and margin structure assumptions. Secondary sources included Saudi Ports Authority throughput statistics, SAGIA foreign investment flow reports, and trade association member surveys. Bottom-up SKU-level demand modeling triangulated against top-down residential housing completion forecasts.
Variance decomposition across product type, material composition, style orientation, and distribution channel dimensions informed volume and value projections throughout the forecast period. CAGRs derived from housing handover schedules, mortgage origination trends, and household formation rates specific to villa versus apartment typologies. Modeled inputs incorporated SFDA registration timeline assumptions and Saudi Building Code amendment trajectories.
Underlying assumptions cover stable Red Sea shipping lane access and sustained SFDA chemical emission protocols, with deviation risk concentrated in import freight cost spikes and visa policy shifts affecting skilled joinery labor availability. Practitioners should keep alternative scenarios live as megaproject delivery schedules and regulatory compliance timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Bamboo Furniture Market
Furniture
US Secondary Wood Products Market
Furniture
Kids Furniture Market
Furniture
Russia Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
North America School Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Back Mount Frames Market
Furniture
India Furniture Market
Furniture
GCC Home Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
RTA Furniture Market
Furniture
Brazil Furniture Market
Furniture
HORECA Furniture Market
Furniture
Contract Furniture and Furnishing Market