
 Kids Table and Chair Market | 2026-2036
Kids Table and Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Table and Chair Market Insights
A capital-intensity divergence between flat-pack specialists and premium solid-wood producers is redrawing competitive boundaries in the kids table and chair market. KidKraft leverages extensive molded-plastic tooling networks to sustain mass-market pricing power across big-box retail channels. Milton & Goose anchors its position through artisan-scale hardwood manufacturing, competing on material provenance and domestic craft credentials rather than unit velocity.
Kids tables and chairs comprise scaled-down furniture systems engineered to ergonomic proportions for children aged two to twelve, typically constructed from solid wood, engineered composites, or food-grade polymers with rounded edges and non-toxic finishes. The primary commercial purpose centers on supporting developmental activities including dining, art creation, and structured play in residential and institutional environments. Wood and composite materials command the deepest margin pools as parents prioritize durability and sustainability signaling over lower-cost plastic alternatives. Activity tables lead volume within product-type segmentation due to multipurpose utility across home and educational settings, while folding tables represent the fastest-growing configuration as space-constrained urban households seek stowable solutions.
ASTM International publishes F963 safety specifications governing mechanical hazards and chemical content in juvenile products, while the Consumer Product Safety Commission enforces mandatory testing and certification through its Children's Product Certificate framework. The European Union's REACH regulation and EN 71 toy safety standards further constrain material selections and surface coating chemistries for export-oriented manufacturers. Stakeholders must monitor evolving chemical restriction lists and state-level extended producer responsibility mandates to preempt compliance-driven margin erosion.
Market Dynamics
ASTM F963 and CPSIA compliance thresholds are compressing margin structures for juvenile furniture manufacturers, forcing capital reallocation toward testing infrastructure and material traceability systems. The divergence between mass-market flat-pack producers and premium solid-wood specialists is hardening into a structural divide that determines competitive viability.
Growth Catalysts
- Preschool enrollment expansion:Early learning centers in the United States are scaling furniture procurement to match rising toddler participation rates.
- REACH material standards:European Union chemical restrictions are accelerating substitution toward water-based finishes and certified sustainable wood sourcing.
- Urban space constraints:Folding and stowable configurations are capturing preference share among apartment-dwelling households in China.
Market Restraints
- Hardwood input volatility:Baltic birch and rubberwood price swings are destabilizing cost forecasting for solid-wood producers.
- Testing facility concentration:Third-party certification capacity clusters in Guangdong and Zhejiang provinces, creating queue bottlenecks.
- Plastic substitution ceiling:Parent preference for durability signaling limits volume expansion of molded-polymer alternatives regardless of price advantage.
Strategic Opportunities
- India household formation:Rising nuclear family prevalence in tier-two cities is generating first-time buyer pools for child-centric furniture.
- Extended producer responsibility mandates:State-level take-back programs in California and New York are creating refurbishment and resale channel openings.
- Sensor-embedded furniture:Convergence of pressure-sensitive surfaces with activity-tracking software is enabling usage-analytics subscription models.
Industry Challenges
- Finishing chemistry expertise:Formulation chemists capable of balancing CPSIA compliance with scratch resistance and colorfastness command scarcity premiums.
- Multi-standard certification timelines:Simultaneous ASTM F963, EN 71, and GB standard testing extends product-to-market intervals by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Table and Chair Market |
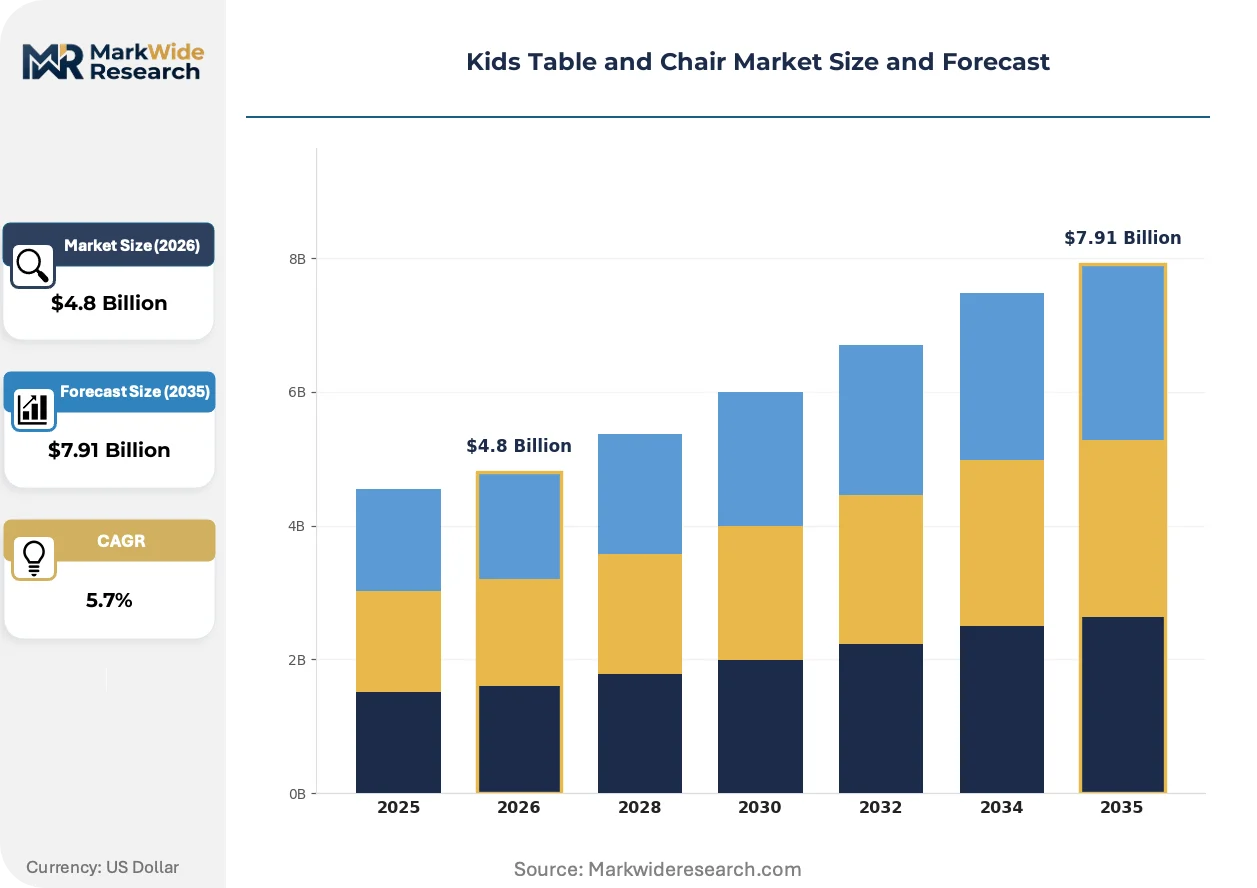
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activity Tables, Drawing Tables, Dining Sets, Folding Tables Material: Wood, Plastic, Metal, Composite Age Group: Toddlers, Preschool, Early School Age, Preteens Design Style: Modern, Vintage, Thematic, Minimalist |
| Companies Covered | Sprout Kids, P’kolino, Nestig, Clafbebe, KidKraft, Piccalio, Milton & Goose, Wood and Hearts, ecoBirdy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Table and Chair Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape how juvenile furniture is engineered, certified, and brought to market. Three distinct vectors are compressing legacy production models while opening differentiated positioning paths.
Adjustable-height mechanisms using gas-lift cylinders and telescoping aluminum channels are enabling single-product lifespan extension across age cohorts. Montessori-method preschools and home-schooling households are adopting these systems at accelerated rates. The technology is miniaturizing formerly institutional-grade adjustability into residential-scale footprints and price points.
REACH Annex XVII restrictions on formaldehyde-emitting resins and certain isocyanates are eliminating conventional engineered wood adhesives from export-qualified production lines. Manufacturers serving European Union markets are reformulating particleboard and MDF substrates to meet E1 and E0 emission classifications. Solid-wood and bamboo alternatives are capturing specification share among premium-positioned brands as a compliance-hedging strategy.
Direct-to-parent subscription models are displacing traditional retail inventory commitments for entry-level and mid-market lines. Urban millennial households in China and the United States are accepting rental-return programs for temporary-use items. This reconfiguration is concentrating fulfillment infrastructure investment near major metropolitan distribution hubs while compressing working capital requirements for participating brands.
Kids Table and Chair Market Segmentation
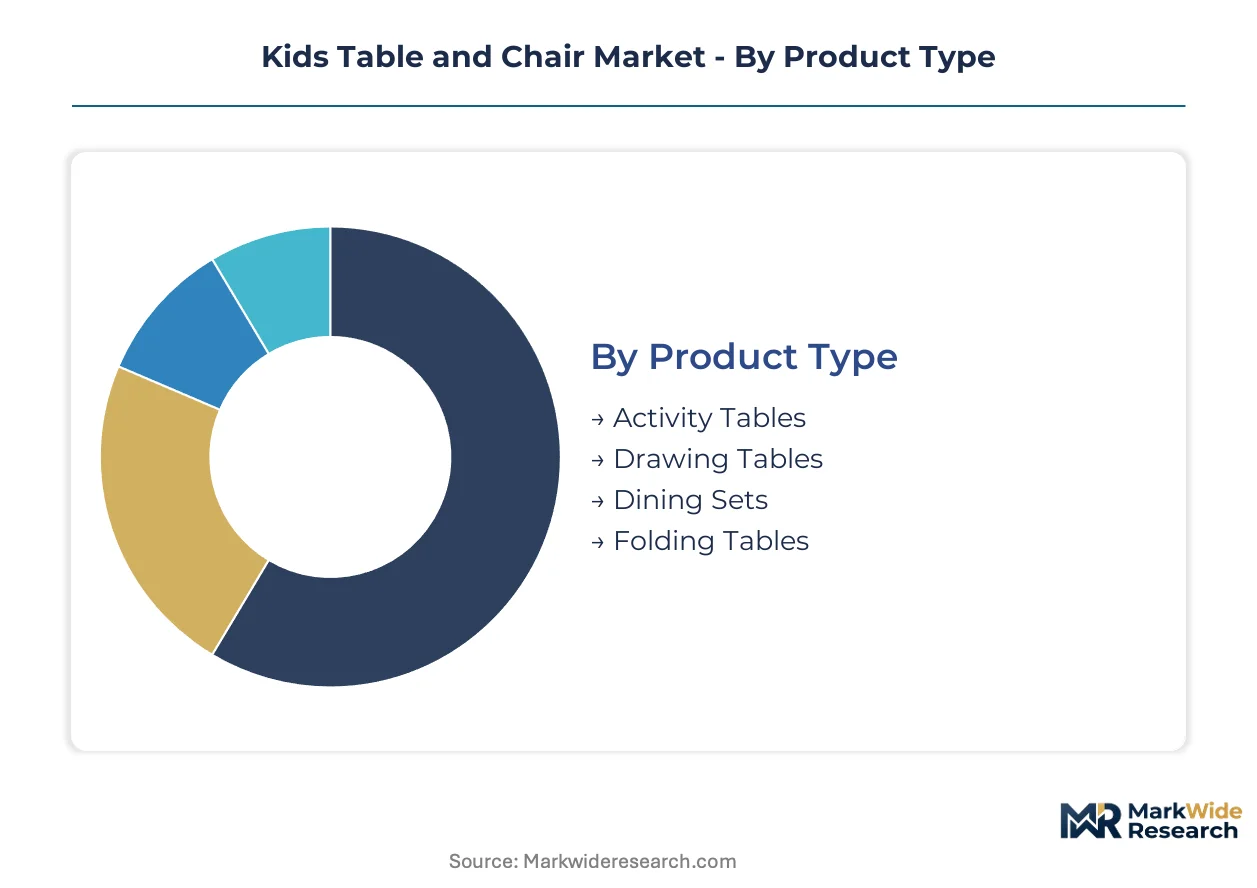
Segmentation in juvenile furniture separates procurement specifications across institutional buyers and residential households. Safety certification tiers, material durability requirements, and space constraints vary sharply between preschools and urban apartments. Manufacturers align production lines to these divergent demand profiles.
Product Type:
ASTM F963 mechanical testing intensity differs sharply across configurations, with folding mechanisms facing additional cycle-testing mandates.
- Activity Tables:Multipurpose surfaces integrate storage bins, paper rolls, and supply caddies for art and sensory play. Preschools in the United States specify these for classroom centers; parents in China purchase them for compact-home learning environments. REACH-compliant finishes and rounded-edge mandates elevate unit costs for export-qualified production.
- Folding Tables:Hinge mechanisms and locking hardware undergo accelerated wear testing under juvenile product safety protocols. Apartment households in Shanghai and Beijing prioritize stowable footprints; rental-return subscription models concentrate inventory investment near these metropolitan hubs.
- Drawing Tables:Tilt-adjustable work surfaces with integrated supply storage serve dedicated art instruction.
- Dining Sets:Scaled seating arrangements match ergonomic proportions to family meal routines.
Activity Tables handle the majority of throughput; Folding Tables is the fastest mover on share.
Material:
Margin pools concentrate where durability signaling commands parent willingness to pay premium differentials.
- Wood:Solid hardwood and plywood substrates carry FSC chain-of-custody documentation for sustainability-positioned brands. Baltic birch and rubberwood price volatility destabilizes cost forecasting for domestic craft producers in the United States. Water-based finish formulations balance CPSIA compliance with scratch resistance.
- Composite:Engineered wood products reformulate adhesives to meet E1 and E0 emission classifications under REACH Annex XVII. European Union export qualification drives substitution away from formaldehyde-emitting resins; bamboo alternatives capture specification share as compliance-hedging strategy.
- Plastic:Food-grade polymers with rounded-edge molding serve mass-market price points.
- Metal:Powder-coated steel frames support institutional durability requirements.
Wood commands the deepest margin structure; Composite is expanding most quickly on regulatory substitution.
Age Group:
Product lifespan extension through adjustable-height engineering compresses replacement frequency in upper cohorts.
- Toddlers:Low-profile seating with fall-resistant stability bases addresses 18-36 month developmental stages.
- Preschool:Gas-lift cylinders and telescoping aluminum channels enable single-product use across 3-5 year age spans. Montessori-method schools in the United States adopt these systems at accelerated rates; miniaturized residential-scale mechanisms reach price points accessible to home-schooling households.
- Early School Age:Standardized desk heights align with primary classroom furniture specifications.
- Preteens:Transition sizing bridges juvenile and adult furniture dimensions.
Preschool captures the largest addressable volume; Early School Age shows steepest expansion trajectory on enrollment growth.
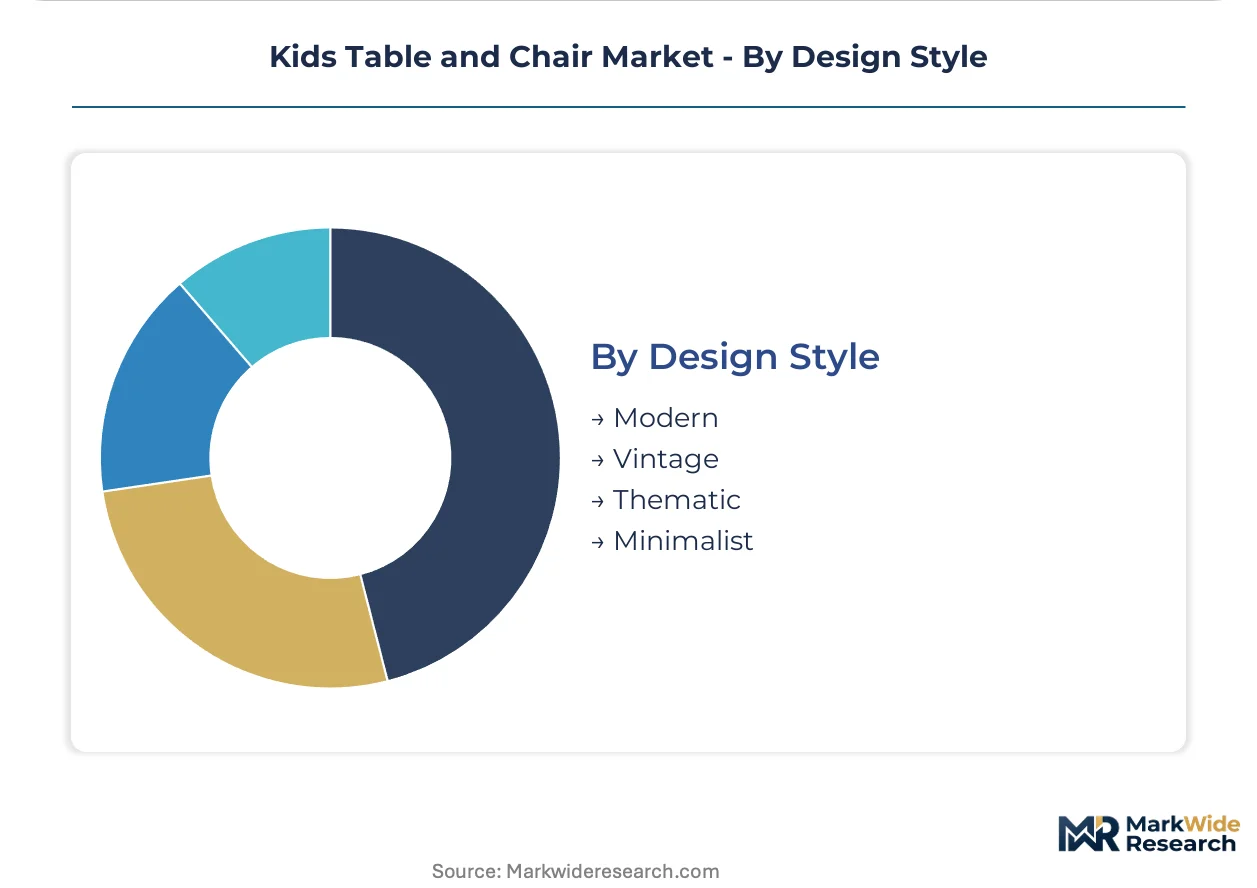
Design Style:
Aesthetic positioning stratifies across parental identity signaling and institutional procurement neutrality.
- Modern:Clean lines and neutral palettes dominate direct-to-consumer photography for millennial buyer segments.
- Minimalist:Reduced component counts and flat-pack logistics align with urban space constraints and subscription-model fulfillment economics. Rental-return programs in China and the United States concentrate inventory near metropolitan distribution hubs.
- Vintage:Heritage styling references mid-century domestic craft traditions.
- Thematic:Licensed character and narrative-driven designs target gift purchase occasions.
Modern leads residential specification; Minimalist is gaining share fastest on logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage through clustered production infrastructure, while US-based craft producers extract premium differentials through domestic sourcing credentials and CPSIA compliance positioning.
United States
Preschool enrollment expansion and home-schooling adoption drive institutional and residential procurement simultaneously. The Consumer Product Safety Commission enforces mandatory Children's Product Certificate testing under CPSIA frameworks. Domestic craft producers concentrate in New England and Pacific Northwest regions, leveraging Baltic birch supply chains and water-based finish expertise.
China
Rising middle-class household spending on child-centric home environments converges with expanding manufacturing scale. GB standards and SAMR oversight govern juvenile product safety certification for domestic consumption and export qualification. Guangdong and Zhejiang provinces host concentrated testing facility infrastructure, though queue bottlenecks extend certification timelines.
Germany
Sustainability-signaling parent preferences elevate demand for FSC-certified solid-wood configurations. REACH Annex XVII restrictions on formaldehyde-emitting resins and isocyanates constrain engineered wood adhesive selections. Industrial clusters in Bavaria and North Rhine-Westphalia specialize in E1 and E0 emission-classified panel production for EU export markets.
India
Nuclear family prevalence in tier-two cities generates first-time buyer pools for child-centric furniture systems. BIS certification requirements and DGFT import frameworks shape competitive entry conditions. Manufacturing activity concentrates in Gujarat and Maharashtra, where domestic rubberwood processing capacity supports cost-competitive solid-wood production.
Japan
Space-constrained urban households in Tokyo and Osaka metropolitan areas prioritize stowable folding configurations. METI oversees product safety standards alignment with international juvenile furniture protocols. Kanto region fabricators specialize in precision-engineered adjustable-height mechanisms for premium residential segments.
Kids Table and Chair Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a bifurcated market structure where flat-pack logistics innovators compete against artisan-scale material specialists. The vendor base separates into three strategic tiers: mass-market molded-polymer producers, mid-market engineered-composite specialists, and premium solid-wood craft houses. Dominant competitive moves include geographic expansion into subscription-model metropolitan hubs and backward integration into certified sustainable wood sourcing.
Among North American craft producers, Milton & Goose and Sprout Kids occupy positions within the premium solid-wood archetype, emphasizing domestic manufacturing credentials and CPSIA compliance positioning. KidKraft anchors the mass-market tier through scaled molded-plastic production networks serving big-box retail channels. These three companies exemplify the structural divergence between velocity-driven and provenance-driven competitive strategies.
| Leading Market Players |
|---|
| Sprout Kids |
| P'kolino |
| Nestig |
| Clafbebe |
| KidKraft |
| Piccalio |
| Milton & Goose |
| Wood and Hearts |
| ecoBirdy |
| Others |
Pricing and Supply Chain Analysis
Water-based finish substitution for solvent-based coatings simultaneously concentrates supply geography in Guangdong and Zhejiang provinces and compresses margin structures for solid-wood producers unable to absorb reformulation costs. This input transition rewards manufacturers with captive chemistry expertise while penalizing flat-pack competitors dependent on volatile resin pricing.
Pricing Analysis
The customization-premium spread separates configured-to-order artisan pieces from mass-market flat-pack units by a factor of three to five on unit economics. Pricing stratifies across premium solid-wood tiers with FSC documentation, standard engineered-composite configurations with E1 emission classifications, and economy molded-polymer lines serving big-box retail. Price differentiation hinges on certification grade and geographic delivery cost, with CPSIA-compliant domestic production commanding sustained premiums. Cost compression in the economy tier is intensifying because testing facility queue bottlenecks in Guangdong extend certification timelines and inflate working capital requirements. Preschool procurement committees exhibit lowest price sensitivity due to institutional durability mandates, while urban millennial renters in subscription programs demonstrate highest elasticity.
Supply Chain Analysis
China and Vietnam anchor juvenile furniture manufacturing through clustered component fabrication and finishing infrastructure. Raw material dependencies draw from Baltic birch supply chains, rubberwood plantations in Southeast Asia, and food-grade polymer resin networks. Single-source vulnerability concentrates in Guangdong and Zhejiang testing facility infrastructure, where certification queue bottlenecks create four-to-six-month product-to-market delays. Distribution runs through big-box retail commitments, direct-to-parent subscription hubs in metropolitan China and the United States, and institutional procurement channels serving preschool networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as sensor-embedded furniture converges with activity-tracking software, creating subscription-analytics ecosystems that displace transactional retail inventory models.
For Market Incumbents: Secure backward integration into certified sustainable wood sourcing to defend margin position against Baltic birch price volatility. KidKraft's molded-plastic tooling networks and Milton & Goose's artisan-scale hardwood manufacturing both require captive supply hedges against REACH Annex XVII adhesive restrictions. Channel control through direct-to-parent subscription platforms represents the priority defensive lever against rental-return entrants.
For New Entrants and Emerging Players: CPSIA fast-track certification through third-party testing partnerships in Guangdong opens white-space penetration in the United States institutional procurement segment. India's tier-two nuclear family formation presents the most penetrable geography for first-time buyer acquisition. Montessori-method preschool specification offers a go-to-market angle with concentrated decision-maker access and durability-signaling requirements that reward premium positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flat-pack logistics innovators facing margin compression from testing facility queue bottlenecks. Long-term viability across the analysis window favors provenance-driven craft houses with domestic sourcing credentials and CPSIA compliance positioning. The signal to watch is state-level extended producer responsibility mandate passage in California and New York, which would accelerate refurbishment and resale channel infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Wood Sourcing | FSC chain-of-custody documentation commands parent willingness to pay premium differentials for durability signaling. |
| Direct-to-Parent Subscription Platform Launch | Rental-return programs concentrate fulfillment infrastructure near metropolitan distribution hubs and compress working capital. |
| Sensor-Embedded Furniture Development | Pressure-sensitive surfaces with activity-tracking software enable usage-analytics subscription models displacing transactional retail. |
| REACH-Compliant Adhesive Reformulation | E1 and E0 emission classifications hedge against Annex XVII restrictions eliminating conventional engineered wood resins. |
| Extended Producer Responsibility Infrastructure | State-level take-back programs in California and New York create refurbishment and resale channel openings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with preschool procurement directors, furniture brand supply chain managers, third-party testing facility operators in Guangdong and Zhejiang, and flat-pack logistics coordinators. Secondary validation drew from ASTM International F963 documentation, Consumer Product Safety Commission enforcement records, European Chemicals Agency REACH Annex XVII updates, and customs trade data on Baltic birch and rubberwood flows. Bottom-up unit economics triangulated against top-down market sizing across product type, material, age group, and design style segmentation.
Across the analysis window, volume and value outputs reflect analytical framework modeling of replacement frequency by age cohort, enrollment-driven institutional procurement cycles, and urban household formation patterns. Segmentation dimensions included product configuration, substrate material with emission classification tier, child developmental stage, and aesthetic positioning. CAGRs were derived from trend extrapolation of preschool expansion rates, middle-class consumption intensity in China, and regulatory compliance cost pass-through elasticity. Forecast inputs incorporated testing facility capacity utilization rates and water-based finish adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained REACH stringency and CPSIA enforcement continuity; material deviation in regulatory timelines or raw material availability would warrant model refresh. Specific risk factors include Baltic birch supply disruption from geopolitical trade friction, queue extension at concentrated certification facilities, and faster-than-anticipated plastic substitution ceilings from parent durability preferences. Recalibration cycles align with material shifts in chemical restriction list updates and state-level extended producer responsibility mandate passage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
China Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Bamboo Furniture Market
Furniture
Italy Luxury Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Global Home Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
Recliner Chair Market
Furniture
France Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Chaises Longue Market
Furniture
Spain Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Armchairs with Footrest Market