
 Toilet Partition Market | 2026-2036
Toilet Partition Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Partition Market Analytics
ASTM E84 surface burning characteristics certification is rotating competitive standing among partition suppliers seeking specification on federally funded projects. Hadrian Manufacturing leverages captive steel fabrication to sustain price stability across its stainless-steel product lines. Bobrick Washroom Equipment anchors its position through extensive distributor relationships with major facility maintenance contractors. Scranton Products differentiates via specialized polymer formulations that resist graffiti and bacterial colonization in educational settings.
Toilet partitions are enclosure systems that separate individual water-closet fixtures in public and commercial restrooms, typically fabricated from laminate composites, solid phenolic resin, stainless steel, or engineered plastics with specified panel thicknesses ranging from 13 mm to 25 mm and hardware rated for 1,000,000 cycle testing. Their primary purpose is to provide privacy, moisture protection, and structural durability in high-traffic sanitation environments. Phenolic partitions command premium positioning due to superior humidity resistance and extended service life in shower-adjacent installations. Floor-mounted systems retain volume leadership across commercial end-use segments, while ceiling-hung configurations gain specification in healthcare settings where floor cleaning protocols demand uninterrupted surfaces. ADA-compliant product styles represent a concentrated margin pool as jurisdictions tighten accessibility enforcement.
The U.S. Department of Justice enforces ADA Standards for Accessible Design, which mandate specific stall dimensions, grab-bar placement, and door-swing clearances that directly shape product development and installation protocols. State-level building codes in California and New York incorporate CalGreen and stretch energy provisions that influence material sourcing and embodied-carbon calculations for public restroom renovations. OSHA sanitation standards for workplace facilities further constrain specification options by requiring partitions that withstand industrial cleaning chemicals. Stakeholders must monitor evolving state procurement preferences for Buy American-compliant steel and phenolic substrates as infrastructure spending flows through federal compliance filters.
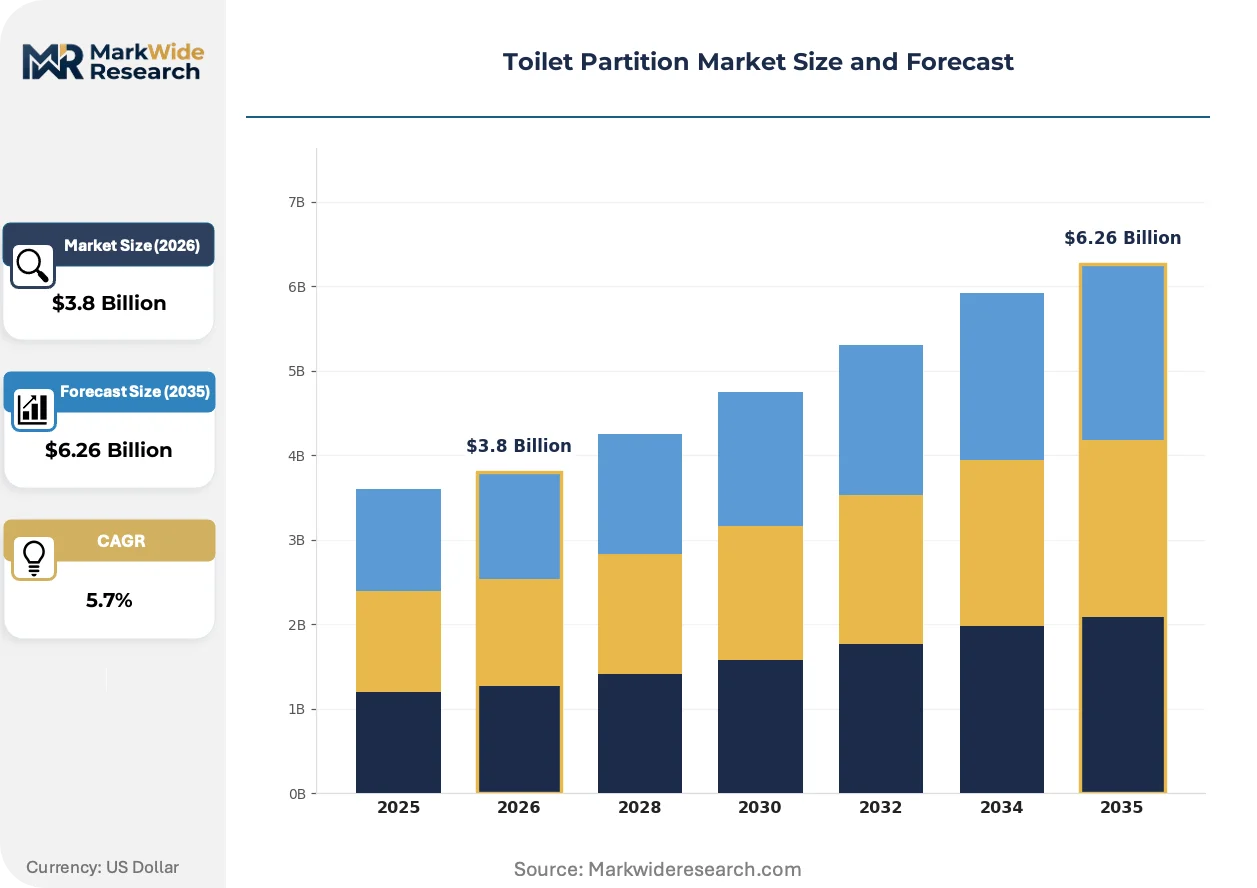
Market Dynamics
Phenolic resin formulations with enhanced moisture resistance are displacing traditional laminate cores across high-traffic institutional environments, compressing specification windows for legacy materials while elevating certification requirements for suppliers seeking federal project access.
Growth Catalysts
- ADA accessibility mandates:The U.S. Department of Justice enforces stall dimension and grab-bar placement standards that force restroom renovation cycles in healthcare and educational facilities, sustaining replacement demand regardless of new construction velocity.
- Solid phenolic technology:Engineered polymer substrates with bacterial resistance properties are capturing specification share in K-12 and university settings where hygiene protocols intensified post-pandemic.
- Texas institutional construction:Commercial building permits for healthcare and government facilities in Dallas-Fort Worth and Houston metro areas concentrate demand for floor-mounted and ceiling-hung partition systems.
Market Restraints
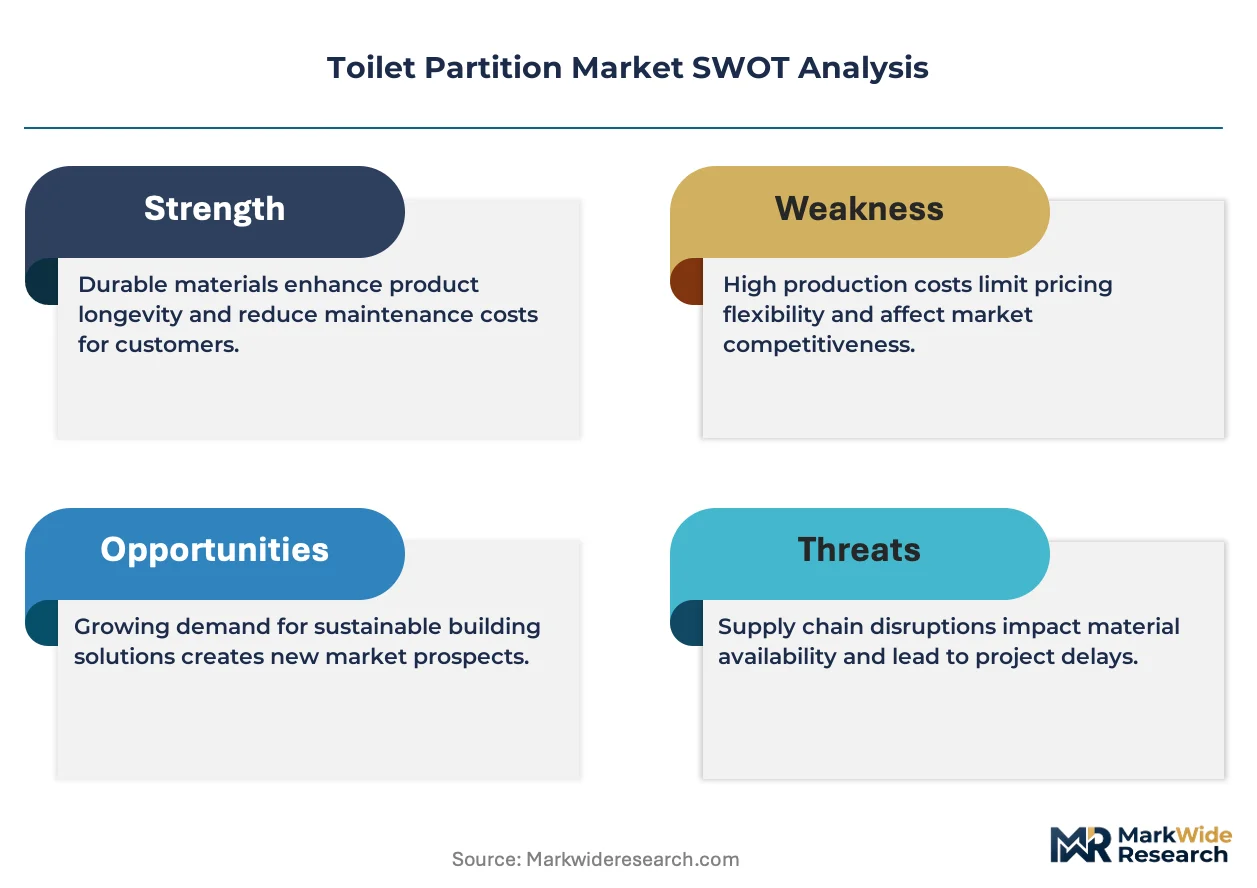
- Steel input cost volatility:Stainless-steel partition pricing fluctuates with nickel and chromium commodity markets, squeezing margin stability for fabricators without captive raw material sourcing.
- Buy American compliance friction:Federal infrastructure spending filters require domestic steel and phenolic substrate verification, disqualifying imported components from specification pools.
- Laminate core substitution ceiling:Traditional high-pressure laminate retains cost advantage in low-traffic retail and office segments, limiting phenolic penetration in budget-constrained renovation projects.
Strategic Opportunities
- Florida healthcare expansion:Aging demographic concentration and hospital system capital programs in Miami-Dade and Tampa Bay markets create concentrated demand for ADA-compliant, antimicrobial partition configurations.
- CalGreen stretch provisions:California's building code extensions on embodied-carbon calculations for public restroom renovations incentivize low-carbon phenolic formulations and recycled-content steel products.
- Facility maintenance contractor consolidation:Direct specification relationships with national property management firms bypass traditional distributor markups and secure multi-site renovation contracts.
Industry Challenges
- ASTM E84 certification timelines:Surface burning characteristics testing for federally funded projects extends product qualification cycles, delaying revenue recognition for new substrate introductions.
- Installation labor coordination:Ceiling-hung healthcare configurations demand specialized structural assessment and MEP alignment, fragmenting project execution across subcontractor tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Partition Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Laminate, Phenolic, Stainless Steel, Plastic Installation Method: Floor-mounted, Ceiling hung, Wall-mounted, Partially anchored Product Style: Classic, Modern, Custom, ADA Compliant End Use: Commercial, Institutional, Healthcare, Educational |
| Companies Covered | Hadrian Manufacturing, Inpro Corporation, Bobrick Washroom Equipment, General Partitions, Wilsonart, Bradley Corporation, ASI Group, Metpar, Scranton Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Partition Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional specification pathways while elevating performance certification as the primary competitive filter across institutional buyer segments.
Solid phenolic resin panels with integrated antimicrobial additives are displacing coated steel and laminate alternatives in educational and healthcare restrooms. School districts in California and Texas specify these substrates for shower-adjacent installations where humidity degradation previously shortened replacement cycles. The technology is displacing mid-grade laminate volume in high-traffic environments where total cost-of-ownership calculations now override first-cost procurement criteria.
OSHA sanitation standards for workplace facilities mandate partition resistance to industrial cleaning chemicals, constraining specification pools to substrates with verified chemical compatibility documentation. Manufacturers must reformulate surface coatings and core binders to withstand quaternary ammonium and bleach-based protocols without delamination or discoloration. Healthcare facilities in New York and Illinois enforce these standards most stringently, driving supplier investment in accelerated aging test facilities.
Buyers increasingly bundle partition specification with full restroom renovation contracts, consolidating vendor relationships and compressing the traditional distributor-specifier channel. General contractors in Florida and Texas now source directly from manufacturers with captive installation capabilities, disintermediating regional distributors who previously controlled project access. This pattern concentrates volume with vertically integrated suppliers capable of design-assist, fabrication, and field installation coordination.
Toilet Partition Market Segmentation
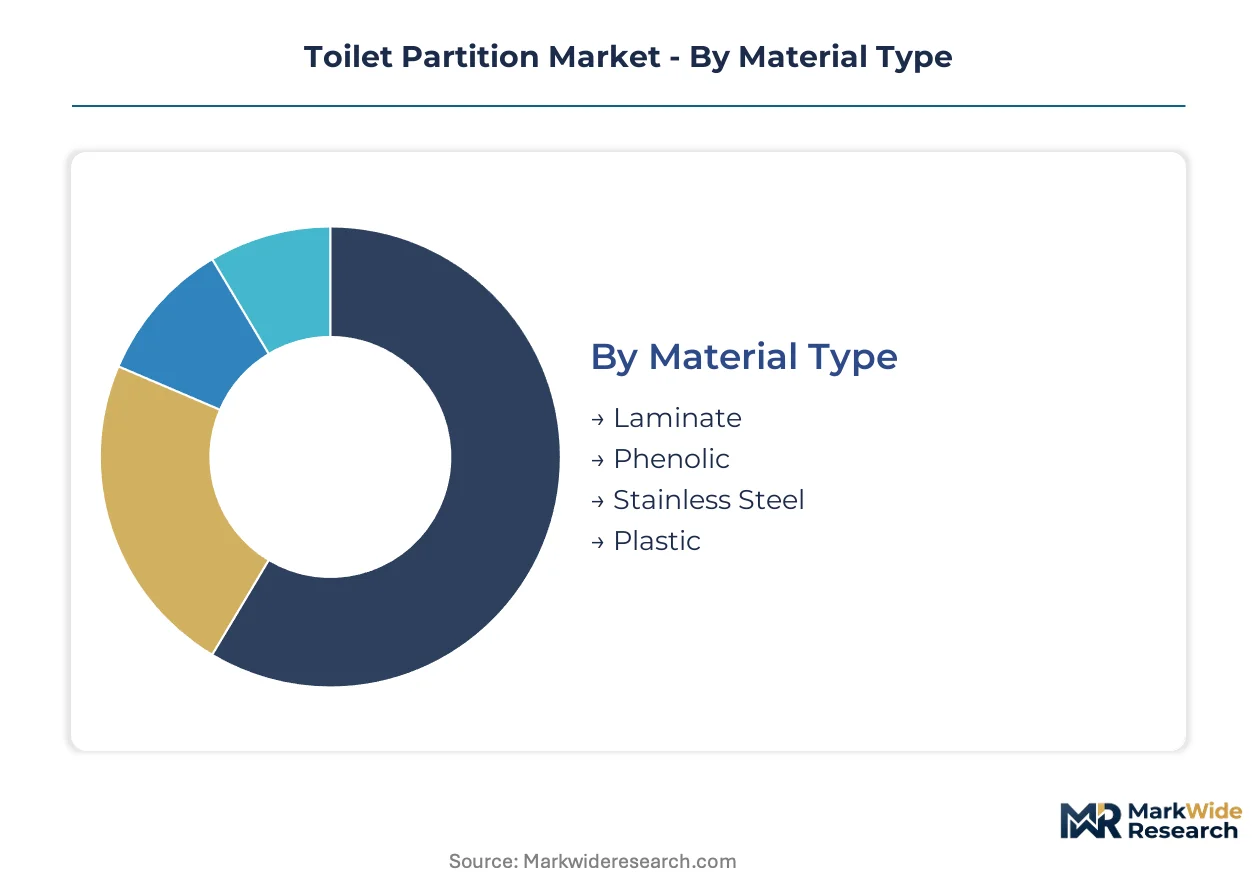
Toilet partition procurement patterns diverge sharply across material grades and installation configurations, with specification authority shifting from architects to facility managers as total cost-of-ownership calculations displace first-cost bidding. Understanding segment boundaries reveals where margin pools concentrate and which substrate technologies command pricing power.
Material Type:
Phenolic formulations dominate specification in moisture-intensive domestic environments, while stainless steel retains export-led positioning for premium international contracts.
- Phenolic:Solid polymer substrates with integrated resin binders deliver humidity resistance and bacterial suppression for shower-adjacent installations. Texas and Florida healthcare systems specify these for extended service life in high-traffic restrooms. The material captures premium positioning where replacement cycle costs outweigh first-cost premiums.
- Laminate:High-pressure composite panels with decorative surfaces and kraft paper cores retain cost advantage in budget-constrained renovations. Retail and office segments in California and New York continue procurement where traffic volumes remain moderate and moisture exposure is limited.
- Stainless Steel:Fabricated 304 and 316-grade enclosures with brushed or polished finishes serve federal facilities requiring Buy American compliance and fire-rated surface characteristics.
- Plastic:Engineered polymer panels with graffiti-resistant coatings target K-12 educational settings where vandalism protocols demand easily restored surfaces.
Phenolic commands the established base. The steepest expansion runs through stainless steel as federal infrastructure spending intensifies domestic fabrication requirements.
Installation Method:
Cost tier stratification separates premium ceiling-hung systems from economy floor-mounted alternatives, with labor coordination requirements driving specification divergence.
- Floor-mounted:Structural support from concrete or steel floor slabs enables rapid installation without overhead anchoring. Commercial construction in Dallas-Fort Worth and Houston concentrates demand where speed-to-occupancy drives contractor selection.
- Ceiling hung:Suspended configurations eliminate floor penetrations for uninterrupted cleaning protocols in healthcare settings. Miami-Dade hospital systems specify these for infection control compliance, though structural assessment and MEP coordination extend project timelines.
- Wall-mounted:Bracket-supported panels anchored to masonry or stud walls serve retrofit applications where floor conditions preclude traditional mounting.
- Partially anchored:Hybrid systems combining floor and ceiling support accommodate irregular structural conditions in aged institutional buildings.
Floor-mounted retains volume leadership across commercial segments. Ceiling-hung configurations are gaining share fastest in healthcare renovation pipelines.
Product Style:
Application-specific requirements separate code-mandated accessibility designs from aesthetic-driven custom configurations.
- ADA Compliant:Stall dimensions, grab-bar placement, and door-swing clearances meeting Department of Justice enforcement standards. California and Texas jurisdictions mandate these for all public facility renovations, creating concentrated specification pools.
- Modern:Minimalist panel profiles with concealed hardware and neutral color palettes target corporate headquarters and hospitality settings where design continuity matters.
- Classic:Traditional panel proportions with visible hardware and institutional color schemes serve government and educational facilities with conservative aesthetic standards.
- Custom:Bespoke dimensions, materials, and finishes for signature architecture projects where standard product lines fail to meet design intent.
ADA Compliant styles anchor regulatory-driven replacement cycles. Custom work delivers the highest margin per project though with irregular volume.
End Use:
Customer type fragmentation splits volume between property management contractors and institutional capital programs with diverging procurement timelines.
- Healthcare:Hospital and clinic systems prioritize antimicrobial substrates and ceiling-hung configurations for infection control. Florida's aging demographic concentration sustains renovation demand in Miami-Dade and Tampa Bay markets.
- Educational:K-12 districts and universities specify graffiti-resistant phenolic for high-traffic restrooms. California school systems lead adoption of bacterial-resistant formulations post-pandemic.
- Commercial:Office, retail, and hospitality properties balance first-cost constraints with durability requirements, sustaining laminate volume in low-traffic applications.
- Institutional:Government facilities, airports, and transportation hubs enforce Buy American compliance and ASTM E84 certification, filtering specification to qualified domestic suppliers.
Healthcare commands the established base. Educational facilities are expanding most quickly as ESSER-funded renovation cycles accelerate across multiple states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure spending and accessibility mandates are reshaping procurement patterns across major construction markets, with institutional renovation cycles concentrating demand in jurisdictions enforcing stringent compliance standards.
United States
Healthcare systems in Texas, California, and Florida are expanding restroom renovation budgets to meet ADA accessibility mandates enforced by the Department of Justice. OSHA sanitation standards for workplace facilities constrain specification pools to substrates with verified chemical resistance. Dallas-Fort Worth and Houston metro areas concentrate demand for floor-mounted partition systems where speed-to-occupancy drives contractor selection.
Canada
Provincial building codes in Ontario and British Columbia incorporate accessibility requirements that mirror federal ADA standards, sustaining replacement demand in educational and healthcare facilities. Health Canada guidelines influence antimicrobial material specifications for hospital renovations. The Greater Toronto Area anchors procurement volume for phenolic and stainless-steel configurations in institutional capital programs.
Germany
Commercial construction in Bavaria and North Rhine-Westphalia drives specification of high-durability partition systems for office and transportation hub applications. REACH regulations govern chemical composition of resin binders and surface coatings used in public restroom installations. The Munich-Stuttgart corridor concentrates demand for premium ceiling-hung configurations in healthcare and hospitality settings.
China
Rapid urbanization in the Yangtze River Delta and Pearl River Delta sustains volume demand for cost-competitive laminate and plastic partition systems in commercial real estate. GB standards for building materials influence domestic manufacturer formulations and fire-resistance certifications. Shanghai and Shenzhen metro areas lead specification of engineered polymer substrates in high-traffic public facilities.
India
Government infrastructure programs and smart city initiatives in Maharashtra and Karnataka are expanding institutional construction pipelines for educational and healthcare facilities. BIS certification requirements filter specification to domestically manufactured steel and composite substrates. The Mumbai-Pune corridor concentrates demand for budget-conscious partition configurations in commercial and public sector projects.
Toilet Partition Market Competitive Landscape
Player mix skews toward mid-scale fabricators with captive material sourcing and regional installation capabilities. The vendor base clusters around three strategic tiers: vertically integrated manufacturers controlling resin formulation and steel fabrication, specialized distributors with design-assist capabilities, and regional installers bundling procurement with maintenance contracts. Dominant competitive moves include backward integration into raw material supply and direct contracting relationships with national facility management firms.
Within the integrated-manufacturer tier, Hadrian Manufacturing and Bobrick Washroom Equipment exemplify archetypes combining captive fabrication with extensive distribution networks. Scranton Products occupies a position among specialized polymer formulators targeting educational and healthcare segments with bacterial-resistant substrate technologies. These three companies represent contrasting approaches to market access—steel-centric compliance fabrication, washroom equipment diversification, and polymer science specialization—each anchoring distinct specification channels within institutional procurement pipelines.
| Leading Market Players |
|---|
| Hadrian Manufacturing |
| Inpro Corporation |
| Bobrick Washroom Equipment |
| General Partitions |
| Wilsonart |
| Bradley Corporation |
| ASI Group |
| Metpar |
| Scranton Products |
| Others |
Value Network & Pricing Analysis
Capacity utilization at domestic phenolic resin plants shapes both supply concentration and price floors for partition substrates. Texas and Ohio manufacturing clusters leverage scale economies to undercut regional competitors on standard-grade phenolic panels, while specialty antimicrobial formulations command premiums that reflect dedicated production line costs and certification overhead.
Pricing Analysis
Certification level creates the primary spread between ASTM E84 fire-rated configurations and standard commercial-grade alternatives. Project-based contracting dominates institutional procurement, with price differentiation resting on substrate durability ratings and ADA compliance bundling. Cost compression in laminate tiers is intensifying because imported kraft paper cores face tariff exposure, squeezing margin stability for distributors without captive fabrication. K-12 educational facilities demonstrate highest price sensitivity, while healthcare systems prioritize total cost-of-ownership over first-cost premiums.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan ports constrain margin recovery for phenolic resin imports serving domestic formulation plants. Supply concentrates in the United States, China, and Germany for engineered polymer substrates and specialty steel hardware. Raw material dependencies center on phenol-formaldehyde resins, decorative kraft paper, and 304-grade stainless steel coils. Single-source vulnerability runs through nickel alloy supply chains. Distribution runs through regional distributor networks with design-assist capabilities, though direct manufacturer contracting is fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toilet partition market sits in early-cycle expansion as post-pandemic hygiene protocols institutionalize antimicrobial substrate specifications across healthcare and educational capital programs. Penetration of solid phenolic technology in K-12 districts remains below saturation thresholds, creating runway for specification share gains.
For Market Incumbents: Shield specification relationships by securing captive phenolic resin formulation capacity and accelerating ASTM E84 certification timelines for next-generation substrates. Laminate substitution pressure from budget-constrained renovators threatens volume in commercial segments, demanding backward integration into kraft paper core supply to defend margin position in mid-tier product lines. For New Entrants and Emerging Players: Lead with antimicrobial phenolic formulations targeting Florida healthcare expansion corridors where infection control protocols drive ceiling-hung configuration demand. The most penetrable white space sits in direct contracting with national facility management firms, bypassing distributor markups through bundled design-assist and installation capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with in-house resin formulation and regional installation networks. Long-term viability hinges on exposure to federal infrastructure spending flows and ADA enforcement intensity. Acquisition targets should demonstrate established distributor relationships in Texas and California markets. The signal to watch is Buy American compliance friction—suppliers with verified domestic substrate sourcing will capture disproportionate specification share as infrastructure filters tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Supply | Captive formulation capacity insulates margin from commodity volatility and accelerates product development cycles for antimicrobial substrates. |
| ASTM E84 Certification Investment | Fire-rated surface characteristics unlock specification pools for federally funded healthcare and institutional renovation projects. |
| Direct Facility Management Contracting | Bypassing distributor channels captures multi-site renovation volumes and compresses customer acquisition costs in commercial segments. |
| Ceiling-Hung Configuration Capability Buildout | Healthcare infection control protocols in Florida and Texas drive specification share for suspended systems requiring structural engineering coordination. |
| Antimicrobial Additive Formulation Partnership | Integrated bacterial resistance properties differentiate phenolic offerings in educational procurement pipelines post-pandemic. |
Research Methodology
A spread of perspectives from plant managers at phenolic resin manufacturers, procurement leads at healthcare facility management firms, distributor channel partners, and specification architects converged on the working assumptions driving volume and value estimates. Secondary validation drew from U.S. Census construction spending data, ASTM International certification registries, and commercial building permit filings in Dallas-Fort Worth, Houston, and Miami-Dade metro areas. Bottom-up project pipeline analysis and top-down construction spending allocation models were triangulated to constrain estimate variance.
Segmentation dimensions modeled include material substrate type, installation configuration, product style compliance tier, and end-use facility category across the projection horizon. CAGRs were derived from regression analysis against construction spending indices and renovation cycle frequency data. Industry-specific forecast inputs incorporated ADA enforcement intensity by state jurisdiction and ESSER fund disbursement timelines for educational facility upgrades.
Forecasts assume regulatory continuity in U.S. Department of Justice ADA enforcement, OSHA sanitation standards, and federal Buy American procurement requirements; material policy shifts would require re-modeling of specification pool assumptions and domestic manufacturing capacity allocation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market