
 Vietnam DIY Home Improvement Market | 2026-2036
Vietnam DIY Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam DIY Home Improvement Market Analytics
Installment financing and pay-later platforms is rewriting competitive access in Vietnam's home improvement sector, allowing smaller contractors and first-time homeowners to purchase premium materials previously restricted to cash buyers. HomePro Vietnam leverages its nationwide store network to sustain showroom-driven conversion rates in secondary cities. LIXIL (INAX) anchors the sanitaryware segment through Japanese-standard quality positioning that commands contractor loyalty. Nippon Paint Vietnam competes on localized color palettes formulated for tropical humidity conditions.
Vietnam DIY home improvement encompasses self-directed residential modification using hand tools, power equipment, decorative coatings, fastening hardware, and surface finishes, with products typically rated for tropical climate exposure including mold resistance and UV stability classifications. The primary purpose spans functional repair, aesthetic upgrading, and property value preservation across urban and peri-urban housing stock. Paint and flooring categories lead current value generation due to frequent reapplication cycles in high-humidity environments. Online retail channels represent the fastest-growing distribution vector as logistics networks penetrate provincial markets. DIY enthusiasts and homeowners together occupy the dominant customer positions, though contractors control bulk purchasing for renovation applications.
Vietnam's Ministry of Construction enforces national technical standards on building materials, while the country's quality assurance framework mandates VOC emissions testing for interior coatings sold in metropolitan zones. BIS-equivalent conformity assessment procedures shape import clearance timelines for foreign suppliers like Rockwool and Andersen Corporation. Stakeholders must monitor how provincial implementation of energy-efficient building codes will alter product specification requirements for windows, insulation, and plumbing fixtures across northern, central, and southern construction zones.
Market Dynamics
Installment financing platforms and pay-later schemes are democratizing access to premium materials across Vietnam's home improvement sector, enabling smaller contractors and first-time homeowners to bypass traditional cash-only purchasing constraints that previously segmented the market.
Growth Catalysts
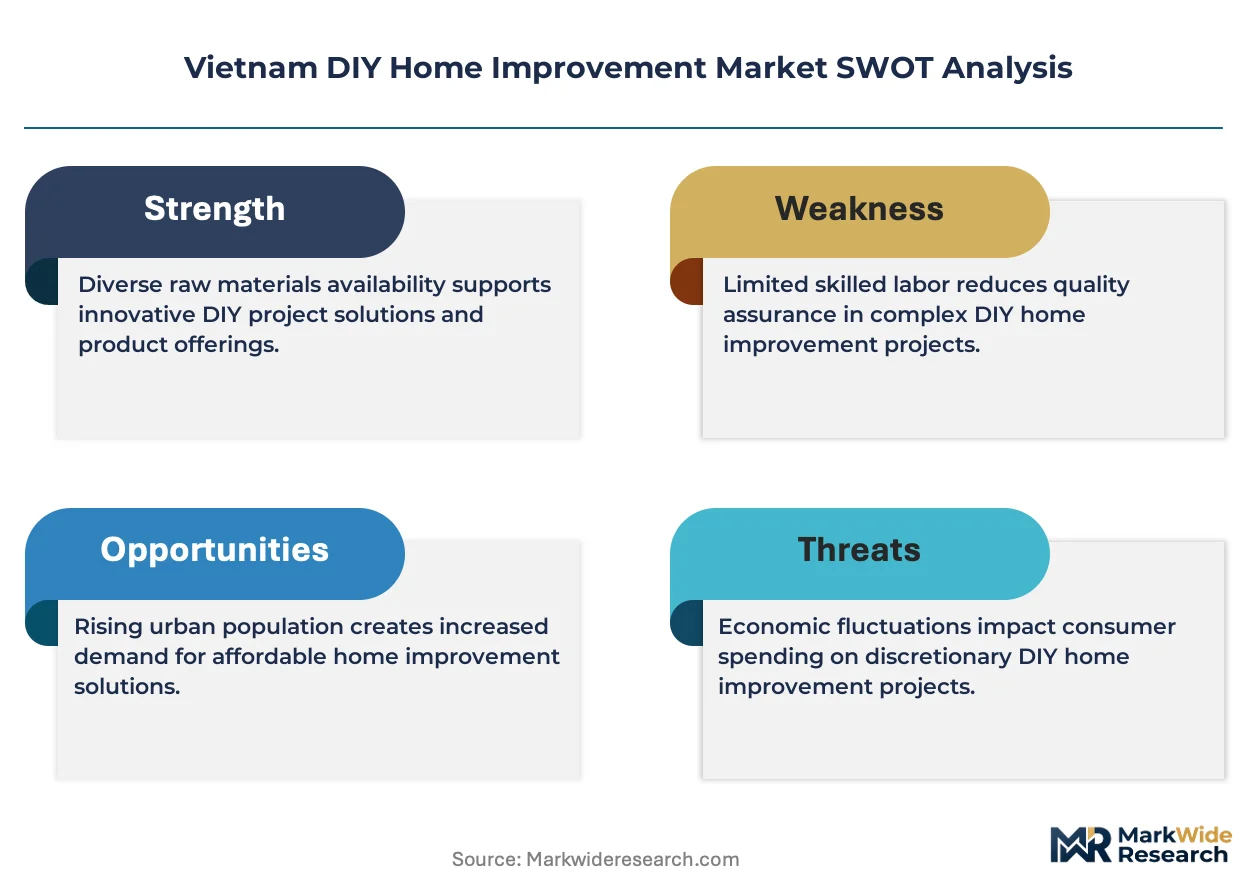
- Green Building Code Enforcement:The Ministry of Construction's mandatory VOC emissions standards for interior coatings in metropolitan zones are accelerating certified low-VOC paint adoption among renovation contractors.
- Apartment Ownership Concentration:Rising ownership rates in the Red River Delta and Southeast economic corridors are generating sustained hardware and power tool demand from urban residential clusters.
- Tropical Climate Product Innovation:Mold-resistant and UV-stable surface finishes formulated specifically for high-humidity environments are expanding reapplication cycles and category value capture.
Market Restraints
- Import Clearance Friction:BIS-equivalent conformity assessment procedures for foreign building material suppliers create extended lead times for insulation and window systems entering Vietnamese ports.
- Logistics Network Gaps:Provincial market penetration remains uneven, with secondary cities outside Ho Chi Minh City and Hanoi facing higher last-mile costs for bulky hardware shipments.
- Skilled Labor Scarcity:Certified installation technicians for water-efficient fixtures and advanced sanitaryware remain concentrated in major urban centers, limiting premium product uptake in peri-urban zones.
Strategic Opportunities
- Central Highlands Expansion:Da Nang and surrounding provinces present underpenetrated demand for DIY retail as middle-class housing stock matures and renovation activity accelerates.
- Online Channel Maturation:E-commerce platforms with dedicated construction material logistics are capturing provincial customers previously served only by traditional hardware distributors.
- Energy-Efficient Retrofit Mandates:Provincial implementation of energy-efficient building codes will create specification requirements for high-performance windows and insulation across northern, central, and southern construction zones.
Industry Challenges
- Certification Timeline Compression:Quality assurance testing for tropical climate product ratings requires specialized laboratory capacity that currently creates bottlenecks for new market entrants.
- Contractor Channel Dependence:Bulk purchasing control by renovation contractors limits direct-to-consumer brand building and margin capture for DIY-focused suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam DIY Home Improvement Market |
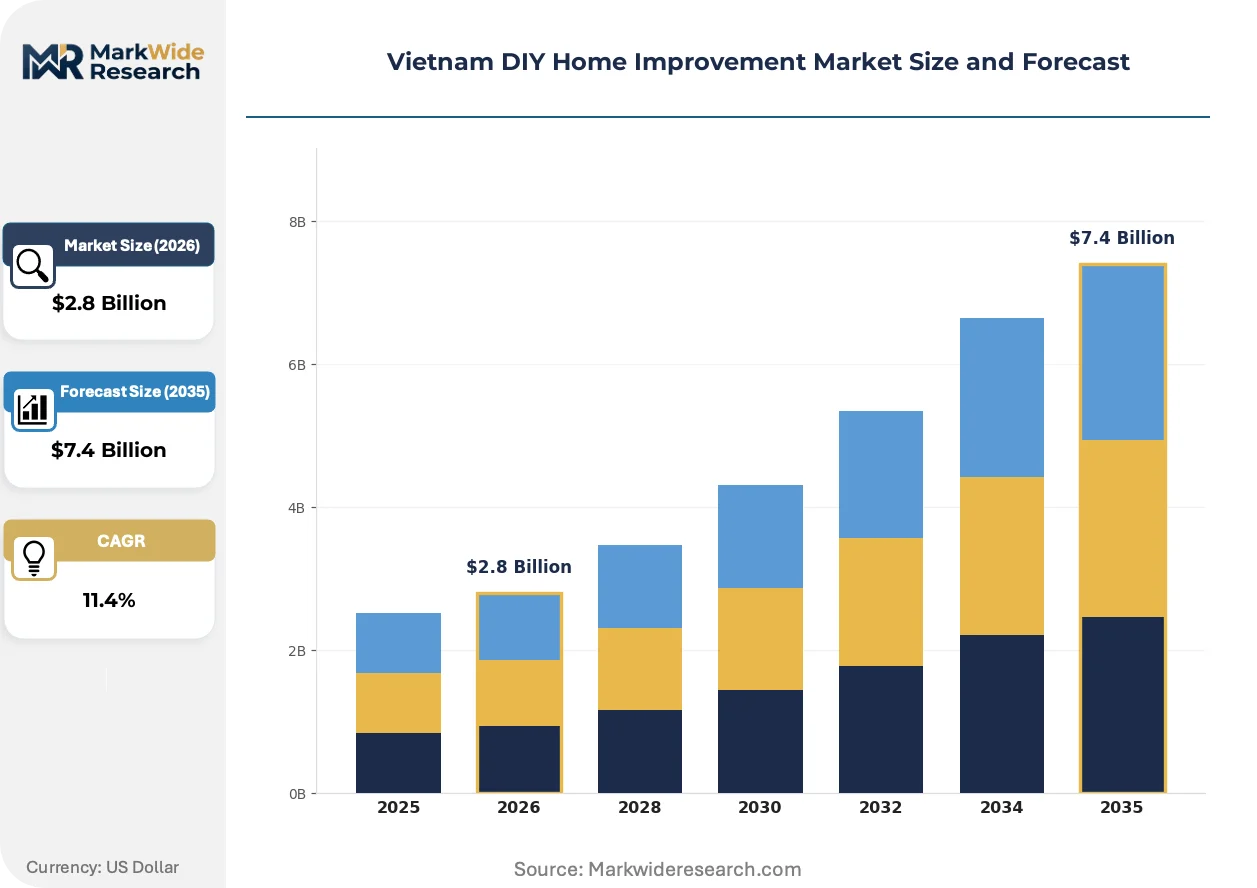
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paint, Hardware, Flooring Distribution Channel: Online Retail, Specialty Stores, Warehouse Clubs, Home Goods Stores Customer Type: Homeowners, Renters, Contractors, DIY Enthusiasts Application: Renovation, Maintenance, Decoration, Landscaping |
| Companies Covered | Kohler, HomePro Vietnam, Ambassador Signage & Lighting, Nippon Paint Vietnam, Jotun Paints Vietnam, Rockwool, ACE Home Center Vietnam, LIXIL (INAX), Andersen Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam DIY Home Improvement Market Evolving Landscape
Digital visualization tools and augmented reality applications are transforming how Vietnamese homeowners plan renovations, compressing the decision cycle between inspiration and purchase while reducing costly material misordering.
Virtual room design software is virtualizing the traditional showroom experience for kitchen and bathroom planning. Urban homeowners in Ho Chi Minh City are adopting these tools at accelerating rates, particularly for tile and fixture selection. The technology is virtualizing physical retail dependency, enabling smaller provincial retailers to compete with flagship showrooms through tablet-based consultation services.
The Ministry of Construction's progressive tightening of green building codes is mandating water-efficiency standards for plumbing fixtures and low-emission classifications for interior coatings. This regulatory trajectory is forcing product portfolio restructuring among sanitaryware and paint suppliers. Northern provinces with older housing stock are experiencing the most acute compliance pressure, driving replacement demand for non-conforming fixtures.
Buyers are consolidating purchases through contractor-managed procurement rather than direct retail sourcing, shifting margin capture toward installation service bundling. Traditional hardware distributors in Hanoi are responding by developing contractor loyalty programs with volume-based pricing tiers. This pattern is most pronounced in high-value renovation segments where project complexity discourages homeowner self-procurement.
Vietnam DIY Home Improvement Market Segmentation
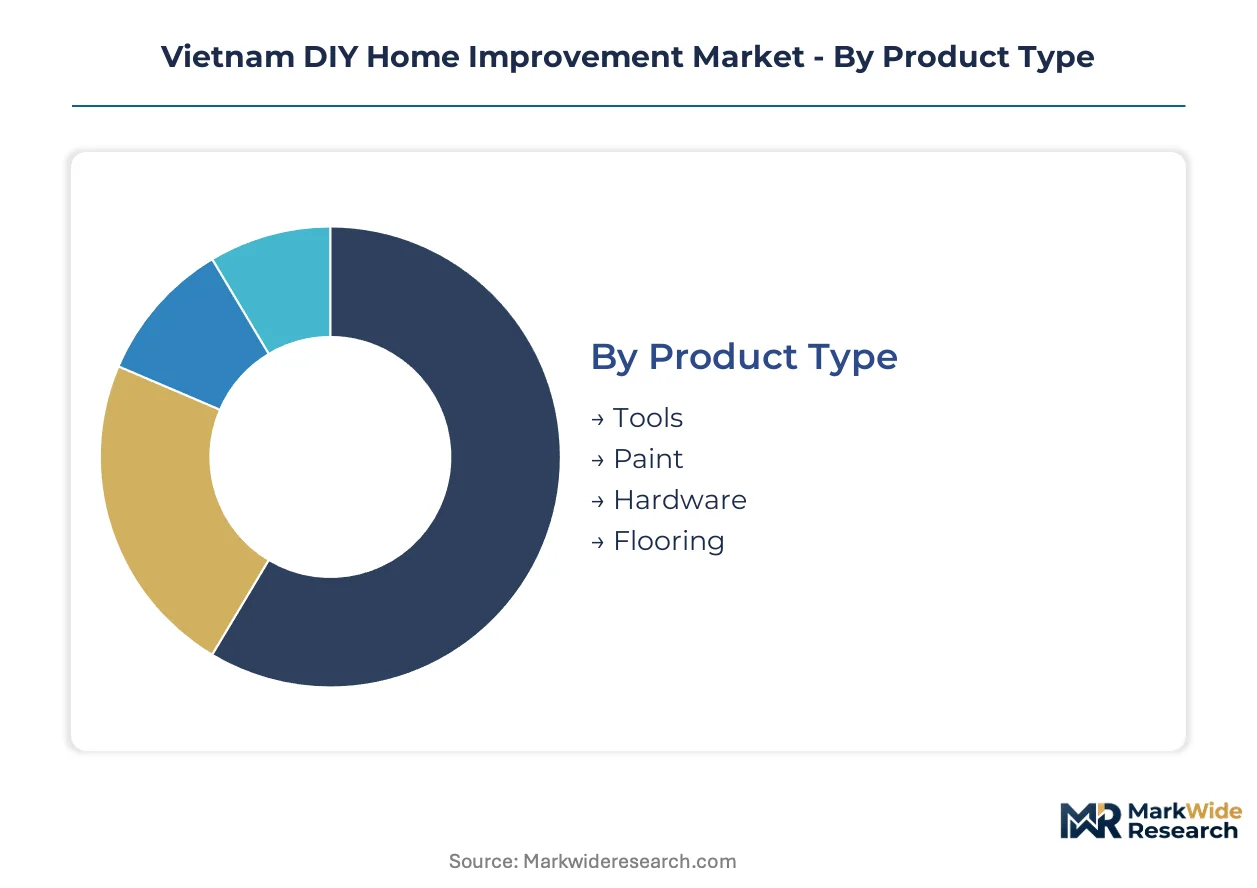
Segmentation in Vietnam's DIY home improvement market reveals how tropical climate conditions, urban housing density, and contractor channel dominance reshape category priorities across product types and customer groups. Understanding these divides exposes where margin concentrates and which channels are capturing the shift from cash-only to financed purchasing.
Product Type:
Mature categories with established reapplication cycles dominate current revenue, while emerging segments with climate-specific formulations are capturing premium positioning.
- Tools:Power equipment and hand tool assortments rated for tropical humidity exposure, including corrosion-resistant coatings and sealed motor housings. Demand clusters in Ho Chi Minh City and Hanoi apartment renovation clusters where rising ownership rates sustain replacement cycles.
- Paint:Low-VOC interior coatings and exterior finishes with mold resistance and UV stability certifications mandated by Ministry of Construction standards for metropolitan zones. Northern provinces with older housing stock face acute compliance pressure, accelerating certified product adoption.
- Hardware:Fastening systems, plumbing fittings, and electrical components.
- Flooring:Surface finishes with moisture barriers and dimensional stability ratings.
Paint handles the majority of throughput; Tools is gaining share fastest as financed purchasing unlocks power equipment access for first-time homeowners.
Distribution Channel:
Channel evolution tracks logistics network maturation and the compression of decision cycles through digital tools.
- Online Retail:E-commerce platforms with dedicated construction material logistics penetrating provincial markets previously served only by traditional hardware distributors. Da Nang and Central Highlands provinces present underpenetrated demand as middle-class housing stock matures.
- Specialty Stores:Focused retailers with technical consultation capacity for tile and fixture selection.
- Warehouse Clubs:Volume-oriented formats with contractor loyalty programs and tiered pricing structures.
- Home Goods Stores:Showroom-driven formats sustaining conversion rates in secondary cities through tablet-based design consultation services.
Home Goods Stores anchor current volume; Online Retail is climbing the fastest as last-mile costs decline outside major urban centers.
Customer Type:
Procurement control separates direct purchasers from those funneled through installation service bundling.
- Homeowners:Urban apartment owners in Red River Delta and Southeast economic corridors driving sustained hardware demand. Financing platforms and pay-later schemes are democratizing access to premium materials previously restricted to cash buyers.
- DIY Enthusiasts:Self-directed modifiers with technical confidence and tool ownership.
- Contractors:Renovation professionals controlling bulk purchasing and limiting direct-to-consumer brand building for high-complexity projects. Traditional Hanoi distributors are responding with volume-based pricing tiers and loyalty programs.
- Renters:Transitory residents with constrained modification rights and portable solution preferences.
Contractors manage the largest transaction volumes; Homeowners are expanding most quickly as apartment ownership concentrates in urban corridors.
Application:
Application mix reflects housing stock age distribution and regulatory compliance timelines across northern, central, and southern construction zones.
- Renovation:Kitchen and bathroom upgrades dominating value generation in Ho Chi Minh City and Hanoi. Green building code enforcement on water-efficiency standards and low-emission classifications is forcing fixture replacement in non-conforming older stock.
- Maintenance:Functional repair cycles compressed by tropical humidity degradation.
- Decoration:Aesthetic upgrading through color and surface finish changes.
- Landscaping:Exterior modification with UV-stable and moisture-resistant material specifications.
Renovation commands the steepest expansion trajectory; Maintenance provides the recurring revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Construction's green building codes and provincial energy-efficiency mandates are redistributing home improvement demand across Vietnam's three macro-regions. Northern provinces face accelerated fixture replacement cycles. Central coastal cities capture emerging middle-class renovation spending. Southern economic corridors sustain volume leadership through apartment ownership concentration.
Red River Delta
Hanoi and surrounding provinces drive certified low-VOC paint demand as older housing stock faces acute compliance pressure. The Ministry of Construction's metropolitan emissions standards force replacement of non-conforming interior coatings. Bac Ninh and Hai Duong industrial zones host distributor consolidation as secondary city hardware networks mature.
North Central Coast
Thanh Hoa and Nghe An provinces generate maintenance-heavy demand from humidity-degraded surface finishes in aging residential stock. Provincial implementation of water-efficiency standards lags national timelines, creating specification gaps for sanitaryware suppliers. Vinh City anchors emerging contractor networks serving peri-urban renovation clusters.
South Central Coast
Da Nang and Quang Nam province present underpenetrated DIY retail opportunity as middle-class housing stock matures. The city's quality assurance testing capacity attracts foreign building material suppliers seeking regional conformity assessment shortcuts. Hoi An's tourism-driven restoration economy sustains niche premium finish demand.
Southeast Economic Corridor
Ho Chi Minh City and Binh Duong province concentrate the steepest power tool and hardware volume growth. Rising apartment ownership rates in Thu Duc City and Di An sustain showroom-driven conversion for kitchen and bathroom renovations. Dong Nai province's logistics infrastructure reduces last-mile costs for bulky material shipments.
Mekong Delta
Can Tho and Long An provinces exhibit lagging online retail penetration for construction materials despite improving provincial logistics networks. The region's dispersed rural housing stock limits contractor channel density. Pay-later platform adoption remains concentrated in urban Can Tho rather than surrounding agricultural zones.
Vietnam DIY Home Improvement Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Vietnam's home improvement sector. Nationwide retail networks with showroom-driven conversion capabilities anchor volume capture in secondary cities. Product-specialist suppliers compete on tropical climate certifications and contractor loyalty programs. Three archetypes dominate: Japanese-standard sanitaryware specialists, Thai-origin multi-category retailers, and paint formulators with localized color palettes. Competitive moves concentrate on contractor loyalty program expansion and provincial distribution network densification.
Within the retail-channel tier, HomePro Vietnam exemplifies nationwide store network leverage for secondary city penetration. Nippon Paint Vietnam and Jotun Paints Vietnam occupy positions as coating specialists competing on humidity-resistant formulations. LIXIL (INAX) represents the Japanese-standard sanitaryware archetype commanding contractor specification preference. These three anchors illustrate how origin-based quality positioning and climate-specific product development separate premium-tier suppliers from commodity competitors.
| Leading Market Players |
|---|
| Kohler |
| HomePro Vietnam |
| Ambassador Signage & Lighting |
| Nippon Paint Vietnam |
| Jotun Paints Vietnam |
| Rockwool |
| ACE Home Center Vietnam |
| LIXIL (INAX) |
| Andersen Corporation |
| Others |
Value Network & Pricing Analysis
Hai Phong Port logistics corridors anchor cost dynamics across Vietnam's DIY home improvement sector, concentrating supply-side pricing power with Thai-origin multi-category retailers while forcing provincial distributors into volume-based tier structures to offset last-mile premiums.
Pricing Analysis
Certification level creates the primary spread between Ministry of Construction-compliant low-VOC coatings and uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on tropical climate ratings and contractor volume commitments. Cost compression in the economy tier is intensifying because provincial distributors are absorbing freight premiums to compete with HomePro Vietnam's national footprint. First-time homeowners using pay-later platforms exhibit lowest price sensitivity, while peri-urban maintenance contractors remain most cost-conscious.
Supply Chain Analysis
Tariff exposure between Thailand and Vietnam dominates supply chain risk calculations for sanitaryware and power tool imports. Manufacturing concentrates in Thailand, China, and South Korea for finished goods, while raw formulation inputs draw from Singapore and Taiwan chemical hubs. Single-source vulnerability persists for mold-resistant additive suppliers serving Nippon Paint Vietnam and Jotun Paints Vietnam. Distribution runs through contractor-managed procurement networks with loyalty-program volume tiers, compressing direct-to-consumer margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's DIY home improvement sector presents a defensive-moat story anchored in regulatory entrenchment: Ministry of Construction certification timelines create structural barriers that entrench incumbent coating and sanitaryware suppliers against commodity importers.
For Market Incumbents: Pre-empt provincial distributor consolidation by locking exclusive logistics partnerships in Da Nang and Can Tho before secondary city networks mature. Deepen backward integration into tropical climate testing laboratories to compress certification bottlenecks that currently delay competitor product launches. Threat substitution from Chinese direct-to-consumer e-commerce platforms intensifies margin pressure in the hardware category. For New Entrants and Emerging Players: Pursue Central Highlands contractor networks in Quang Nam and Binh Dinh provinces where incumbent loyalty programs remain underdeveloped. The most penetrable segment is mid-tier flooring with moisture-barrier specifications for apartment renovations in Da Nang's maturing housing stock. Go-to-market angle should anchor on tablet-based virtual room design services that virtualize showroom dependency without flagship real estate investments. For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese trading house subsidiaries seeking to monetize non-core ASEAN building material positions. Long-term viability frames around energy-efficient retrofit mandate implementation timelines across northern, central, and southern construction zones. Signal to monitor is provincial adoption acceleration of water-efficiency standards that would force replacement cycles for non-conforming sanitaryware inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Contractor Loyalty Program Expansion | Volume-based tier pricing locks procurement control in Hanoi's renovation corridors. |
| Provincial Logistics Partnership | Last-mile cost reduction in Da Nang enables showroom-driven conversion without flagship investment. |
| Certification Laboratory Investment | In-house tropical climate testing compresses Ministry of Construction approval timelines for new formulations. |
| Pay-Later Platform Integration | Financed purchasing access unlocks premium material adoption among first-time apartment owners. |
| Virtual Design Tool Deployment | Tablet-based consultation services let provincial retailers compete with HomePro Vietnam's flagship network. |
Research Methodology
The analysis maps paint and coatings, power tools, sanitaryware, and hardware fastening systems, each validated through contractor procurement managers, provincial distributor principals, and Ministry of Construction certification officers. Primary interviews with renovation contractors in Ho Chi Minh City and Hanoi combined with secondary validation against customs records, building permit databases, and retailer point-of-sale systems. Bottom-up SKU-level demand modeling triangulated against top-down construction sector value-add estimates.
Assumption sets held green building code enforcement timelines and logistics network densification rates fixed while varying apartment ownership growth and pay-later platform penetration. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and application purpose across the projection horizon. CAGRs derived from historical reapplication cycle frequencies in tropical humidity conditions and provincial housing stock age distributions.
Macroeconomic conditions sit as an overlay; deviation in Dong exchange rate volatility or construction sector credit availability would shift the trajectory of premium material adoption. Forecasts reflect documented assumptions on regulatory implementation pacing and logistics infrastructure investment flows. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Home Remodeling Market