
 Europe Luxury Furniture Market | 2026-2036
Europe Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Furniture Market Foresight
Italy's Brianza manufacturing corridor is fragmenting as heritage craft houses scale automated finishing lines alongside hand-worked upholstery cells. Minotti leverages vertical integration from tannery partnerships to flagship retail to protect margin pools in leather seating. Molteni&C anchors its position through architect co-design programs that lock in specification dominance for corporate headquarters projects. Roche Bobois competes via rapid customization platforms delivering six-week bespoke sofas to residential clients across France and Belgium.
Europe luxury furniture denotes high-design interior products manufactured with premium materials, precise joinery tolerances, and limited production runs for affluent residential, hospitality, and corporate environments. Construction employs solid hardwood frames, full-grain leather, hand-tied spring systems, and multi-layer lacquer finishes achieving durability benchmarks exceeding standard contract furniture by significant margins. Wood and leather material segments command the deepest margin pools due to raw material scarcity and artisan labor intensity, while upholstery dominates unit volume through fabric sofa demand in urban residential towers. The hospitality end user segment generates the fastest growth as boutique hotel chains across Portugal and Spain commission signature interior packages from single-source European ateliers.
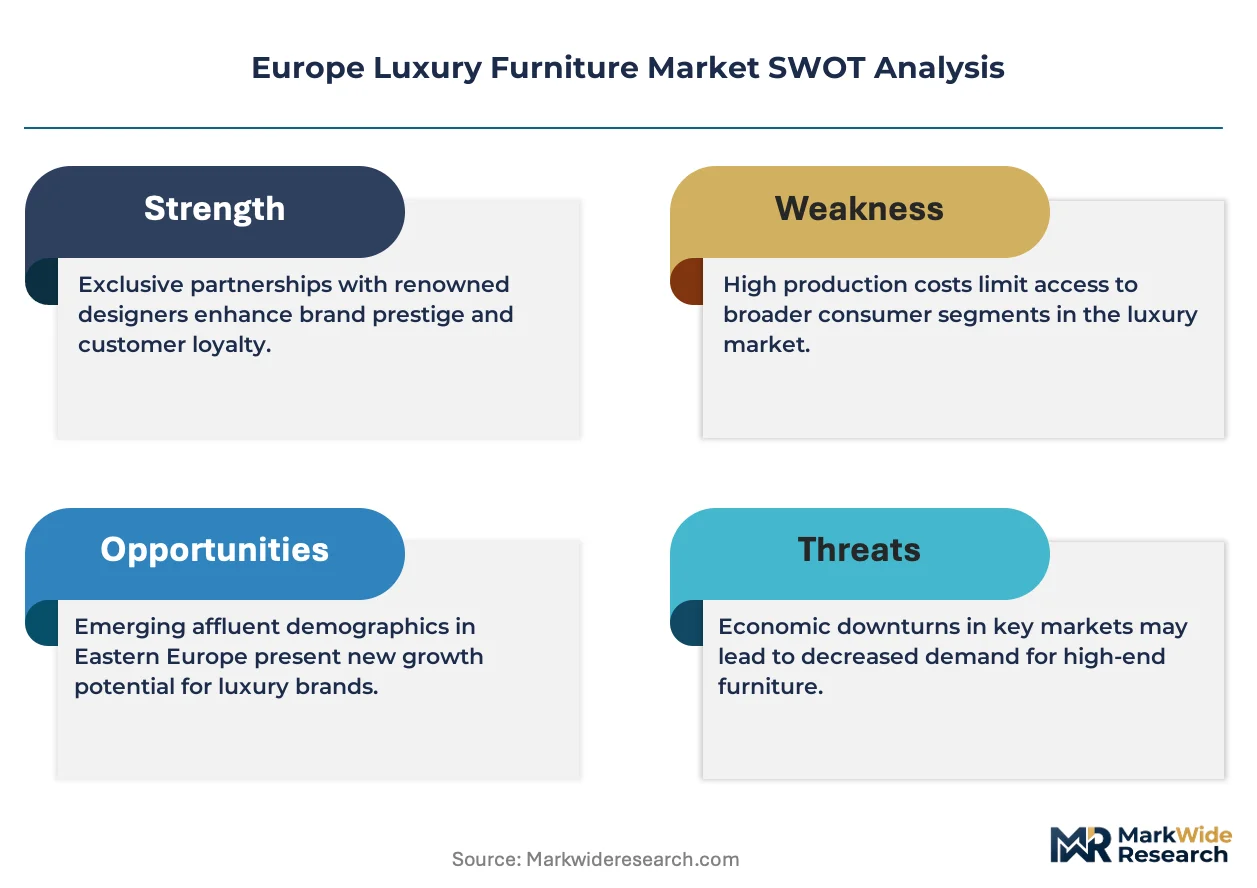
REACH chemical restrictions and the EU Green Deal's embodied carbon disclosure requirements shape material sourcing decisions, forcing reformulation of adhesives and finishes across the supply chain. ECHA scrutiny of flame retardant compounds in upholstered products creates compliance costs that favor larger manufacturers with dedicated regulatory teams. Stakeholders must monitor CSRD supply chain reporting mandates and decide whether to absorb traceability investments or consolidate supplier bases to reduce audit burden.
Market Dynamics
The EU Green Deal's embodied carbon disclosure rules are forcing European luxury furniture manufacturers to reconfigure supply chains around certified sustainable timber and low-VOC finishing systems. Compliance investments are compressing margin pools for mid-tier producers while amplifying competitive advantages for vertically integrated ateliers with captive material sourcing.
Growth Catalysts
- Hospitality fit-out demand:Boutique hotel chains across Portugal and Spain are commissioning signature interior packages from single-source European ateliers, driving specification lock-in for premium seating and case goods.
- REACH chemical reformulation:Pressure from ECHA scrutiny of flame retardant compounds is accelerating R&D investment in halogen-free upholstery treatments, creating first-mover advantages for compliant manufacturers.
- CSRD supply chain mandates:Corporate sustainability reporting requirements are pushing high-net-worth residential buyers toward traceable timber certification schemes, concentrating procurement with audited suppliers.
Market Restraints
- Raw material scarcity:Full-grain leather and certified sustainable hardwood face constrained supply from European tanneries and managed forestry operations, amplifying input cost volatility.
- Artisan labor concentration:Hand-tied spring systems and multi-layer lacquer finishing depend on skilled craftspeople concentrated in Italy's Brianza corridor, creating geographic supply risk.
- Regulatory compliance fragmentation:Divergent national implementations of EU Green Deal carbon accounting create audit complexity for cross-border manufacturers serving multiple member states.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Denmark show rising demand for bespoke residential interiors from Milan-based design houses, with limited local competition at the premium tier.
- Architect co-design platforms:Direct specification relationships with corporate headquarters project designers offer margin protection through early-stage design influence and exclusivity agreements.
- Rapid customization technology:Six-week bespoke sofa production cycles enabled by modular frame systems and digital fabric libraries are capturing time-sensitive residential clients in France and Belgium.
Industry Challenges
- Master craftsperson succession gaps:Traditional hand-finishing techniques face generational transfer risks as aging artisans retire without adequate apprenticeship pipeline depth in Brianza workshops.
- Dual certification timelines:Simultaneous pursuit of FSC chain-of-custody and EU Ecolabel approvals extends product launch cycles, delaying revenue recognition for seasonal collections.
- Legacy ERP integration friction:Carbon accounting software deployment encounters data architecture conflicts with established production planning systems, complicating CSRD reporting automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Furniture Market |
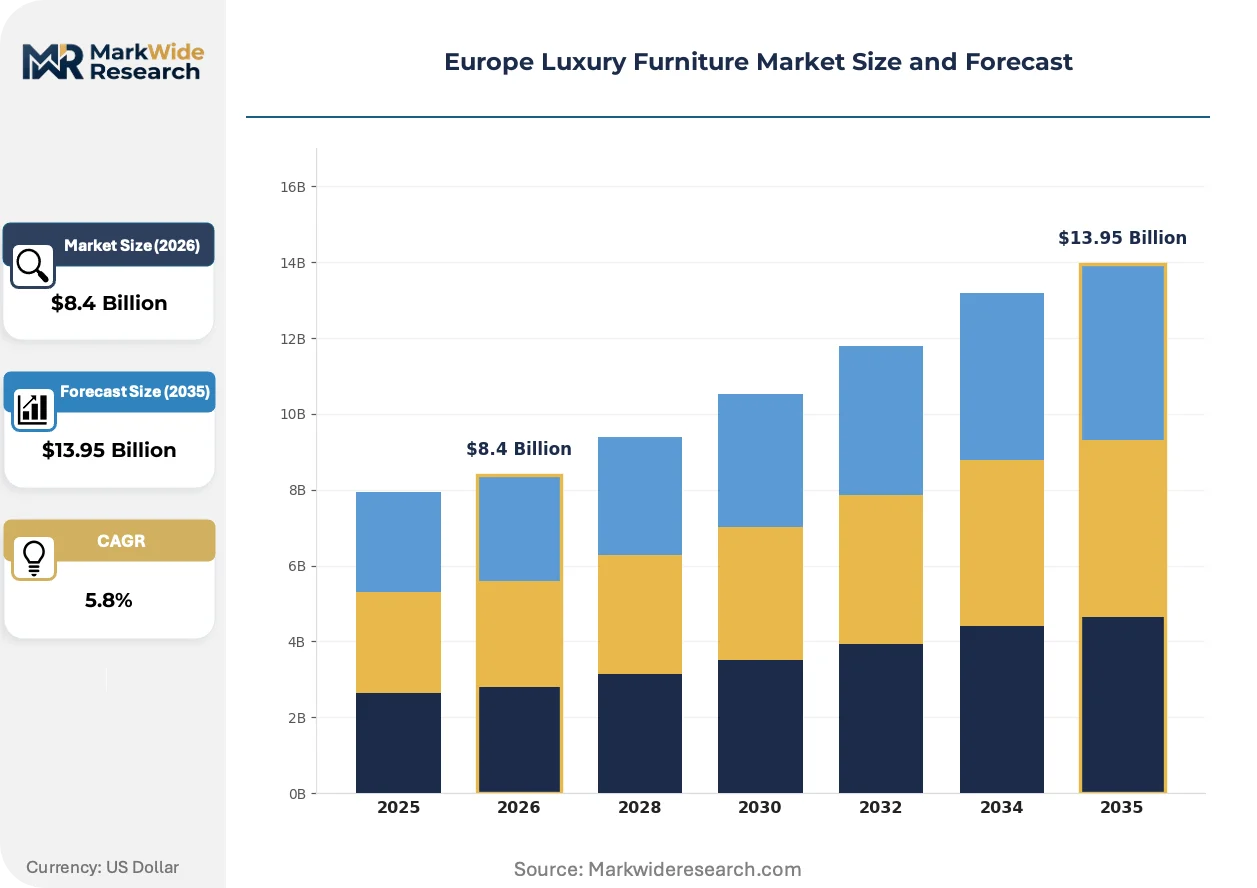
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Leather, Upholstery, Metal End User: Residential, Hospitality, Retail, Corporate Design Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | Minotti, Molteni&C, Roche Bobois, Fritz Hansen, Cassina, Poltrona Frau, Ligne Roset, Poliform, B&B Italia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Furniture Market Shifts & Advancements
Digital fabrication and regulatory transparency are converging to reshape how European luxury furniture is designed, certified, and delivered to affluent residential and commercial clients.
Parametric design software paired with CNC machining is digitizing the transition from hand-drawn drafts to precision-cut joinery components. High-end residential developers in London and Paris are specifying digitally verified tolerances for custom millwork packages. This compression of design-to-production cycles is reducing revision rounds while preserving artisan finishing stages for surface treatments.
REACH authorization requirements for isocyanates in polyurethane foam are forcing reformulation of cushioning systems across upholstered product lines. Italian manufacturers are accelerating water-based adhesive substitution programs to preempt ECHA restriction list expansion. The hospitality segment faces the steepest compliance curve due to fire safety certification interdependencies with foam density specifications.
Direct-to-architect digital platforms are displacing traditional showroom-dependent specification processes for corporate headquarters projects. Milan and Frankfurt-based design studios now source full interior packages through password-protected online catalogs with real-time carbon footprint dashboards. This channel shift concentrates procurement authority with specification consultants rather than end-user purchasing departments.
Europe Luxury Furniture Market Segmentation
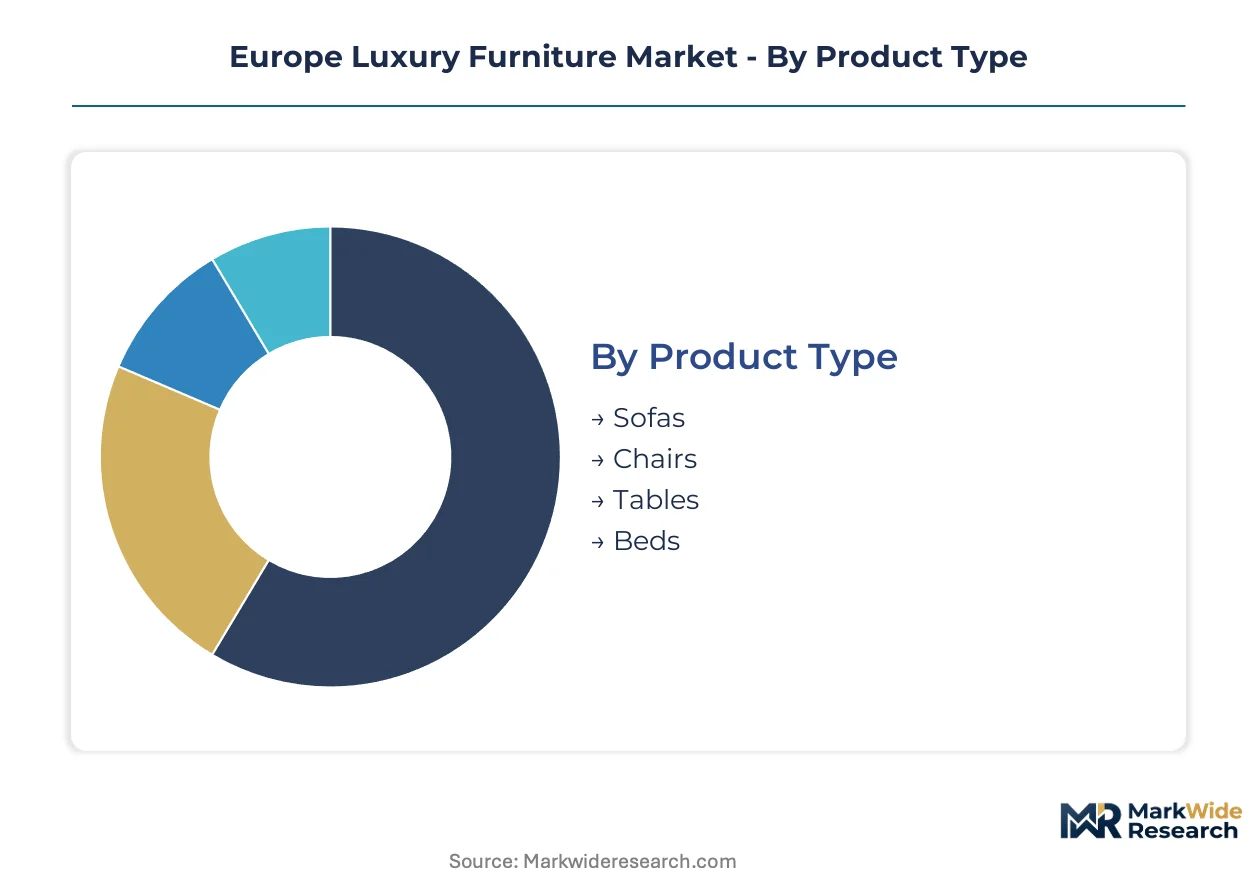
Segmentation in European luxury furniture reveals how material scarcity, regulatory pressure, and end-use specification patterns concentrate margin pools across distinct product and customer categories. Understanding these partitions exposes where vertically integrated ateliers can defend pricing power against commoditization.
Product Type:
Cost tier stratification across seating, surface, and sleep products determines production complexity and artisan labor intensity.
- Sofas:Multi-component upholstered systems requiring hand-tied spring assemblies and modular frame engineering. Demand concentrates in Paris and Milan residential towers where space constraints favor compact sectionals with premium fabric libraries.
- Chairs:Sculptural seating ranging from ergonomic task designs to ceremonial armchairs. Portuguese boutique hotels are commissioning signature chair collections as anchor pieces for lobby and restaurant zones, driving specification lock-in.
- Tables:Dining and conference surfaces employing solid hardwood slabs or stone inlay.
- Beds:Platform and canopy frames with integrated storage and adjustable base compatibility.
Sofas command the established base. The steepest expansion runs through Chairs.
Material:
Raw material sourcing geography and certification burden shape competitive positioning across the four primary input categories.
- Wood:Solid hardwood frames and veneer systems from FSC-certified European forestry operations. Brianza manufacturers face compressed margins from dual FSC and EU Ecolabel certification timelines, favoring larger ateliers with dedicated compliance teams.
- Leather:Full-grain hides from Italian and French tanneries with vegetable-tanning and aniline-dye processes. Constrained supply from European tanneries amplifies price volatility for seating upholstery in high-net-worth residential procurement.
- Upholstery:Fabric and foam cushioning systems.
- Metal:Brass, bronze, and powder-coated steel for structural and decorative elements.
Wood commands the established base. Upholstery is gaining share fastest.
End User:
Customer type determines specification authority, purchase cycle length, and sensitivity to carbon disclosure requirements.
- Residential:Affluent individual buyers procuring for primary and secondary homes. Sweden and Denmark show rising demand for Milan-sourced bespoke interiors with limited local premium competition.
- Hospitality:Boutique hotel chains and independent properties commissioning signature interior packages. Spain and Portugal properties are driving the steepest growth as they seek single-source atelier relationships for complete fit-outs.
- Retail:Flagship stores and luxury showroom environments.
- Corporate:Headquarters and executive floor installations.
Residential commands the established base. Hospitality delivers the steepest expansion trajectory.
Design Style:
Aesthetic positioning determines architect and designer specification relationships across project types.
- Modern:Clean lines, minimal ornamentation, and material-forward expression. Frankfurt and London corporate headquarters projects are specifying modern collections through direct-to-architect digital platforms with real-time carbon dashboards.
- Traditional:Historic reference forms with hand-applied decorative techniques. Aging artisan populations in Brianza create succession risk for marquetry and carving specializations.
- Rustic:Weathered finishes and reclaimed material emphasis.
- Minimalist:Extreme reduction and functional purity.
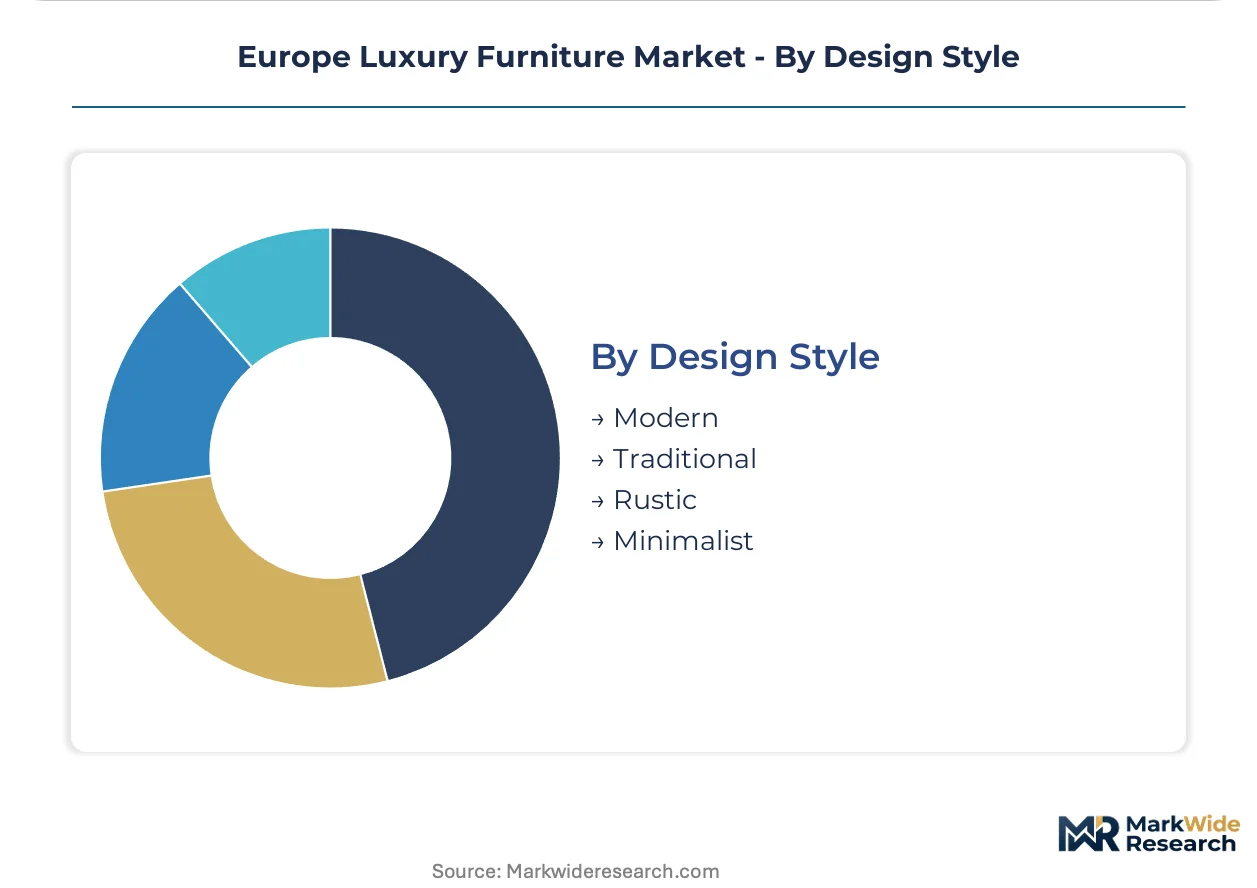
Traditional commands the established base. Modern shows the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA chemical scrutiny and EU Green Deal carbon disclosure rules are reconfiguring manufacturing footprints across the continent. REACH compliance investments favor larger ateliers with dedicated regulatory teams.
Italy
Milan's Brianza corridor hosts the densest concentration of heritage craft houses and automated finishing ateliers. CSRD supply chain mandates push manufacturers toward FSC-certified timber sourcing. Artisan workshops in Como and Monza supply premium hospitality fit-outs across Southern Europe.
France
Parisian residential towers drive demand for compact sectionals with premium fabric libraries. ANSM and CNIL oversight intersects with EU chemical regulations for upholstered products. Lyon-based design studios source through direct-to-architect digital platforms with real-time carbon dashboards.
Spain
Portuguese and Spanish boutique hotel chains commission signature interior packages from single-source ateliers. National implementations of EU Green Deal carbon accounting create audit complexity for cross-border manufacturers. Barcelona design houses scale rapid customization platforms for time-sensitive residential clients.
Germany
Frankfurt corporate headquarters projects specify modern collections through architect co-design programs. KBA and federal environmental regulations add compliance layers to REACH requirements. Stuttgart industrial designers influence specification authority for executive floor installations.
Sweden
Rising demand for Milan-sourced bespoke interiors meets limited local premium competition in Stockholm residential developments. Swedish environmental protection agency standards align with EU Ecolabel timelines. Gothenburg architects specify traceable timber certification schemes for high-net-worth procurement.
Europe Luxury Furniture Market Competitive Landscape
Heritage craft houses and industrial ateliers split the market between artisan labor intensity and automated finishing scale. The vendor base concentrates in Italy's manufacturing corridor with secondary clusters in France and Scandinavia. Three archetypes dominate: vertically integrated tannery-to-retail operators, architect co-design specialists, and rapid customization platform operators. Competitive moves center on M&A for captive material sourcing and strategic partnerships with hospitality chains for specification lock-in.
Within the heritage-integrated tier, Minotti and Poltrona Frau represent vertically anchored positions spanning raw material partnerships to flagship retail networks. Molteni&C exemplifies the architect-centric archetype through specification relationships with corporate headquarters designers. Roche Bobois occupies the rapid-customization vector with six-week bespoke production cycles for residential clients across France and Belgium.
| Leading Market Players |
|---|
| Minotti |
| Molteni&C |
| Roche Bobois |
| Fritz Hansen |
| Cassina |
| Poltrona Frau |
| Ligne Roset |
| Poliform |
| B&B Italia |
| Others |
Supply & Pricing Matrix
The Brenner Pass freight corridor's volatile fuel surcharges and Alpine tunnel capacity constraints amplify cost differentials between Milan-based ateliers and Nordic distributors. Brianza manufacturers pass through logistics premiums to Paris and Stockholm residential buyers while absorbing margin compression on hospitality bulk contracts. This freight-cost wedge stratifies final pricing across EU member states independent of product specification parity.
Pricing Analysis
Price spreads between Milan-sourced bespoke seating and comparable Nordic-produced alternatives exceed thirty percent at retail. Three-tier pricing structure across artisan-grade, atelier-standard, and contract-economy levels dominates, with differentiation driven by FSC chain-of-custody certification depth and hand-finishing labor hours. Pricing pressure stems from REACH chemical reformulation costs concentrated in foam cushioning systems. Corporate hospitality buyers exhibit lowest price sensitivity due to specification lock-in incentives, while residential developers in secondary French cities negotiate hardest on volume.
Supply Chain Analysis
Extended ninety-day payment terms from Brianza tanneries to frame manufacturers strain working capital for mid-tier ateliers. Geographic supply concentrates in Italy, France, and Sweden, with raw material dependencies on full-grain leather from Tuscan tanneries, FSC-certified Slovenian oak, and Belgian linen weavers. Single-source vulnerability runs through aging master craftspeople in Como and Monza workshops. Distribution runs through architect-specification digital platforms displacing traditional showroom channels for corporate headquarters projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-architect digital platforms are reconfiguring this market toward ecosystem economics where specification authority aggregates with design consultants rather than end purchasers. Interoperability between carbon accounting dashboards and procurement systems is accelerating this platform shift across Frankfurt and London corporate projects.
For Market Incumbents: Insulate specification relationships through exclusive co-design partnerships with starchitecture firms for headquarters fit-outs. Capture tannery capacity via long-term hide offtake agreements to preempt input cost volatility from ECHA chemical scrutiny. Lock in hospitality chain procurement through single-source interior package contracts spanning seating, surface, and lighting categories. For New Entrants and Emerging Players: Swedish and Danish residential developments show geographic underpenetration by Milan-based design houses with limited Stockholm premium competition. Target rapid customization platforms delivering six-week bespoke production cycles to time-sensitive Paris and Brussels residential clients. Enter through digital-native specification tools with embedded carbon footprint transparency to bypass incumbent showroom infrastructure. For Investors and Strategic Acquirers: Architect-co-design specialist ateliers with locked corporate headquarters relationships represent the priority acquisition archetype for multiple expansion. Long-term viability hinges on succession pipelines for hand-finishing craftspeople and ERP integration readiness for CSRD reporting automation. Monitor ECHA restriction list expansion timelines as inflection signals for compliant manufacturer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Tannery Partnership Lock-in | Captures full-grain leather supply from Tuscan operations ahead of REACH reformulation deadlines. |
| Architect Platform Integration | Embed carbon dashboard APIs into Frankfurt and London design studio procurement workflows. |
| Hospitality Chain Exclusivity | Single-source fit-out contracts with Portuguese and Spanish boutique properties secure specification lock-in. |
| Rapid Customization Scale-up | Six-week bespoke production cycles capture time-sensitive residential demand in France and Belgium. |
| CSRD Compliance Automation | ERP carbon accounting modules reduce audit burden for cross-border manufacturer reporting. |
Research Methodology
Cross-validation between artisan workshop production records and hospitality procurement databases anchors the qualitative findings in verifiable output volumes. Primary interviews with Brianza atelier owners, Milan-based specification consultants, Portuguese hotel development directors, and Frankfurt corporate facility managers combined with secondary validation from ECHA chemical restriction filings, FSC chain-of-custody registries, EU Green Deal implementation texts, and Italian industrial association export data. Bottom-up production capacity modeling and top-down end-use demand estimation triangulate market sizing.
Calibration against historical CAGRs from comparable luxury goods categories and furniture subsegments refines the projection framework. Segmentation dimensions span product type, material category, end-user vertical, and design style across the analysis window. CAGRs derive from regression against macroeconomic indicators, regulatory implementation timelines, and hospitality development pipeline data. Forecast inputs include REACH chemical authorization schedules and CSRD reporting mandate phase-ins.
Practitioners should monitor ECHA restriction list expansions, FSC certification backlog durations, and Alpine logistics corridor capacity for early signals. Forecasts reflect assumptions regarding sustained high-net-worth residential demand and hospitality fit-out continuation. Macroeconomic contraction, regulatory acceleration beyond modeled timelines, or generational craftsperson attrition exceeding replacement rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Home Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
United Kingdom Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Furniture Laminate Market
Furniture
Wooden Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Recliner Chair Market
Furniture
Armchairs with Footrest Market
Furniture
Italy Luxury Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
HORECA Furniture Market