
 US Contract Furniture and Furnishing Market | 2026-2036
US Contract Furniture and Furnishing Market Size, Share, and Industry Trends Forecast 2026-2036
US Contract Furniture and Furnishing Market Analytics
The US contract furniture and furnishing sector is pivoting between premium custom fabrication and commodity-grade specification, with project budgets diverging sharply across hospitality and corporate verticals. Steelcase Inc leverages its domestic manufacturing footprint to control lead times for large-scale office rollouts. Bernhardt Hospitality anchors its position through specialized woodworking capabilities serving boutique hotel chains. Haworth competes on configurable systems that integrate power and data infrastructure.
Contract furniture and furnishing encompasses durable, specification-grade interior products engineered for commercial installation rather than residential use, typically meeting CAL 117 flammability standards and BIFMA performance criteria for intensive daily cycles. The category serves workplaces, lodging properties, medical facilities, and learning environments where product lifespan, warranty terms, and compliance documentation drive procurement decisions. Seating products dominate volume flows across the sector, while healthcare-grade upholstery commands disproportionate margin pools due to antimicrobial performance requirements and stringent cleanability protocols. Wood and metal material segments retain the largest installed bases, though plastic formulations are displacing traditional substrates in high-traffic education settings where cost per seat drives specification.
The US market operates under overlapping federal and state regulatory frameworks, with the EPA regulating formaldehyde emissions in composite wood products through TSCA Title VI and OSHA establishing workplace ergonomics guidance that shapes task seating design parameters. California's Air Resources Board maintains the nation's most restrictive volatile organic compound limits, effectively setting the compliance ceiling for national product lines. Stakeholders must monitor evolving procurement standards from the General Services Administration and healthcare systems' infection-control committees, as these buyer specifications increasingly override manufacturer-led product development priorities.
Market Dynamics
Corporate workplace densification is compressing square footage per employee while elevating performance requirements for multi-functional furniture systems. This structural tension between space efficiency and ergonomic compliance is forcing specification-grade manufacturers to engineer products that serve three or more use modes within single footprints.
Growth Catalysts
- California Title 24 energy codes:Stringent daylighting and plug-load mandates are accelerating demand for integrated furniture-embedded power systems in commercial interiors across the state.
- Texas metropolitan construction corridors:Elevated commercial permitting in Dallas-Fort Worth, Houston, and Austin is concentrating procurement volumes for hospitality and healthcare furnishings.
- Antimicrobial upholstery specifications:Healthcare infection-control committees are mandating cleanable surface technologies that exceed CAL 117 standards, creating premium tier demand.
Market Restraints
- Domestic hardwood supply concentration:Appalachian and Pacific Northwest timber sourcing faces mill capacity constraints and freight cost volatility that compress margin on solid wood casegoods.
- OSHA workplace ergonomics guidance:Evolving task seating parameters require continuous design recertification, extending product development cycles and raising compliance overhead.
- Steel and aluminum input cost exposure:Frame and base metal pricing tied to commodity markets creates margin unpredictability for systems furniture manufacturers.
Strategic Opportunities
- Biophilic design integration:Living wall systems and organic material palettes are penetrating corporate wellness programs in Pacific Coast markets seeking WELL Building certification.
- Modular healthcare patient room systems:Reconfigurable headwall and casework platforms address surge capacity needs in acute care facilities across the Southeast.
- Lease-to-own financing channels:Furniture-as-a-service models are emerging in technology sector headquarters seeking to convert capex to opex for rapid scaling.
Industry Challenges
- BIFMA performance testing bottlenecks:Third-party laboratory capacity constraints are extending certification timelines for new product introductions by four to eight weeks.
- Legacy ERP integration with configurators:Made-to-order manufacturing systems require expensive middleware development to connect web-based specification tools with production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Contract Furniture and Furnishing Market |
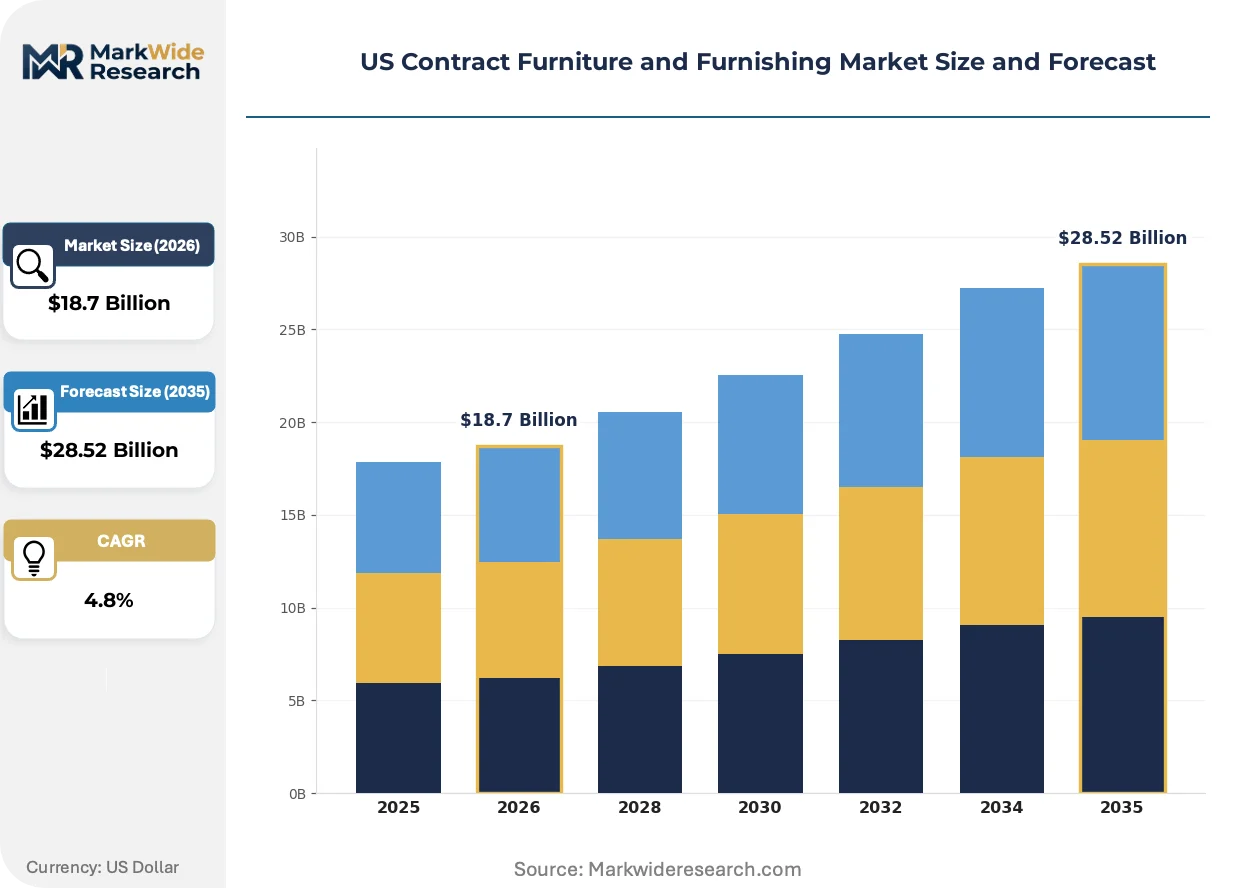
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Desks, Cabinets End User: Offices, Hospitality, Healthcare, Education Material: Wood, Metal, Plastic, Upholstery Style: Traditional, Modern, Minimalist, Industrial |
| Companies Covered | Bryan Ashley, Bernhardt Hospitality, Steelcase Inc, Knoll, Haworth, HNI Corporation, CF Kent, SitOnIt Seating, Kimball Hospitality, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Contract Furniture and Furnishing Market Evolving Landscape
Embedded sensor networks and adaptive material science are transforming static furniture into responsive environmental infrastructure. This shift from passive objects to active workplace systems is redefining competitive differentiation beyond traditional aesthetics and durability metrics.
Power-over-Ethernet (PoE) lighting and charging infrastructure is converging with height-adjustable workstation frames to create unified building systems that reduce electrical rough-in costs. Corporate real estate teams in Class A office towers are specifying these integrated platforms to accelerate tenant improvement timelines. The technology is converging with open-plan furniture layouts to eliminate the traditional separation between architectural and furniture specification.
EPA TSCA Title VI formaldehyde emission standards are tightening composite wood product sourcing requirements, effectively disqualifying certain overseas panel suppliers from federal and healthcare procurement channels. Manufacturers with captive North American particleboard and MDF supply chains are capturing specification share in GSA-scheduled projects. California Air Resources Board VOC limits are cascading into national product lines as de facto compliance ceilings.
Building owners are unbundling furniture procurement from general contractor packages to engage directly with specification houses for warranty and lifecycle accountability. This disintermediation is compressing traditional dealer networks while elevating manufacturer-direct specification support capabilities. Healthcare systems in the Midwest are pioneering this model to secure infection-control documentation and extended service agreements.
US Contract Furniture and Furnishing Market Segmentation
Procurement patterns in the US contract furniture sector diverge sharply across end-use environments, with healthcare infection-control mandates and corporate densification requirements creating incompatible specification pathways. Manufacturers must engineer distinct product architectures for each vertical rather than adapting universal platforms.
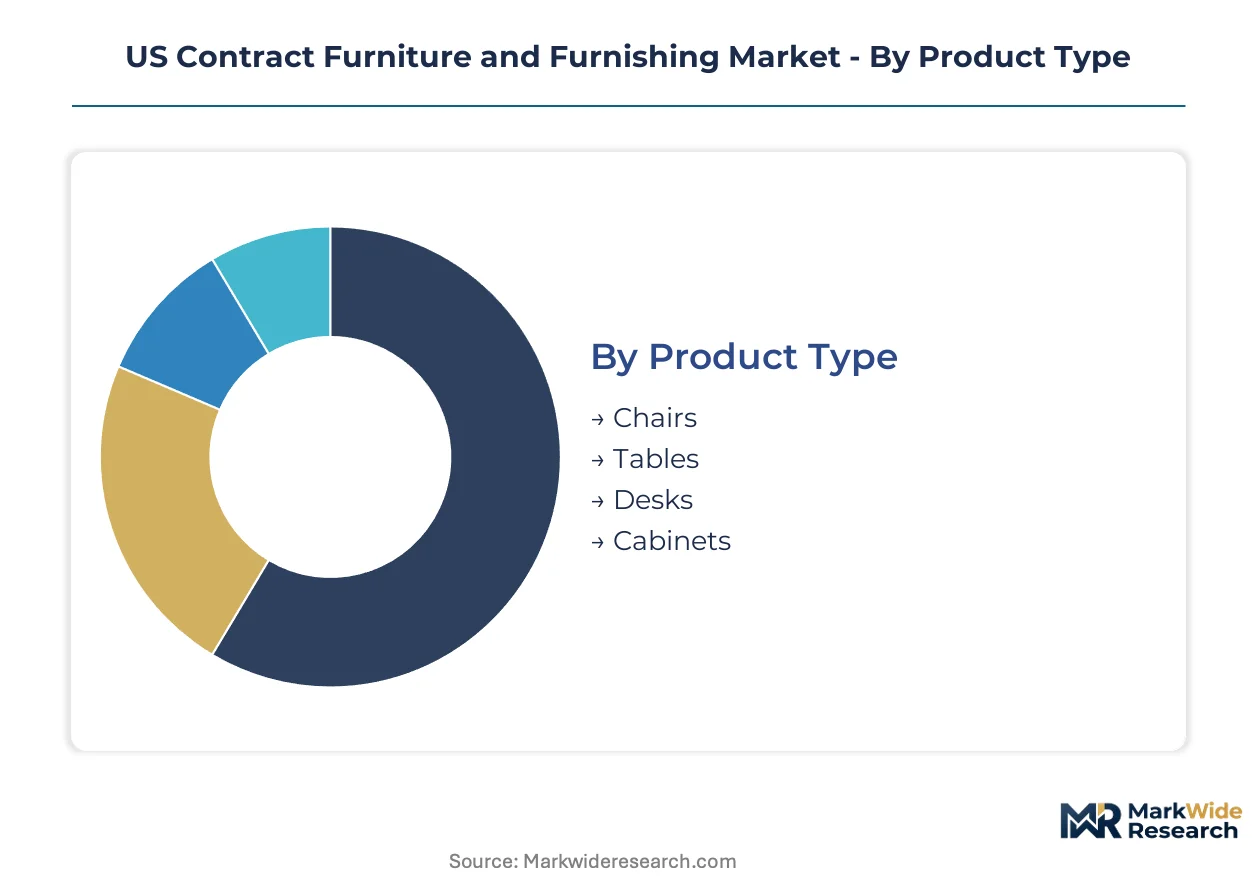
Product Type:
Buyers in this category differentiate primarily by duty-cycle intensity and reconfiguration frequency, with task seating demanding the highest engineering investment per unit.
- Chairs:Ergonomic task seating with adjustable lumbar support and pneumatic height mechanisms dominates corporate procurement in Texas metropolitan corridors where workplace densification elevates performance requirements. OSHA workplace ergonomics guidance shapes design parameters, forcing continuous recertification that extends development cycles.
- Tables:Conference and training tables with integrated power and data infrastructure are accelerating in California commercial interiors under Title 24 energy codes mandating daylighting and plug-load efficiency. Steel and aluminum frame pricing volatility compresses margin predictability for systems furniture manufacturers.
- Desks:Height-adjustable workstations with embedded PoE charging systems serve multi-functional use modes within compressed square footage per employee.
- Cabinets:Lockable storage with BIFMA-tested hardware cycles supports document retention requirements in federal and healthcare procurement channels.
Volume sits with Chairs; growth tilts toward Tables.
End User:
Compliance documentation and warranty accountability vary dramatically across these verticals, with healthcare and federal procurement demanding the most extensive certification packages.
- Offices:Corporate workplace densification compresses square footage per employee while elevating multi-functional requirements for furniture systems. Texas metropolitan construction corridors concentrate procurement volumes for large-scale rollouts.
- Hospitality:Boutique hotel chains in California and Texas specify specialized woodworking capabilities with extended lifecycle warranties. Domestic hardwood supply constraints in Appalachian and Pacific Northwest sourcing compress margin on solid wood casegoods.
- Healthcare:Infection-control committees mandate antimicrobial upholstery technologies exceeding CAL 117 flammability standards, creating premium tier demand for cleanable surface specifications.
- Education:High-traffic institutional settings prioritize cost-per-seat metrics, with plastic formulations displacing traditional substrates in K-12 and university procurement.
Procurement volume clusters in Offices; Healthcare claims the steepest expansion trajectory.
Material:
Margin structure and supply chain risk exposure separate these substrates, with captive North American supply chains capturing specification share in GSA-scheduled projects.
- Wood:Composite wood products face EPA TSCA Title VI formaldehyde emission standards that disqualify certain overseas panel suppliers from federal and healthcare channels. Manufacturers with captive North American particleboard and MDF supply chains secure competitive positioning.
- Metal:Frame and base construction for systems furniture ties pricing to commodity steel and aluminum markets, creating margin unpredictability that complicates long-term project bidding.
- Plastic:High-impact formulations serve education and high-traffic environments where replacement cost drives specification over aesthetic longevity.
- Upholstery:Healthcare-grade fabrics with antimicrobial performance and stringent cleanability protocols command disproportionate margin pools relative to volume.
Installed base concentration favors Wood; Upholstery gains share fastest on healthcare demand.
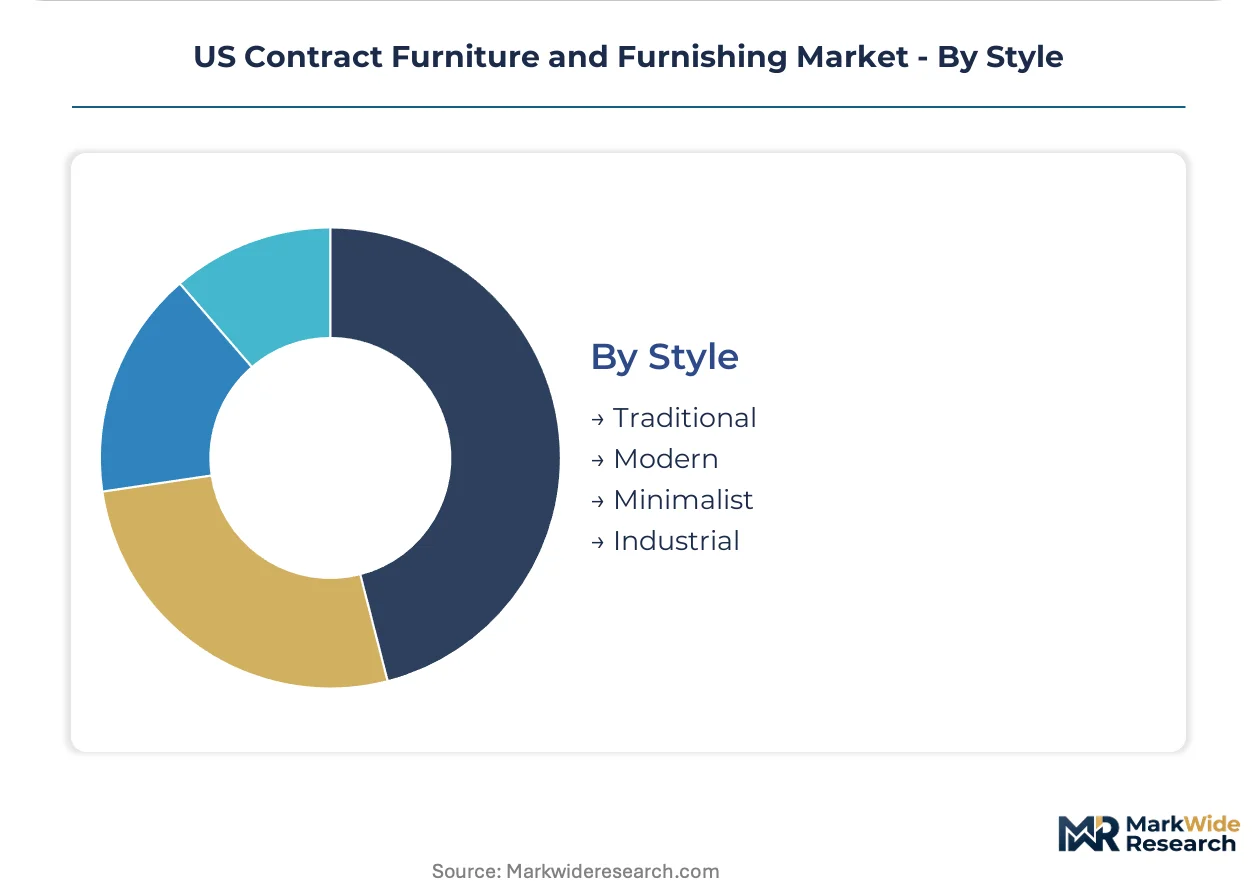
Style:
Aesthetic differentiation maps to building certification programs and regional design preferences, with biophilic and wellness-oriented specifications penetrating Pacific Coast markets.
- Traditional:Classic wood profiles with ornate detailing serve heritage hospitality properties and executive office suites in established East Coast financial centers.
- Modern:Clean lines and neutral palettes dominate Class A office towers seeking WELL Building certification in California and Pacific Northwest markets.
- Minimalist:Reduced material volumes and concealed hardware align with sustainability scoring systems and circular economy procurement criteria.
- Industrial:Exposed metal frames and reclaimed wood aesthetics anchor co-working spaces and creative sector headquarters in Austin and Dallas-Fort Worth corridors.
Modern styling captures current specification volume; Industrial climbs fastest on Texas construction activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metropolitan corridor anchors procurement volume for hospitality and healthcare furnishings, with commercial construction permits sustaining elevated activity across Texas metropolitan construction corridors.
Texas
Hospitality and healthcare furnishings concentrate procurement volumes in Dallas-Fort Worth, Houston, and Austin corridors where commercial permitting remains elevated. State energy efficiency standards complement federal procurement guidelines for federal and healthcare channels. Industrial-style furniture with exposed metal frames dominates co-working spaces and creative sector headquarters in Austin and Dallas-Fort Worth corridors.
California
Title 24 energy codes mandate daylighting and plug-load efficiency, accelerating demand for integrated furniture-embedded power systems in commercial interiors. The California Air Resources Board maintains the nation's most restrictive volatile organic compound limits, effectively setting compliance ceilings for national product lines. Biophilic design and wellness-oriented specifications penetrate corporate wellness programs in Pacific Coast markets seeking WELL Building certification.
Pacific Northwest
Appalachian and Pacific Northwest timber sourcing faces mill capacity constraints and freight cost volatility that compress margin on solid wood casegoods. EPA TSCA Title VI formaldehyde emission standards tighten composite wood product sourcing requirements for federal procurement. Modern styling with clean lines and neutral palettes dominates Class A office towers in Seattle and Portland markets.
Southeast
Healthcare infection-control committees mandate antimicrobial upholstery technologies exceeding CAL 117 flammability standards, creating premium tier demand. Modular healthcare patient room systems address surge capacity needs in acute care facilities across Georgia, Florida, and the Carolinas. Traditional wood profiles with ornate detailing serve heritage hospitality properties in established East Coast financial centers extending into the Southeast.
Midwest
Corporate workplace densification compresses square footage per employee while elevating multi-functional requirements for furniture systems. OSHA workplace ergonomics guidance shapes task seating design parameters, forcing continuous recertification that extends development cycles. Healthcare systems in Illinois, Michigan, and Ohio pioneer direct manufacturer engagement to secure infection-control documentation and extended service agreements.
US Contract Furniture and Furnishing Market Competitive Landscape
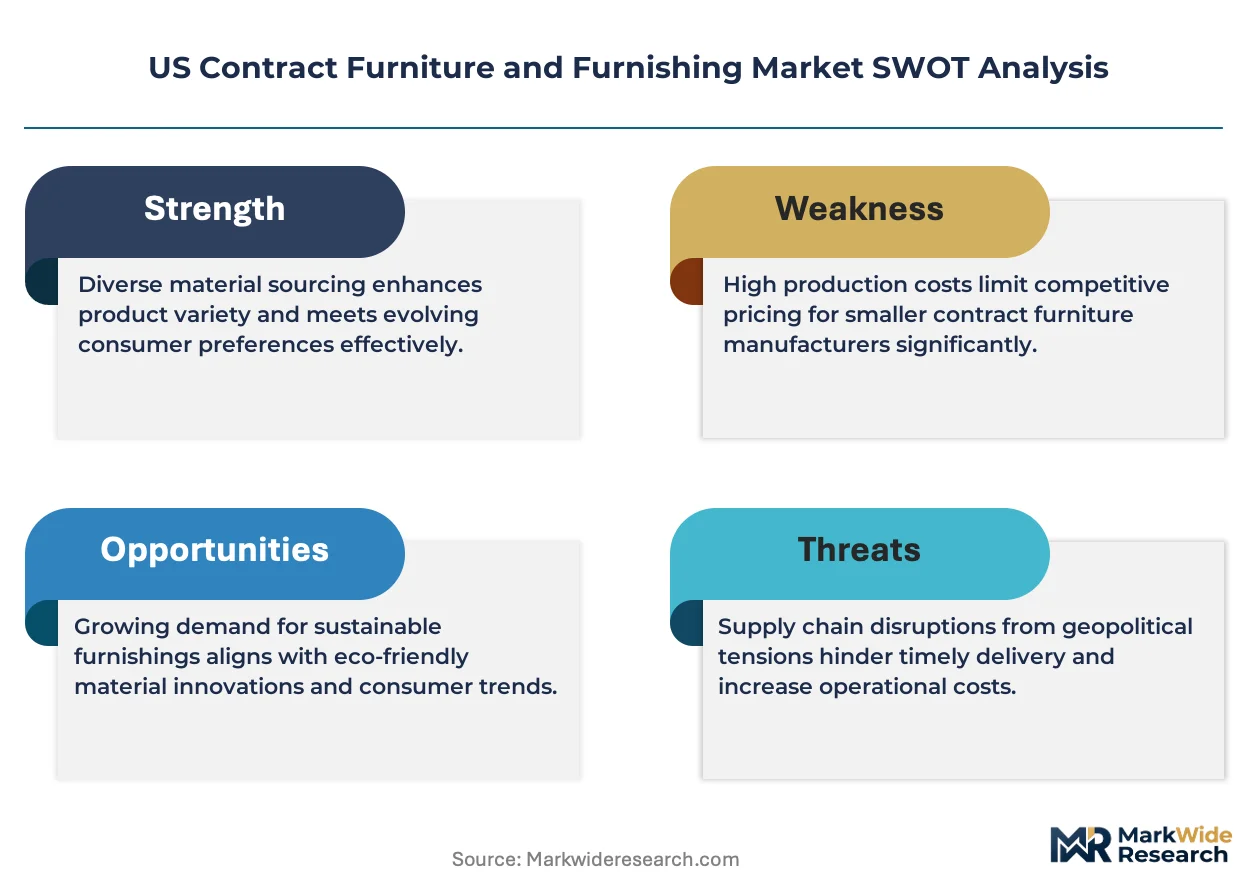
Capital-heavy producers compete with asset-light designers across a market structure that fragments between domestic manufacturing footprints and specification-driven brand houses. The vendor base separates into three strategic archetypes: integrated manufacturers controlling captive supply chains, hospitality specialists commanding woodworking capabilities, and systems furniture houses competing on configurable platforms. Dominant competitive moves include geographic expansion into Texas metropolitan corridors and portfolio diversification toward healthcare-grade upholstery specifications.
Within the integrated manufacturing tier, Steelcase Inc and HNI Corporation anchor positions through domestic production control over lead times for large-scale office rollouts. Bernhardt Hospitality exemplifies the hospitality specialist archetype through specialized woodworking capabilities serving boutique hotel chains. Haworth occupies a position on the systems furniture vector, competing on configurable platforms that integrate power and data infrastructure.
| Leading Market Players |
|---|
| Bryan Ashley |
| Bernhardt Hospitality |
| Steelcase Inc |
| Knoll |
| Haworth |
| HNI Corporation |
| CF Kent |
| SitOnIt Seating |
| Kimball Hospitality |
| Others |
Value Network & Pricing Analysis
Power-over-Ethernet integration into height-adjustable workstation frames simultaneously compresses electrical rough-in costs and concentrates specification power among manufacturers with captive North American supply chains. This technology shift rewards domestic producers able to certify embedded power systems under California Title 24 while disqualifying overseas competitors from federal and healthcare procurement channels.
Pricing Analysis
Warranty-term anchoring dominates value-based pricing in healthcare and federal procurement, where infection-control documentation and extended service agreements command substantial premiums over commodity-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-grade antimicrobial upholstery from hospitality woodworking and education-sector plastic seating. Cost compression in solid wood casegoods intensifies because Appalachian and Pacific Northwest timber sourcing faces mill capacity constraints. Education buyers exhibit highest price sensitivity due to cost-per-seat procurement mandates, while healthcare systems prioritize lifecycle accountability over unit economics.
Supply Chain Analysis
Domestic-content mandates under EPA TSCA Title VI and GSA scheduling requirements are reshaping composite wood product sourcing toward captive North American particleboard and MDF supply chains. Manufacturing concentration centers on the United States, with secondary component sourcing from Canada and Mexico under USMCA provisions. Steel and aluminum frame materials, textile substrates, and electronic control systems for height-adjustable mechanisms constitute critical input dependencies. Tariff exposure on Chinese-made hardware and motor components creates vulnerability for systems furniture producers. Distribution runs through manufacturer-direct specification channels and regional dealer networks serving metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Air Resources Board VOC limits and EPA TSCA Title VI formaldehyde standards erect compliance moats that protect incumbent manufacturers with certified North American supply chains while raising capital barriers for prospective entrants.
For Market Incumbents: Lock in specification relationships with healthcare infection-control committees and federal procurement officers by investing in antimicrobial upholstery R&D and extended warranty documentation. Threats from commodity-grade Asian producers intensify as education-sector plastic seating displaces traditional substrates. Priority levers include backward integration into captive composite wood manufacturing and direct engagement with Texas metropolitan construction corridors. For New Entrants and Emerging Players: Embedded sensor networks for occupancy tracking and environmental monitoring offer technology-first entry points into corporate wellness programs seeking WELL Building certification. White-space targets concentrate in modular healthcare patient room systems for Southeast acute care facilities and furniture-as-a-service financing for technology sector headquarters. Go-to-market execution should prioritize pilot deployments with mid-market co-working operators in Austin and Dallas-Fort Worth. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated manufacturers seeking hospitality woodworking capabilities or healthcare-grade upholstery expertise. Long-term viability favors specialists with demonstrated compliance documentation and regional specification relationships. The signal to watch is acceleration of direct manufacturer engagement by healthcare systems disintermediating traditional dealer networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Wood Manufacturing | EPA TSCA Title VI compliance secures federal and healthcare procurement access against overseas competitors. |
| Healthcare-Grade Upholstery Certification Investment | Antimicrobial performance documentation captures premium tier demand from infection-control committees. |
| Direct Manufacturer Specification Channel Development | Bypassing dealer networks aligns with Midwest healthcare systems' lifecycle accountability requirements. |
| Power-over-Ethernet Platform Integration | California Title 24 compliance accelerates tenant improvement timelines in Class A office towers. |
| Modular Healthcare Patient Room System Launch | Reconfigurable headwall platforms address surge capacity needs across Southeast acute care facilities. |
Research Methodology
Document review covered BIFMA performance testing protocols, EPA TSCA Title VI compliance documentation, GSA procurement schedules, and California Air Resources Board regulatory filings, complemented by interviews with specification-grade furniture manufacturers, healthcare infection-control committee members, federal procurement officers, and commercial real estate development executives. Secondary validation drew from commercial construction permit databases, hospitality industry procurement surveys, and OSHA workplace ergonomics guidance documents. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, material, and style segmentation dimensions.
Market size and growth trajectory outputs reflect econometric modeling across the projection horizon, with segment-level CAGRs derived from regression analysis against construction permit volumes, employment density trends, and regulatory implementation timelines. Segmentation dimensions modeled include product duty-cycle intensity, end-use compliance documentation requirements, material substrate supply chain configuration, and aesthetic specification aligned with building certification programs. Industry-specific forecast inputs incorporated healthcare infection-control committee mandate adoption curves and corporate workplace densification square-footage compression rates.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on commercial construction, abrupt shifts in federal procurement policy, and technological disruption from fully integrated smart building systems that eliminate discrete furniture specification. Forecasts reflect documented assumptions about regulatory enforcement continuity and material cost volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Indonesia Home Furniture Market
Furniture
US Secondary Wood Products Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
India Home Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Global Folding Furniture Market
Furniture
HORECA Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
Europe Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Europe Home Furniture Market
Furniture
Upholstered Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Canada Secondary Wood Products Market