
 China Home Furniture Market | 2026-2036
China Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Furniture Market Analysis
Subscription-based furniture leasing and software-defined customization is shifting how Chinese manufacturers monetize their product lines. OPPEIN Home Group leverages its integrated design-to-installation platform to dominate whole-home solutions. Kuka Home sustains leadership in upholstered seating through advanced automation at its Hangzhou facilities. Man Wah Holdings anchors the motion-recliner segment with proprietary mechanism engineering.
China home furniture comprises movable functional objects for interior spaces, typically constructed from engineered wood panels with formaldehyde emission ratings under GB/T 39600-2021 standards, finished with lacquers, fabrics, or metals to serve residential and commercial dwelling purposes. Sofas and beds capture the largest revenue pools as replacement cycles shorten in tier-one cities. Wood-based materials retain volume leadership while metal and glass combinations gain share in minimalist urban interiors. Online distribution channels are displacing traditional retail stores for standardized items, though retail stores persist for experiential purchases of premium bedroom and living room sets.
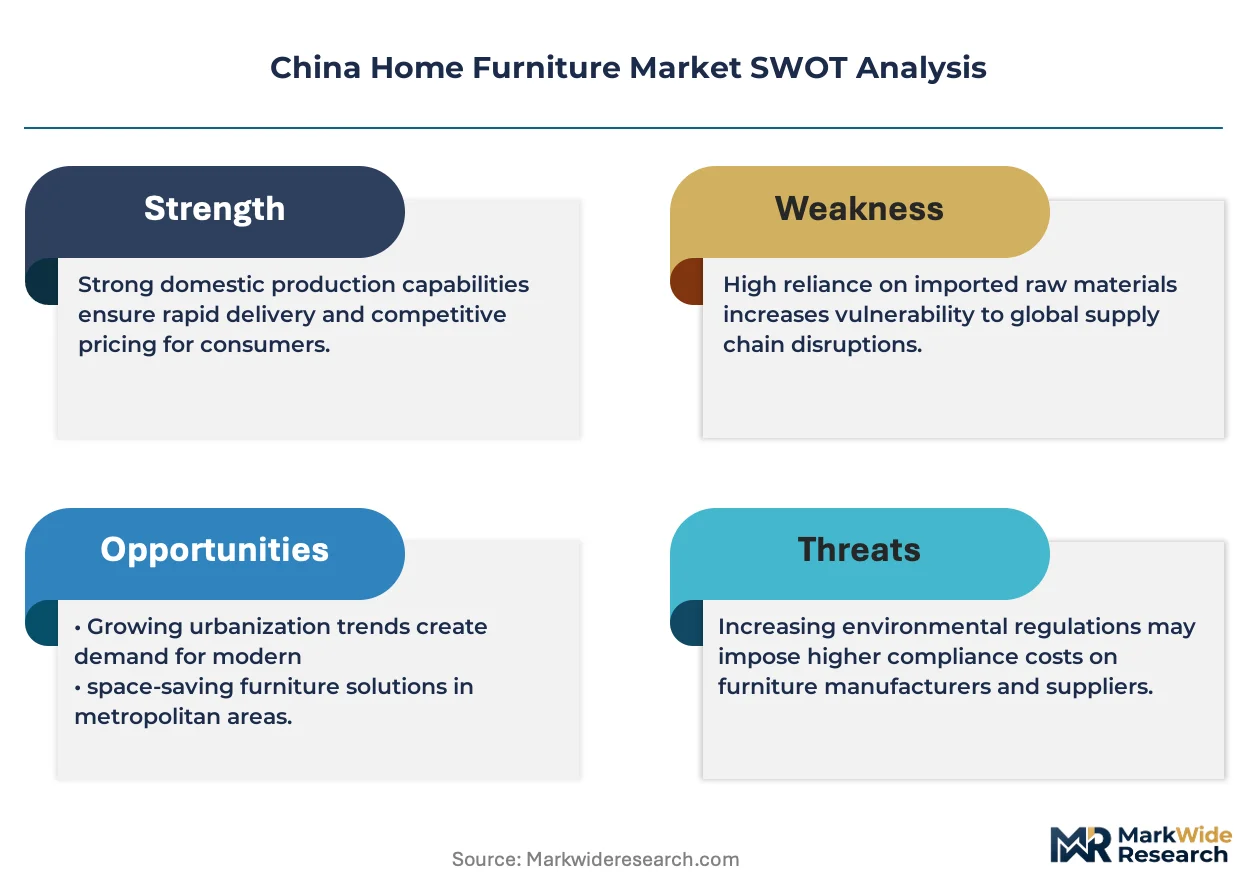
GB standards administered by SAMR enforce strict volatile organic compound limits on panel furniture, compelling manufacturers to reformulate adhesives and coatings. NMPA-aligned product safety inspections for children's furniture create compliance barriers for unqualified producers. China's dual carbon goals under MEE pressure energy-intensive lacquering and drying operations toward electrification. Stakeholders must monitor evolving provincial enforcement of green building codes that increasingly specify certified low-emission furnishings for new residential developments.
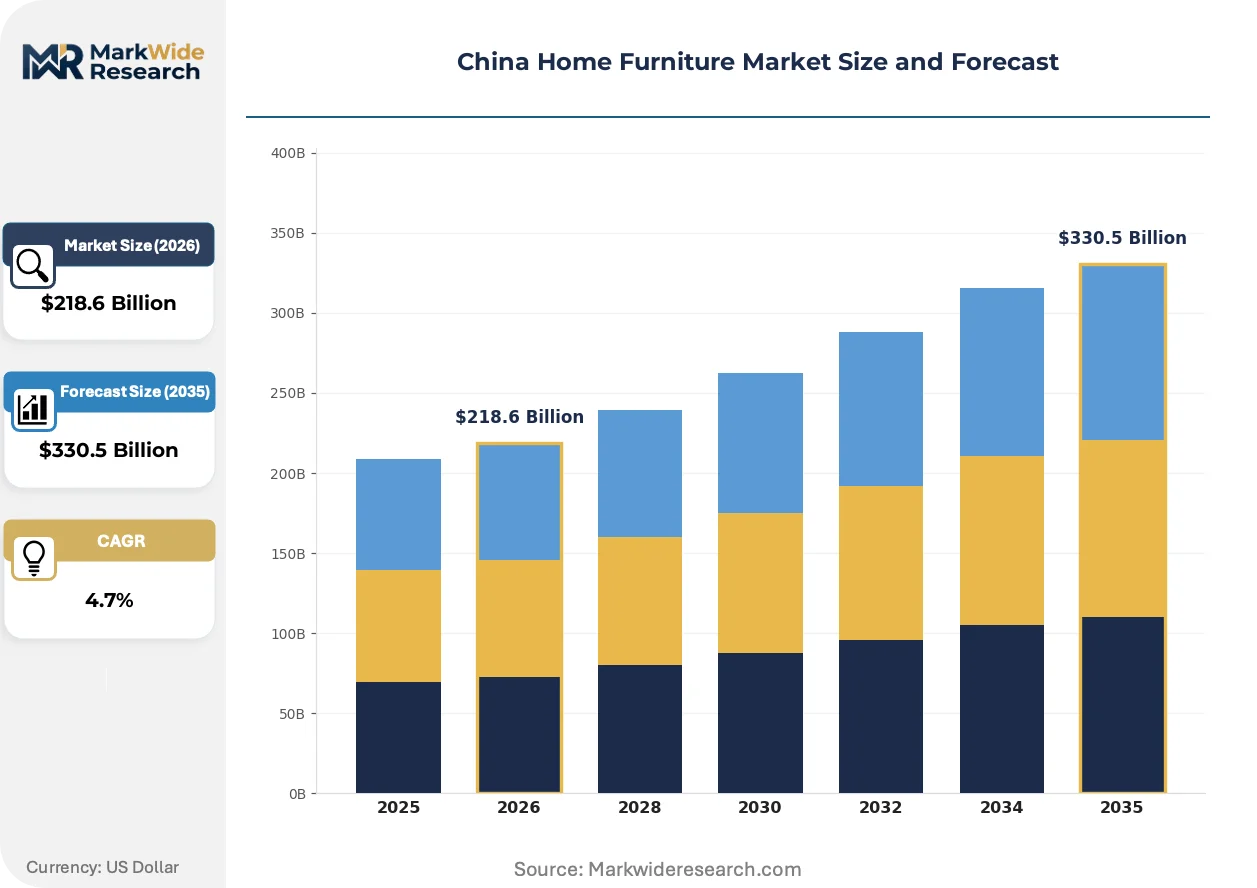
Market Dynamics
MIIT smart manufacturing directives are compressing production timelines across China's furniture sector while SAMR's GB/T 39600-2021 formaldehyde standards force wholesale adhesive reformulation. These dual pressures are restructuring competitive advantage toward integrated digital-physical platforms.
Growth Catalysts
- MIIT Industrial Internet:Smart factory mandates accelerate robotic deployment in panel cutting and edge-banding operations. Manufacturers achieving MES integration capture preferential placement in state procurement catalogs.
- Yangtze River Delta cluster density:Proximity of engineered wood suppliers, hardware manufacturers, and logistics hubs within 200km of Shanghai reduces inbound freight costs. This geographic concentration enables just-in-sequence assembly for whole-home solution providers.
- Urban residential complex standardization:Prefabricated construction methods in tier-one cities create bundled furniture procurement opportunities. Developers specify certified low-emission furnishings to meet green building code requirements.
Market Restraints
- Adhesive input volatility:MDI and urea-formaldehyde resin prices fluctuate with petrochemical feedstock costs. Manufacturers lack pricing power to pass through sustained increases to cost-sensitive apartment furnishers.
- Hebei-Guangdong supply concentration:Engineered wood panel production clusters in these provinces create geographic vulnerability. Flood or power rationing events disrupt national supply with limited alternative sourcing.
- GB standard compliance friction:SAMR's volatile organic compound testing protocols require third-party certification cycles exceeding 90 days. Small workshops face exclusion from formal retail channels.
Strategic Opportunities
- Subscription-based furniture leasing:Young professionals in Shenzhen and Chengdu reject ownership for flexibility. Leasing platforms capture recurring revenue while retaining asset value for secondary markets.
- Software-defined customization:Parametric design tools allow consumers to modify dimensions and finishes without engineering overhead. This technology convergence reduces SKU proliferation while preserving perceived personalization.
- MEE dual carbon electrification incentives:Lacquering and drying operations converting to electric heat pumps receive provincial subsidies. Early adopters secure carbon credit reserves for future compliance trading.
Industry Challenges
- Industrial software integration complexity:Legacy ERP systems in family-owned workshops resist MES layer implementation. Data silos between design software and production scheduling create order fulfillment errors.
- Skilled CNC programming scarcity:Complex five-axis routing for curved solid wood components requires operators with combined mechanical and software competencies. Vocational pipelines produce insufficient qualified technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Furniture Market |
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $330.5 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Tables, Chairs Material: Wood, Metal, Glass, Fabric End User: Residential, Offices, Hospitality, Public Spaces Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | OPPEIN Home Group, Kuka Home, Man Wah Holdings, Suofeiya Home, QuanU Furniture, Red Apple Furniture, Sleemon Holdings, Markor International, Shandong Huid Intelligent Home, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Furniture Market Emerging Trajectories
Digital thread technologies are collapsing the traditional sequence of design, production, and installation into concurrent workflows. Manufacturers are racing to deploy connected platforms before competitors lock in platform economics.
Parametric furniture design software is modularizing how Chinese manufacturers configure product families. Urban apartment developers in Hangzhou and Nanjing specify platform-based systems where wall units, storage, and seating reconfigure without structural modification. This technology is modularizing the traditional SKU-based inventory model into component libraries that reduce working capital requirements by half.
SAMR's expanded GB standards for children's furniture safety are forcing comprehensive design reviews. Manufacturers must now submit mechanism testing data and material traceability documentation before market release. The children's bedroom segment faces the steepest compliance burden, with unqualified producers exiting rather than absorbing certification costs.
Young household formation in tier-one cities is compressing replacement cycles for sofas and mattresses. Online channels capture standardized orders while experiential retail persists for premium bedroom sets requiring tactile evaluation. This channel bifurcation is most visible in Shanghai, where showrooms function as design consultation hubs rather than inventory points.
China Home Furniture Market Segmentation
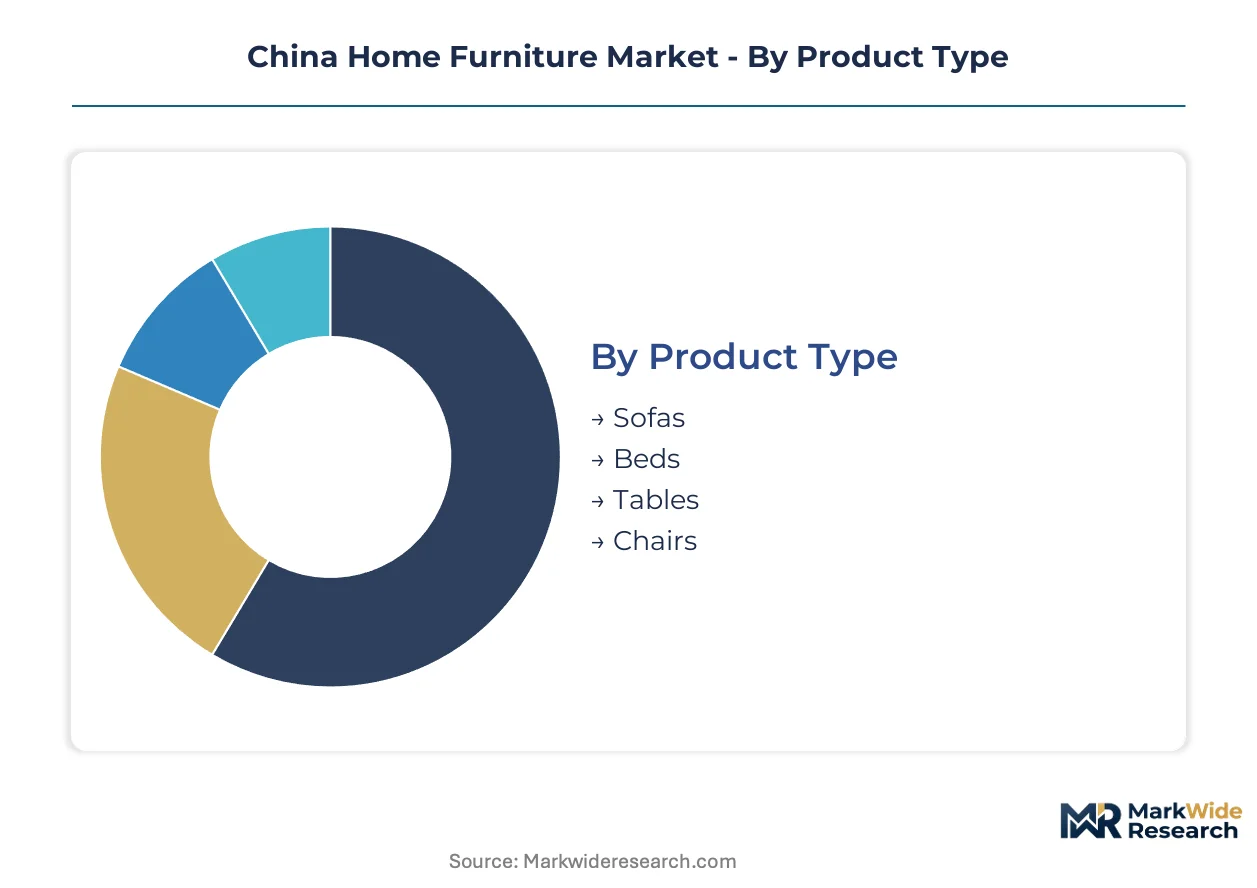
China's home furniture market fragments across four critical dimensions that determine procurement patterns, margin structures, and compliance exposure. Each category reveals distinct buyer priorities shaped by MIIT manufacturing mandates, SAMR emission standards, and urban residential development cycles.
Product Type:
Replacement frequency and space utilization requirements separate buyers across living room, bedroom, and dining applications.
- Sofas:Upholstered seating systems with fabric or leather coverings over engineered wood or metal frames, rated for residential VOC compliance under GB/T 39600-2021. Demand clusters in tier-one city apartment renovations where young professionals replace units every 5-7 years versus traditional 10-15 year cycles.
- Beds:Platform and storage-integrated designs dominate, combining panel construction with certified low-emission adhesives. Prefabricated residential complexes in the Yangtze River Delta specify standardized bedroom sets to accelerate unit turnover.
- Tables:Dining and occasional tables span solid wood premium tiers to laminate economy options. Commercial co-working spaces in Shenzhen drive demand for modular configurations.
- Chairs:Task seating for home offices surged post-pandemic; ergonomic certification now filters procurement in white-collar districts.
Volume sits with sofas; growth tilts toward beds as green building codes harden furnishing specifications.
Material:
Compliance cost exposure and finish durability differentiate procurement decisions across substrate categories.
- Wood:Engineered panels with E0 or ENF formaldehyde ratings retain dominant share. Hebei and Guangdong production clusters supply panel stock to Yangtze River Delta assemblers, though SAMR testing protocols extend certification timelines.
- Metal:Powder-coated steel and aluminum framing gains traction in minimalist urban interiors. Shanghai developers specify metal-glass combinations for premium rental inventory.
- Glass:Tempered glass tabletops and shelving components serve aesthetic-driven segments. Safety testing under NMPA-aligned protocols adds compliance layers for children's furniture applications.
- Fabric:Upholstery textiles span synthetic blends to natural fibers with flame-retardant treatments. Leasing platforms in Chengdu prioritize stain-resistant synthetics for asset longevity.
Wood commands current volume; metal and glass combinations are expanding most quickly among tier-one renovators.
End User:
Procurement scale and specification authority separate fragmented residential buyers from institutional purchasers with technical staffs.
- Residential:Individual households and family buyers purchasing for owned or rental apartments. Online channels capture standardized orders; retail showrooms persist for tactile evaluation of premium bedroom sets.
- Offices:Corporate procurement of workstations and meeting furniture. MEE dual carbon goals pressure facility managers toward certified low-emission panel specifications.
- Hospitality:Hotel and serviced apartment operators sourcing durable, high-turnover furnishings. Bulk procurement contracts favor manufacturers with MES-integrated production for delivery reliability.
- Public Spaces:Government and institutional buyers with state procurement catalog requirements. MIIT smart manufacturing certification filters vendor eligibility.
Residential transactions generate highest unit volume; hospitality contracts deliver steadiest margin profiles.
Distribution Channel:
Touchpoint requirements and order customization levels determine channel selection across buyer segments.
- Online:E-commerce platforms and brand direct-to-consumer sites. Standardized sofas and storage units move through Tmall and JD.com with 7-day return policies.
- Retail Stores:Physical showrooms with design consultation services. Whole-home solution providers like OPPEIN leverage integrated platforms to close complex bedroom and living room configurations.
- Wholesalers:Regional distributors serving secondary cities and furniture retailers. Inventory financing terms determine competitive positioning in price-sensitive interior provinces.
- Direct Sales:Manufacturer-owned channels for project-based institutional contracts. Urban residential developers in Hangzhou and Nanjing negotiate directly for bundled furnishing packages.
Online channels capture volume leadership; retail stores retain margin advantage through design services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's furniture production concentrates in coastal manufacturing belts while consumption tilts toward interior urban centers. This spatial mismatch shapes logistics costs and regional competitive dynamics across the market.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou anchor China's highest-value furniture demand. MIIT smart manufacturing directives accelerate robotic deployment in Jiangsu panel-cutting facilities. The cluster integrates engineered wood suppliers, hardware manufacturers, and logistics hubs within 200km of Shanghai port.
Pearl River Delta
Shenzhen and Guangzhou drive premium upholstery demand from young professionals in rental apartments. SAMR's GB/T 39600-2021 formaldehyde standards compel adhesive reformulation across Guangdong workshops. Foshan's Shunde district hosts dense concentrations of metal-framing and glass-component suppliers.
Beijing-Tianjin-Hebei
Capital region demand centers on whole-home solutions for prefabricated residential complexes. MEE dual carbon goals pressure Hebei lacquering operations toward electrification. Langfang and Bazhou furniture industrial parks supply standardized bedroom sets to state procurement catalogs.
Sichuan-Chongqing
Chengdu's leasing platforms capture recurring revenue from flexibility-seeking young households. Provincial green building codes increasingly specify certified low-emission furnishings for new developments. Chongqing's riverside logistics hubs reduce inland freight costs for Yangtze River Delta assemblers.
Shandong Peninsula
Qingdao and Yantai manufacturers serve export-oriented upholstery demand alongside domestic coastal markets. Shandong Huid Intelligent Home exemplifies automation investment in the region's panel furniture sector. Jinan vocational institutes address CNC programming scarcity for curved solid wood routing.
China Home Furniture Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across China's furniture sector. The market structures into three tiers: integrated whole-home solution providers, specialized seating manufacturers, and regional panel fabricators. Strategic archetypes include MES-integrated scale players, subscription-leasing platform operators, and component-library specialists. Competitive intensity centers on backward integration into engineered wood supply and parametric design software deployment.
Among integrated solution providers, OPPEIN Home Group and Suofeiya Home occupy positions exemplifying design-to-installation platform economics. Kuka Home represents the specialized seating archetype with Hangzhou-based automation heritage. Man Wah Holdings anchors the motion-recliner segment through proprietary mechanism engineering. These three companies illustrate divergent paths to margin defense: platform breadth, manufacturing depth, and technical specialization respectively.
| Leading Market Players |
|---|
| OPPEIN Home Group |
| Kuka Home |
| Man Wah Holdings |
| Suofeiya Home |
| QuanU Furniture |
| Red Apple Furniture |
| Sleemon Holdings |
| Markor International |
| Shandong Huid Intelligent Home |
| Others |
Supply Flow & Price Mechanics
Urban residential developers in the Yangtze River Delta anchor procurement volume and impose project-based pricing with strict emission certification requirements. SAMR's GB/T 39600-2021 testing protocols extend vendor qualification cycles, compressing margins for non-compliant workshops while rewarding certified suppliers with pricing power.
Pricing Analysis
Cost compression in economy-tier panel furniture accelerates as Hebei and Guangdong producers flood secondary markets with uncertified inventory. Three-tier pricing structure across premium, standard, and economy levels separates OPPEIN's whole-home bundles from Kuka's automated seating and regional fabricators. Price differentiation hinges on GB/T 39600-2021 certification grade and MES integration depth. Young professionals in tier-one cities show lowest price sensitivity for subscription leasing, while interior province wholesalers face relentless margin pressure from adhesive cost volatility.
Supply Chain Analysis
Single-source vulnerability sits with Hebei's engineered wood panel clusters, where flood and power rationing events disrupt national supply with limited alternative sourcing. Raw material dependencies center on MDI resins, urea-formaldehyde adhesives, and imported hardware mechanisms from Germany and Italy. Supply chain risk concentrates in regulatory restriction, as SAMR's volatile organic compound testing protocols extend certification timelines beyond 90 days. Distribution runs through direct sales channels for bundled residential projects, with online platforms capturing standardized sofa and storage unit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's home furniture market functions as a cost-of-compliance arena where SAMR's GB/T 39600-2021 formaldehyde standards erect barrier-to-entry moats favoring certified incumbents with testing infrastructure.
For Market Incumbents: Hedge against adhesive input volatility through backward integration into engineered wood supply or long-term resin offtake agreements with petrochemical suppliers. MIIT smart manufacturing mandates favor MES-integrated producers in state procurement catalogs, making legacy ERP migration the priority capability investment. Parametric design software deployment defends margin position against software-defined customization entrants. For New Entrants and Emerging Players: Leasing platform operators in Chengdu and Shenzhen represent the most penetrable channel partner type for asset-light entry. Subscription-based furniture models bypass capital-intensive manufacturing while capturing recurring revenue from flexibility-seeking young households. White-space targets include MEE-aligned electrification retrofits for lacquering operations and component-library supply to whole-home solution providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale panel fabricators in Shandong with automation heritage but insufficient certification infrastructure for GB standard compliance. Long-term viability rests on dual carbon alignment and provincial green building code enforcement trajectories. Watch SAMR's expanded children's furniture safety protocols as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MES-Integrated Production Scale-Up | MIIT smart manufacturing certification unlocks state procurement catalog placement. |
| Parametric Design Platform Launch | Software-defined customization reduces SKU proliferation while preserving personalization premiums. |
| Backward Integration into Panel Supply | Captive engineered wood production hedges Hebei-Guangdong geographic concentration risk. |
| Subscription Leasing Model Expansion | Recurring revenue platforms in Chengdu and Shenzhen retain asset value for secondary markets. |
| GB Standard Compliance Investment | SAMR certification infrastructure excludes unqualified competitors from formal retail channels. |
Methodological Framework
Independent corroboration across furniture manufacturer executives, urban residential developers, SAMR compliance officers, and logistics operators underwrites the qualitative findings. Primary interviews with design-to-installation platform managers and CNC programming vocational institutes combined with secondary validation from MIIT industrial policy filings, SAMR GB standard documentation, and Yangtze River Delta customs data. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period anchoring to historical MIIT smart manufacturing deployment phases and SAMR regulatory enforcement cycles structured the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-user category, and distribution channel complexity. CAGRs derived from trend-line extrapolation of replacement cycle compression in tier-one cities and green building code penetration rates. Industry-specific inputs incorporated MEE dual carbon electrification incentive trajectories and provincial enforcement variance.
Caveats apply where SAMR testing protocol revisions or MEE carbon target acceleration could materially shift the outlook. Forecasts reflect assumptions about continued urban residential complex standardization and adhesive cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
India Luxury Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
United States Home Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
North America Furniture Market
Furniture
North America School Furniture Market
Furniture
Metal Furniture Market
Furniture
Chaises Longue Market
Furniture
Spain Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Europe Sustainable Mattress Market
Furniture
Exam Tables Market
Furniture
Canada Home Furniture Market