
 HORECA Furniture Market | 2026-2036
HORECA Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
HORECA Furniture Market Foresight
Multi-source procurement among boutique hotel chains is repositioning how regional manufacturers compete for specification contracts. Andreu World leverages its Mediterranean manufacturing base to sustain lead times for European hospitality developers. Kimball Hospitality anchors its competitive stance through domestic upholstery capacity in North Carolina. Fritz Hansen competes on design heritage while extending its commercial footprint across Scandinavian hotel portfolios.
HORECA furniture encompasses commercial-grade seating, tables, and fixed installations engineered for intensive daily use in food service and lodging environments, typically meeting fire-retardant upholstery standards and moisture-resistant frame specifications to withstand cleaning protocols. The primary commercial purpose centers on balancing aesthetic differentiation with durability metrics that reduce total cost of ownership across high-turnover dining and guest room settings. Wood and upholstery materials command the dominant margin pools given their customization complexity and specification dependency among design-led hotel brands. Metal frames represent the fastest-growing material category as industrial design preferences penetrate mid-market restaurant chains across Europe and Asia.
The EU Green Deal and REACH chemical frameworks constrain foam and adhesive sourcing for European hospitality projects, while EPA formaldehyde emissions standards shape product qualification for US hotel development pipelines. California's TB 117-2013 flammability standard creates a de facto national benchmark that manufacturers must navigate for interstate hotel supply contracts. Stakeholders should monitor how extended producer responsibility frameworks in Germany and France will shift cost structures for furniture take-back and material recovery programs.
Market Dynamics
The EU Green Deal's cascading material mandates are forcing HORECA furniture suppliers to requalify entire product lines, compressing procurement timelines for European hospitality developers while creating specification bottlenecks for wood and upholstery sourcing.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany and France are mandating furniture take-back programs, creating service revenue streams for manufacturers with established recovery infrastructure.
- Mediterranean tourism renovation cycles:Coastal urban markets in Spain, Portugal, and Greece are replacing aging hospitality infrastructure, concentrating demand for moisture-resistant frame specifications.
- Industrial design penetration:Metal frames are displacing traditional materials across mid-market European and Asian restaurant chains, opening specification opportunities for welded-frame specialists.
Market Restraints
- REACH chemical constraints:ECHA restrictions on foam and adhesive formulations limit supplier pools for European hospitality projects, extending qualification timelines.
- Formaldehyde emission standards:EPA thresholds and California's TB 117-2013 create interstate compliance friction for US hotel supply contracts.
- Custom upholstery concentration:Boutique hotel chains' multi-source procurement strategies fragment order volumes, eroding economies of scale for regional manufacturers.
Strategic Opportunities
- Material recovery integration:EU circular economy directives reward closed-loop upholstery and wood recovery systems with preferential procurement scoring.
- Scandinavian design heritage leverage:Hotel portfolios across Denmark, Norway, and Sweden prioritize specification partners with documented Nordic manufacturing lineage.
- North Carolina domestic capacity:US developers are anchoring upholstery sourcing in states with established fire-retardant testing infrastructure to bypass import lead time volatility.
Industry Challenges
- Fire-retardant certification latency:California TB 117-2013 testing backlog delays product launches for interstate hotel contracts by four to six months.
- Moisture-resistant frame engineering:Mediterranean climate specifications require specialized joint sealing and hardware selection that extends R&D cycles.
- Multi-source coordination complexity:Boutique chains' distributed procurement teams create specification version control failures across United States, Germany, and Japan programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HORECA Furniture Market |
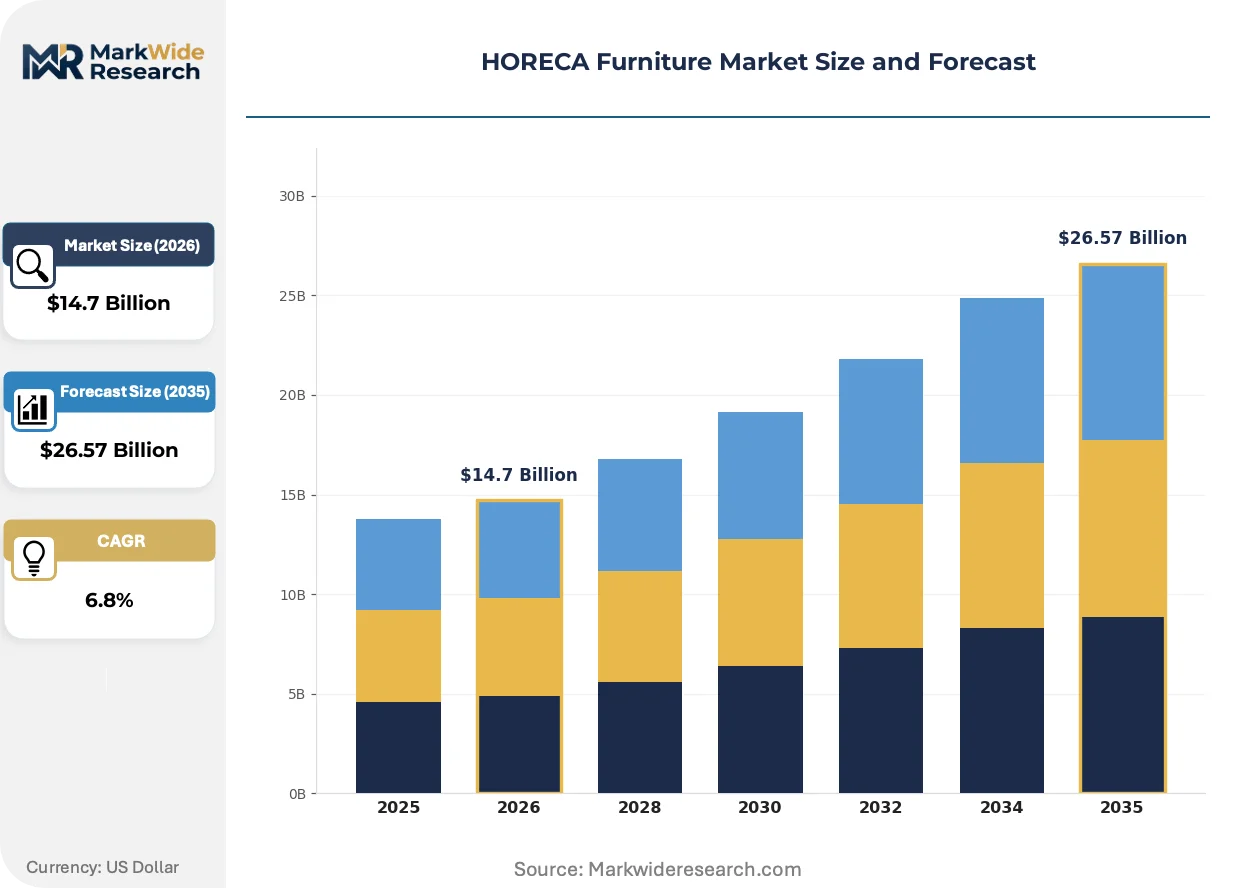
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Chairs, Sofas, Stools Material: Wood, Metal, Plastic, Upholstery End User: Restaurants, Cafés, Hotels, Bars Design Style: Contemporary, Rustic, Classic, Industrial |
| Companies Covered | Janus et Cie, Andreu World, Kimball Hospitality, Nowy Styl, Kinnarps, Bernhardt Hospitality, Fritz Hansen, Beaufurn, MINGSUN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HORECA Furniture Market Shifts & Advancements
Design modularity and regulatory material substitution are compressing traditional furniture development cycles, while procurement centralization among boutique hospitality chains is redrawing competitive access patterns.
Aluminum-tube framing systems with snap-fit joint hardware are modularizing restaurant seating configurations for European mid-market chains. Operators in Germany and the Netherlands are specifying these systems to enable same-day layout reconfigurations without specialized labor. The technology is modularizing procurement decisions, allowing property managers to purchase component libraries rather than fixed SKUs.
REACH Annex XVII restrictions on flame retardant formulations are forcing upholstery suppliers to reformulate foam cores and barrier fabrics for European hospitality projects. Manufacturers serving Spanish and Portuguese coastal hotels are accelerating bio-based adhesive testing to maintain specification eligibility. The regulatory pressure is concentrating supplier relationships around laboratories with ECHA pre-registration capabilities.
Design-led hotel brands are consolidating specification authority at regional headquarters, displacing property-level furniture autonomy. Procurement teams in Tokyo, Berlin, and New York are issuing unified standards documents that override local architect preferences. This concentration is visible most acutely in Japanese boutique chains, where central design committees now gate all furniture selections above threshold contract values.
HORECA Furniture Market Segmentation
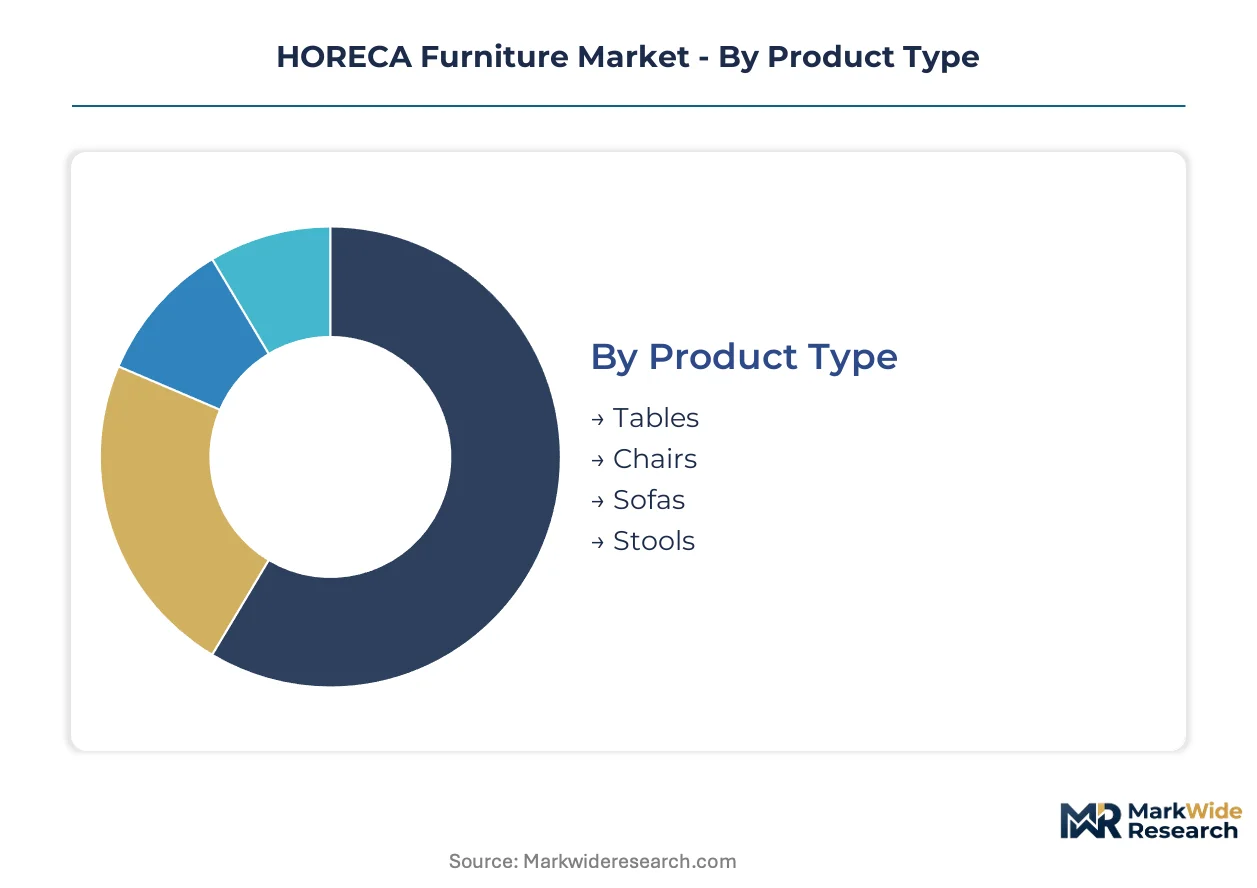
Segmentation in HORECA furniture determines procurement workflows, durability specifications, and compliance pathways. Each dimension carries distinct margin profiles and qualification requirements that shape supplier positioning.
Product Type:
Capital intensity varies sharply across seating versus surface categories, with fixed installations demanding the highest upfront tooling investment.
- Tables:Engineered with moisture-resistant substrates and edge-banding systems for intensive cleaning protocols. Demand concentrates in Mediterranean coastal hotels in Spain and Portugal where renovation cycles prioritize expandable configurations for banquet operations.
- Chairs:Stackable frames with fire-retardant upholstery meeting California TB 117-2013 standards dominate contract specifications. Boutique hotel chains across Germany and Japan are consolidating procurement authority for chair programs at regional headquarters.
- Sofas:Custom upholstery programs require specialized foam cores and barrier fabrics compliant with REACH Annex XVII restrictions.
- Stools:Counter-height seating for bars and cafés emphasizes welded-frame durability and footrail reinforcement.
Tables absorb the bulk of installed capacity; chairs are expanding most quickly.
Material:
Supplier qualification timelines diverge based on regulatory testing burdens and supply chain traceability requirements.
- Wood:Solid and engineered substrates dominate premium hotel specifications, with EU Green Deal mandates forcing requalification of entire product lines for European projects. Coastal urban markets in Greece and Portugal specify moisture-resistant frame engineering with specialized joint sealing.
- Upholstery:Foam cores and barrier fabrics face REACH chemical constraints that limit supplier pools and extend qualification timelines. North Carolina domestic capacity anchors US developer sourcing to bypass import lead time volatility.
- Metal:Aluminum-tube framing with snap-fit joint hardware enables same-day layout reconfigurations for mid-market European chains.
- Plastic:Polymer seating targets high-turnover casual dining with lower unit economics and faster replacement cycles.
Wood commands the dominant margin pool; metal frames are climbing the fastest.
End User:
Operational intensity and replacement frequency create distinct durability specifications across hospitality subsectors.
- Hotels:Guest room and lobby installations require fire-retardant certification and moisture-resistant engineering. Design-led brands in Japan and Germany centralize specification authority above threshold contract values.
- Restaurants:High-turnover dining environments prioritize stain-resistant upholstery and reinforced frame joints for daily intensive use.
- Cafés:Flexible seating configurations emphasize lightweight mobility and compact storage for variable occupancy patterns.
- Bars:Counter seating and standing-height surfaces demand footrail durability and spill-resistant finishes.
Hotels absorb the bulk of installed capacity; restaurants are gaining share fastest.
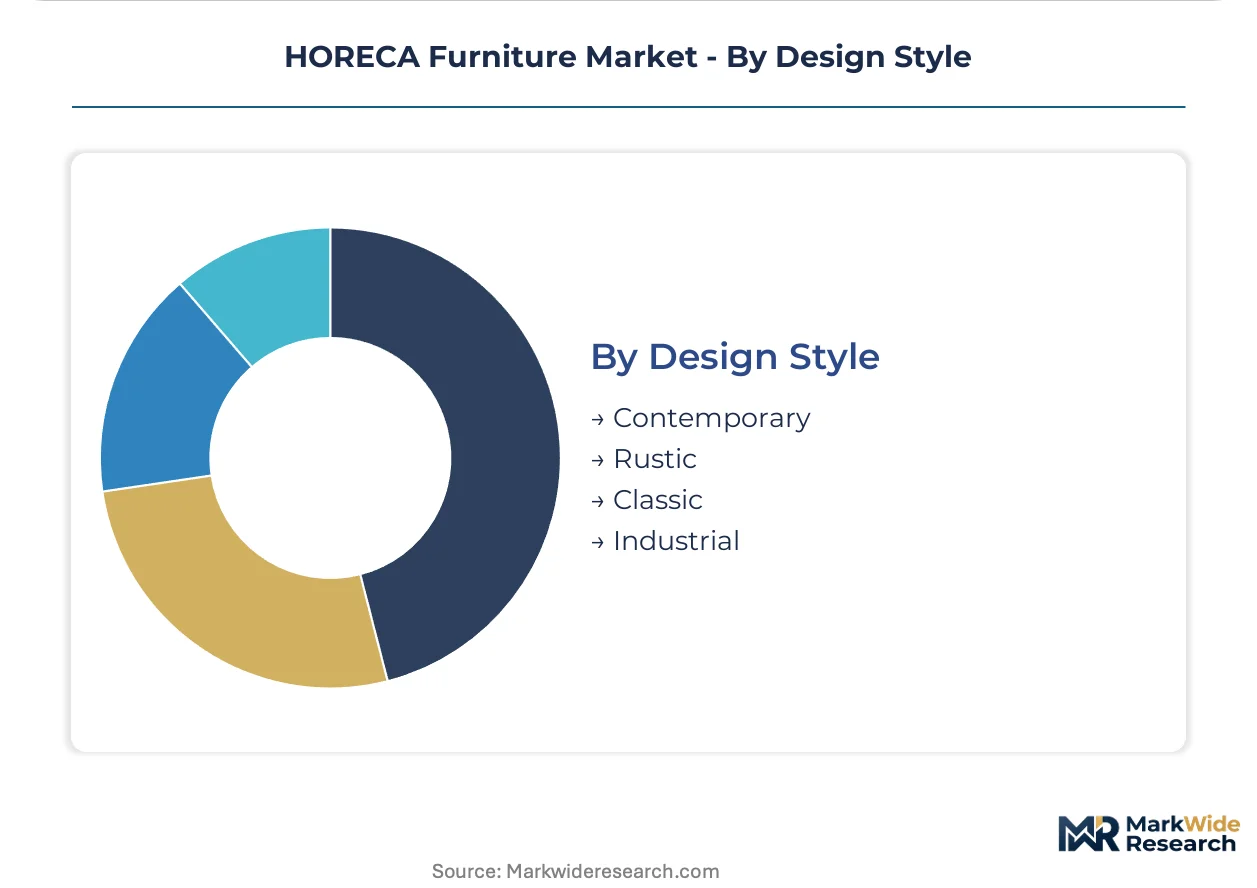
Design Style:
Specification dependency on design heritage creates asymmetric competitive access for regional manufacturers.
- Contemporary:Clean-line aesthetics with modular component systems enable property-level reconfiguration. Scandinavian hotel portfolios prioritize specification partners with documented Nordic manufacturing lineage.
- Industrial:Exposed metal frames and raw material finishes penetrate mid-market European and Asian restaurant chains. Welded-frame specialists capture specification opportunities as this aesthetic displaces traditional materials.
- Rustic:Reclaimed wood and distressed finishes target boutique hospitality in Mediterranean markets.
- Classic:Traditional silhouettes with ornate detailing serve heritage hotel properties and formal dining establishments.
Contemporary absorbs the bulk of installed capacity; industrial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solid timber reserves in Scandinavia and engineered wood clusters in North Carolina anchor raw-material access for hospitality-grade furniture manufacturing. Boutique hotel development pipelines in Germany, Japan, and the United States concentrate specification demand. Mediterranean coastal renovation cycles in Spain, Portugal, and Greece drive moisture-resistant frame engineering requirements.
United States
Boutique hotel chains are consolidating procurement authority for custom upholstery programs at regional headquarters in New York and Los Angeles. EPA formaldehyde emissions standards and California's TB 117-2013 flammability benchmark create interstate compliance requirements for hotel supply contracts. North Carolina's domestic upholstery capacity anchors developer sourcing to bypass import lead time volatility.
Germany
Extended Producer Responsibility frameworks mandate furniture take-back programs, creating service revenue streams for manufacturers with recovery infrastructure. EU Green Deal material mandates force suppliers to requalify entire product lines for European hospitality projects. Berlin and Munich hotel developers prioritize specification partners with documented circular economy credentials.
Japan
Design-led boutique chains are centralizing specification authority above threshold contract values through Tokyo-based design committees. METI guidelines on sustainable material sourcing influence procurement scoring for hospitality developers. Osaka and Kyoto hotel renovation projects emphasize fire-retardant certification aligned with domestic building codes.
Spain
Mediterranean tourism infrastructure renovation cycles concentrate demand for moisture-resistant frame specifications in Barcelona and Valencia coastal properties. REACH Annex XVII restrictions on flame retardant formulations force upholstery suppliers to reformulate foam cores for hospitality projects. Andalusian hotel operators specify expandable table configurations for banquet operations.
Greece
Coastal urban markets in Athens and Thessaloniki are replacing aging hospitality infrastructure with engineered wood installations. ECHA chemical constraints on adhesive formulations limit supplier pools for European qualification timelines. Aegean island resort developments prioritize specialized joint sealing for humidity-resistant frame engineering.
HORECA Furniture Market Competitive Landscape
Global majors compete with regional champions across specification access and lead-time reliability in the HORECA furniture sector. The vendor base separates into heritage design houses with documented Nordic or Mediterranean lineage, domestic upholstery specialists anchored near fire-retardant testing infrastructure, and metal-frame fabricators capturing industrial aesthetic demand. Strategic moves concentrate on geographic expansion through specification partnerships and backward integration into foam core and timber supply.
Within the heritage-tier segment, Andreu World and Fritz Hansen exemplify design-led positioning anchored in Mediterranean and Scandinavian manufacturing lineage respectively. Kimball Hospitality occupies a position among domestic-capability anchors, leveraging North Carolina-based upholstery infrastructure to serve United States hotel development pipelines. These three entities represent distinct competitive archetypes: geographic-specialist heritage, regional manufacturing-base defense, and domestic-capability anchoring.
| Leading Market Players |
|---|
| Janus et Cie |
| Andreu World |
| Kimball Hospitality |
| Nowy Styl |
| Kinnarps |
| Bernhardt Hospitality |
| Fritz Hansen |
| Beaufurn |
| MINGSUN |
| Others |
Supply & Pricing Matrix
Fire-retardant foam core costs cascade through upholstery pricing tiers, with REACH-compliant formulations commanding premium positioning against standard grades while California TB 117-2013 certification requirements compress margins for non-compliant suppliers serving interstate hotel contracts.
Pricing Analysis
Warranty and take-back service bundling separates premium HORECA furniture tiers from unbundled commodity offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and customization depth. Pricing pressure stems from boutique hotel chains' multi-source procurement fragmentation, which erodes volume discounts for regional manufacturers. Mid-market restaurant chains exhibit highest price sensitivity, while design-led boutique hotels prioritize specification heritage over unit cost.
Supply Chain Analysis
Skilled upholstery workforce availability in North Carolina and Valencia anchors manufacturing concentration against tightening labor pools in Scandinavian woodcraft regions. Supply draws from solid timber reserves in Scandinavia, engineered wood clusters in North Carolina, and aluminum extrusion capacity in Germany. Single-source vulnerability concentrates around REACH-compliant foam core suppliers with ECHA pre-registration capabilities. Distribution runs through specification-driven architect-designer channels rather than wholesale inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HORECA furniture market sits in a material-transition phase as aluminum-tube snap-fit framing displaces traditional welded and wood joinery across European mid-market restaurant chains.
For Market Incumbents: Acquire circular economy recovery infrastructure to capture Extended Producer Responsibility service revenue streams in Germany and France. Backward integration into foam core formulation secures REACH compliance against chemical supply consolidation. Boutique hotel procurement centralization threatens regional manufacturer access; anchor specification relationships through domestic testing infrastructure in North Carolina or Mediterranean manufacturing lineage. For New Entrants and Emerging Players: Launch via modular component library models targeting German and Dutch restaurant operators seeking same-day layout reconfiguration capability. White-space opportunity concentrates in industrial aesthetic metal framing for Asian mid-market chains. Mediterranean coastal renovation cycles in Spain and Portugal offer specification entry points for moisture-resistant frame engineering specialists. For Investors and Strategic Acquirers: German take-back mandate enforcement is the leading indicator that circular economy credentials will determine procurement scoring for European hospitality projects. Long-term viability favors manufacturers with closed-loop upholstery recovery systems and documented Nordic or Mediterranean design heritage. Monitor ECHA flame retardant restriction expansions as inflection signals for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Core Production | REACH Annex XVII compliance secures specification eligibility for European hospitality developers. |
| Circular Economy Certification Program | EU Green Deal procurement scoring rewards documented material recovery and take-back infrastructure. |
| Modular Component System Launch | Snap-fit aluminum framing captures German and Dutch restaurant chain layout reconfiguration demand. |
| Domestic Upholstery Capacity Expansion | North Carolina fire-retardant testing infrastructure bypasses import lead time volatility for US hotel pipelines. |
| Heritage Design Lineage Documentation | Scandinavian hotel portfolios prioritize specification partners with verifiable Nordic manufacturing provenance. |
Research Methodology
Trade association filings, customs and trade flow databases, and hospitality development permit records formed the secondary backbone of this analysis. Primary interviews with furniture specification directors at boutique hotel chains, procurement leads at restaurant franchise operators, and regulatory compliance officers at upholstery manufacturers combined with secondary validation. Bottom-up and top-down triangulation cross-checked regional renovation cycle intensity against manufacturer capacity utilization patterns.
Bottom-up modeling anchored volume estimates in project-level hospitality development pipelines across Spain, Portugal, Greece, Germany, Japan, and the United States. Segmentation dimensions included product type, material category, end-user sector, and design style tier across the analysis window. CAGRs derived from fitted trend lines against historical replacement cycle data and regulatory mandate implementation schedules. Forecast inputs incorporated EU Green Deal material mandate compliance timelines and Extended Producer Responsibility framework rollout phases.
The model assumes a particular technology adoption path; alternative pathways for aluminum-tube snap-fit framing penetration would alter the outlook for traditional wood and welded-frame suppliers. Forecasts reflect assumptions about Mediterranean tourism recovery trajectory and REACH chemical restriction expansion scope. Material deviation in German take-back enforcement intensity or California flammability standard revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
UK Sustainable Office Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
GCC Smart Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Lecterns Market
Furniture
GCC Home Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Cabinet Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
India Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Global Furniture Market
Furniture
United States Upholstered Furniture Market