
 GCC Home Furniture Market | 2026-2036
GCC Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Home Furniture Market Foresight
Subscription-based interior styling and furniture refresh services are pivoting how GCC retailers monetize repeat engagement beyond one-time transactions. Danube Home leverages its vertically integrated manufacturing and retail footprint to control margin pools across living room and bedroom collections. IKEA anchors market penetration through flat-pack logistics and localized Saudi showroom expansion. Al Huzaifa differentiates on bespoke upholstery craftsmanship targeting high-net-worth residential buyers in Dubai and Abu Dhabi.
GCC home furniture encompasses movable household fixtures—typically constructed from engineered wood, solid timber, metal framing, glass, or woven textiles—designed for domestic interior spaces spanning living, sleeping, dining, and work functions. Manufacturing processes range from CNC-machined panel production for cost-efficient bedroom sets to hand-finished joinery for premium dining room collections. Living room furniture commands the largest revenue share given frequent replacement cycles and showpiece purchasing behavior across Gulf households. Office seating is gaining structural momentum as hybrid work arrangements persist and corporate buyers in Riyadh and Doha upgrade residential-adjacent workspaces. Wood and engineered wood materials dominate volume, though metal and glass compositions are expanding in contemporary outdoor furniture lines aimed at year-round Gulf climates.
Saudi Standards, Metrology and Quality Organization (SASO) SABER platform mandates pre-shipment conformity for imported furniture, elevating compliance costs for non-certified suppliers while creating preference for established regional distributors. UAE's Emirates Conformity Assessment Scheme (ECAS) and Gulf Standardization Organization (GSO) technical regulations on formaldehyde emissions and upholstery flammability similarly filter market access. Stakeholders must monitor evolving Gulf customs union harmonization and Saudi local content requirements as these frameworks increasingly determine competitive viability and supplier selection criteria.
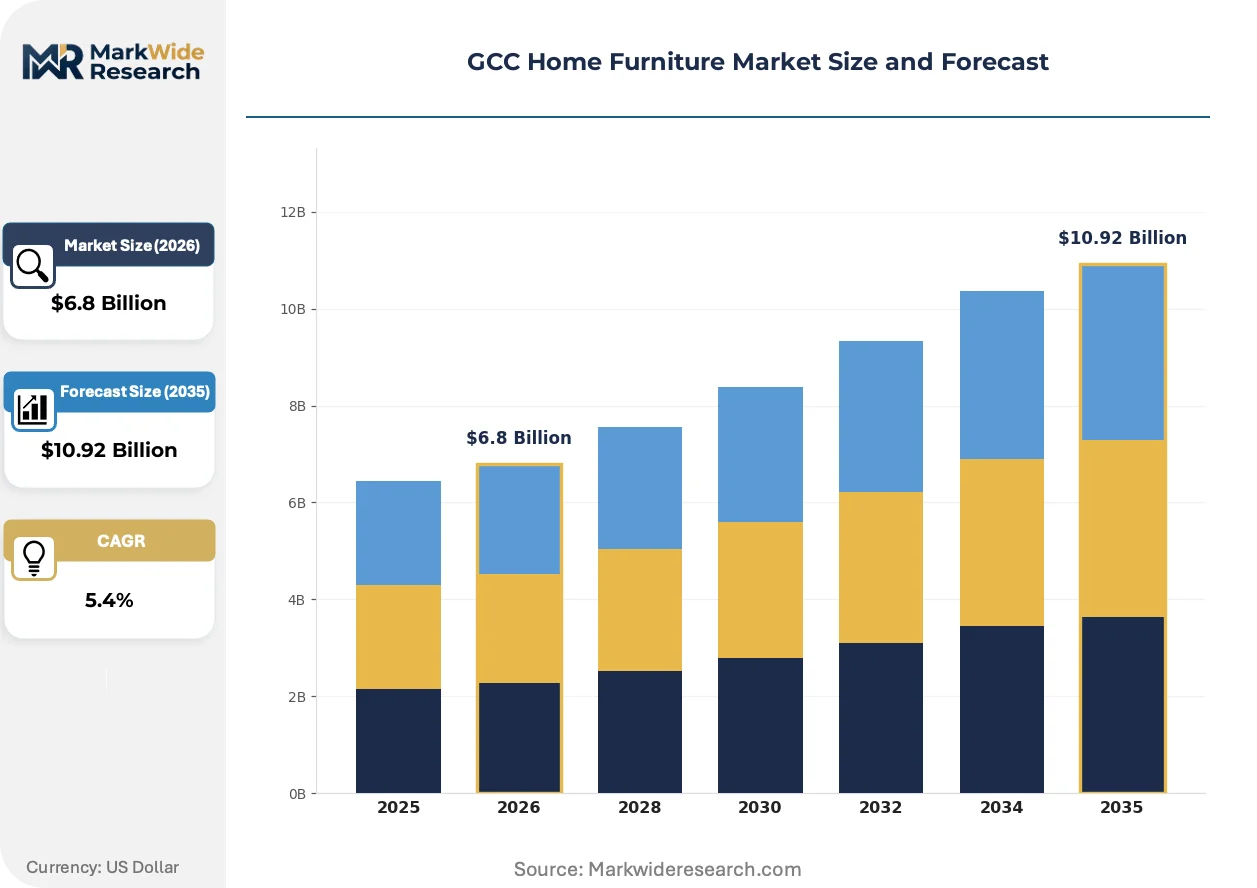
Market Dynamics
Gulf residential construction pipelines are pulling furniture procurement forward into fixed-price contracts with developers, compressing traditional retail replacement cycles and concentrating volume with project-specification teams rather than individual consumers.
Growth Catalysts
- Giga-project construction corridors:Saudi Arabia's Riyadh and Jeddah development zones are embedding furniture packages directly into residential and hospitality delivery schedules, locking in multi-year procurement commitments ahead of occupancy.
- SASO SABER pre-shipment conformity:The Saudi platform's mandatory certification for imported upholstered goods is filtering non-compliant suppliers and creating preference for established distributors with in-country testing capabilities.
- Hybrid work normalization:Corporate buyers in Doha and Riyadh are upgrading residential-adjacent office seating, extending furniture demand beyond traditional domestic living spaces into employer-subsidized home workspaces.
Market Restraints
- Engineered wood input volatility:Panel substrate costs fluctuate with regional petrochemical feedstock pricing, squeezing margin pools for mid-range bedroom and storage collections.
- Import concentration risk:Non-GCC Asian manufacturing clusters dominate flat-pack and upholstered supply, exposing distributors to shipping rate spikes and customs clearance bottlenecks at Jebel Ali and Dammam ports.
- Upholstery flammability technical barriers:GSO technical regulations on foam and fabric ignition resistance require specialized testing infrastructure unavailable to smaller regional assemblers.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets lack the giga-project density of Saudi Arabia and UAE, creating whitespace for subscription-based furniture refresh services targeting expatriate professionals.
- ECAS regulatory tailwind:UAE's Emirates Conformity Assessment Scheme incentivizes local warehousing and final-stage assembly, rewarding distributors who shift from pure import to light manufacturing within free zones.
- Metal-glass outdoor convergence:Year-round Gulf climates are accelerating demand for contemporary patio and terrace collections that blend weather-resistant metal framing with tempered glass surfaces.
Industry Challenges
- Artisan upholstery skill scarcity:Bespoke hand-finishing capabilities for high-net-worth residential buyers concentrate in legacy Dubai workshops, constraining Al Huzaifa-style differentiation at scale.
- SABER certification timeline compression:Pre-shipment documentation requirements add 4-6 weeks to procurement cycles, forcing project developers to front-load specification decisions or absorb delay penalties.
- Legacy ERP integration friction:Regional distributors upgrading from manual order management to cloud-based inventory systems face data migration bottlenecks during peak construction delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Home Furniture Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Living Room, Bedroom, Dining Room, Office Seating, Outdoor Furniture Material: Wood, Metal, Glass, Fabric, Leather, Rattan Sales Channel: Specialty Stores, Department Stores, Online Retailers, Direct Sales, Wholesale Distributors Customer Type: Residential Buyers, Property Developers, Hospitality Establishments, Corporate Offices |
| Companies Covered | Danube Home, Saudi Modern Factory Co, Al Huzaifa, Herman Miller, Al Aamer Furniture Co, IKEA, Midas Furniture, Ashley Furniture Industries Inc., Home Center, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Home Furniture Market Shifts & Advancements
Digital specification tools and localized manufacturing footprints are compressing the gap between project conceptualization and furniture delivery across Gulf construction corridors.
CNC-machined panel production is rewriting cost structures for standardized bedroom and storage collections. Saudi-based project developers are specifying these systems for volume residential units, enabling factory-direct procurement that bypasses traditional retail markups and compresses lead times from 12 weeks to 4 weeks.
UAE's ECAS conformity scheme is tightening documentation requirements for formaldehyde emissions in engineered wood products. Distributors are responding by shifting final cutting and edge-banding operations into Dubai South free zones, creating tariff-advantaged assembly nodes that qualify for domestic origin certification.
Subscription-based interior refresh services are displacing one-time retail transactions among younger expatriate households in Doha and Abu Dhabi. These buyers prefer quarterly furniture rotation over ownership, forcing traditional retailers to unbundle product sales from styling consultation and logistics services.
GCC Home Furniture Market Segmentation
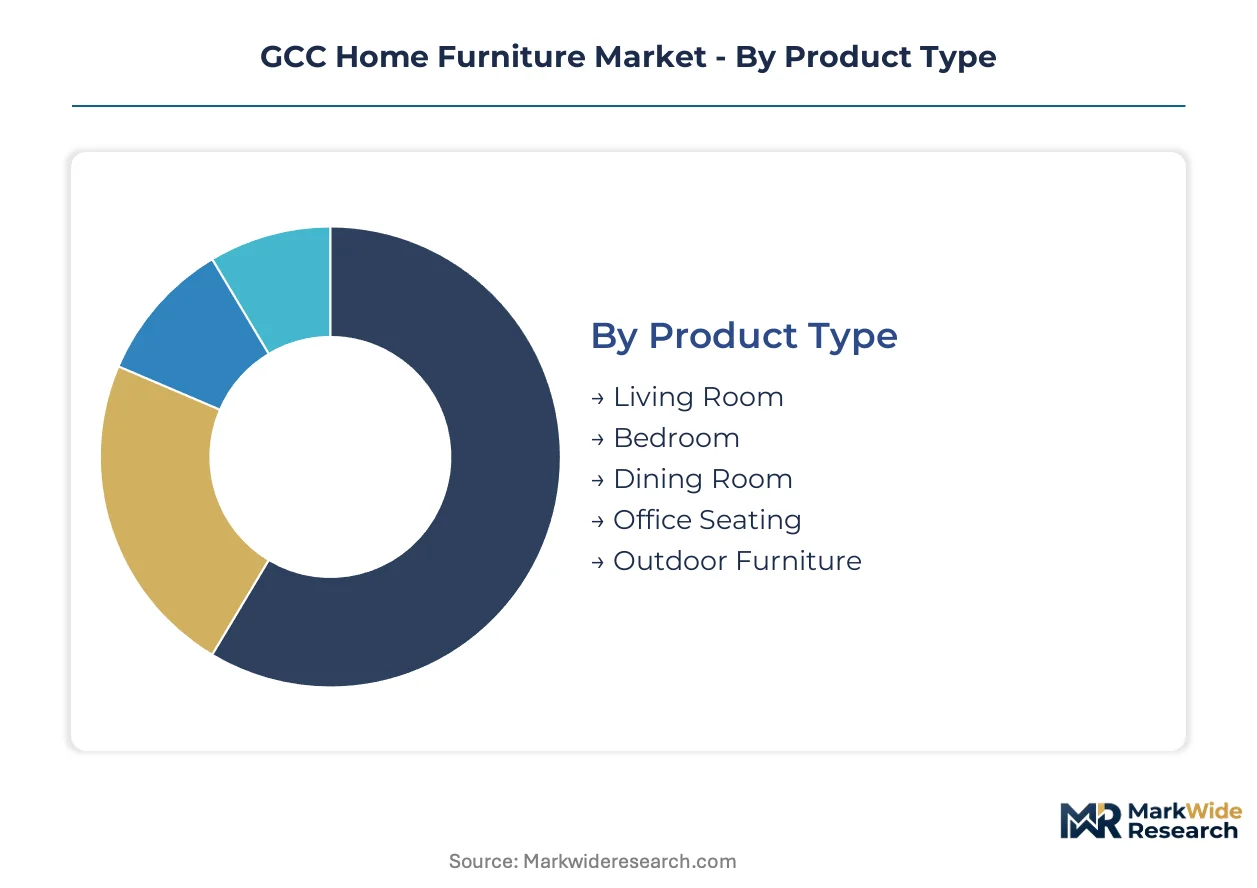
Furniture procurement patterns across the Gulf diverge sharply between project-driven bulk contracts and individual retail purchases. Understanding these segment boundaries clarifies why manufacturing scale, compliance infrastructure, and logistics capabilities determine competitive viability.
Product Type:
Standalone furniture categories dominate residential replacement cycles, while embedded systems integrate directly into developer fit-out specifications.
- Living Room:Sofas, sectionals, and coffee tables constructed from engineered wood frames with fabric or leather upholstery. Demand concentrates in Riyadh and Jeddah residential corridors where giga-project handovers trigger bulk procurement of standardized showpiece collections.
- Bedroom:CNC-machined panel systems for wardrobes, bed frames, and nightstands. Saudi project developers specify these for volume residential units, enabling factory-direct procurement that compresses lead times from 12 weeks to 4 weeks.
- Dining Room:Hand-finished joinery targeting high-net-worth buyers in Dubai and Abu Dhabi.
- Office Seating:Ergonomic chairs and workstations for employer-subsidized home workspaces in Doha and Riyadh.
- Outdoor Furniture:Weather-resistant metal-glass compositions for year-round Gulf terrace usage.
Volume placements concentrate in Living Room; the faster expansion belongs to Office Seating.
Material:
Cost tier positioning separates commodity inputs from premium specification grades across Gulf import channels.
- Wood:Solid timber and engineered panels forming structural frames for bedroom and storage collections. Panel substrate costs fluctuate with regional petrochemical feedstock pricing, squeezing margin pools for mid-range manufacturers.
- Metal:Powder-coated aluminum and steel framing for contemporary outdoor and office seating lines. UAE distributors are shifting final cutting and welding operations into Dubai South free zones to qualify for ECAS domestic origin certification.
- Glass:Tempered surfaces for dining and outdoor tabletops.
- Fabric:Upholstery textiles subject to GSO flammability technical regulations.
- Leather:Premium hides for bespoke residential commissions.
- Rattan:Woven synthetic alternatives for coastal hospitality projects.
Wood commands the dominant procurement volume; metal compositions are climbing the fastest as outdoor and office categories expand.
Sales Channel:
Customer type determines whether transactions flow through retail touchpoints or bypass them entirely for direct specification.
- Specialty Stores:Curated showrooms with in-house design consultation for residential buyers in Dubai and Abu Dhabi. Subscription-based refresh services are displacing one-time transactions among younger expatriate households in Doha.
- Department Stores:Mid-range collections for standardized bedroom and living room procurement.
- Online Retailers:Flat-pack logistics platforms with localized Saudi showroom support.
- Direct Sales:Project-specification teams locking multi-year furniture packages into giga-project delivery schedules.
- Wholesale Distributors:ECAS-certified warehousing for engineered wood products.
Direct Sales channels capture the largest project volumes; online platforms are expanding most quickly.
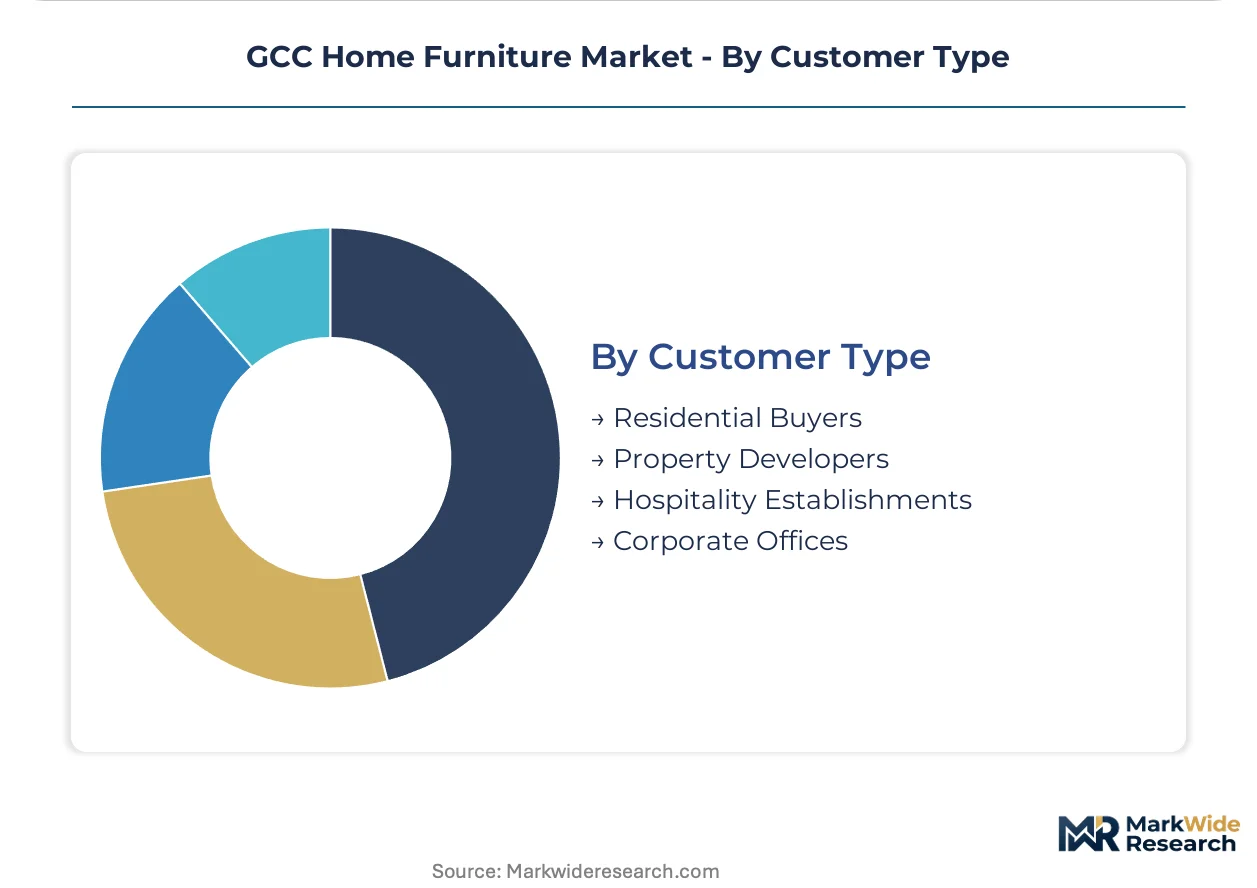
Customer Type:
Application maturity separates established residential replacement cycles from emerging hybrid-work categories.
- Residential Buyers:Individual households purchasing showpiece living room collections and bedroom replacement sets. Quarterly furniture rotation preferences are forcing traditional retailers to unbundle product sales from styling services.
- Property Developers:Saudi giga-project contractors embedding furniture packages directly into residential and hospitality delivery schedules.
- Hospitality Establishments:Bulk procurement for hotel and serviced apartment fit-outs.
- Corporate Offices:Employer-subsidized home workspace upgrades in Riyadh and Doha.
Property Developers drive the steepest volume concentration; Corporate Offices represent the fastest-expanding demand category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's giga-project construction corridors are pulling the majority of GCC furniture procurement volume, with developer-direct contracts displacing traditional retail channels across residential and hospitality fit-outs.
Saudi Arabia
SABER pre-shipment conformity mandates are filtering non-compliant upholstered goods from import channels, elevating preference for distributors with in-country testing infrastructure. The Saudi Standards, Metrology and Quality Organization tightened formaldehyde emission thresholds for engineered wood in 2024. NEOM and the Red Sea Project are embedding furniture packages directly into hospitality delivery schedules, locking in multi-year procurement commitments.
United Arab Emirates
ECAS domestic origin certification is incentivizing final-stage assembly operations within Dubai South and Jebel Ali free zones. The Emirates Conformity Assessment Scheme now requires localized documentation for tempered glass and metal framing components. Abu Dhabi's Al Reem Island and Dubai's Dubai Hills Estate are concentrating bespoke upholstery demand among high-net-worth residential buyers.
Qatar
Employer-subsidized home workspace upgrades are accelerating office seating procurement beyond traditional domestic replacement cycles. The Qatar General Organization for Standardization maintains GSO-aligned technical regulations on upholstery flammability. Doha's Lusail City development is pulling contemporary outdoor furniture volumes for terrace-focused residential typologies.
Kuwait
Expatriate professional households are driving subscription-based furniture refresh services that displace one-time retail ownership models. The Public Authority for Industry administers import conformity procedures without the giga-project density of neighboring markets. Kuwait City's Salmiya and Sharq districts concentrate specialty showroom demand among younger, mobility-oriented residents.
Bahrain
Underpenetrated project development pipelines are creating whitespace for wholesale distributors establishing ECAS-certified warehousing nodes. The Bahrain Standards and Metrology Directorate harmonizes with Gulf technical regulations on foam ignition resistance. Manama's Seef and Juffair corridors host the majority of mid-range bedroom and living room retail transactions.
GCC Home Furniture Market Competitive Landscape
Capital-heavy producers with captive manufacturing footprints compete with asset-light designers and specification teams for developer-direct contracts across Gulf construction corridors. The market structures around three tiers: vertically integrated regional fabricators controlling margin pools through in-house panel production, global flat-pack logistics platforms leveraging localized showroom networks, and bespoke upholstery specialists concentrating hand-finishing capabilities in legacy workshops. Strategic moves center on free-zone assembly qualification for domestic origin certification and backward integration into CNC-machined panel systems.
Among regional fabricators, Danube Home exemplifies the vertically integrated archetype through manufacturing and retail footprint control. Al Huzaifa occupies a position within the bespoke upholstery tier targeting residential buyers in Dubai and Abu Dhabi. IKEA anchors the flat-pack logistics platform segment with localized Saudi showroom expansion. These three players represent distinct competitive vectors—captive production, craftsmanship differentiation, and scale logistics—without overlapping positioning.
| Leading Market Players |
|---|
| Danube Home |
| Saudi Modern Factory Co |
| Al Huzaifa |
| Herman Miller |
| Al Aamer Furniture Co |
| IKEA |
| Midas Furniture |
| Ashley Furniture Industries Inc. |
| Home Center |
| Others |
Supply & Pricing Matrix
SASO SABER formaldehyde emission mandates gate qualified supply and premium-tier pricing access, as distributors lacking in-country testing infrastructure face exclusion from Saudi project pipelines while compliant players capture margin premiums on certified bedroom and upholstery collections.
Pricing Analysis
Project-completion guarantees anchor value-based pricing for developer-direct contracts, where fixed-price furniture packages bundle SASO-certified engineered wood with penalty clauses for delivery delays. Price differentiation separates SABER-compliant distributors from non-certified importers, with the former commanding 15-20% premiums on upholstered goods. Cost compression in mid-range panel furniture intensifies because petrochemical feedstock volatility squeezes engineered wood substrate margins. Property developers exhibit lowest price sensitivity given occupancy deadline penalties, while individual retail buyers in Kuwait and Bahrain remain most responsive to promotional cycles.
Supply Chain Analysis
Dual-sourcing requirements from Saudi giga-project developers mandate qualification of at least two SABER-certified upholstery suppliers per contract, fragmenting volume across Malaysia, Vietnam, and Turkey rather than concentrating with single-country manufacturers. Raw material dependencies center on Malaysian rubberwood panels, Chinese melamine-faced particleboard, and Italian tannery hides. Single-source vulnerability concentrates in specialized foam suppliers meeting GSO flammability standards. Distribution runs through Jebel Ali and Dammam port-centric warehousing with final-mile staging into free-zone assembly nodes for ECAS domestic origin qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
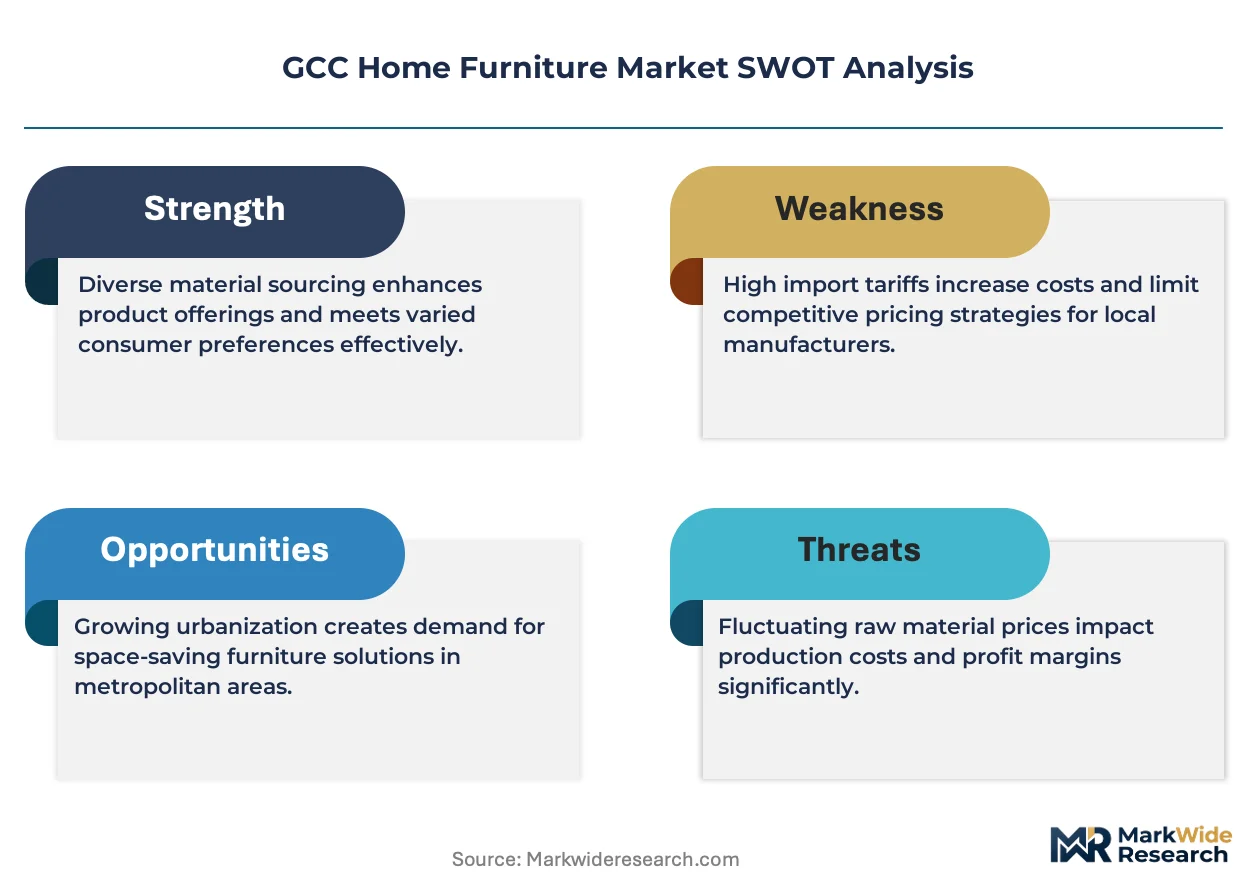
This market reads as a cost-of-compliance story: SASO SABER pre-shipment certification creates a barrier-to-entry moat that rewards established distributors with sunk testing infrastructure while filtering speculative importers.
For Market Incumbents: Hedge against Asian manufacturing concentration by qualifying secondary panel suppliers in Turkey and Egypt for bedroom collections, while reinforcing SABER testing capabilities as a competitive lock-in mechanism against emerging UAE-based distributors seeking Saudi market entry. For New Entrants and Emerging Players: Expatriate professional households in Kuwait and Bahrain represent the most penetrable buyer archetype, where subscription-based furniture refresh services displace traditional ownership models; enter through digital-native styling platforms unbundled from inventory-heavy retail footprints. For Investors and Strategic Acquirers: ECAS certification timeline compression at Dubai South free zones is the leading indicator that light-manufacturing assembly nodes will command acquisition premiums; target distributors with existing warehouse leases and customs brokerage relationships over pure import-trading operations, watching for developer-direct contract win rates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SABER Testing Infrastructure Investment | In-country certification capabilities lock out non-compliant competitors from NEOM and Red Sea Project pipelines. |
| Free-Zone Assembly Qualification | Dubai South final-stage operations secure ECAS domestic origin status for tariff-advantaged Gulf customs union distribution. |
| Subscription Service Unbundling | Quarterly furniture rotation models capture lifetime value from mobile expatriate professionals in Doha and Abu Dhabi. |
| Panel Supplier Diversification | Rubberwood sourcing from Malaysia and Vietnam reduces petrochemical feedstock cost volatility exposure. |
| Artisan Upholstery Capability Acquisition | Legacy Dubai workshop hand-finishing skills differentiate high-net-worth residential bids against CNC-standardized competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Saudi project procurement directors, UAE free-zone operations managers, and Kuwaiti retail category buyers. SASO technical regulation updates, GSO flammability standards documentation, and ECAS conformity scheme bulletins provided compliance framework validation. Bottom-up furniture shipment volumes triangulated against top-down construction pipeline values across Riyadh, Jeddah, and Dubai development corridors.
Granularity-level modeling disaggregated the analysis window by product type, material composition, sales channel, and customer archetype, with separate trajectory assumptions for project-driven bulk contracts versus individual retail replacement cycles. CAGRs derived from construction handover schedules, hospitality fit-out timelines, and hybrid-work furniture upgrade patterns. Forecast inputs incorporated SABER certification adoption curves and free-zone assembly migration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf customs union harmonization timelines and Saudi local content requirement escalations. Deviation in giga-project delivery schedules or SABER platform procedural changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Kids Furniture Market
Furniture
India Furniture Market
Furniture
India Home Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
US Sustainable Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Unfinished Wood Furniture Market