
 Flush Door Market | 2026-2036
Flush Door Market Size, Share, and Industry Trends Forecast 2026-2036
Flush Door Market Analysis
Multi-source procurement toward captive panel manufacturing is pivoting as cost volatility reshapes supplier relationships. Masonite International leverages its North American fiberboard infrastructure to sustain raw material security. Jeld-Wen anchors its position through vertically integrated distribution across big-box and pro-dealer channels. Greenply competes on laminated veneer lumber technology leadership in South Asian markets.
A flush door is a flat-surfaced door built with a timber or composite frame encased by thin face skins, typically plywood, MDF, or veneer, with internal voids or solid filler determining acoustic and thermal performance. The primary purpose is to provide a smooth, paint-ready or pre-finished surface for interior and exterior openings in residential, commercial, and institutional buildings. Solid core configurations command premium positioning in fire-rated and sound-proof applications where density and mass drive code compliance. Hollow core variants dominate volume in residential interior installations where cost efficiency and weight reduction outweigh performance demands. MDF segment growth reflects shifting builder preference for consistent dimensional stability over natural timber in humid climates.
India's BIS standards for fire resistance and structural integrity directly shape product certification requirements and factory-level testing investment. The US EPA formaldehyde emission regulations under TSCA Title VI constrain adhesive chemistry choices for wood composite doors entering American distribution. China's GB standards for interior decoration materials enforce volatile organic compound thresholds that filter supplier eligibility. Stakeholders must monitor evolving cross-border timber legality frameworks and regional green building code adoption to anticipate where certification premiums will expand or compress margin pools.
Market Dynamics
Multi-source procurement toward captive panel manufacturing is pivoting as cost volatility reshapes supplier relationships across engineered wood products. Raw material security now dictates competitive positioning in flush door manufacturing.
Growth Catalysts
- BIS fire resistance mandates:India's certification requirements for structural integrity and fire-rated performance drive factory-level testing investment and premium product development.
- Engineered wood substitution:MDF and laminated veneer lumber technologies displace solid timber in humid climate construction, expanding addressable applications.
- Suburban residential construction:Maharashtra's Mumbai-Pune corridor and Gujarat's Ahmedabad-Surat cluster concentrate demand for cost-efficient interior door solutions.
Market Restraints
- Adhesive chemistry constraints:US EPA formaldehyde emission regulations under TSCA Title VI limit binder options for composite door exports to American distribution.
- Timber legality verification:Cross-border timber sourcing faces escalating documentation requirements under evolving EUTR and Lacey Act enforcement.
- Core material density limitations:Hollow core configurations fail to meet acoustic and thermal performance thresholds in institutional and high-rise applications.
Strategic Opportunities
- Pre-finished surface systems:Factory-applied coating technologies eliminate on-site finishing labor, capturing contractor preference in commercial build-outs.
- Green building code alignment:LEED and IGBC certification pathways create specification pull for low-VOC and recycled-content door assemblies.
- Integrated distribution platforms:Big-box and pro-dealer channel consolidation enables direct-to-contractor fulfillment models bypassing traditional wholesaler tiers.
Industry Challenges
- Skilled laminator shortage:Veneer matching and pressing expertise gaps constrain quality consistency in decorative flush door production.
- Fire testing backlog:BIS certification timelines extend 12-18 months, delaying product launches and locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flush Door Market |
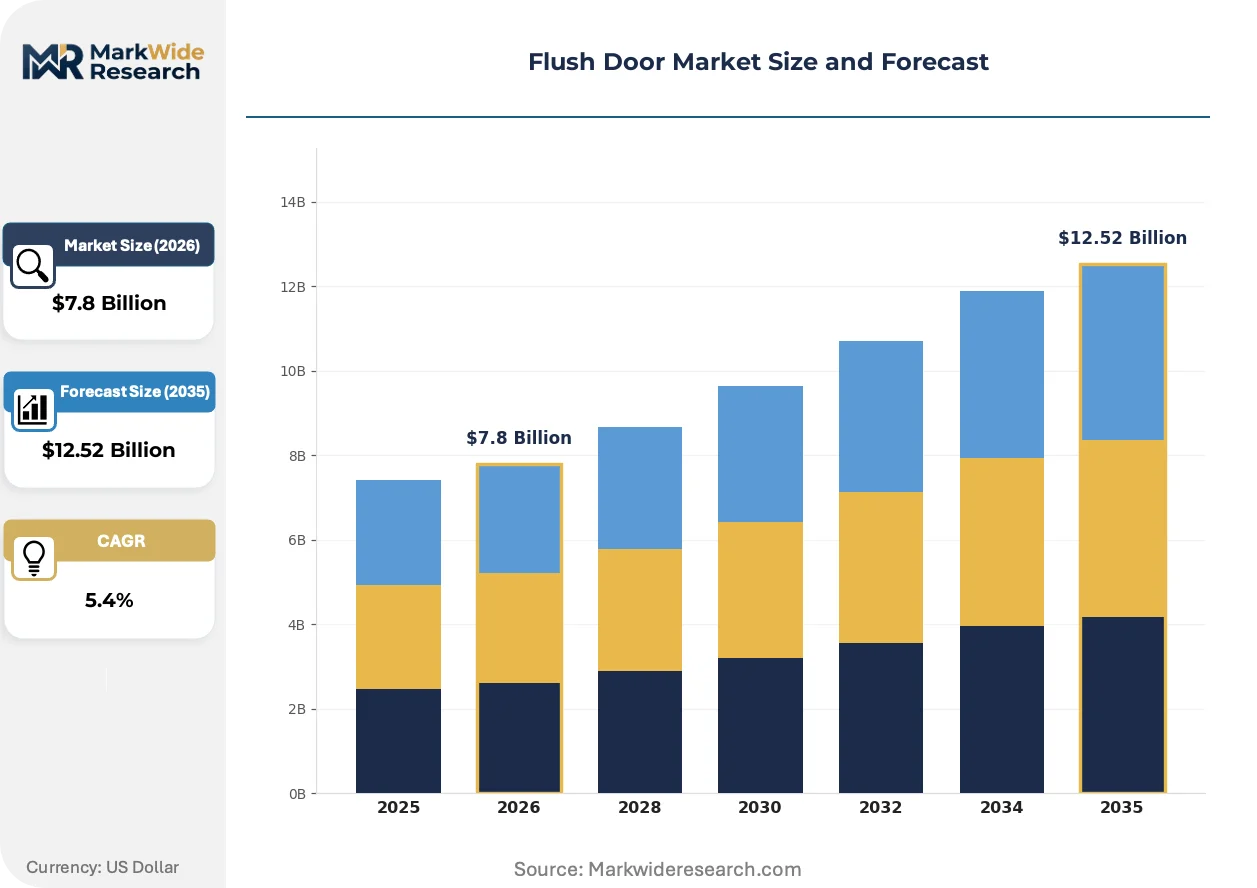
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Core, Hollow Core, MDF, Veneer Material: Wood, Steel, Aluminum, Plastic End User: Residential, Commercial, Institutional, Industrial Application: Interior, Exterior, Fire Rated, Sound Proof |
| Companies Covered | Simpson Door, Enfield Doors, Jeld-Wen, Duroply Industries Limited, Minimax, Masonite International, Archidply, Greenply, Steves Door, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flush Door Market Emerging Trajectories
Surface engineering and core material science are compressing the performance gap between premium architectural doors and mass-market flush products. Manufacturing automation is rewriting cost structures.
Cross-laminated timber and high-density fiberboard core technologies are rewriting density-to-weight performance ratios in fire-rated door assemblies. Hospital and educational facility specifiers now source flush doors meeting 90-minute fire ratings at 40% weight reduction versus traditional solid core. This shift is compressing freight costs and installation labor requirements while expanding code-compliant applications.
REACH restrictions on formaldehyde-releasing adhesives and China's GB standards for volatile organic compounds are forcing reformulation of urea-formaldehyde binders in Asian manufacturing. European import gates now require third-party emissions testing documentation. Indian exporters to EU markets are accelerating phenolic resin and bio-based adhesive pilot programs to maintain market access.
Builder procurement consolidation toward direct mill relationships is disintermediating traditional distributor networks. Large residential developers in India's western states now specify custom dimensions and finishes through factory-direct contracts. This bypasses regional stock-and-sell wholesalers, compressing margin pools at intermediary tiers while rewarding scale manufacturers with captive distribution infrastructure.
Flush Door Market Segmentation
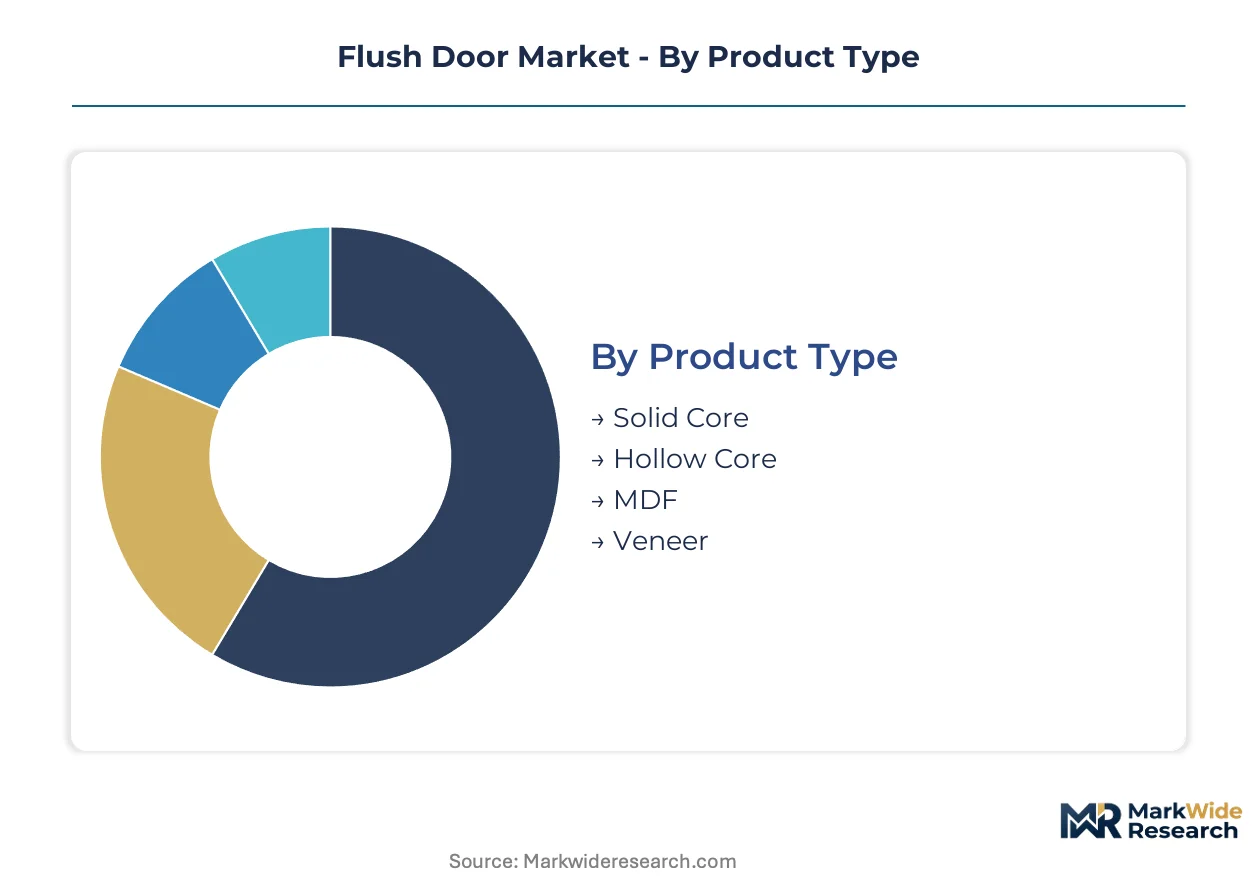
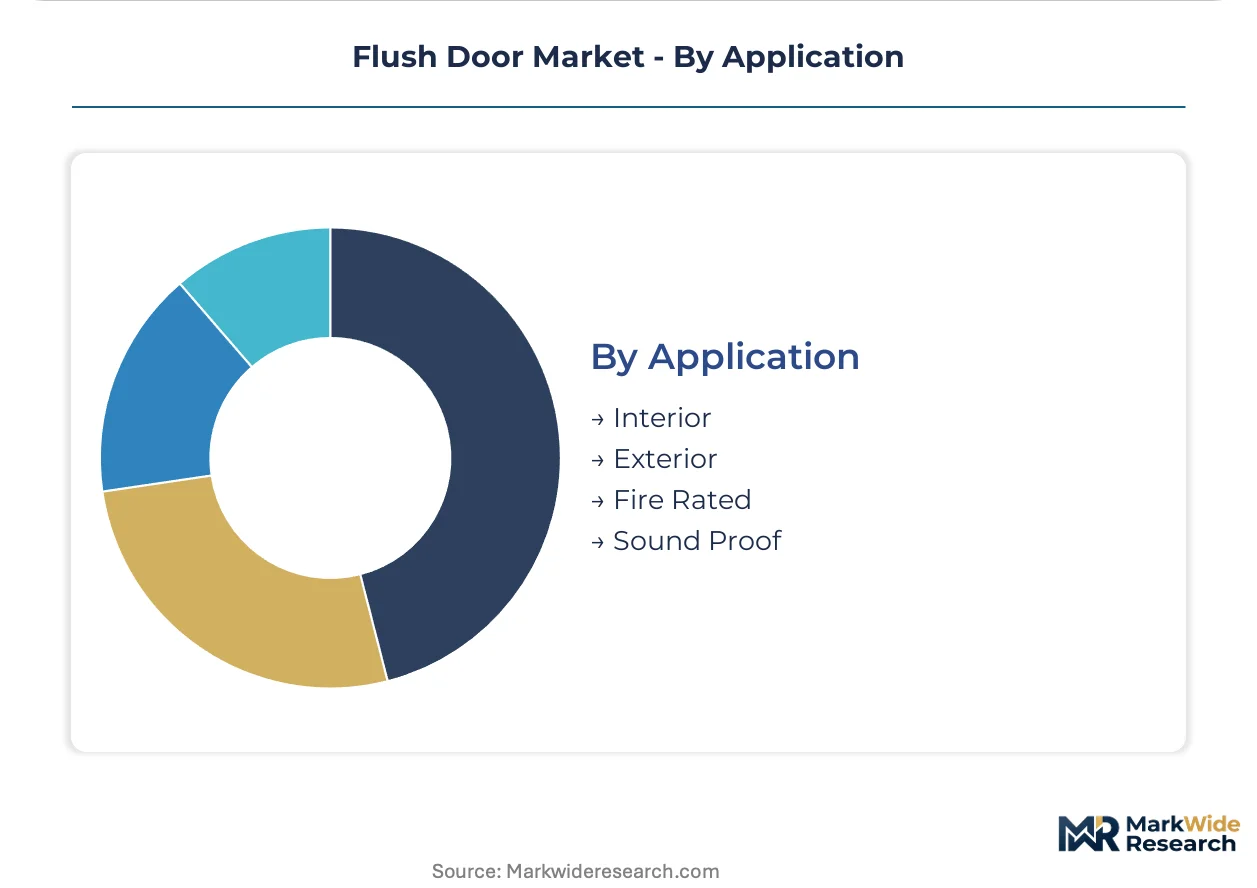
Flush door manufacturers configure product portfolios across four intersecting dimensions: core construction, substrate material, end-use environment, and performance specification. Each segmentation axis carries distinct margin profiles, certification requirements, and procurement channel preferences that shape competitive positioning.
Product Type:
Volume concentrates in hollow core configurations for residential interiors. Premium capture belongs to solid core and fire-rated assemblies where density and mass drive specification.
- Solid Core:Built with particleboard, MDF, or timber block infill between face skins. Density exceeds 35 pounds per cubic foot. Demand clusters in Maharashtra's hospital and educational construction where BIS fire ratings mandate mass-driven assemblies. Premium pricing reflects 12-18 month certification timelines and specialized laminator labor.
- Hollow Core:Cellular cardboard or thin wood lattice structure minimizes weight. Dominates Gujarat's Ahmedabad-Surat residential corridor where cost efficiency outweighs acoustic performance. Builder procurement consolidation favors factory-direct hollow core contracts bypassing regional wholesalers.
- MDF:Medium-density fiberboard faces deliver dimensional stability in humid climates. India's western coastal states specify MDF over natural timber for moisture resistance.
- Veneer:Decorative hardwood surfaces command specification in premium commercial fit-outs. Skilled matching expertise constrains supply scalability.
Mature deployment sits with hollow core. Newer deployment is concentrated in MDF as engineered wood substitution accelerates.
Material:
Substrate selection follows climate exposure, fire code, and maintenance lifecycle requirements across end-use segments.
- Wood:Timber frames and skins remain dominant in residential construction. BIS structural integrity standards govern moisture content and grade classification. India's timber legality documentation requirements under evolving EUTR enforcement constrain import sourcing flexibility.
- Steel:Galvanized or cold-rolled frames with mineral core infill serve 90-minute fire-rated applications. Hospital and high-rise specifiers in Mumbai-Pune corridor specify steel for institutional code compliance.
- Aluminum:Lightweight frames with honeycomb cores suit exterior exposure in coastal environments. Corrosion resistance drives adoption in Gujarat's chemical industrial zones.
- Plastic:PVC or fiberglass-reinforced polymer assemblies serve high-moisture environments. Limited penetration outside specialized industrial wash-down facilities.
Wood commands the largest installed base. Steel is expanding most quickly as fire code stringency tightens across western Indian states.
End User:
Procurement scale and specification authority separate institutional buyers from fragmented residential decision-makers.
- Residential:Single-family and multi-family construction drives volume. Suburban expansion in Maharashtra and Gujarat concentrates demand for cost-optimized interior solutions.
- Commercial:Office and retail fit-outs specify pre-finished surfaces to accelerate build-out schedules. Direct mill relationships disintermediate traditional distributor tiers.
- Institutional:Hospitals, schools, and government buildings mandate certified fire and acoustic performance. BIS testing backlogs delay product launches and lock working capital.
- Industrial:Manufacturing and warehousing facilities prioritize durability over aesthetics. Steel and plastic substrates dominate this specification tier.
Residential absorbs the highest unit volume. Institutional commands the steepest premium expansion trajectory as certification requirements proliferate.
Application:
Performance specification tiers separate commodity interior doors from engineered fire and acoustic assemblies.
- Interior:Standard duty doors for non-rated partitions. Hollow core and MDF variants dominate this high-volume, price-sensitive segment.
- Exterior:Weather-resistant construction with moisture barriers and thermal breaks. Aluminum and steel frames gain share in humid coastal zones.
- Fire Rated:Tested assemblies meeting 30, 60, or 90-minute resistance per BIS and NFPA standards. Cross-laminated timber and high-density fiberboard cores enable 40% weight reduction versus traditional solid core.
- Sound Proof:Mass-loaded cores and perimeter seals achieve STC 35-50 ratings. Recording studios, conference facilities, and healthcare patient rooms drive specification.
Interior applications hold mature market penetration. Fire rated is climbing the fastest as building code adoption accelerates across Indian states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Timber plantations across the Pacific Northwest and Southeast United States anchor North American fiberboard supply chains for engineered door manufacturing. India's western coastal states concentrate plywood and veneer processing infrastructure. China's Yangtze River Delta houses the densest cluster of MDF substrate production facilities serving Asian construction markets.
United States
Multi-family residential construction in Texas and Florida drives specification for hollow core interior assemblies. The EPA's TSCA Title VI formaldehyde emission standards constrain adhesive chemistry for composite doors entering distribution. Masonite International leverages its fiberboard infrastructure across the Southeast to sustain raw material security for domestic manufacturing.
India
Suburban residential expansion across Maharashtra's Mumbai-Pune corridor and Gujarat's Ahmedabad-Surat cluster concentrates demand for cost-optimized flush door solutions. BIS certification mandates for fire resistance and structural integrity shape factory-level testing investment and product development timelines. Greenply competes on laminated veneer lumber technology leadership across South Asian markets.
China
Urban renewal projects in the Yangtze River Delta and Pearl River Delta sustain volume demand for pre-finished interior door systems. GB standards for volatile organic compound thresholds in interior decoration materials enforce emissions documentation requirements. Zhejiang and Jiangsu provinces host the primary concentration of MDF face skin manufacturing capacity serving domestic builders.
Germany
Energy-efficient building renovation across Bavaria and North Rhine-Westphalia drives specification for thermally performing door assemblies. REACH restrictions on formaldehyde-releasing adhesives force reformulation of traditional urea-formaldehyde binders in European manufacturing. The Cologne-Düsseldorf industrial corridor concentrates decorative veneer pressing and pre-finishing operations for premium commercial fit-outs.
Brazil
Affordable housing programs in São Paulo and Minas Gerais sustain volume demand for engineered wood interior solutions. Timber legality documentation requirements under evolving enforcement frameworks constrain import sourcing flexibility for Amazon-sourced hardwoods. The Curitiba manufacturing cluster specializes in moisture-resistant MDF substrates for humid climate construction applications.
Flush Door Market Vendor Landscape
Backward integration into captive panel manufacturing dominates the current landscape as cost volatility reshapes supplier relationships. The vendor base separates into three tiers: multinational scale manufacturers with fiberboard infrastructure, regional specialists with veneer pressing expertise, and commodity assemblers sourcing skins and cores from merchant markets. Strategic archetypes include raw material-secured integrated producers, technology-focused engineered wood specialists, and distribution-anchored brand houses. Capacity expansion and direct-to-contractor fulfillment models represent the dominant competitive moves reshaping channel economics.
Among North American integrated producers, Masonite International and Jeld-Wen occupy positions anchored by captive fiberboard supply chains and vertically aligned distribution networks. Duroply Industries Limited exemplifies the regional specialist archetype with concentrated positioning in South Asian laminated veneer lumber applications. Greenply represents the technology-focused tier competing on engineered substrate performance in humid climate construction markets.
| Leading Market Players |
|---|
| Simpson Door |
| Enfield Doors |
| Jeld-Wen |
| Duroply Industries Limited |
| Minimax |
| Masonite International |
| Archidply |
| Greenply |
| Steves Door |
| Others |
Supply Flow & Price Mechanics
Captive fiberboard manufacturing anchors both supply security and pricing power across engineered flush door production. Manufacturers with in-house panel capacity command margin resilience against veneer price swings and adhesive cost spikes that destabilize merchant-market assemblers.
Pricing Analysis
Warranty and BIS certification bundling separates premium solid core offerings from unbundled hollow core commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks fire rating, core density, and factory finish complexity. Cost compression in economy tiers intensifies as builder procurement consolidation squeezes regional wholesaler markups. Residential developers in Gujarat's Ahmedabad-Surat corridor exhibit highest price sensitivity; hospital specifiers in Maharashtra's Mumbai-Pune belt prioritize certified performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian hardwood veneer suppliers subject to EUTR documentation enforcement. Raw material security draws from Pacific Northwest fiberboard plantations, Yangtze River Delta MDF substrate mills, and Indian laminated veneer lumber processors. Timber legality verification requirements under evolving cross-border frameworks constitute the dominant supply chain risk. Distribution runs through vertically aligned big-box and pro-dealer channels that disintermediate traditional stock-and-sell wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineered wood substitution is displacing solid timber across humid climate construction, compressing legacy sawmill-dependent business models. This technology transition rewards manufacturers with captive panel infrastructure and certified substrate expertise.
For Market Incumbents: Extend laminated veneer lumber capacity in Maharashtra and Gujarat to defend against MDF import competition from Chinese substrate mills. Deepen BIS fire testing laboratory partnerships to compress 12-18 month certification timelines that lock competitor working capital. Channel control through direct-to-contractor fulfillment platforms represents the critical defensive lever against distributor disintermediation.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in fire-rated institutional doors creates white-space opportunity for cross-laminated timber core specialists. Target hospital and educational construction in India's western states where BIS mandates concentrate specification authority. Factory-applied pre-finished surface systems offer the most penetrable go-to-market angle, eliminating on-site finishing labor that contractors increasingly refuse.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building materials conglomerates seeking engineered wood technology capabilities. Long-term viability hinges on adhesive chemistry reformulation expertise as REACH and EPA restrictions tighten. Acquire targets with phenolic resin or bio-based binder pilot programs. The signal to watch is BIS certification timeline compression that releases working capital and accelerates product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fiberboard Capacity Expansion | Pacific Northwest timber plantations anchor raw material security against veneer price volatility. |
| BIS Fire Testing Laboratory Partnership | Compressed certification timelines unlock working capital and accelerate premium product launches. |
| Pre-Finished Surface Technology Investment | Factory-applied coatings capture contractor preference by eliminating on-site finishing labor. |
| Direct-to-Contractor Distribution Platform | Bypassing regional wholesalers captures margin compression from builder procurement consolidation. |
| Bio-Based Adhesive Reformulation Program | Phenolic resin alternatives maintain EU market access under REACH formaldehyde restrictions. |
Methodological Framework
Multi-period observation of BIS certification timelines, adhesive chemistry patent filings, and regional construction permit data anchored the trend analysis, supplemented by interviews with plant managers at engineered wood facilities, procurement leads at residential developers, distribution channel partners in western Indian states, and technical R&D directors at substrate manufacturers. Secondary validation drew from customs and trade data, BIS testing laboratory records, SEC filings of North American fiberboard producers, and builder association procurement surveys. Bottom-up volume modeling triangulated against top-down construction spend allocation across the analysis window.
Segment-weighting applied core construction type, substrate material, end-use environment, and performance specification tier as primary dimensions. CAGRs were derived from fitted growth curves applied to construction pipeline data and material substitution elasticity estimates. Forecast inputs incorporated BIS regulatory adoption trajectories, REACH adhesive restriction phase-in schedules, and fiberboard capacity expansion announcements.
Inputs from BIS certification databases and construction permit registries were available through the study window; gaps in real-time adhesive cost series and informal sector production estimates introduce uncertainty bands around volume projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Europe Wall Coverings Market