
 Canada Home Furniture Market | 2026-2036
Canada Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Furniture Market Outlook
A capital-intensity divergence between domestic manufacturers and import-reliant retailers is collapsing as Canadian producers scale automated fabrication. Canadel Furniture leverages vertical integration across its Quebec manufacturing base to sustain margin control against offshore pricing pressure. Palliser Furniture anchors its competitive position through captive upholstery operations in Manitoba, while EQ3 differentiates via design-forward contemporary collections targeted at urban markets.
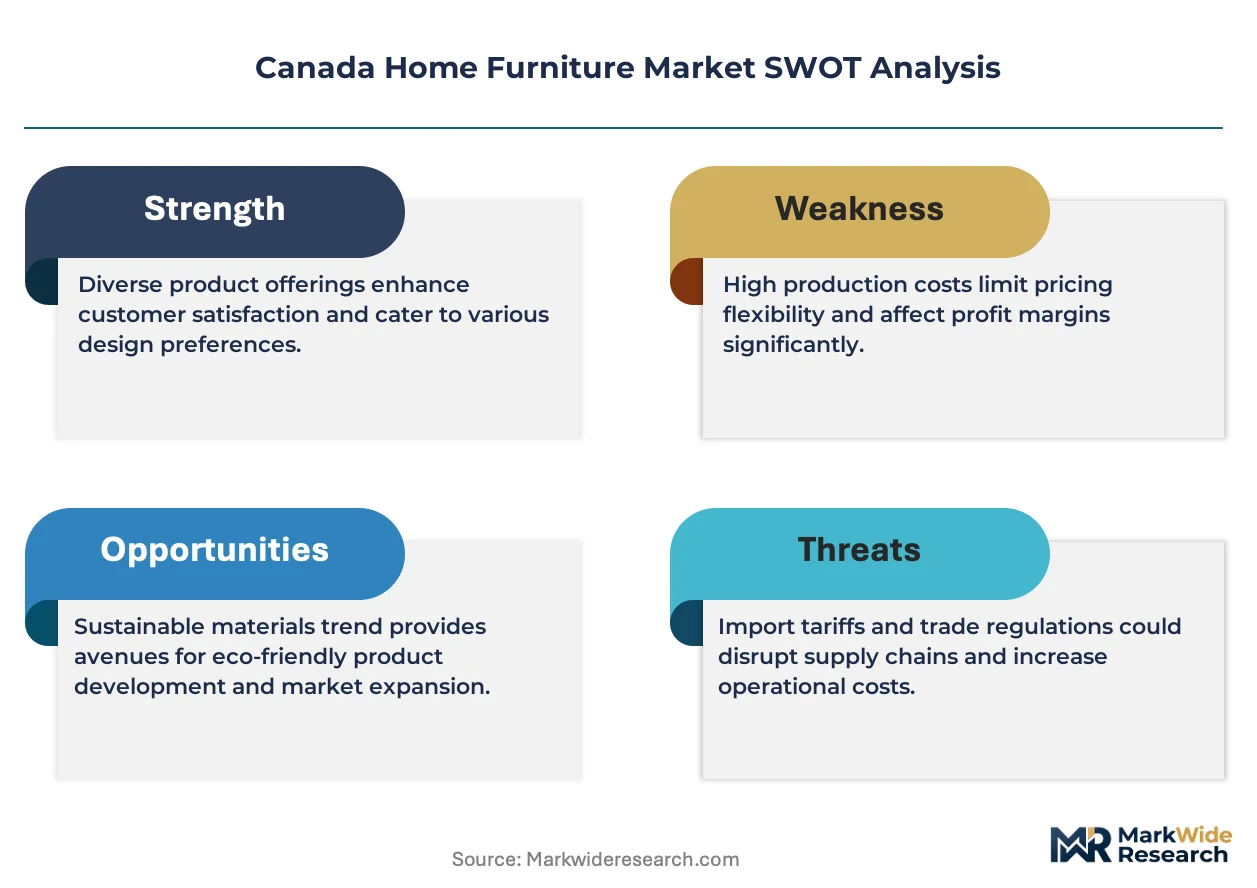
Canada home furniture encompasses movable residential fixtures constructed from wood, metal, upholstered textiles, or glass composites, engineered for domestic dwelling functions including seating, surface support, storage, and display. Primary manufacturing employs CNC routing for hardwood frames, foam-in-place upholstery systems, and powder-coated metal finishing to meet durability specifications for residential use. Wood material commands structural importance in Canadian consumer preference, reflecting heritage craft associations and domestic timber supply access. Sofas and upholstered seating capture premium margin pools through customization services, while online retailers represent the fastest-growing distribution vector as logistics networks mature for bulky-goods delivery. Contemporary style segments compete with traditional and rustic categories for share among younger demographics in major metropolitan zones.
Health Canada's Consumer Product Safety Program enforces flammability and chemical exposure standards for upholstered articles, while the Competition Act monitors environmental marketing claims affecting product positioning. The Canadian Standards Association maintains structural integrity benchmarks for residential furniture, shaping manufacturer compliance investments and retail procurement criteria. Stakeholders must monitor evolving provincial extended producer responsibility frameworks and carbon-border adjustment preparations affecting import sourcing economics.
Market Dynamics
Health Canada's Consumer Product Safety Program is tightening chemical disclosure mandates for upholstered goods, forcing manufacturers to reconfigure material sourcing and testing protocols ahead of provincial extended producer responsibility expansion.
Growth Catalysts
- Urban condominium densification:Toronto and Vancouver tower construction is compressing furniture replacement cycles as smaller footprints demand space-optimized, multi-functional designs.
- REACH-aligned material standards:British Columbia's sustainable-living consumer base is pulling formaldehyde-free and low-VOC certified products into mainstream retail assortments.
- CNC routing automation:Quebec manufacturers are deploying computer-numerical control systems to reduce hardwood frame production variance and accelerate custom order turnaround.
Market Restraints
- Cross-border lumber tariffs:Softwood lumber duties on US-bound exports are squeezing margin buffers for British Columbia and Quebec sawmill-dependent producers.
- Containerized import dependency:Vancouver and Halifax port congestion creates inventory volatility for retailers sourcing finished goods from Southeast Asian contract manufacturers.
- Upholstery foam supply concentration:Domestic polyurethane production is concentrated among three petrochemical suppliers, exposing frame manufacturers to input price spikes.
Strategic Opportunities
- Manitoba captive upholstery:In-house foam-in-place and fabric cutting operations offer margin insulation against offshore finished-goods pricing pressure.
- Carbon-border adjustment preparation:Early compliance with embodied-carbon documentation positions domestic producers for preferential procurement under federal green purchasing mandates.
- Bulky-goods logistics maturation:Last-mile networks for sofa and mattress delivery are enabling direct-to-consumer channels previously blocked by freight economics.
Industry Challenges
- Heritage woodworking skill attrition:Quebec's traditional joinery craft corridors face retirement-driven talent gaps as CNC programming displaces manual apprenticeship pipelines.
- Flammability testing backlog:Health Canada's third-party laboratory capacity constraints are extending product launch timelines for treated upholstery lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Furniture Market |
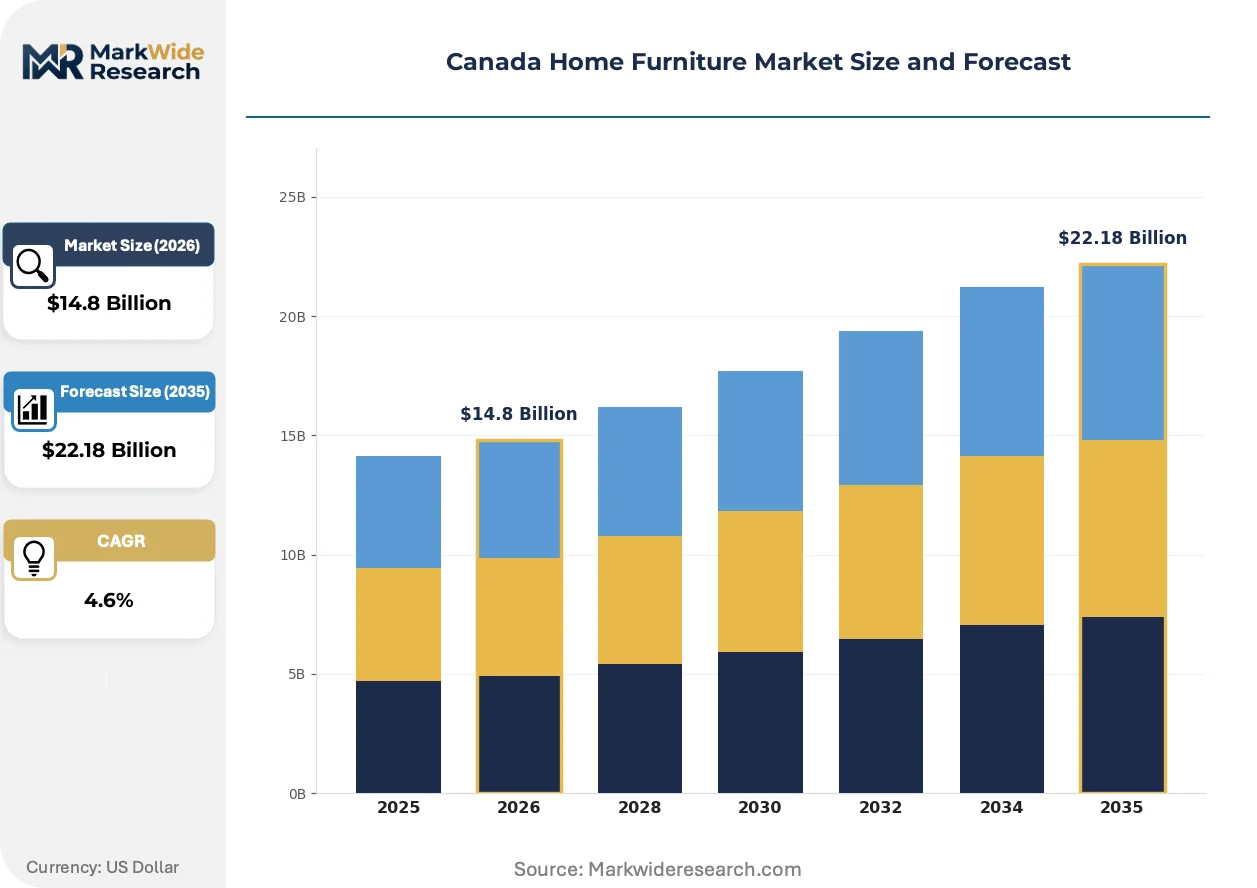
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Upholstered, Glass Style: Contemporary, Traditional, Rustic, Minimalist Distribution Channel: Online Retailers, Furniture Outlets, Big Box Stores, Custom Shops |
| Companies Covered | Sklar Peppler Home, Canadel Furniture, Dorel Industries, Coja Leatherline, Bermex, Palliser Furniture, Durham Furniture, Nienkämper, EQ3, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Furniture Market Strategic Shifts
Material transparency and fabrication automation are converging to reshape competitive positioning across Canadian residential furniture supply chains. Three developments merit particular attention.
Water-based finishing systems are supplanting solvent-based lacquers in hardwood surface treatment. Ontario and Quebec manufacturers serving the Toronto condominium market are adopting these systems to meet tenant-improvement specifications for low-emitting interiors. The shift is compressing the competitive window for imported finished goods that lack third-party emissions certification.
The Competition Act's environmental claims provisions are tightening substantiation requirements for "sustainable" and "eco-friendly" product positioning. Retailers now face penalties for unsubstantiated marketing, forcing procurement teams to demand chain-of-custody documentation from British Columbia and Quebec suppliers. Upholstered seating lines with verifiable recycled-content or FSC-certified wood frames are gaining shelf-space preference.
Urban millennial buyers are compressing furniture replacement cycles from decade-long horizons to three-to-five-year refresh intervals. Toronto and Vancouver condominium turnover rates are driving this pattern, with online retailers capturing disproportionate share through augmented-reality visualization tools that reduce purchase hesitation. The channel shift is pressuring traditional showroom operators to unbundle delivery and assembly services previously bundled in sticker prices.
Canada Home Furniture Market Segmentation
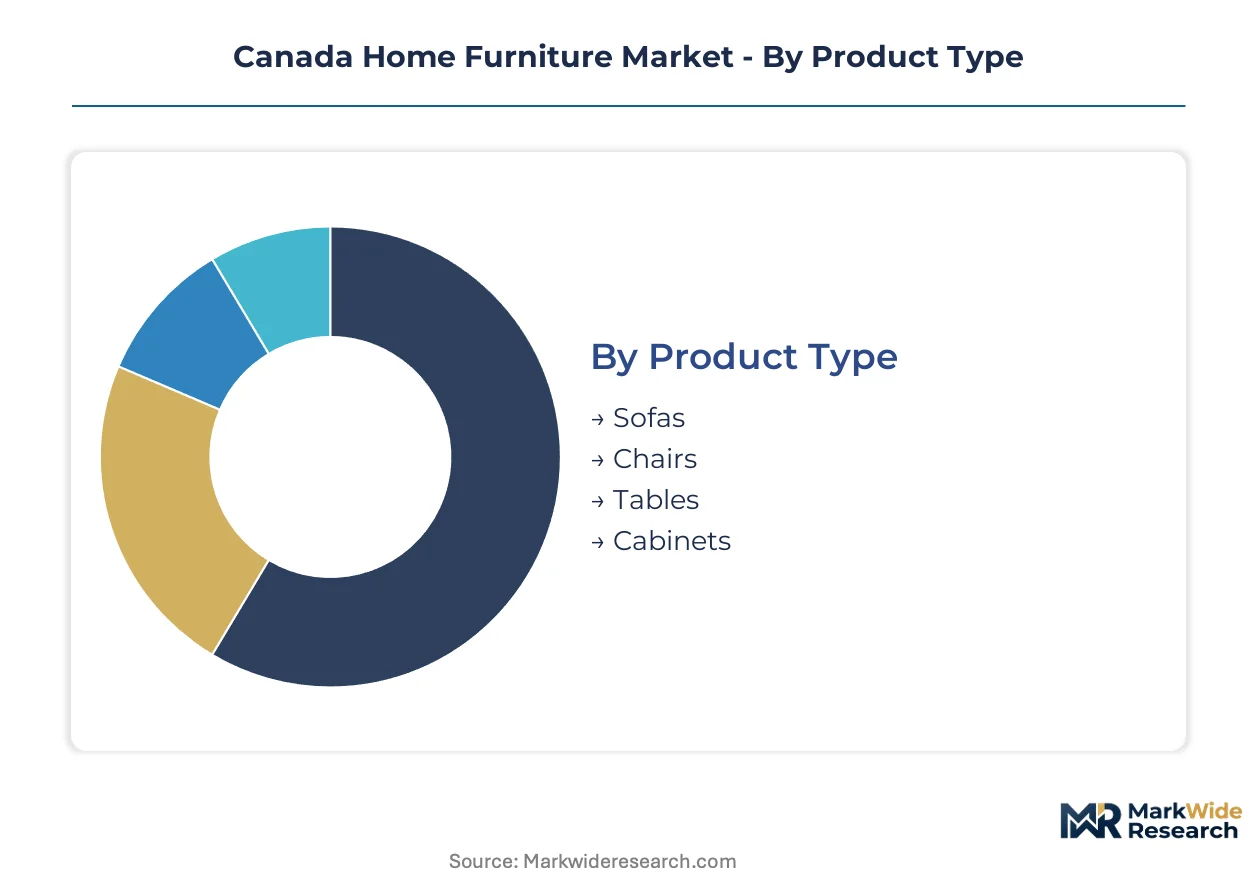
Segmentation in the Canada home furniture market reveals how channel strategy, material sourcing, and design positioning intersect with regulatory compliance and urban consumer behavior. Understanding these divides exposes where margin pools concentrate and where logistics investments unlock access.
Product Type:
Channel mix varies sharply across product categories, with bulky upholstered goods flowing through specialized delivery networks while hard goods migrate toward mass retail and digital platforms.
- Sofas:Multi-seat upholstered assemblies with hardwood frames, foam cushioning, and fabric or leather coverings. Demand concentrates in Toronto and Vancouver condominium markets where space-optimized sectionals and sleepers address compact footprints. Customization services command premium positioning as Health Canada flammability testing extends lead times for treated upholstery lines.
- Chairs:Single-seat seating spanning dining, accent, and recliner configurations. British Columbia's sustainable-living consumer base is pulling formaldehyde-free certified products into mainstream retail assortments through REACH-aligned material standards.
- Tables:Surface support fixtures including dining, coffee, and console variants constructed from solid wood, engineered substrates, or metal frames. Quebec manufacturers leverage CNC routing automation to reduce hardwood frame production variance.
- Cabinets:Storage and display units encompassing kitchen, bathroom, and freestanding room divisions. Custom shops in Quebec's heritage woodworking corridors retain share through bespoke joinery despite CNC programming displacing manual apprenticeship pipelines.
Sofas dominate installed base. Chairs are where expansion concentrates.
Material:
Cost tier stratification separates commodity inputs from certified sustainable alternatives, with embodied-carbon documentation increasingly shaping procurement criteria under federal green purchasing mandates.
- Wood:Structural frames and surface veneers derived from domestic softwood and hardwood harvests. British Columbia and Quebec sawmill-dependent producers face margin compression from cross-border lumber tariffs on US-bound exports.
- Metal:Powder-coated steel and aluminum components for frames, legs, and hardware systems. Ontario manufacturers serving Toronto condominium markets adopt water-based finishing systems to meet tenant-improvement specifications.
- Upholstered:Fabric, leather, and synthetic textile coverings over foam and fiberfill cushioning. Domestic polyurethane production concentration among three petrochemical suppliers exposes frame manufacturers to input price spikes.
- Glass:Tempered and laminated panels for tabletops, shelving, and decorative inserts. Vancouver and Halifax port congestion creates inventory volatility for retailers sourcing finished glass components from Southeast Asian contract manufacturers.
Wood dominates installed base. Upholstered materials are climbing the fastest.
Style:
Customer type alignment maps generational cohorts to aesthetic preferences, with urban millennial buyers compressing replacement cycles and driving channel shift toward augmented-reality-enabled digital platforms.
- Contemporary:Clean lines, neutral palettes, and modular configurations emphasizing spatial efficiency. Toronto and Vancouver condominium turnover rates accelerate three-to-five-year refresh intervals versus traditional decade-long horizons.
- Traditional:Ornate detailing, rich wood tones, and heritage craft associations. Quebec's traditional joinery craft corridors face retirement-driven talent gaps as CNC programming displaces manual apprenticeship pipelines.
- Rustic:Distressed finishes, reclaimed wood aesthetics, and farmhouse-inspired silhouettes. British Columbia suppliers with verifiable FSC-certified wood frames gain shelf-space preference as Competition Act environmental claims provisions tighten substantiation requirements.
- Minimalist:Reduced material volumes, hidden storage, and multi-functional adaptability for compact urban dwellings. Online retailers capture disproportionate share through visualization tools that reduce purchase hesitation.
Traditional dominates installed base. Contemporary is gaining share fastest.
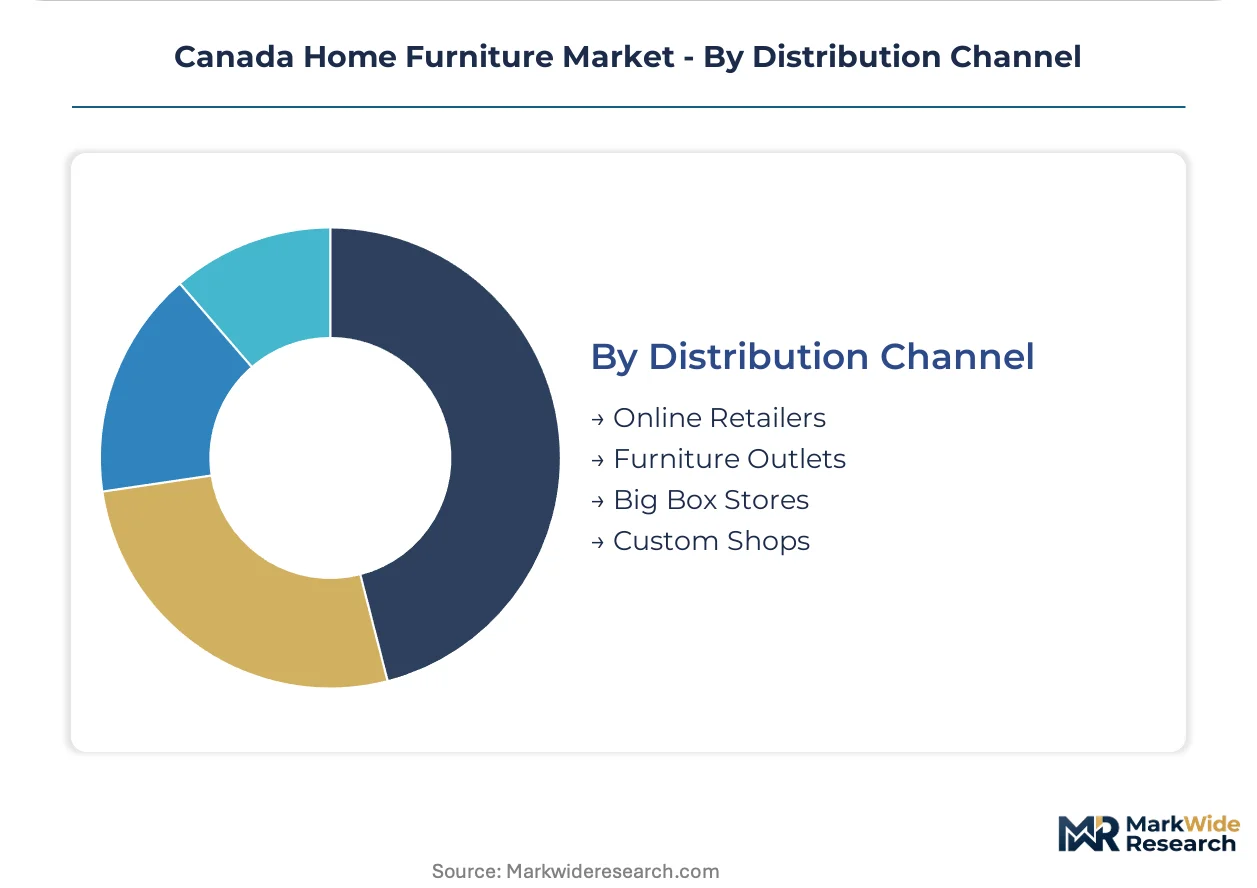
Distribution Channel:
Supply concentration patterns determine which channels control inventory velocity, with captive upholstery operations and last-mile logistics investments reshaping competitive access.
- Online Retailers:Digital-native platforms with augmented-reality visualization, direct-to-consumer logistics, and unbundled delivery services. Bulky-goods last-mile networks for sofa and mattress delivery enable channels previously blocked by freight economics.
- Furniture Outlets:Specialized showrooms with full-service design consultation and white-glove delivery. Manitoba captive upholstery operations offer margin insulation against offshore finished-goods pricing pressure.
- Big Box Stores:Mass-market retailers with standardized assortments and volume-driven procurement. Early compliance with embodied-carbon documentation positions domestic producers for preferential procurement under federal green purchasing mandates.
- Custom Shops:Bespoke manufacturers with in-house design, material selection, and craft fabrication. Quebec manufacturers deploy CNC routing to accelerate custom order turnaround while preserving heritage woodworking associations.
Furniture outlets dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quebec's automated hardwood frame production commands pricing premiums against Ontario's import-reliant retail corridors. British Columbia's timber access and Vancouver's condominium density create asymmetric margin capture across provincial boundaries.
Ontario
Toronto's condominium tower construction accelerates furniture refresh cycles as space-optimized sectionals displace traditional dining sets. Health Canada's Consumer Product Safety Program enforces flammability standards for upholstered goods entering the Greater Toronto Area. Kitchener-Waterloo CNC equipment suppliers are scaling automated routing systems for frame manufacturers serving the urban market.
Quebec
Montreal's heritage woodworking corridors retain craft associations despite CNC programming displacing manual apprenticeship pipelines. The Competition Act monitors environmental marketing claims affecting product positioning from Quebec manufacturers. Trois-Rivières sawmill-dependent producers face margin compression from cross-border softwood lumber duties on US-bound exports.
British Columbia
Vancouver's sustainable-living consumer base pulls formaldehyde-free certified products into mainstream retail assortments through REACH-aligned material standards. Health Canada's Consumer Product Safety Program tightens chemical disclosure mandates for upholstered goods sold in the province. Port Metro Vancouver congestion creates inventory volatility for retailers sourcing finished components from Southeast Asian contract manufacturers.
Manitoba
Winnipeg's captive upholstery operations offer margin insulation against offshore finished-goods pricing pressure through in-house foam-in-place production. Provincial extended producer responsibility frameworks are expanding compliance requirements for furniture disposal. The Manitoba manufacturing base anchors competitive positioning through integrated fabric cutting and assembly operations.
Alberta
Calgary's energy-sector housing turnover drives replacement demand for contemporary and minimalist furniture configurations. Federal green purchasing mandates are positioning early embodied-carbon compliance as a procurement differentiator. Edmonton distribution hubs are maturing last-mile networks for bulky-goods delivery to prairie markets.
Canada Home Furniture Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Canadian residential furniture supply base. The market structure fragments between automated Quebec manufacturers and import-reliant Ontario retailers, with captive upholstery operations in Manitoba bridging this divide. Three archetypes dominate: vertically integrated hardwood frame producers, design-forward contemporary specialists, and logistics-enabled direct-to-consumer platforms. Competitive moves concentrate on CNC automation deployment and last-mile delivery infrastructure investment.
Within the heritage-integrated manufacturing tier, Canadel Furniture and Palliser Furniture exemplify archetypes combining automated production with regional timber access. EQ3 occupies a position anchoring design-forward contemporary collections for urban condominium markets. These three entities represent the span from Quebec's CNC-routed hardwood operations through Manitoba's captive upholstery integration to digitally-native distribution targeting Toronto and Vancouver density.
| Leading Market Players |
|---|
| Sklar Peppler Home |
| Canadel Furniture |
| Dorel Industries |
| Coja Leatherline |
| Bermex |
| Palliser Furniture |
| Durham Furniture |
| Nienkämper |
| EQ3 |
| Others |
Value Chain & Pricing Dynamics
Health Canada's Consumer Product Safety Program gates both supplier qualification and price differentiation simultaneously, as flammability certification requirements separate treated upholstery lines from uncertified imports while extending lead times that support configured-to-order premiums.
Pricing Analysis
Configured-to-order pricing commands spreads of 35-50% above standard SKUs across Toronto and Vancouver condominium markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth. Cost compression in the economy tier intensifies because containerized import dependency exposes retailers to Vancouver and Halifax port congestion. First-time urban buyers exhibit highest price sensitivity, while heritage-craft seekers in Quebec's woodworking corridors accept premium positioning for bespoke joinery.
Supply Chain Analysis
Canada and Vietnam anchor hardwood frame and finished upholstery production respectively, with Quebec's CNC-routed operations supplying domestic structural components and Southeast Asian contract manufacturers feeding Toronto's mass retail corridors. British Columbia sawmills and Quebec timber harvests provide domestic softwood and hardwood inputs, while polyurethane foam production concentrates among three domestic petrochemical suppliers. Tariff exposure on US-bound softwood lumber exports squeezes margin buffers for British Columbia and Quebec producers. Distribution runs through specialized last-mile networks for bulky upholstered goods and mass retail channels for hard goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada home furniture market represents early-cycle expansion as urban condominium densification in Toronto and Vancouver accelerates furniture refresh intervals from decade-long horizons to three-to-five-year cycles.
For Market Incumbents: Fortify captive upholstery operations against offshore pricing pressure through Manitoba-based foam-in-place integration and fabric cutting automation. Health Canada's tightening chemical disclosure mandates threaten import-reliant competitors with compliance gaps; incumbents should accelerate FSC-certified wood frame documentation to capture preferential procurement under federal green purchasing mandates. Channel control through owned last-mile delivery infrastructure locks out digitally-native entrants in bulky goods categories. For New Entrants and Emerging Players: Lead with augmented-reality visualization tools targeting Toronto and Vancouver millennial buyers who compress replacement cycles and hesitate at traditional showroom friction. The online retail channel remains underpenetrated relative to furniture outlets, offering white-space access for digital-native platforms with unbundled delivery and assembly services. A direct-to-consumer go-to-market angle bypasses incumbent showroom investments while capturing share from import-reliant retailers exposed to port congestion volatility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Quebec's automated hardwood frame production as CNC routing deployment reduces labor content per unit. Long-term viability over a 5-10 year window favors vertically integrated manufacturers with regional timber access and in-house upholstery operations over import-dependent retail models. The signal to watch is Health Canada laboratory capacity expansion, as reduced flammability testing backlogs would compress lead times and erode configured-to-order pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| CNC Automation Deployment | Quebec manufacturers reduce hardwood frame variance and accelerate custom turnaround against offshore competition. |
| Captive Upholstery Integration | Manitoba in-house foam-in-place operations insulate margins from Southeast Asian finished-goods pricing pressure. |
| Carbon-Border Compliance Preparation | Early embodied-carbon documentation positions domestic producers for federal green purchasing mandate preference. |
| Last-Mile Logistics Maturation | Bulky-goods delivery networks enable direct-to-consumer channels previously blocked by freight economics in Toronto. |
| Water-Based Finishing Adoption | Ontario manufacturers meet Toronto tenant-improvement specifications for low-emitting interiors ahead of import competition. |
Study Parameters
Operator-level perspectives from furniture manufacturing executives, retail procurement directors, CNC equipment suppliers, and last-mile logistics operators anchored the qualitative base. Primary interviews combined with secondary validation from Health Canada regulatory filings, Canadian Standards Association benchmark documentation, and customs trade data on softwood lumber and upholstered goods imports. Bottom-up and top-down triangulation cross-checked production capacity estimates against retail inventory velocity patterns.
Sensitivity analysis framing tested forecast outputs against variable adoption rates for augmented-reality visualization tools and divergent paths for provincial extended producer responsibility expansion. Segmentation dimensions modeled across the analysis window include product type, material composition, style positioning, and distribution channel structure. CAGRs derived from volume trajectory analysis incorporating urban condominium construction permits, household formation rates, and furniture replacement cycle compression indicators.
The analysis sits within stated boundaries; outcomes outside sustained Toronto and Vancouver tower construction velocity or abrupt shifts in cross-border lumber tariff regimes would require recalibration. Forecasts reflect assumptions on Health Canada laboratory capacity expansion and REACH-aligned material standard adoption trajectories. Recalibration cycles align with material shifts in condominium turnover rates and federal green purchasing mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America Secondary Wood Products Market
Furniture
Indonesia Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
US Multifunctional Furniture Market
Furniture
Spain Furniture Market
Furniture
North America Slide Rails Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Europe Upholstered Furniture Market
Furniture
Cabinet Market
Furniture
Recliner Chair Market
Furniture
Sanded Plywood Market
Furniture
Massive Wood Slabs Market
Furniture
China Furniture Market
Furniture
Metal Furniture Market
Furniture
Italy Furniture Retail Market